
Cloud Based Solutions For Drug Discovery Development And Manufacturing Market Overview:
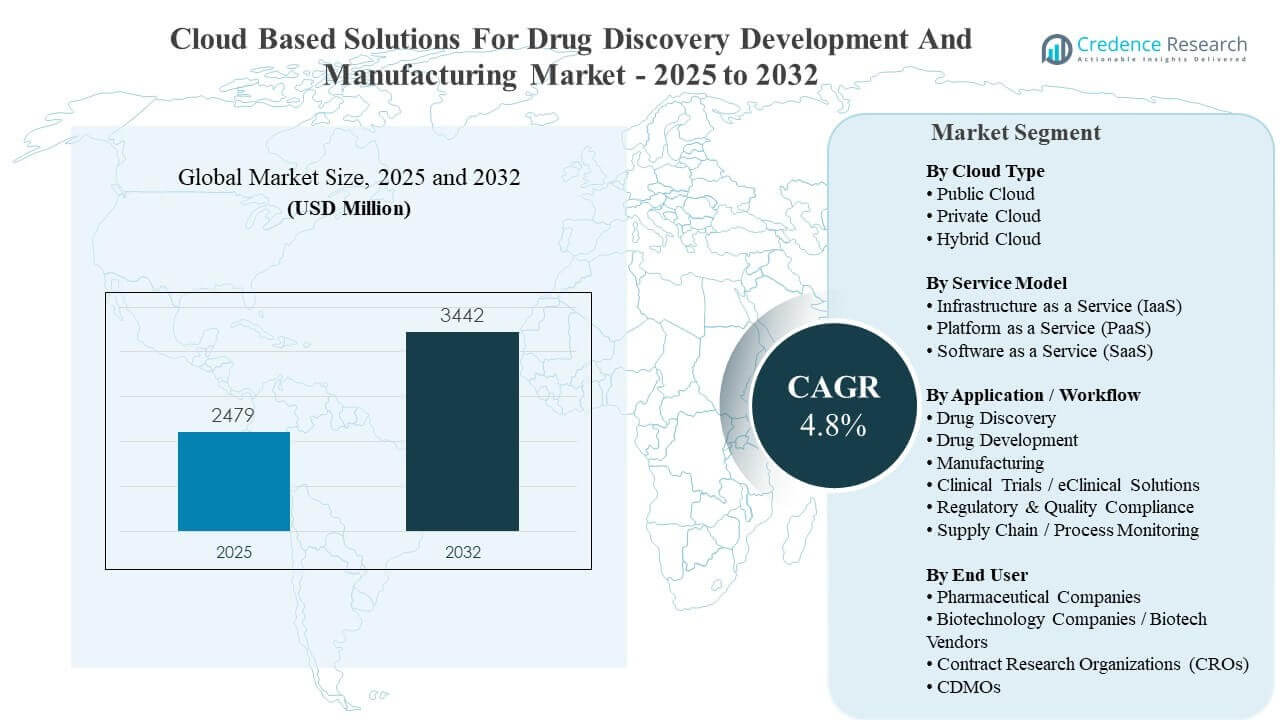
The global Cloud Based Solutions For Drug Discovery Development And Manufacturing Market size was estimated at USD 2479 million in 2025 and is expected to reach USD 3442 million by 2032, growing at a CAGR of 4.8% from 2025 to 2032. The strongest growth driver is the accelerating shift of life-sciences R&D and regulated operations toward scalable cloud-native platforms that can support high-performance compute, AI workloads, and secure collaboration across distributed teams. Cloud delivery also improves standardization of workflows across discovery, development, manufacturing, and quality functions by centralizing data access, validation processes, and auditability. North America continues to anchor early adoption through ecosystem depth, with enterprise deployments increasingly extending to global sites and partners.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Size 2025 | USD 2479 million |
| Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market, CAGR | 4.8% |
| Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Size 2032 | USD 3442 million |
Key Market Trends & Insights
- The Cloud Based Solutions for Drug Discovery Development and Manufacturing Market recorded a base-year value of USD 2479 million (2025).
- The Cloud Based Solutions for Drug Discovery Development and Manufacturing Market is projected to reach USD 3442 million by 2032.
- The Cloud Based Solutions for Drug Discovery Development and Manufacturing Market is expanding at a 4.8% CAGR during 2025–2032.
- SaaS accounted for 46.6% (2025), supported by faster deployment cycles and vendor-managed compliance, upgrades, and security.
- North America held 36.8% (2025) and Europe accounted for 28.4% (2025), reflecting strong concentration of biopharma R&D, clinical operations digitization, and enterprise cloud modernization.
Segment Analysis
Cloud adoption across life-sciences workflows is increasingly shaped by the need to unify data, tools, and collaboration across discovery, development, manufacturing, clinical, and quality functions. Cloud-based delivery improves accessibility for cross-functional teams and external partners by enabling controlled data sharing, standardized process execution, and centralized governance. Demand is also strengthened by rising AI enablement in regulated environments, which requires scalable compute, secure data layers, and repeatable validation practices.
Buying decisions are heavily influenced by the ability to deploy compliant workloads quickly, reduce the internal burden of platform maintenance, and integrate diverse toolchains across R&D and operations. Organizations prioritize platforms that support audit readiness, configurable workflows, and interoperability across multiple stakeholders such as sponsors, CROs, and CDMOs. Long-term vendor selection is also tied to ecosystem strength, implementation expertise, and the ability to scale across geographies with consistent controls.
By Cloud Type Insights
Cloud type adoption is guided by trade-offs between scalability, governance, and IP protection across sensitive R&D and regulated datasets. Public cloud deployments are widely used for burst compute, analytics, and experimentation in discovery-oriented workloads that require elastic capacity. Private cloud remains relevant for organizations prioritizing tighter control over sensitive assets, legacy integration, or specific residency constraints. Hybrid cloud is increasingly favored for end-to-end programs because hybrid architectures allow regulated core systems to coexist with scalable public-cloud analytics and AI services.
By Service Model Insights
Software as a Service (SaaS) accounted for the largest share of 46.6% in 2025. SaaS leads due to faster time-to-value through preconfigured workflows that reduce implementation complexity across regulated functions. Vendor-managed upgrades, validation support, and security controls reduce internal IT workload and improve consistency across global deployments. SaaS models also strengthen cross-organization collaboration by enabling standardized access for pharma sponsors, biotech vendors, CROs, and CDMOs. Integration-friendly APIs and embedded analytics further support SaaS preference for workflow-heavy domains such as quality, regulatory, and clinical operations.
By Application / Workflow Insights
Application demand is shaped by the need to connect data-driven discovery with downstream development execution, regulated documentation, and operational visibility. Drug discovery workflows increasingly depend on cloud-scale compute for modeling, simulation, and AI-based screening, which benefits from elastic capacity and modern toolchains. Drug development and clinical operations rely on cloud platforms to support multi-site coordination, data capture, monitoring, and traceability across stakeholders. Manufacturing and supply chain workflows also move to cloud to enable process visibility, performance monitoring, and more consistent compliance documentation. Regulatory and quality functions remain a steady adoption driver because cloud systems can improve version control, audit readiness, and enterprise standardization.
By End User Insights
End-user adoption is segmented by scale, regulatory burden, and collaboration intensity across outsourced and in-house models. Pharmaceutical companies typically drive enterprise deployments due to portfolio-wide standardization needs, security governance requirements, and multi-region operating structures. Biotechnology companies and biotech vendors adopt cloud solutions to access advanced analytics and AI capabilities without large infrastructure investments. CROs and CDMOs use cloud platforms to streamline sponsor collaboration, study execution, and quality documentation while supporting multiple clients and programs. Other end users, including academic and research sponsors, increasingly adopt cloud tools for collaboration and data sharing, particularly for multi-institution programs.
Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Drivers
Expansion of AI-enabled discovery and development workflows
Cloud adoption accelerates as life-sciences organizations expand AI-driven discovery and development programs that require scalable compute and governed data access. Cloud platforms support elastic capacity for modeling, simulation, and screening workloads that fluctuate across project phases. Standardized environments also improve reproducibility of analytics and reduce delays caused by infrastructure constraints. Compliance-ready controls strengthen adoption in regulated settings where auditability and traceability are essential. Integration of analytics, workflow orchestration, and data management increases value across the pipeline.
- For instance, Recursion completed its BioHive-2 AI supercomputer with 63 NVIDIA DGX H100 systems and 504 NVIDIA H100 GPUs, and the company reported benchmark performance that was 4 times faster than BioHive-1, underscoring the scale of cloud-aligned infrastructure now supporting AI-enabled drug discovery workflows.
Demand for compliant, standardized platforms across regulated functions
Regulated processes in clinical operations, quality, and regulatory submissions benefit from cloud systems that provide consistent controls and centralized governance. Cloud delivery improves document lifecycle management, version control, and audit trails across distributed teams. Organizations adopt cloud to reduce fragmented tool usage and to enforce standard operating processes across sites and partners. Standardization also supports faster onboarding of CROs and CDMOs by aligning workflows and permissions. This driver remains strong as compliance requirements intensify and global trial activity expands.
Growth of distributed collaboration across pharma ecosystems
Drug development increasingly depends on collaboration across sponsors, biotechnology partners, CROs, CDMOs, and specialized vendors. Cloud platforms improve collaboration by enabling controlled sharing of data, workflows, and dashboards with role-based access. Centralized systems reduce handoff friction, lower rework, and improve visibility across program milestones. Collaboration demand is especially high for multi-region studies and outsourced manufacturing programs that require consistent documentation. Cloud-based integration layers help connect partner systems without excessive custom infrastructure.
Need for operational agility across manufacturing and supply workflows
Manufacturing and supply chain workflows benefit from cloud adoption as organizations seek faster response to demand variability, quality events, and process deviations. Cloud platforms support process monitoring, performance analytics, and standardized batch and quality documentation across sites. Integration of operational data with R&D and quality functions strengthens end-to-end visibility and governance. The ability to deploy improvements rapidly across multiple facilities increases operational agility. This driver is reinforced by expanding biologics pipelines and complex outsourced supply models.
- For instance, Takeda and TCS reported that their EDGE innovation model released 12 digital products across more than 40 design sprints, evaluated over 40 use cases, and reduced time-to-market for new digital products and services by 50%, reflecting how cloud-enabled digital operating models can improve agility across supply-focused pharma operations.
Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Challenges
Data governance and IP protection remain primary challenges for cloud adoption in discovery and manufacturing workflows. Sensitive molecular datasets, proprietary processes, and regulated patient-related information require strong access controls, encryption, and continuous monitoring. Organizations also face policy complexity due to data residency requirements and cross-border collaboration needs. Security reviews can slow vendor onboarding and delay program timelines. Stakeholder confidence depends on consistent governance and clearly defined accountability across partners.
- For instance, Moderna said it standardized its real-world data strategy on AWS Data Exchange, reduced data extraction and analysis time by 70%, shortened onboarding from 8–10 days to 3 days, and kept data encrypted both in transit and at rest to meet its security requirements.
Integration complexity is another constraint, especially when legacy systems and diverse vendor tools must operate in a single workflow. Fragmented data models, inconsistent identifiers, and differing validation practices can create bottlenecks across discovery-to-manufacturing handoffs. Migration planning is often complicated by program continuity requirements and parallel operations during transition. Skills gaps in cloud architecture and regulated validation can increase reliance on external partners. Adoption success depends on strong implementation governance and interoperable platform design.
Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Trends and Opportunities
Adoption is trending toward unified platforms that connect safety, regulatory, quality, clinical, and operational data with workflow automation. Organizations increasingly prioritize consolidated data layers and consistent process models to reduce duplication and accelerate decision cycles. Cloud-native analytics and AI capabilities are being embedded directly into workflow tools rather than operating as standalone environments. This shift increases demand for configurable systems that can scale across functions without sacrificing compliance. Vendors that deliver interoperable, modular platforms are well positioned.
- For instance, Veeva stated that its Development Cloud brings together clinical, regulatory, quality, and safety applications on one cloud platform, with more than 350 companies using Vault Clinical, more than 250 using Vault RIM, more than 350 using Vault Quality, and more than 35 using Vault Safety.
Opportunities are expanding in hybrid architectures and partner ecosystems that simplify collaboration across sponsors, CROs, and CDMOs. Hybrid deployments allow organizations to keep sensitive assets under tighter control while using public-cloud services for scalable analytics and AI. Multi-cloud strategies are also rising as organizations optimize vendor risk, cost, and specialized capabilities. Integration accelerators, prevalidated templates, and compliance toolkits can reduce deployment time and improve adoption outcomes. Service providers can differentiate by combining implementation expertise with operating model transformation.
Regional Insights
North America
North America accounted for 36.8% (2025), supported by strong concentration of leading cloud providers, deep biopharma R&D investment, and mature enterprise adoption of regulated cloud operations. The region benefits from broad availability of cloud-skilled talent and established partner ecosystems that accelerate implementation and validation. Life-sciences organizations in North America also prioritize AI-enabled discovery and scalable analytics, increasing demand for secure compute and governed data platforms. Adoption is reinforced by high outsourcing activity that requires standardized collaboration with CROs and CDMOs.
Europe
Europe held 28.4% (2025), driven by a large pharmaceutical base, expanding clinical operations digitization, and strong adoption of quality and regulatory workflow platforms. European deployments often emphasize data residency, cross-country governance, and standardized compliance processes across distributed operating models. Demand is also supported by collaboration across multinational trials and cross-border manufacturing networks. Growth is strengthened by modernization initiatives focused on interoperability, audit readiness, and controlled data sharing.
Asia Pacific
Asia Pacific captured 24.9% (2025), reflecting expanding biotech activity, rising clinical trial execution, and ongoing modernization of manufacturing and supply operations. Adoption is propelled by scaling R&D footprints and increasing use of data-driven discovery tools that benefit from elastic cloud compute. Organizations increasingly pursue cloud deployment to improve collaboration and consistency across regional sites and outsourced partners. The region also shows strong momentum in digital transformation programs that connect R&D, quality, and operations.
Latin America
Latin America represented 5.8% (2025), supported by gradual expansion of clinical trial activity and increasing adoption of cloud-based enterprise systems. Adoption is influenced by the pace of modernization across healthcare infrastructure and life-sciences operations. Organizations prioritize solutions that simplify implementation, improve collaboration with global sponsors, and reduce operational overhead. Growth potential is linked to improved digital readiness and broader participation in multi-region studies and outsourced operations.
Middle East & Africa
Middle East & Africa accounted for 4.1% (2025), supported by growing national digital initiatives and increasing investment in healthcare modernization. Adoption in life sciences is progressing through cloud-first strategies in leading markets and expansion of clinical and operational digitization. Organizations prioritize secure platforms that can support governance needs and integrate with international partners. Growth is expected to strengthen as regional ecosystems mature and life-sciences investments expand.
Competitive Landscape
Competition is shaped by platform depth, compliance readiness, and the ability to support end-to-end workflows spanning discovery, development, clinical execution, regulatory, quality, and manufacturing operations. Hyperscale providers compete through scalable compute, AI tooling, secure cloud controls, and broad partner ecosystems. Enterprise software and workflow specialists differentiate through domain-specific configurations, validation support, and interoperability with regulated documentation needs. Consulting and services-led players strengthen adoption by combining implementation, change management, and operating model transformation to accelerate outcomes.
Amazon Web Services (AWS) is positioned as a foundational infrastructure and AI-enablement layer for life-sciences cloud deployments, supporting scalable compute and managed services that can be aligned with regulated governance requirements. AWS deployments commonly emphasize secure data architectures, high-performance compute for modeling and analytics, and ecosystem integrations with workflow and data platform partners. The approach enables organizations to scale discovery and development workloads without building large internal infrastructure footprints. AWS also benefits from strong implementation partner coverage that supports validation and migration programs for complex enterprises.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Amazon Web Services (AWS)
- IBM
- Oracle
- Accenture
- Tata Consultancy Services (TCS)
- Veeva Systems
- ArisGlobal
- Nutanix
- Alibaba Cloud / Alibaba Group
- XtalPi
- Cloud Pharmaceuticals
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Benchling announced a partnership with Lilly TuneLab to bring Lilly’s AI models into the Benchling platform for biotech and life sciences users. Benchling said the collaboration would let scientists work with models trained on Lilly’s drug disposition, safety, and preclinical datasets directly inside Benchling’s secure R&D environment.
- In January 2026, Veeva Systems launched Veeva Environmental Monitoring, a cloud-native application unified with Veeva LIMS to modernize manufacturing quality control. Veeva said the new solution helps laboratories and manufacturing facilities schedule, collect, and analyze environmental samples for GMP compliance and sterility monitoring.
- In January 2026, Oracle announced Oracle Life Sciences AI Data Platform, a generative AI-enabled offering built to unify data and agentic intelligence for pharmaceutical, biotech, and medical device organizations. The launch expands Oracle’s cloud-based life sciences portfolio aimed at accelerating development and data-driven decision-making.
- In December 2025, IQVIA announced a strategic collaboration with AWS and named AWS its preferred agentic cloud provider for IQVIA’s next-generation AI platform. IQVIA said the partnership is designed to improve clinical trial automation, medical affairs workflows, and healthcare analytics through scalable cloud-based AI.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 2479 million |
| Revenue forecast in 2032 | USD 3442 million |
| Growth rate (CAGR) | 4.8% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Cloud Type Outlook: Public Cloud, Private Cloud, Hybrid Cloud; By Service Model Outlook: IaaS, PaaS, SaaS; By Application / Workflow Outlook: Drug Discovery, Drug Development, Manufacturing, Clinical Trials / eClinical Solutions, Regulatory & Quality Compliance, Supply Chain / Process Monitoring; By End User Outlook: Pharmaceutical Companies, Biotechnology Companies / Biotech Vendors, CROs, CDMOs, Other End Users |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Amazon Web Services (AWS), IBM, Oracle, Google, Accenture, Tata Consultancy Services (TCS), Veeva Systems, ArisGlobal, Nutanix, Alibaba Cloud / Alibaba Group, XtalPi, Cloud Pharmaceuticals |
| No.of Pages | 336 |
Segmentation
By Cloud Type
- Public Cloud
- Private Cloud
- Hybrid Cloud
By Service Model
- Infrastructure as a Service (IaaS)
- Platform as a Service (PaaS)
- Software as a Service (SaaS)
By Application / Workflow
- Drug Discovery
- Drug Development
- Manufacturing
- Clinical Trials / eClinical Solutions
- Regulatory & Quality Compliance
- Supply Chain / Process Monitoring
By End User
- Pharmaceutical Companies
- Biotechnology Companies / Biotech Vendors
- Contract Research Organizations (CROs)
- Contract Development and Manufacturing Organizations (CDMOs)
- Other End Users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
What is the CAGR for the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
What is the largest segment in the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
What factors are driving growth in the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
Which are the leading companies in the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
Which region leads the Cloud Based Solutions For Drug Discovery Development And Manufacturing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 2479 million → 2032: USD 3442 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Drivers
- 3.3 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Restraints & Challenges
- 3.4 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cloud-Based Solutions for Drug Discovery, Development And Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Cloud-Based Solutions for Drug Discovery, Development And Manufacturing. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cloud-Based Solutions for Drug Discovery, Development And Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Cloud-Based Solutions for Drug Discovery, Development And Manufacturing
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cloud-Based Solutions for Drug Discovery, Development And Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
