
3D Printing for Personalized Healthcare Market Overview:
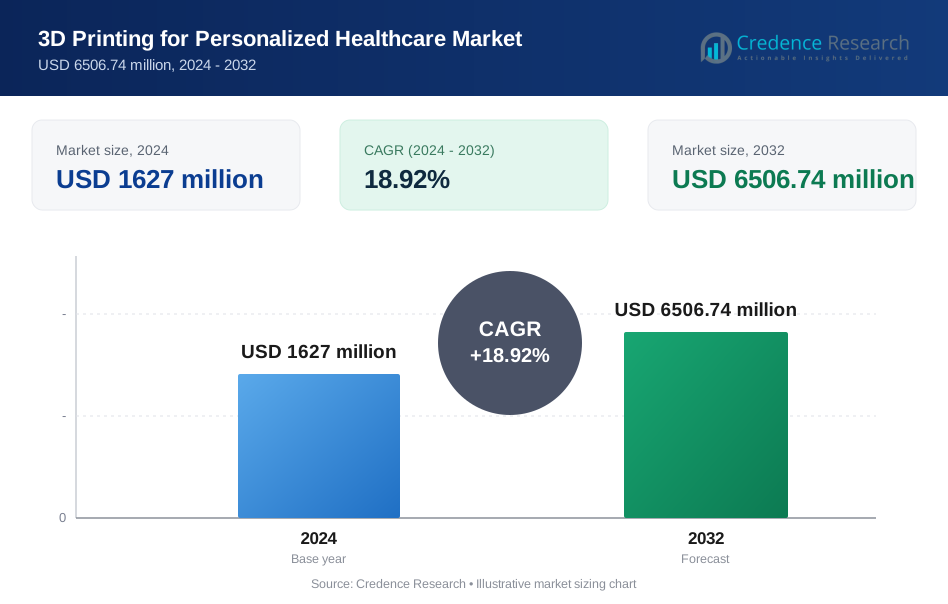
3D Printing for Personalized Healthcare Market was valued at USD 1627 million in 2024 and is anticipated to reach USD 6506.74 million by 2032, growing at a CAGR of 18.92 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D Printing for Personalized Healthcare Market Size 2024 | USD 1627 million |
| 3D Printing for Personalized Healthcare Market, CAGR | 18.92 % |
| 3D Printing for Personalized Healthcare Market Size 2032 | USD 6506.74 million |
3D Printing for Personalized Healthcare Market Insights
- Demand rises due to increasing use of patient-specific implants and surgical guides, driven by improved accuracy and shorter recovery times.
- Key trends include growth in biofabrication, expanding point-of-care 3D printing labs, and wider adoption of advanced biocompatible materials across clinical settings.
- Market competition is shaped by major players focusing on precision systems, clinical-grade materials, and integrated design workflows; top segments include implants with about 41% share.
- North America leads with around 38% regional share, followed by Europe and Asia Pacific, supported by strong healthcare infrastructure and rapid clinical adoption.

3D Printing for Personalized Healthcare Market Segmentation Analysis:
By Technology
Droplet deposition leads the 3D Printing for Personalized Healthcare Market with about 32% share in 2024. Healthcare providers choose this method for its accuracy in fabricating patient-specific models and surgical guides. Strong adoption comes from low material waste and flexible use with biocompatible polymers. Photopolymerization and laser beam melting expand due to rising demand for detailed prototypes and metal implants. EBM and laminated object manufacturing remain niche options for specialized research and complex parts. Overall growth comes from precision needs in medical planning and faster production cycles in treatment workflows.
- For instance, Stratasys produced more than 2,000 customized surgical guides for leading hospitals using its PolyJet droplet-based platform, which supports layer resolutions as fine as 14 microns. The company validated accuracy through studies showing dimensional error margins under 100 microns for patient-specific maxillofacial models. This level of precision strengthened adoption of droplet deposition for complex surgical planning.
By Application
Implants dominate the market with nearly 41% share in 2024. Hospitals and device makers rely on custom implants for orthopedic, dental, and cranial reconstruction needs. Personalized geometry improves patient outcomes and reduces revision surgeries. Tissue engineering gains momentum through advances in bioinks and scaffold designs. External wearable devices grow with higher demand for ergonomic prosthetics. Clinical study devices support rapid prototyping for trials. Adoption rises due to better material strength, patient comfort, and improved time-to-treatment.
- For instance, Stryker has manufactured over 2 million 3D printed implants (not all of which are patient-matched) using its AMagine facilities and technology since 2013. The number 130,000 might refer to a specific product line or a historical data point, but the overall number is significantly higher.
By End User
Medical and surgical centers hold the top position with about 45% share in 2024. These centers use 3D printing to create anatomical models, implant guides, and patient-specific tools that enhance surgical accuracy. Strong uptake comes from reduced operating time and improved pre-operative planning. Pharmaceutical and biotechnology companies expand usage for drug delivery devices and tissue engineering research. Academic institutions grow as research funding increases and training needs rise. End-user growth reflects broader clinical integration and improved regulatory clarity for custom medical devices.
Key Growth Drivers
Rising Demand for Patient-Specific Medical Solutions
Personalized treatment is now a core focus in modern healthcare, and this shift drives strong demand for 3D printing in patient-specific devices. Hospitals and surgeons rely on customized implants, anatomical models, and prosthetics that match individual body structures with high precision. This approach improves surgical accuracy, reduces complications, and shortens recovery time. Growing clinical adoption also comes from better imaging technologies that convert CT and MRI data into printable models. The need for enhanced patient outcomes and reduced procedure time supports rapid expansion. As more healthcare systems move toward personalized care standards, 3D printing becomes a critical tool for improving both treatment quality and clinical workflow efficiency.
- For instance, Materialise supported more than 350,000 patient-specific surgical procedures using its medical 3D printing solutions, with anatomical models produced at dimensional accuracies below 0.5 mm. Its Mimics Innovation Suite converts CT/MRI data into 3D-printable files used in over 300 hospitals worldwide. The platform helped reduce average operating time by up to 62 minutes in documented orthopedic and cranial surgeries, reinforcing the clinical value of customized models.
Advances in Biocompatible Materials and Printing Technologies
Breakthroughs in biocompatible polymers, metals, ceramics, and bioinks fuel market growth by enabling safe and durable medical products. These materials support the production of complex implants, scaffolds, and wearable devices that meet strict clinical requirements. Technologies such as photopolymerization, laser melting, and droplet deposition allow seamless fabrication of detailed structures, reducing production errors and enhancing device performance. Medical researchers also benefit from better control over porosity, surface finish, and mechanical strength. Broader material availability encourages hospitals and device companies to integrate 3D printing into treatment pathways. Continuous innovation ensures a steady shift from prototype applications to routine clinical use, expanding market acceptance.
- For instance, EOS systems are widely used for medical applications and are a major player in the field, the production of over a million implants is a figure not supported by search results related to the company's direct output or the general market data.
Growing Use of 3D Printing in Surgical Planning and Training
Surgeons increasingly employ 3D-printed anatomical models for planning complex procedures, improving accuracy and reducing operating time. These models help simulate surgical steps, anticipate risks, and enhance communication with patients. Medical trainees also gain hands-on learning through realistic replicas of organs, bones, and pathological structures. This reduces dependence on cadavers and improves training quality. Hospitals adopt these models to minimize intraoperative errors and improve patient confidence. Clinical studies continue to validate the benefits of 3D-assisted planning, strengthening regulatory support. As surgical complexity increases across cardiology, orthopedics, oncology, and neurology, demand for reliable 3D-printed guides and models grows steadily.
Key Trends & Opportunities
Expansion of Biofabrication and Tissue Engineering
Advances in biofabrication open new opportunities for engineered tissues, scaffolds, and regenerative therapies. Researchers experiment with multi-material printers and bioinks that mimic natural tissue structures. This trend supports long-term goals such as patient-specific organ patches, cartilage repair constructs, and vascularized tissues. Rising collaborations between research centers and biotech firms help scale early innovations toward clinical pathways. Regulatory agencies show growing interest in establishing standards for biofabricated products, which encourages further investment. While still in early development stages, tissue engineering via 3D printing promises major breakthroughs in treating chronic diseases and trauma, positioning the technology as a future cornerstone of regenerative medicine.
- For instance, CELLINK developed bioinks used in over 1,800 global research labs, enabling fabrication of tissue constructs with cell viability rates above 85% after printing.
Increasing Adoption of Point-of-Care 3D Printing Labs
Hospitals worldwide set up on-site 3D printing labs to speed up device production and reduce dependency on external suppliers. These labs can create surgical guides, dental models, and prosthetic components within hours rather than weeks. Point-of-care adoption supports emergency cases, trauma care, and reconstructive surgery by providing rapid, tailored solutions. The trend also reduces costs by minimizing outsourcing and improving workflow coordination between surgeons and biomedical engineers. Government programs and academic partnerships accelerate lab establishment in major hospitals. This shift enables high customization, improved patient communication, and faster treatment cycles, creating a strong opportunity for market expansion.
- For instance, 3D Systems supported more than 140 certified point-of-care medical printing programs across hospitals, enabling same-day production of surgical guides and anatomical models. Its printers achieve accuracy within 150 microns, reducing preoperative preparation time for complex surgeries. Clinical partners reported reductions of up to 70 minutes in operating room time when using patient-specific guides for maxillofacial and orthopedic procedures, highlighting the value of in-house labs.
Key Challenges
Regulatory Complexity for Custom Medical Devices
Navigating regulatory approval remains a major barrier, especially for patient-specific implants and bioengineered products. Authorities require detailed validation for material safety, mechanical performance, and manufacturing consistency. Because each device differs from the next, standardization becomes difficult, increasing approval time and compliance costs. Hospitals and manufacturers must align printing workflows with stringent quality management systems. Lack of uniform global standards adds more complexity, especially for cross-border commercialization. Smaller firms struggle to scale due to compliance burdens. These challenges slow widespread adoption and delay the transition from pilot projects to routine clinical deployment.
High Equipment Costs and Limited Technical Expertise
3D printing systems for medical use involve high initial investment, often restricting adoption in small hospitals and clinics. Advanced metal printers, bioprinters, and software tools require skilled technicians and biomedical engineers, creating a talent gap in many regions. Training staff, maintaining machinery, and ensuring consistent print quality add operational challenges. Limited awareness of 3D-printing capabilities also leads to underutilization of available systems. Smaller healthcare facilities may rely on external service providers, increasing turnaround time. These cost and skill constraints slow market penetration despite strong demand for personalized healthcare solutions.
Regional Analysis
North America
North America holds the leading position in the 3D Printing for Personalized Healthcare Market with about 38% share in 2024. Strong adoption comes from advanced hospital networks, early regulatory clarity, and high investment in medical 3D printing labs. Surgeons widely use anatomical models, surgical guides, and custom implants to improve outcomes. Research institutions support innovation in biofabrication and tissue engineering. The presence of major medical device companies accelerates commercialization of personalized solutions. Growing healthcare spending and higher acceptance of patient-specific treatments further strengthen market leadership across the United States and Canada.
Europe
Europe ranks second with nearly 29% market share in 2024, supported by strong medical infrastructure and early integration of additive manufacturing in clinical workflows. Countries such as Germany, the United Kingdom, France, and the Netherlands lead adoption across orthopedics, dental applications, and reconstructive surgery. The region benefits from strict quality standards and active regulatory bodies that encourage safe deployment of customized devices. Research partnerships between universities and biotech firms improve access to advanced biocompatible materials. Rising focus on precision medicine and government support for hospital-based 3D printing labs continue to elevate market growth.
Asia Pacific
Asia Pacific shows the fastest growth and accounts for about 24% share in 2024, driven by expanding healthcare infrastructure, rising medical tourism, and strong investment in digital health technologies. China, Japan, South Korea, and India lead adoption across surgical planning, prosthetics, and dental care. Local manufacturers increase access to cost-effective 3D printers and materials, supporting broader clinical use. Rapid urbanization and higher incidence of orthopedic and trauma cases further boost demand for custom implants. Growing research funding and government-backed innovation programs accelerate integration of personalized healthcare solutions across the region.
Latin America
Latin America holds roughly 6% share in 2024, with adoption rising in major economies such as Brazil, Mexico, and Argentina. Growth comes from improving hospital capabilities and increasing interest in patient-specific surgical tools. Medical universities and private clinics introduce 3D printing for training and procedural planning. However, limited reimbursement structures and high equipment costs slow broader deployment. Partnerships with global medical device companies help expand access to advanced technologies. As healthcare modernization continues, demand for personalized implants and anatomical models is expected to increase across key markets.
Middle East & Africa
The Middle East & Africa region represents about 3% share in 2024, with gradual but steady adoption led by the UAE, Saudi Arabia, and South Africa. Investments in smart hospitals, digital health, and surgical innovation support early use of anatomical models and prosthetic customization. Specialized centers integrate 3D printing for orthopedics and maxillofacial procedures. However, technological gaps and limited local manufacturing capacity restrict wider penetration. Government healthcare reforms, rising chronic disease cases, and growing interest in precision medicine create future opportunities for personalized medical printing solutions across emerging markets.
3D Printing for Personalized Healthcare Market Segmentations:
By Technology
- Droplet Deposition
- Photopolymerization
- Laser Beam Melting
- Electronic Beam Melting (EBM)
- Laminated Object Manufacturing
- Others
By Application
- External Wearable Devices
- Clinical Study Devices
- Implants
- Tissue Engineering
By End User
- Medical & Surgical Centers
- Pharmaceutical & Biotechnology Companies
- Academic Institutions
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the 3D Printing for Personalized Healthcare Market features strong participation from leading innovators such as Materialise NV, Stratasys Ltd, Organovo Holdings, Inc., Proto Labs, General Electric, 3D Systems Corporation, Formlabs Inc., SLM Solutions Group AG, ExOne Company, and Oxford Performance Materials, Inc. These companies focus on advanced printing systems, biocompatible materials, and software platforms that support the creation of custom implants, surgical guides, prosthetics, and anatomical models. Many players invest in R&D to enhance precision, speed, and regulatory compliance for clinical-grade printing. Strategic partnerships with hospitals, research institutes, and medical device manufacturers help expand clinical adoption. Firms also compete through point-of-care printing solutions, cloud-based design tools, and integrated workflow systems. Growing emphasis on biofabrication and tissue engineering pushes companies to develop next-generation bioprinting technologies. This competitive environment drives continuous innovation and accelerates the transition of 3D printing from prototyping to routine clinical use.
Key Player Analysis
- Materialise NV
- Stratasys Ltd
- Organovo Holdings, Inc.
- Proto Labs
- General Electric
- 3D Systems Corporation
- Formlabs Inc.
- SLM Solutions Group AG
- ExOne Company
- Oxford Performance Materials, Inc.
Recent Developments
- In November 2025, ExOne Company ExOne was highlighted as a key company in a North America 3D Printing in Healthcare market analysis covering customized surgical models, implants, prosthetics, and tissue engineering applications. Its binder-jet 3D printing systems are recognized in the report as part of the technology base enabling personalized medical solutions in the region.
- In Dec 2024, Materialise NV Launched a fully integrated Materialise Mimics platform to speed 3D planning and the creation of patient-specific devices, improving workflow efficiency for hospitals and medical-device partners (aimed squarely at scaling personalized care).
- In April 2024, Formlabs launched its Form 4 and Form 4B resin 3D printers, with Form 4B designed specifically for dental and medical professionals. It supports a wide range of biocompatible resins for fast production of patient-specific dental models, surgical guides, and other personalized healthcare parts.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of patient-specific implants will accelerate as hospitals expand 3D printing capabilities.
- Point-of-care printing labs will become standard in major medical centers.
- Advances in bioinks and biomaterials will improve tissue engineering applications.
- Bioprinting progress will move closer to functional organ and tissue development.
- Software integration will enhance design accuracy and speed for clinical models.
- Regulatory clarity will strengthen, supporting wider approval of custom medical devices.
- Cost reductions in printers and materials will increase adoption among mid-sized hospitals.
- Training programs will expand, improving technical expertise in clinical 3D printing.
- Partnerships between device firms and healthcare institutions will drive innovation.
- Asia Pacific will show the fastest growth as investment in personalized care rises.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Personalized Medical Solutions
The shift toward patient-specific care is driving demand for 3D printing in healthcare, as hospitals and surgeons increasingly require custom implants, anatomical models, and prosthetics that precisely match individual patient anatomy, improving surgical outcomes and reducing recovery times.
Advances in Biocompatible Materials and Printing Technologies
Breakthroughs in biocompatible polymers, metals, ceramics, and bioinks enable the safe and effective production of complex medical devices, implants, and tissue scaffolds, supporting broader clinical adoption and expanding the range of treatable conditions.
Expansion of Point-of-Care 3D Printing Labs
Hospitals are establishing on-site 3D printing labs to rapidly produce surgical guides, dental models, and prosthetic components, reducing turnaround times, lowering costs, and enabling immediate customization for urgent and complex cases.
Growth in Surgical Planning and Training Applications
Surgeons and medical trainees increasingly use 3D-printed anatomical models for preoperative planning and education, which enhances procedural accuracy, reduces intraoperative errors, and improves patient communication and confidence.
Progress in Biofabrication and Tissue Engineering
Ongoing innovation in biofabrication and tissue engineering, including the development of advanced bioinks and multi-material printers, is opening new possibilities for regenerative medicine, such as patient-specific tissue constructs and organ patches.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for 3D Printing for Personalized Healthcare Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is 3D Printing for Personalized Healthcare Market projected to grow between 2024 and 2032?
Which 3D Printing for Personalized Healthcare Market segment held the largest share in 2024?
What are the primary factors fueling the growth of 3D Printing for Personalized Healthcare Market?
Who are the leading companies in 3D Printing for Personalized Healthcare Market?
Which region commanded the largest share of 3D Printing for Personalized Healthcare Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Medical & Surgical Centers
- 1.2.2 Pharmaceutical & Biotechnology Companies
- 1.2.3 Academic Institutions
- 1.3 By Technology
- 1.3.1 Droplet Deposition
- 1.3.2 Photopolymerization
- 1.3.3 Laser Beam Melting
- 1.3.4 Electronic Beam Melting (EBM)
- 1.3.5 Laminated Object Manufacturing
- 1.3.6 Others
- 1.4 By Application
- 1.4.1 Implants
- 1.4.2 Tissue Engineering
- 1.4.3 External Wearable Devices
- 1.4.4 Clinical Study Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1627 million → 2032: USD 6506.74 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D Printing for Personalized Healthcare Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D Printing for Personalized Healthcare Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D Printing for Personalized Healthcare Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D Printing for Personalized Healthcare Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D Printing for Personalized Healthcare Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D Printing for Personalized Healthcare Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D Printing for Personalized Healthcare Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D Printing for Personalized Healthcare Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1627 million → 2032: USD 6506.74 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D Printing for Personalized Healthcare Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medical & Surgical Centers
- 12.3.7.2 Pharmaceutical & Biotechnology Companies
- 12.3.7.3 Academic Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Droplet Deposition
- 12.4.7.2 Photopolymerization
- 12.4.7.3 Laser Beam Melting
- 12.4.7.4 Electronic Beam Melting (EBM)
- 12.4.7.5 Laminated Object Manufacturing
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Implants
- 12.5.7.2 Tissue Engineering
- 12.5.7.3 External Wearable Devices
- 12.5.7.4 Clinical Study Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D Printing for Personalized Healthcare End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D Printing for Personalized Healthcare Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D Printing for Personalized Healthcare Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D Printing for Personalized Healthcare Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Materialise NV
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stratasys Ltd
- 18.4 Organovo Holdings, Inc.
- 18.5 Proto Labs
- 18.6 General Electric
- 18.7 3D Systems Corporation
- 18.8 Formlabs Inc.
- 18.9 SLM Solutions Group AG
- 18.10 ExOne Company
- 18.11 Oxford Performance Materials, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

