
Colorectal Cancer Screening Tests Market Overview:
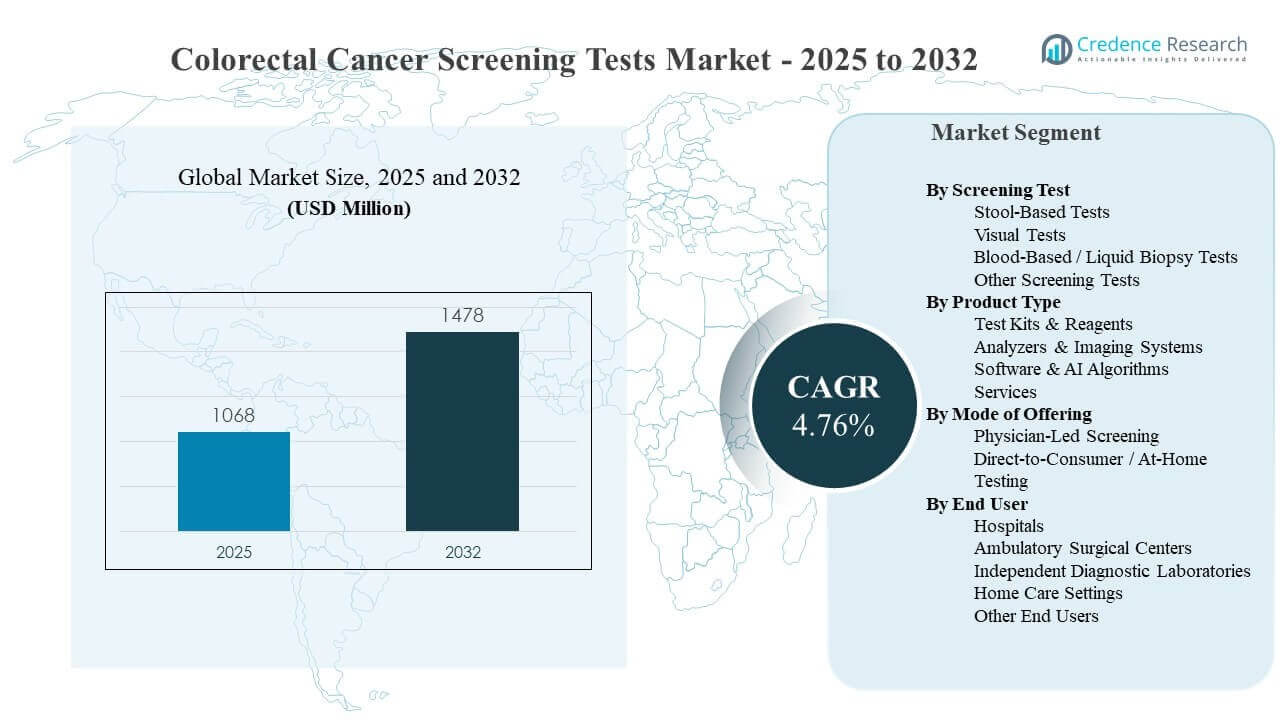
The global colorectal cancer screening tests market size was estimated at USD 1,068 million in 2025 and is expected to reach USD 1,478 million by 2032, growing at a CAGR of 4.76% from 2025 to 2032. Growth is primarily supported by expanding guideline-led screening uptake, reinforced by organized programs and payer-backed initiatives that raise participation and improve follow-up pathways after positive results. Technology progress across noninvasive assays and procedure workflows is improving patient acceptance and clinical confidence, helping screening shift from episodic testing to more consistent population-scale utilization.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Colorectal Cancer Screening Tests Market Size 2025 | USD 1,068 million |
| Colorectal Cancer Screening Tests Market, CAGR | 4.76% |
| Colorectal Cancer Screening Tests Market Size 2032 | USD 1,478 million |
Key Market Trends & Insights
- North America accounted for 34.70% share in 2025, reflecting strong reimbursement coverage, program maturity, and high diagnostic throughput across lab and endoscopy capacity.
- Europe captured 29.80% share in 2025, supported by broader adoption of organized screening and standardized pathways that improve completion and referral for confirmatory procedures.
- Asia Pacific reached 25.90% share in 2025, driven by rising preventive-care demand in large urban populations and expanding diagnostic infrastructure across major markets.
- Colonoscopy led the market with a 43.10% share in 2025, anchored by its clinical role in confirmatory diagnosis and polyp removal within integrated screening pathways.
- Physician-led screening represented 74.20% share in 2025, indicating continued reliance on clinician-directed ordering, referral, and follow-up coordination.
Segment Analysis
Market segmentation reflects a dual-track model in which procedure-based screening remains central for diagnostic certainty and therapeutic intervention, while noninvasive testing expands access and improves adherence among average-risk populations. Stakeholders are prioritizing higher completion rates, faster turnaround times, and improved navigation from initial testing to confirmatory procedures. The market is also shaped by workflow modernization, including digital ordering, reminders, and clinical decision support that reduce friction across patient journeys.
Noninvasive formats continue to broaden the addressable audience by lowering barriers related to bowel preparation, facility visits, and time away from work. At the same time, health systems are working to protect procedure capacity for high-risk patients and for follow-up after positive noninvasive results. This combination supports steady demand for kits and reagents, imaging and endoscopy ecosystems, and related services that enable screening, triage, diagnosis, and surveillance.
By Screening Test Insights
Colonoscopy accounted for the largest share of 43.10% in 2025. The modality remains the reference standard for confirmatory evaluation after positive noninvasive results and is closely tied to clinical guidelines and specialist referral patterns. Established reimbursement practices and care pathways keep utilization resilient even as noninvasive testing expands. Procedural ecosystems also benefit from ongoing upgrades in visualization, workflow efficiency, and quality metrics that support consistent performance across screening programs.
By Product Type Insights
Test Kits & Reagents accounted for the largest share of 55.40% in 2025. High-volume screening workflows rely on scalable consumables that can be deployed across centralized laboratories and distributed collection channels. Kits support repeat-testing cycles and broader outreach, which helps sustain recurring demand. Program managers also favor formats that improve operational predictability, simplify logistics, and reduce patient burden, reinforcing the importance of consumable-led screening strategies.
By Mode of Offering Insights
Physician-Led Screening accounted for the largest share of 74.20% in 2025. Clinician-directed pathways remain dominant because they align with guideline-based risk assessment, referral coordination, and the clinical follow-up required after positive results. Health systems and payers continue to rely on physician-led models to improve adherence, reduce missed follow-ups, and standardize pathways across populations. Integrated ordering, reminders, and navigation services further strengthen this channel’s role in driving completion and continuity of care.
By End User Insights
Hospitals accounted for the largest share of 39.30% in 2025. Hospitals anchor procedure-based screening and downstream diagnostic workups, particularly when imaging and endoscopy resources are bundled into coordinated care pathways. Multidisciplinary capabilities also support triage, confirmatory diagnosis, and surveillance planning, which concentrates activity in hospital settings. At the same time, lab networks and ambulatory centers continue to expand capacity and improve access, supporting a broader shift toward distributed screening without displacing hospitals’ central role.
Colorectal Cancer Screening Tests Market Drivers
Expansion of guideline-led screening and earlier eligibility
Lower starting ages in screening guidance and stronger awareness campaigns are expanding the eligible population and increasing screening volumes. Health systems and payers are focusing on improving participation and closing adherence gaps through outreach and navigation. Organized programs increasingly connect initial testing with clear referral pathways for follow-up procedures. These efforts raise completion rates and improve continuity across screening, diagnosis, and surveillance.
Growth in noninvasive testing adoption and repeat-testing behavior
Noninvasive options reduce barriers linked to procedure anxiety, preparation burden, and access constraints. Stool-based and emerging blood-based approaches improve convenience and make screening easier to integrate into routine preventive care. Repeat-testing cycles support recurring demand and strengthen program planning. Broader distribution through retail and direct ordering further supports adoption, particularly among populations that avoid facility-based screening.
- For instance, Exact Sciences' second-generation Cologuard multi-target stool DNA test demonstrated an overall sensitivity of 95.2% for colorectal cancer at a specificity of 92.4% for colonoscopy-confirmed negative samples, with 83.3% sensitivity for high-grade dysplasia.
Workflow modernization across diagnostics and endoscopy ecosystems
Digital ordering, reminders, and results routing reduce friction across patient journeys and strengthen follow-up discipline. Provider organizations are investing in standard protocols that connect positive results to confirmatory procedures and surveillance schedules. Endoscopy and imaging workflows continue to improve through operational upgrades that increase throughput and standardize quality. Combined, these improvements support higher effective capacity and greater reliability of program performance.
Rising emphasis on population health outcomes and total cost of care
Payers and providers increasingly view screening as a measurable lever to reduce downstream treatment costs and improve outcomes through earlier detection. Programs are designed around performance indicators such as completion rates and time-to-follow-up. Procurement decisions are increasingly influenced by operational efficiency, patient engagement capability, and pathway integration. This results in stronger demand for solutions that improve adherence and shorten delays between screening and diagnosis.
- For instance, research published by the Blue Cross Blue Shield Association and Blue Health Intelligence using member claims data found that 81% of BCBS members diagnosed with colorectal cancer through a preventive screening were classified at an early stage, versus a 73% early-stage rate in the overall diagnosed population.
Colorectal Cancer Screening Tests Market Challenges
Capacity constraints remain a structural challenge, especially for specialist availability and procedure throughput in settings with high demand. Even when noninvasive testing increases participation, follow-up colonoscopy bottlenecks can limit the clinical benefits of expanded screening. Program operators must manage referral discipline, patient navigation, and scheduling coordination to avoid delays that reduce effectiveness.
- For instance, Medtronic’s GI Genius computer-aided detection platform reached 99.7% sensitivity with a false-positive rate below 1%, performed real-time analysis 82% faster than the endoscopist, and increased adenoma detection rate to 54.8% versus 40.4% with conventional colonoscopy, showing how technology can improve the diagnostic yield of each limited colonoscopy slot.
Variation in access, reimbursement, and program maturity across geographies also constrains uniform adoption. Inconsistent patient awareness and uneven infrastructure for lab processing and endoscopy can reduce completion rates and increase drop-off after positive tests. Ensuring high-quality sample handling, timely reporting, and consistent follow-up requires investment in logistics and care coordination. These factors can slow scaling and create performance differences across regions and care settings.
Market Trends and Opportunities
A major opportunity is the continued shift toward decentralized screening models that improve convenience and participation. Expanded distribution, simplified collection, and remote support tools help reduce friction for average-risk populations. As care pathways mature, solutions that combine ordering, reminders, and follow-up coordination can differentiate offerings and improve measured outcomes. This trend supports growth across kits, services, and enabling software.
- For instance, Exact Sciences' Cologuard Plus an at-home stool DNA test approved by the FDA in early 2025 incorporates novel biomarkers and enhanced sample stability that reduce false positives by nearly 40% compared to its predecessor, minimizing unnecessary follow-up colonoscopies.
Another trend is the broader integration of analytics and decision support across screening and procedure workflows. Workflow tools that reduce administrative burden and improve documentation can strengthen referral discipline and pathway standardization. Clinical performance monitoring and quality reporting also support program optimization. Over time, differentiated platforms will be those that improve completion rates and reduce time-to-follow-up across the full screening-to-diagnosis continuum.
Regional Insights
North America
North America led the market with 34.70% share in 2025. Program maturity, strong reimbursement frameworks, and established lab and endoscopy capacity support consistent screening volumes. Stakeholders continue to emphasize adherence improvement and follow-up discipline to reduce missed diagnostic pathways after positive results. Integration of digital navigation and standardized referral protocols supports program efficiency and continuity of care.
Europe
Europe accounted for 29.80% share in 2025. Organized screening pathways and standardized protocols support broader participation across covered populations. Many markets emphasize scalable noninvasive testing with clear referral mechanisms for confirmatory procedures. Continued focus on population health KPIs and quality metrics supports stable adoption and incremental modernization of screening workflows.
Asia Pacific
Asia Pacific represented 25.90% share in 2025. Urban preventive-care growth and expanding diagnostic infrastructure are driving adoption across major countries. Private lab expansion and hospital investments are improving access to screening and follow-up services. Ongoing efforts to improve awareness and program reach are expected to sustain growth as capacity and pathways mature.
Latin America
Latin America reached 5.80% share in 2025. Adoption varies by country due to differences in reimbursement, infrastructure, and program organization. Growth is supported by increasing awareness and gradual expansion of diagnostic capacity, particularly in larger urban centers. Wider access to scalable noninvasive testing can help improve participation where procedure capacity is constrained.
Middle East & Africa
Middle East and Africa held 3.80% share in 2025. Screening uptake remains uneven, shaped by differences in health system capacity, awareness, and access to diagnostics. Growth is supported by expanding private health care networks and gradual improvements in preventive care utilization in select markets. Stronger referral coordination and capacity investments will be critical to improving completion and follow-up rates.
Competitive Landscape
Competition centers on improving screening participation, pathway completion, and follow-up discipline through modality innovation and workflow enablement. Companies differentiate through test performance, operational scalability, and the ability to integrate ordering, logistics, and results routing into provider workflows. Partnerships across diagnostics, care navigation, and provider channels strengthen distribution reach and improve program performance. Long-term positioning increasingly depends on demonstrating measurable improvements in completion rates and time-to-diagnosis across end-to-end screening pathways.
Exact Sciences Corp. is positioned around scaled noninvasive screening and pathway enablement, combining broad access channels with operational support that improves patient completion and follow-up. The company’s approach emphasizes consistency in test delivery, results management, and care coordination to reduce drop-off after screening. Ongoing focus on improving screening participation supports demand generation, while integration into clinical workflows strengthens repeat utilization. This model aligns with payer and provider priorities for population outcomes and total cost of care.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Exact Sciences Corp.
- Guardant Health
- Geneoscopy Inc.
- Quest Diagnostics
- Labcorp
- Olympus Corp.
- Fujifilm Holdings Corp.
- Medtronic plc
- KARL STORZ SE & Co. KG
- PENTAX Medical
- Epigenomics AG
- Freenome Holdings Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In a March 2025, Exact Sciences launched Cologuard Plus, a next-generation noninvasive colorectal cancer screening test for average-risk adults aged 45 and older. The company said the test is FDA-approved, covered by Medicare, and designed to reduce unnecessary follow-up colonoscopies compared with the original Cologuard test.
- In a July 2025, Geneoscopy announced a new FDA-approved stool collection method aimed at simplifying at-home colorectal cancer screening. The company described the update as a way to make stool collection easier for patients using its colorectal cancer screening platform.
- In an August 2025, Exact Sciences and Freenome said they entered an agreement under which Exact Sciences will acquire exclusive U.S. rights to current and future versions of Freenome’s blood-based, single-indication colorectal cancer screening tests. Freenome said the deal is an exclusive license agreement worth up to $885 million based on regulatory and screening-guideline milestones, with commercial launch of the first version anticipated in 2026.
- In a September 2025, Guardant Health and Quest Diagnostics unveiled a multi-year strategic collaboration to broaden access to Guardant’s Shield blood-based colorectal cancer screening test in the United States. The companies said the partnership would use Quest Diagnostics’ national testing network to make Shield available more widely to clinicians and patients.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1,068 million |
| Revenue forecast in 2032 | USD 1,478 million |
| Growth rate (CAGR) | 4.76% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Screening Test Outlook; By Product Type Outlook; By Mode of Offering Outlook; By End User Outlook |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Exact Sciences Corp.; Guardant Health; Geneoscopy Inc.; Quest Diagnostics; Labcorp; Olympus Corp.; Fujifilm Holdings Corp.; Medtronic plc; KARL STORZ SE & Co. KG; PENTAX Medical; Epigenomics AG; Freenome Holdings Inc. |
| No. of Pages | 326 |
Segmentation
By Screening Test- Stool-Based Tests
- Fecal Immunochemical Test (FIT)
- Guaiac-based Fecal Occult Blood Test (gFOBT)
- Stool DNA Test (sDNA/FIT-DNA)
- Visual Tests
- Colonoscopy
- CT Colonography
- Flexible Sigmoidoscopy
- Blood-Based / Liquid Biopsy Tests
- Septin9 Blood Test
- microRNA Panels
- Other Emerging Blood-Based Biomarker Tests
- Other Screening Tests
- Capsule Endoscopy
- Other Emerging Screening Modalities
- Test Kits & Reagents
- Analyzers & Imaging Systems
- Software & AI Algorithms
- Services
- Physician-Led Screening
- Direct-to-Consumer / At-Home Testing
- Hospitals
- Ambulatory Surgical Centers
- Independent Diagnostic Laboratories
- Home Care Settings
- Other End Users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the colorectal cancer screening tests market in 2025 and its forecast for 2032?
What is the CAGR for the colorectal cancer screening tests market during 2025–2032?
Which segment holds the largest share in 2025?
What factors are driving growth in this market?
Who are the leading companies in the colorectal cancer screening tests market?
Which region leads the market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1,068 million → 2032: USD 1,478 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Colorectal Cancer Screening Tests Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Colorectal Cancer Screening Tests Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Colorectal Cancer Screening Tests Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Colorectal Cancer Screening Tests Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Colorectal Cancer Screening Tests Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Colorectal Cancer Screening Tests Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Colorectal Cancer Screening Tests Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Colorectal Cancer Screening Tests Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1,068 million → 2032: USD 1,478 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Colorectal Cancer Screening Tests Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Colorectal Cancer Screening Tests Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Colorectal Cancer Screening Tests Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Colorectal Cancer Screening Tests Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

