
Market Overview
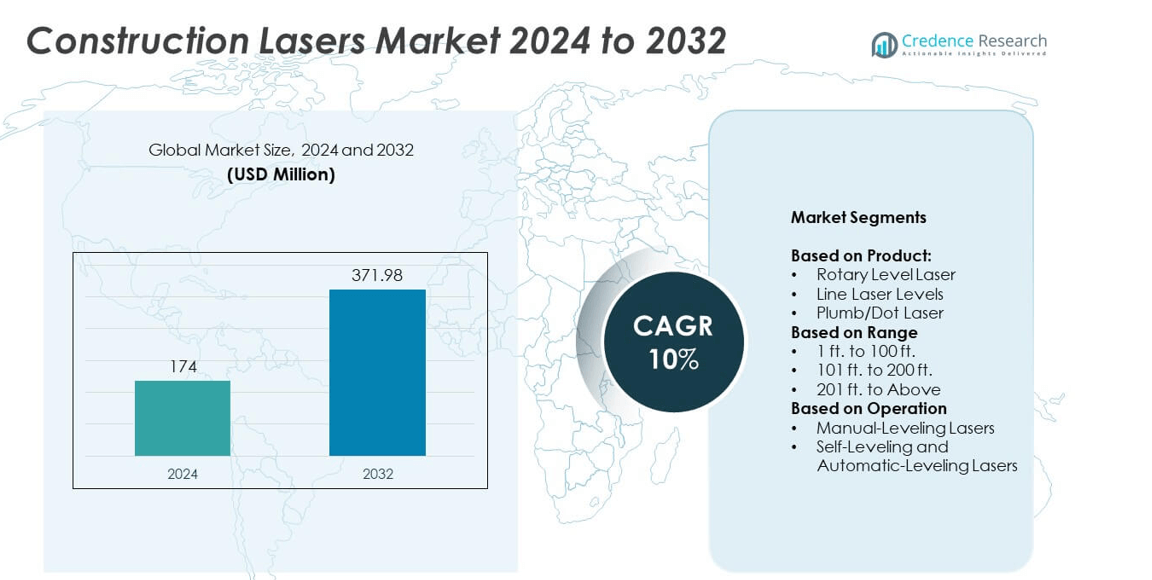
Construction Lasers market size was valued USD 174 Million in 2024 and is anticipated to reach USD 371.98 Million by 2032, at a CAGR of 10% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction Lasers Market Size 2024 | USD 174 Million |
| Construction Lasers Market, CAGR | 10% |
| Construction Lasers Market Size 2032 | USD 371.98 Million |
The construction lasers market is led by key players such as Laser Tools Co. Inc, Spectra Precision, Fluor, STABILA, Trimble, Hilti, Topcon, Qualcomm, Stanley Black & Decker, Inc., ADA Instruments, Pacific Laser Systems, SOLA, Makita, Leica Geosystems AG, AdirPro, DotProduct, and Kapro Industries Ltd. These companies focus on developing advanced rotary and self-leveling lasers with improved accuracy, durability, and digital integration to meet growing construction demands. North America emerged as the leading region, holding 38% of the market share in 2024, driven by significant infrastructure investments, technological adoption, and the presence of established construction equipment manufacturers.
Market Insights
- The construction lasers market was valued at USD 174 million in 2024 and is expected to reach USD 371.98 million by 2032, growing at a CAGR of 10%.
- Rising infrastructure development, urbanization, and demand for accurate leveling tools are driving market growth across residential, commercial, and industrial construction projects.
- Key trends include the adoption of smart, connected laser systems, integration with BIM platforms, and rising popularity of compact, multi-functional devices for small and mid-sized contractors.
- The market is moderately competitive, with companies focusing on innovation, product durability, wireless connectivity, and expanding distribution networks to maintain an edge.
- North America led the market with 38% share in 2024, followed by Europe at 27% and Asia Pacific at 25%, while rotary level lasers accounted for the largest product share, driven by their wide application in grading, alignment, and large-scale infrastructure projects.
Market Segmentation Analysis:
By Product
Rotary level lasers dominated the construction lasers market with over 45% share in 2024. Their ability to project 360-degree horizontal and vertical reference lines makes them ideal for large construction sites. These lasers are preferred for grading, foundation work, and alignment applications that demand high accuracy. Line laser levels followed closely, finding use in interior construction, tiling, and framing due to their ease of setup. Demand is driven by growing infrastructure projects and contractors’ focus on reducing human error. Advanced models with digital displays and Bluetooth connectivity further boost adoption across residential and commercial projects.
- For instance, Spectra Precision sells the LL500 self-leveling rotary laser with a working diameter of 1,600 ft and accuracy of ±1/16-inch at 100 ft.
By Range
Construction lasers in the 101 ft. to 200 ft. range accounted for around 50% of market share in 2024. This range supports most mid-size construction tasks, including site leveling, ceiling alignment, and wall positioning, making it the preferred choice among contractors. Models in this range balance cost and coverage, offering high precision without excessive investment. The segment benefits from growing mid-scale infrastructure projects, especially in developing regions. Increasing demand for portable and battery-efficient devices with extended operating ranges is encouraging manufacturers to introduce improved models with enhanced beam visibility and rugged design.
- For instance, the Topcon RL-H5A rotary laser has a working span of 800 meters (≈ 2,600 ft) diameter.
By Operation
Self-leveling and automatic-leveling lasers led the market with approximately 60% share in 2024. These lasers automatically adjust to maintain accuracy, saving time and reducing manual calibration efforts. Their adoption is rising in commercial and civil construction projects where efficiency and precision are critical. Manual-leveling lasers remain in use for smaller projects and budget-conscious buyers but are gradually being replaced. Growth is driven by the demand for user-friendly tools that minimize errors and support faster project execution. Integration of smart sensors and wireless controls is further improving productivity on construction sites.
Market Overview
Rising Infrastructure Development
Rising infrastructure spending is the primary growth driver for the construction lasers market. Large-scale projects such as highways, airports, and urban redevelopment demand precise leveling and alignment tools. Rotary and line lasers ensure accuracy in grading, excavation, and layout tasks, reducing project delays. Emerging economies are investing heavily in public infrastructure, boosting demand for advanced surveying tools. Government initiatives to upgrade aging infrastructure in developed regions further strengthen the market. This driver remains the most critical as it directly fuels product adoption across residential, commercial, and industrial construction sectors.
- For instance, the LRE203-G rotary laser from UniqueNav features an automatic leveling horizontal accuracy of $\pm$15" (arc seconds). When used with a receiver, the instrument has a working range of up to 1,000 meters diameter. This makes it suitable for large-scale construction and surveying projects
Adoption of Digital Construction Tools
The integration of digital construction tools drives market growth by enabling precision and automation. Self-leveling lasers, often paired with digital measuring devices, enhance efficiency and reduce human errors. Contractors increasingly favor connected devices that integrate with Building Information Modeling (BIM) systems. This digital shift supports faster project completion and reduces rework. Manufacturers are launching smart lasers with Bluetooth and wireless connectivity to cater to this demand. The adoption of automated solutions is expected to expand with Industry 4.0 practices, fueling further penetration of technologically advanced construction lasers globally.
- For instance, the DeWalt DCLE34033D1 High Precision 3 x 360° Green Laser features three full-coverage green laser lines. It has an accuracy of $\pm\(1/8-inchat50ft(\)\pm$3.1mm at 15m). The visible working range is up to 230 ft (70 m). When used with an optional DW0892G detector in pulse mode, the working range extends to 330 ft (100 m). The laser is compatible with either a 12V MAX or 20V MAX battery.
Growing Focus on Worker Productivity
Increasing demand for improved worker productivity significantly supports market expansion. Construction lasers reduce manual effort in leveling, alignment, and layout tasks, enabling faster project execution. Companies seek to minimize labor costs and improve output, making precision tools essential. The need for accurate measurements in large construction projects enhances reliance on automated systems. Portable and battery-efficient models allow teams to work continuously without downtime. This focus on efficiency is pushing contractors to replace traditional tools with advanced laser equipment, driving overall market growth across all construction project sizes.
Key Trends & Opportunities
Integration of Smart Technologies
Smart construction lasers equipped with wireless connectivity and sensor-based automation are gaining popularity. These devices allow remote operation and instant data transfer, streamlining construction workflows. Integration with cloud platforms enables real-time monitoring and error detection, improving decision-making. Manufacturers are leveraging IoT and AI to enhance beam accuracy and adapt to site conditions. This trend opens opportunities for suppliers to target high-tech infrastructure projects and smart city developments. The push toward connected job sites ensures that smart-enabled laser tools will see strong adoption over the forecast period.
- For instance, PLS (a Fluke company)’s HV2R Manual-Slope Rotary Laser Kit features accuracy of ≤ 2.2 mm at 30 m (≈ 3/32-inch at 100 ft), working range of ≤ 30 m without detector and ≤ 300 m with its XLD detector.
Rise of Compact and Multi-Function Devices
There is a growing opportunity in compact, multi-functional laser devices that offer portability and flexibility. Contractors increasingly demand tools that can handle multiple tasks, such as grading, alignment, and squaring, with a single setup. Compact models save space and are ideal for interior and residential applications where mobility is key. Manufacturers are focusing on lightweight yet rugged designs that deliver professional accuracy. This trend aligns with the increasing demand for cost-effective solutions for small and medium contractors, creating new revenue streams for market players globally.
- For instance, Spectra Precision’s LL300N rotary laser has ±3/32 inch accuracy at 100 ft, a working diameter range of 1,650 ft (500 m), and battery life of about 90 hours on alkaline batteries.
Key Challenges
High Initial Investment Costs
The high upfront cost of advanced construction lasers remains a major challenge for market penetration. Small contractors and individual users often hesitate to invest in rotary or self-leveling models due to budget constraints. Although these tools improve accuracy and save time, the initial expense can be prohibitive, especially in price-sensitive markets. Rental services and used equipment markets are growing as a result, impacting direct sales. Manufacturers must focus on offering affordable models or financing options to expand adoption among small and mid-scale construction businesses.
Lack of Skilled Operators
The shortage of trained personnel to operate advanced construction lasers poses another challenge. Accurate use of self-leveling and rotary lasers requires some level of technical expertise. Inexperienced operators can misinterpret readings, leading to costly construction errors and rework. Training programs and easy-to-use interfaces are critical to overcome this barrier. Manufacturers are working on developing user-friendly devices with intuitive controls and auto-calibration features. However, widespread adoption may still be limited until workforce training improves, particularly in developing markets where skill gaps are more prominent.
Regional Analysis
North America
North America held the largest share of the construction lasers market with 38% in 2024. The region benefits from robust investments in commercial buildings, infrastructure upgrades, and smart city projects. The U.S. dominates due to rapid adoption of self-leveling and rotary lasers in road construction and residential developments. Contractors focus on precision tools to reduce project delays, driving strong demand. Canada’s construction sector also contributes through public infrastructure spending and housing projects. Growing use of digital construction technologies, coupled with government funding for transportation and energy infrastructure, supports continued growth of construction lasers across the region.
Europe
Europe accounted for 27% of the construction lasers market in 2024, driven by renovation projects and energy-efficient building initiatives. Countries like Germany, the U.K., and France lead adoption due to stringent building standards and growing demand for precise leveling tools. Urban redevelopment projects and government focus on sustainable infrastructure contribute to market expansion. Integration of lasers with digital measuring systems is gaining traction, improving efficiency. The shift toward prefabrication and modular construction supports demand for accurate tools. Eastern Europe is experiencing gradual growth, supported by rising construction investments in Poland, Hungary, and other emerging economies.
Asia Pacific
Asia Pacific captured 25% market share in 2024, supported by rapid urbanization and infrastructure expansion in China, India, and Southeast Asia. Mega projects such as metro rail networks, smart cities, and industrial zones drive demand for rotary and line lasers. Affordable labor and government funding encourage the use of modern tools to speed up timelines. Manufacturers are increasingly targeting this region with cost-effective and portable solutions. Japan and South Korea contribute through technological innovation and advanced construction practices. The growing real estate sector and large-scale public infrastructure projects are expected to sustain strong market growth.
Latin America
Latin America represented 6% of the construction lasers market in 2024. Brazil, Mexico, and Chile are leading contributors, supported by increasing investment in residential and commercial construction. Infrastructure modernization programs, particularly in transportation and energy, drive adoption of precise leveling and alignment tools. Demand is rising for cost-effective and durable equipment suited to varied site conditions. Economic fluctuations and budget limitations remain challenges but are being offset by public-private partnerships. Adoption of portable laser devices is increasing among small contractors, helping improve productivity and accuracy in construction projects across the region’s emerging economies.
Middle East & Africa
Middle East & Africa held a 4% share of the construction lasers market in 2024. Rapid urbanization and ambitious infrastructure projects, including smart cities and mega real estate developments, fuel market demand. The Gulf countries dominate due to large-scale investments in commercial buildings, airports, and transport networks. Africa is witnessing steady growth through housing projects and government-backed infrastructure initiatives. The region is gradually adopting self-leveling lasers to meet project quality standards. Although economic volatility and limited skilled workforce pose challenges, increasing foreign investment and construction activity continue to support the market’s expansion across key countries.
Market Segmentations:
By Product:
- Rotary Level Laser
- Line Laser Levels
- Plumb/Dot Laser
By Range
- 1 ft. to 100 ft.
- 101 ft. to 200 ft.
- 201 ft. to Above
By Operation
- Manual-Leveling Lasers
- Self-Leveling and Automatic-Leveling Lasers
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The construction lasers market is characterized by the presence of key players such as Laser Tools Co. Inc, Spectra Precision, Fluor, STABILA, Trimble, Hilti, Topcon, Qualcomm, Stanley Black & Decker, Inc., ADA Instruments, Pacific Laser Systems, SOLA, Makita, Leica Geosystems AG, AdirPro, DotProduct, and Kapro Industries Ltd. Competition is driven by continuous innovation, with companies focusing on developing advanced self-leveling and rotary lasers with enhanced accuracy and durability. Many players are integrating wireless connectivity and digital interfaces to meet the demand for smart construction tools. Partnerships with distributors and contractors expand market presence and improve after-sales service networks. Manufacturers are also investing in compact, battery-efficient models to cater to small and medium contractors. The competitive landscape is further shaped by price differentiation, product reliability, and regional expansion strategies, ensuring that companies remain competitive in a growing market focused on precision and efficiency.
Key Player Analysis
- Laser Tools Co. Inc
- Spectra Precision
- Fluor
- STABILA
- Trimble
- Hilti
- Topcon
- Qualcomm
- Stanley Black & Decker, Inc.
- ADA Instruments
- Pacific Laser Systems
- SOLA
- Makita
- Leica Geosystems AG
- AdirPro
- DotProduct
- Kapro Industries Ltd.
Recent Developments
- In 2025, STABILA launched the LAX 500 G cross line plus plumb point laser. This model features highly visible green laser lines that allow users to work directly at distances up to 40 meters, enhancing usability for interior construction tasks.
- In 2023, Topcon positioning systems launched the LN-50 3D laser. This new layout navigator offers streamline precision measurement. The range for this new laser is 50-meters, which is user friendly, self-leveling and cost effective.
- In 2022, Precisional LLC acquired four industrial technology businesses from Trimble, including Spectra Precision Tools.
Report Coverage
The research report offers an in-depth analysis based on Product, Range, Operation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by infrastructure development projects worldwide.
- Demand for self-leveling and automatic lasers will increase due to rising need for accuracy.
- Adoption of smart and connected laser devices will expand with digital construction trends.
- Compact and multi-functional lasers will gain popularity among small and mid-scale contractors.
- Asia Pacific will emerge as a major growth hub supported by urbanization and mega projects.
- Manufacturers will focus on rugged, battery-efficient models for outdoor construction applications.
- Integration with BIM systems will enhance efficiency and project planning in construction sites.
- Rental services for construction lasers will expand, catering to cost-sensitive contractors.
- Product innovation will focus on improving visibility and range for large-scale projects.
- Training programs will grow to address skill gaps and ensure proper equipment handling.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Infrastructure Development
Large-scale infrastructure projects such as highways, airports, and urban redevelopment require precise leveling and alignment, driving demand for advanced construction lasers across residential, commercial, and industrial sectors.
Adoption of Digital Construction Tools
Integration of construction lasers with digital platforms and BIM systems enhances project accuracy and efficiency, encouraging contractors to invest in smart, connected laser devices that streamline workflows and reduce human error.
Growing Focus on Worker Productivity
Construction lasers significantly reduce manual labor and speed up leveling and alignment tasks, enabling faster project completion and minimizing labor costs, which is increasingly important for contractors seeking to improve productivity.
Integration of Smart Technologies
The adoption of wireless connectivity, sensor-based automation, and IoT-enabled features in construction lasers allows for remote operation, real-time data transfer, and improved accuracy, making these tools attractive for high-tech and large-scale projects.
Expansion of Compact and Multi-Function Devices
Demand for portable, multi-functional laser devices is rising among small and mid-sized contractors who require flexible, cost-effective tools for a variety of construction tasks, supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Construction Lasers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Construction Lasers market projected to grow between 2025 and 2032?
Which Construction Lasers market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Construction Lasers market?
Who are the leading companies in the Construction Lasers market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Range
- 1.2.1 1 ft. to 100 ft.
- 1.2.2 101 ft. to 200 ft.
- 1.2.3 201 ft. to Above
- 1.3 By Product
- 1.3.1 Rotary Level Laser
- 1.3.2 Line Laser Levels
- 1.3.3 Plumb/Dot Laser
- 1.4 By Operation
- 1.4.1 Manual-Leveling Lasers
- 1.4.2 Self-Leveling and Automatic-Leveling Lasers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 174 million → 2032: USD 371.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Construction Lasers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Construction Lasers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Construction Lasers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Construction Lasers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Construction Lasers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Construction Lasers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Construction Lasers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Construction Lasers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 174 million → 2032: USD 371.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Construction Lasers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Range - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 1 ft. to 100 ft.
- 12.3.7.2 101 ft. to 200 ft.
- 12.3.7.3 201 ft. to Above
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rotary Level Laser
- 12.4.7.2 Line Laser Levels
- 12.4.7.3 Plumb/Dot Laser
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Manual-Leveling Lasers
- 12.5.7.2 Self-Leveling and Automatic-Leveling Lasers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Construction Lasers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Construction Lasers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Construction Lasers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Spectra Precision
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Trimble
- 17.4 Hilti
- 17.5 Topcon
- 17.6 Stanley Black & Decker, Inc.
- 17.7 Leica Geosystems AG
- 17.8 Makita
- 17.9 STABILA
- 17.10 Pacific Laser Systems
- 17.11 Kapro Industries Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

