
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Credit Risk Assessment Market Size 2024 | USD 8,305.94 million |
| Credit Risk Assessment Market, CAGR | 13.78% |
| Credit Risk Assessment Market Size 2032 | USD 23,330.08 million |
Market Overview
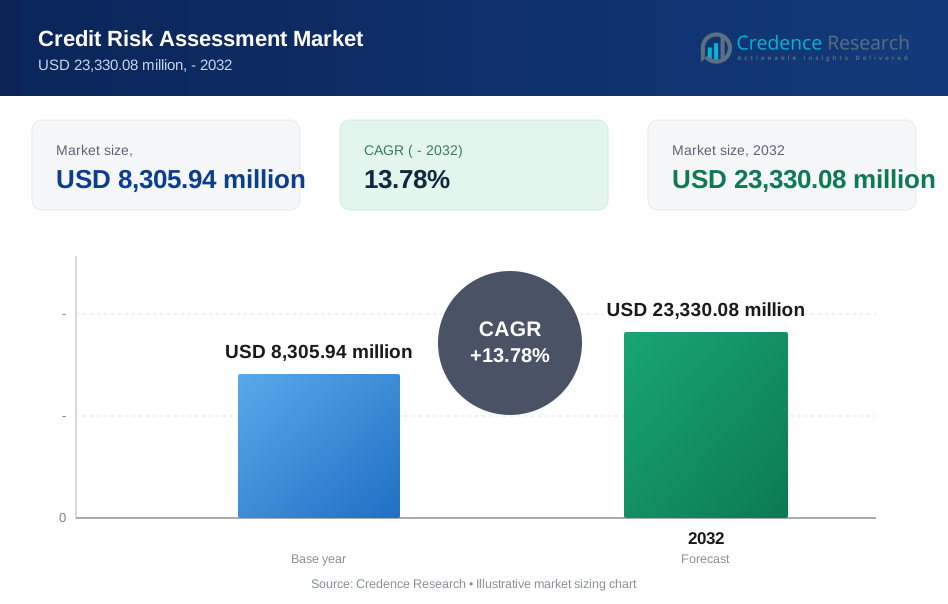
The Global Crtedit Risk Assessment Marke is projected to grow from USD 8,305.94 million in 2024 to an estimated USD 23,330.08 million Based on 2032, with a compound annual growth rate (CAGR) 13.78% from 2025 to 2032. The market expansion reflects rising demand for automated credit scoring, regulatory compliance, and AI-driven risk analytics.
Key drivers include the proliferation of alternative data sources, regulatory mandates for comprehensive risk reporting, and a surge indigital lending platforms. Financial institutions embrace AI-powered analytics to detect credit anomalies faster and reduce default exposure. Cloud-based deployment models lower entry barriers and support scalable risk assessment. Adoption of predictive modeling and scenario analysis drove innovation and shaped emerging trends. Integration of blockchain for transparent credit histories and deployable APIs improved interoperability and drove broader adoption across tier-2 and tier-3 financial institutions.
North America holds the largest share thanks to stringent regulatory frameworks and early adoption of AI technologies. Europe follows with significant investments in digital banking initiatives. Asia Pacific demonstrates the fastest growth rate due to expanding fintech ecosystems and rising consumer credit usage. Latin America exhibits growing demand as financial inclusion initiatives expand credit access. Key players include FICO, Experian, Equifax, Moody’s, and SAS Institute, which compete on product innovation and service integration.
Market Insights
- The Global Credit Risk Assessment Market will expand from USD 8,305.94 million in 2024 to USD 23,330.08 million by 2032 at a 13.78 % CAGR.
- It leverages AI-driven analytics, cloud platforms, and API-centric architectures to enhance risk scoring accuracy.
- Heightened mandates like Basel III and IFRS 9 push institutions to deploy automated reporting and compliance workflows.
- It supports fintech and neobank growth by enabling instant credit decisions and scalable loan origination.
- Firms face high costs and delays when they align modern risk engines with legacy core banking systems.
- It leads revenue share through strict regulatory frameworks and early AI adoption in banking and financial services.
- It records the fastest CAGR thanks to expanding fintech ecosystems, alternative data use, and rising consumer credit demand.
Report Scope
This report segments the Global Credit Risk Assessment Market as follows:
Market Drivers
Stringent Regulatory Compliance and Reporting Standards Elevate Demand
Financial regulators worldwide enforce rigorous credit risk guidelines that compel institutions to enhance transparency and fortify risk management frameworks. The Global Credit Risk Assessment Market benefits when banks upgrade reporting systems to meet Basel III, IFRS 9, and other mandates. It promotes investment in solutions that automate data collection, validation, and audit trails. Institutions gain confidence by reducing manual errors and ensuring regulatory alignment. Vendors respond by offering configurable workflows that adapt to evolving policies. Clients report shorter compliance cycles and improved audit readiness. This regulatory pressure sustains steady demand for advanced assessment tools.
- For instance, financial institutions in India have accelerated adoption of automated compliance monitoring systems following RBI’s February-2024 mandate on compliance automation.
Adoption of Alternative Data Sources Enhances Credit Insights
Lenders expand data inputs beyond traditional financial statements to refine credit scoring accuracy. The Global Credit Risk Assessment Market registers growth when firms integrate social media indicators, utility payments, and transaction histories. It drives deployments of platforms that correlate disparate data streams. Analysts uncover borrower behavior patterns that standard models overlook. Providers optimize APIs that ingest real-time feeds and apply rule-based filters. Clients report higher approval rates for underbanked segments. This adoption widens risk visibility and reduces default rates.
- For instance, lenders in India have integrated behavioral metrics from digital transactions to refine credit scoring models, improving loan approval rates for underbanked segments.
AI and Machine Learning Integration Accelerates Risk Detection Precision
Machine learning algorithms empower institutions to detect subtle credit anomalies and emerging risk clusters. The Global Credit Risk Assessment Market expands when providers incorporate neural networks and ensemble models. It drives development of predictive modules that score potential defaulters with high accuracy. Risk managers leverage scenario analysis tools that stress test portfolios under varied economic conditions. Providers deliver dashboards that visualize risk exposures and trend shifts. Clients reduce non-performing assets through early warnings. This innovation cements AI’s role in modern risk frameworks.
Expansion of Digital Lending Platforms Broadens Market Opportunities
Digital lenders require robust risk assessment engines to support instant credit decisions at scale. The Global Credit Risk Assessment Market grows when fintech companies integrate cloud-native platforms. It expedites loan origination workflows and minimizes manual intervention. Platforms employ decision-ing rules engines that balance speed with prudential controls. Lenders launch mobile apps that offer personalized credit offers within minutes. Providers supply SDKs and microservices that simplify integration. This synergy between fintech and risk assessment solutions fuels rapid market expansion.
Market Trends
Proliferation of Real-Time Analytics and Continuous Monitoring
Institutions deploy analytics engines that analyze credit performance in real time. The Global Credit Risk Assessment Market benefits when providers offer continuous monitoring modules that flag risk escalations instantly. It alerts risk managers to credit score changes and portfolio drifts. Vendors integrate streaming APIs that ingest transactional data from multiple channels. Clients refine risk strategies with detailed trend reports and heat-map visualizations. Firms achieve faster decision loops and reduce blind spots. That capability drives preference for platforms with real-time dashboards and alert frameworks.
- For instance, a study on real-time data processing in credit risk assessment found that integrating streaming frameworks improved model accuracy and responsiveness, with financial institutions processing over 1.8 billion transactional records daily.
Shift Toward Embedded Risk Assessment in Core Banking Systems
Banks incorporate risk assessment models directly into loan origination portals and customer interfaces. The Global Credit Risk Assessment Market grows when institutions embed risk engines within mobile and web applications. It streamlines workflows by eliminating data handoffs and manual validations. Providers develop microservices that deliver credit scores via simple API calls. Financial product teams adjust credit criteria dynamically based on user profiles. Deployment speed improves with containerized software and modular architecture. This integration trend boosts collaboration between IT and risk functions.
- For instance, embedded banking solutions are projected to generate over 25 billion in annual revenue for banks by 2026, with more than 50 financial institutions actively integrating risk assessment models into their platforms.
Market Challenges
Complex Regulatory Hurdles and Legacy System Integration Complexity
The Global Credit Risk Assessment Market faces intense scrutiny under evolving data protection laws and cross-border data transfer regulations. It places pressure on vendors to adopt robust encryption and audit capabilities. Institutions struggle to align custom risk models with legacy core banking platforms. It raises implementation time and increases project cost. Organizations report gaps in data completeness and standardization across multiple sources. That situation limits accuracy of scoring algorithms and heightens operational risk.
- For instance, over 1,200 financial institutions worldwide have reported challenges in aligning risk models with legacy banking platforms, leading to an average implementation delay of 14 months
Adoption Resistance and Model Explainability Constraints Hinder Progress
Enterprises exhibit caution when they evaluate AI-driven risk engines for lack of transparent decision logic. The Global Credit Risk Assessment Market must address stakeholder demands for interpretability and audit trails. It challenges providers to deliver clear model governance frameworks. Risk teams resist changes when they cannot trace outcome drivers. That barrier slows deployment of advanced predictive analytics. It compels solution architects to balance performance with explainability requirements.
Market Opportunities
Untapped Demand in Emerging Digital Lending Channels
Fintech firms and neobanks in emerging economies expand credit services to underserved populations. The Global Credit Risk Assessment Market gains traction when it supplies robust risk tools to these digital lenders. It supports microloan origination and peer-to-peer lending platforms with automated credit evaluation. Vendors adapt solutions for mobile-first user experiences and API-driven workflows. Clients benefit from reduced default rates and improved portfolio diversification. Partnerships between risk providers and non-bank financial institutions drive further penetration. This synergy unlocks new revenue streams for both vendors and lenders.
Growth Potential through Integration of Alternative Data and Advanced Analytics
Financial institutions seek broader data sets that use utility payments, social signals and behavioral metrics. The Global Credit Risk Assessment Market expands when it incorporates these diverse inputs into credit scoring models. It increases approval accuracy for thin-file clients and reduces bias in automated decisions. Providers offer customizable analytics modules that fit unique regional requirements. Continuous model refinement via machine learning enhances predictive precision. Collaboration between data aggregators and risk vendors accelerates solution development. This trend drives demand for scalable platforms with modular architectures.
Market Segmentation Analysis
By Product
The Global Credit Risk Assessment Market splits into Software Solutions, Risk Models, and Credit Scoring Systems. It offers configurable platforms that centralize data, enable scenario simulation, and deliver automated scorecards. Vendors tailor modules to address institution-specific risk appetites and support rapid deployment. Clients gain consistency in risk evaluation and streamline decision workflows.
By Services
The Global Credit Risk Assessment Market comprises Consulting, Implementation, Training and Support, and Managed Services. It guides organizations through solution selection, system integration, and user onboarding. Firms leverage expert consultants to map regulatory requirements and optimize tool configuration. Training programs enhance analyst proficiency, and managed services provide continuous maintenance and updates.
Segments
Based on Product
- Software Solutions
- Risk Models
- Credit Scoring Systems
Based on Services
- Consulting
- Implementation
- Training and Support
- Managed Services
Based on End User
- Banks
- Credit Unions
- Non-Banking Financial Institutions
- Government Agencies
- Others
Based on Application
- Banking and Financial Services
- Insurance
- Retail
- Telecommunications
- Automotive
- Healthcare
- Others
Based on Technology
- Artificial Intelligence
- Machine Learning
- Blockchain
- Big Data Analytics
- Cloud Computing
Based on Solutions
- Fraud Detection
- Risk Compliance
- Portfolio Management
- Predictive Analytics
Based on Component
- Data Management
- Risk Analytics
- Reporting and Visualization
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Dominant North American Market Driven by Regulatory Rigor and Technological Leadership
North America commands largest revenue share thanks to strict regulations and mature financial infrastructure. The Global Credit Risk Assessment Market benefits when institutions integrate advanced analytics and machine learning into credit workflows. It uses data repositories from credit bureaus and financial exchanges to support accurate risk scoring. Vendors provide tailored dashboards and API connectors that align with US and Canadian reporting standards. Banks reduce default exposure through stress tests on multiple scenarios and deploy automated decision modules. Clients report improved audit readiness and faster model validation cycles. That environment sustains innovation and leads to continuous platform enhancement.
European Market Embraces Digital Banking Initiatives and Harmonized Regulations
Europe exhibits steady growth driven by unified frameworks and strong digital banking programs. The Global Credit Risk Assessment Market expands when companies adopt IFRS 9 and GDPR-compliant solutions. It taps into centralized credit registries and regional data consortia for more transparent risk assessments. Vendors release modular architectures that support multi-language interfaces and local reporting formats. Financial institutions adjust risk models to reflect economic fluctuations in the Eurozone and the UK. Clients gain streamlined cross-border credit evaluations and standardized audit trails. That approach fosters collaboration between regulators and technology providers.
Asia Pacific Records Fastest Growth Fueled by Fintech Expansion and Data Innovation
Asia Pacific displays fastest CAGR thanks to rising fintech adoption and expanding consumer credit markets. The Global Credit Risk Assessment Market grows when it incorporates alternative data sources popular in the region. It integrates telecommunication records, online payment histories, and utility bill data to score thin-file customers. Providers optimize cloud-native platforms that enable quick deployment across emerging economies. Lenders improve portfolio performance with real-time risk alerts and mobile decision engines. Clients experience wider financial inclusion and reduced underwriting friction. That trend drives local partnerships and customized product offerings.
Key players
- Experian
- Equifax
- Trans Union
- Moody’s Analytics
- FICO
- Credit Metrics
- Risk Insights
Competitive Analysis
The Global Credit Risk Assessment Market features intense rivalry among established data bureaus and specialized analytics firms. Experian, Equifax, and Trans Union leverage extensive consumer databases and global reach to deliver comprehensive credit insights. Moody’s Analytics and FICO differentiate through sophisticated predictive models and regulatory compliance expertise. Credit Metrics focuses on bespoke risk frameworks for niche lending segments, while Risk Insights competes on agile deployment and cloud-native solutions. It challenges larger vendors by offering rapid integration and competitive pricing. Leading providers invest heavily in AI and alternative data partnerships to refine scoring precision and expand addressable markets. They pursue strategic alliances with fintech platforms and core banking vendors to embed risk engines directly into client workflows. Continuous product enhancements and geographic expansion fuel market share battles, compelling firms to tailor offerings for regional requirements and vertical-specific use cases. This dynamic landscape rewards organizations that combine data depth, algorithmic innovation, and seamless implementation.
Market Concentration and Characteristics
The Global Credit Risk Assessment Market exhibits moderate concentration, with top-tier firms controlling a significant share while specialized vendors occupy niche segments. It features a dual structure where global bureaus supply extensive credit data and analytics giants deliver advanced modeling capabilities. Regional players tailor solutions to local regulatory and cultural requirements, which sustains diversification. The market embraces modular architectures, API-driven integrations, and cloud deployments that support rapid scalability. Strong barriers to entry stem from data acquisition costs, regulatory compliance demands, and the need for robust security frameworks. Clients value depth of data, model transparency, and seamless system integration when selecting providers.
Report Coverage
The research report offers an in-depth analysis based on Product, Services, End User, Application, Technology, Solutions, Component and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Global Credit Risk Assessment Market will integrate more real-time data feeds to enable instantaneous credit decisioning. It will empower lenders to adjust credit limits dynamically based on live portfolio risk metrics.
- Global Credit Risk Assessment Market will adopt advanced AI models that explain decision drivers for greater transparency. It will help risk teams validate scoring outputs and satisfy audit mandates without manual analysis.
- Global Credit Risk Assessment Market will expand use of alternative data, including social and behavioral signals, to score thin-file customers. It will broaden credit access in underbanked regions and support financial inclusion initiatives.
- Global Credit Risk Assessment Market will embed risk engines within customer-facing applications to streamline loan origination. It will reduce manual handoffs and speed up approval cycles for retail and SME lending.
- Global Credit Risk Assessment Market will leverage blockchain to secure credit histories and prevent data tampering. It will provide immutable audit trails that strengthen trust among stakeholders and regulators.
- Global Credit Risk Assessment Market will shift toward modular cloud-native architectures to support rapid scaling. It will allow institutions to deploy new risk modules without overhauling core systems.
- Global Credit Risk Assessment Market will integrate stress-testing and scenario analysis tools into standard workflows. It will enable risk managers to simulate economic shocks and calibrate capital reserves proactively.
- Global Credit Risk Assessment Market will offer managed services that handle end-to-end model maintenance and updates. It will relieve in-house teams from technical upkeep and ensure continuous compliance.
- Global Credit Risk Assessment Market will adopt collaborative data consortia models for peer benchmarking. It will give institutions deeper insight into relative portfolio performance and emerging risk clusters.
- Global Credit Risk Assessment Market will prioritize explainable AI frameworks that balance performance with clarity. It will foster broader stakeholder buy-in and accelerate adoption across conservative financial organizations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Compliance and Reporting Standards
Global enforcement of credit risk regulations such as Basel III and IFRS 9 compels financial institutions to upgrade risk management frameworks, driving demand for automated and auditable credit risk assessment solutions.
Adoption of Alternative Data Sources
Lenders are increasingly integrating non-traditional data such as utility payments, social media activity, and transaction histories to improve credit scoring accuracy, expanding the market’s reach to underbanked and thin-file customers.
AI and Machine Learning Integration
The deployment of AI and machine learning enables faster, more precise detection of credit anomalies and emerging risk clusters, encouraging financial institutions to invest in advanced analytics platforms.
Expansion of Digital Lending Platforms
The rapid growth of fintech and digital lending requires robust, scalable risk assessment engines to support instant credit decisions and automated loan origination, fueling market expansion.
Cloud-Based and API-Centric Deployments
Cloud-native architectures and API-driven integrations lower entry barriers and enable rapid, scalable deployment of credit risk solutions, making them accessible to a broader range of financial institutions including tier-2 and tier-3 banks.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size in 2023, and what are the projections for 2032 and CAGR?
What major drivers propel the Global Credit Risk Assessment Market?
Which region is expected to see the fastest growth?
What challenges does the Credit Risk Assessment Market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Software Solutions
- 1.2.2 Risk Models
- 1.2.3 Credit Scoring Systems
- 1.3 By End User
- 1.3.1 Banks
- 1.3.2 Credit Unions
- 1.3.3 Non-Banking Financial Institutions
- 1.3.4 Government Agencies
- 1.3.5 Others
- 1.4 By Technology
- 1.4.1 Artificial Intelligence
- 1.4.2 Machine Learning
- 1.4.3 Blockchain
- 1.4.4 Big Data Analytics
- 1.4.5 Cloud Computing
- 1.5 By Application
- 1.5.1 Banking and Financial Services
- 1.5.2 Insurance
- 1.5.3 Retail
- 1.5.4 Telecommunications
- 1.5.5 Automotive
- 1.5.6 Healthcare
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,305.94 million → 2032: USD 23,330.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Credit Risk Assessment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Credit Risk Assessment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Credit Risk Assessment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Credit Risk Assessment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Credit Risk Assessment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Credit Risk Assessment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Credit Risk Assessment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Credit Risk Assessment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,305.94 million → 2032: USD 23,330.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Credit Risk Assessment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software Solutions
- 12.3.7.2 Risk Models
- 12.3.7.3 Credit Scoring Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Banks
- 12.4.7.2 Credit Unions
- 12.4.7.3 Non-Banking Financial Institutions
- 12.4.7.4 Government Agencies
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Artificial Intelligence
- 12.5.7.2 Machine Learning
- 12.5.7.3 Blockchain
- 12.5.7.4 Big Data Analytics
- 12.5.7.5 Cloud Computing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Banking and Financial Services
- 12.6.7.2 Insurance
- 12.6.7.3 Retail
- 12.6.7.4 Telecommunications
- 12.6.7.5 Automotive
- 12.6.7.6 Healthcare
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Credit Risk Assessment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Credit Risk Assessment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Credit Risk Assessment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Credit Risk Assessment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Experian
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Equifax
- 18.4 TransUnion
- 18.5 Moody’s Analytics
- 18.6 FICO
- 18.7 SAS Institute
- 18.8 Credit Metrics
- 18.9 Risk Insights
- 18.10 Oracle
- 18.11 IBM
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

