
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Center Physical Security Market Size 2024 | USD 2209 Million |
| Data Center Physical Security Market, CAGR | 13.22% |
| Data Center Physical Security Market Size 2032 | USD 5964.59 Million |
Market Overview:
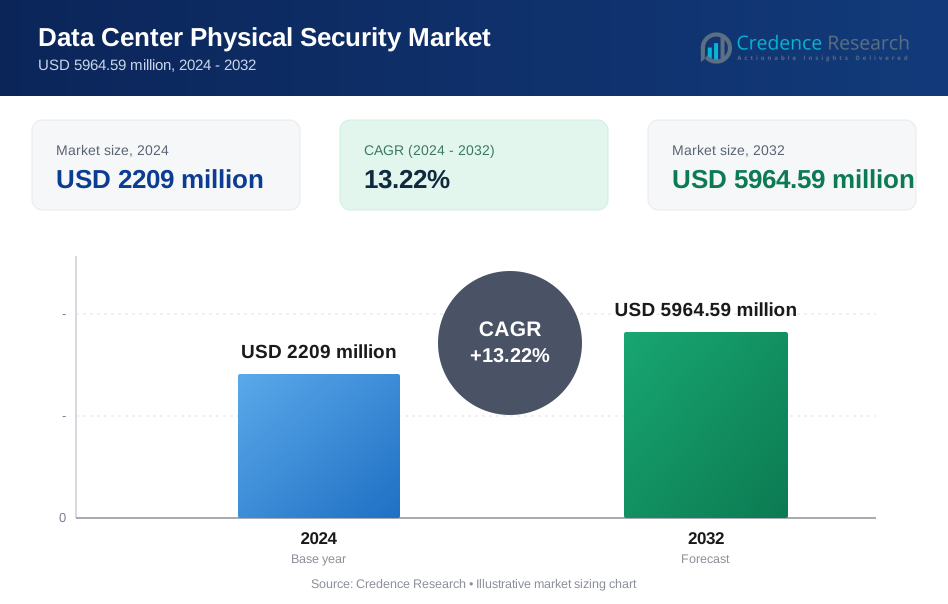
The Data Center Physical Security Market is projected to grow from USD 2209 million in 2024 to USD 5964.59 million by 2032, with a compound annual growth rate (CAGR) of 13.22%.
The growth of the Data Center Physical Security Market is driven by the increasing demand for secure data storage and management, as enterprises and government organizations increasingly rely on data centers to handle sensitive information. Rising concerns over cyber threats, data breaches, and physical security breaches have fueled the adoption of advanced security solutions. Additionally, the growing number of hyperscale data centers and the rapid expansion of cloud-based services require enhanced physical security measures. Trends such as the integration of artificial intelligence, biometrics, and access control systems, as well as the implementation of video surveillance, are shaping the market. The increased regulatory requirements for data privacy and compliance also contribute to the rising demand for physical security solutions in data centers. Furthermore, as companies focus on sustainability, energy-efficient security solutions are becoming more popular, providing additional momentum for market growth.
The Data Center Physical Security Market is geographically diverse, with North America holding the largest share, driven by its high concentration of data centers and advanced security technologies. Europe, particularly the UK, Germany, and France, follows closely due to strict regulatory standards like GDPR. The Asia-Pacific region, led by China, India, and Japan, is experiencing rapid growth with increasing data center investments and government initiatives for data security. Latin America and the Middle East & Africa are also expanding, with countries like Brazil, Mexico, and the UAE showing rising demand for secure data infrastructure. Key players like Honeywell International Inc., Bosch Sicherheitssysteme GmbH, Cisco Systems, Inc., and Hangzhou Hikvision Digital Technology Co., Ltd. are driving the market by offering advanced physical security solutions globally.
Market Insights:
- The Data Center Physical Security Market is projected to grow from USD 2209 million in 2024 to USD 5964.59 million by 2032, with a CAGR of 13.22%.
- Rising cyber threats, data breaches, and physical security concerns are driving the market's growth as organizations invest in advanced security solutions to protect sensitive data.
- The expansion of hyperscale data centers and cloud-based services demands enhanced physical security measures, contributing to market expansion.
- Integration of AI, biometrics, and access control systems, alongside video surveillance, is shaping market trends, enhancing the efficiency of security solutions.
- Increasing regulatory requirements for data privacy and compliance, such as GDPR and HIPAA, are boosting the demand for secure data center operations.
- The push for energy-efficient and sustainable security solutions is gaining traction as organizations focus on reducing their carbon footprint.
- Key regions, including North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, are witnessing varying degrees of market growth, with North America holding the largest share.
Market Drivers:
Growing Data Breaches and Cybersecurity Threats:
The increasing frequency of data breaches and cybersecurity threats is a primary driver of the Data Center Physical Security Market. As organizations manage and store critical and sensitive data in data centers, the need for enhanced physical security measures to prevent unauthorized access has become paramount. For instance, companies like Fortinet and Cisco are developing cutting-edge intrusion prevention systems to secure data centers from cyberattacks targeting physical infrastructure. The rise of such cyberattacks underscores the importance of safeguarding the data center environment, prompting companies to invest in robust physical security solutions.
Expansion of Hyperscale Data Centers:
The rapid growth of hyperscale data centers, driven by cloud computing, big data, and IoT applications, has significantly fueled the demand for advanced physical security systems. As hyperscale data centers house vast amounts of data, the potential risks associated with physical threats increase. For instance, Amazon Web Services (AWS) incorporates multi-layered security systems, including biometric access control and advanced surveillance technologies, to protect its large-scale data centers. Companies operating such data centers are adopting comprehensive security measures to mitigate potential breaches and ensure the safety of critical assets.
Regulatory Compliance and Data Privacy Requirements:
Strict regulations and data privacy laws imposed by governments and regulatory bodies have heightened the need for secure data center operations. Compliance with regulations such as GDPR and HIPAA requires organizations to implement stringent security protocols to safeguard data from physical threats. For instance, Equinix, a global data center leader, ensures compliance by deploying state-of-the-art security solutions that align with international standards. The growing emphasis on regulatory compliance is driving investments in physical security solutions, as failure to meet these standards can result in severe penalties and damage to a company's reputation.
Integration of Advanced Security Technologies:
The integration of advanced technologies such as artificial intelligence, biometrics, and machine learning into physical security systems is further driving the market's growth. AI-driven surveillance, facial recognition, and automated access control systems are improving the overall efficiency and effectiveness of data center security. For instance, Microsoft Azure employs AI-powered monitoring tools to detect and respond to potential threats in real-time. These technologies help organizations identify risks swiftly, reducing the likelihood of breaches and enhancing the overall security posture of data centers.
Market Trends:
Adoption of AI-Driven Security Solutions:
One of the key trends in the Data Center Physical Security Market is the increasing use of artificial intelligence (AI) to enhance security operations. AI-driven technologies, such as video analytics and automated monitoring systems, help in identifying and responding to potential security threats in real time. These systems analyze vast amounts of data from surveillance cameras, sensors, and access control systems, enabling data centers to detect unusual activity and prevent breaches more efficiently. For instance, IBM provides AI-powered security solutions, such as automated threat detection and video analytics tools, that help streamline security processes while reducing operational costs. AI-powered systems also reduce the need for human intervention, optimizing security operations and lowering costs.
Growing Use of Biometric Authentication:
Biometric authentication is gaining traction in data center physical security as a reliable and secure access control solution. Traditional methods like keycards and passwords are increasingly being replaced by biometric technologies, such as fingerprint scanning, facial recognition, and retina scans, which provide enhanced security by ensuring only authorized personnel can access sensitive areas. For instance, Hikvision offers advanced biometric access control systems that combine facial recognition and fingerprint technology for robust security. The shift toward biometric systems reflects the growing need for advanced solutions that minimize the risk of unauthorized access to data center facilities.
Integration of Cloud-Based Security Solutions:
Cloud-based physical security solutions are becoming more prevalent as organizations seek scalable and cost-effective methods to protect their data centers. These solutions allow for centralized monitoring, real-time data sharing, and seamless integration across multiple sites. For instance, Honeywell provides cloud-based security solutions that enable centralized management of surveillance systems across global data center locations. Cloud-based platforms also offer flexibility in managing security operations remotely, which has become particularly important as companies expand globally and require consistent security measures across different locations.
Emphasis on Energy-Efficient Security Systems:
Sustainability is an emerging trend in the Data Center Physical Security Market, with a growing focus on energy-efficient security systems. As data centers strive to reduce their carbon footprint, they are adopting energy-efficient lighting, surveillance cameras, and access control systems that consume less power without compromising security. For instance, Axis Communications has introduced energy-efficient surveillance cameras that use low power consumption technology, aligning with the industry’s push for greener solutions. This trend aligns with the broader industry push toward green data center operations.
Market Challenges Analysis:
High Initial Costs and Maintenance Expenses:
A key challenge in the Data Center Physical Security Market is the substantial initial investment required for advanced security systems. Deploying comprehensive solutions like biometric access control, AI-driven surveillance, and integrated monitoring systems demands significant capital expenditure on hardware, software, and infrastructure upgrades. For smaller data centers or organizations with limited budgets, the high upfront costs can be a major financial barrier, deterring them from adopting the necessary security measures. Furthermore, these systems require continuous maintenance, including regular updates to stay ahead of evolving security threats, repairs of malfunctioning equipment, and the need for ongoing monitoring. This leads to increased operational costs, contributing to the total cost of ownership. The need for highly skilled personnel to manage, monitor, and maintain these systems adds another layer of expense. As a result, organizations often delay investing in critical physical security upgrades, leaving themselves vulnerable to security breaches, data theft, and unauthorized access, which can ultimately lead to significant financial and reputational damage.
Complex Integration with Existing Infrastructure:
Another significant challenge in the market is the complexity of integrating modern security solutions with existing data center infrastructure. Many organizations operate legacy systems that are outdated or incompatible with the latest security technologies, such as AI-enhanced surveillance and biometric authentication systems. Integrating these new solutions into an already established infrastructure can be technically complex, requiring careful planning and expertise. This process often demands significant time and financial resources, as it involves not only upgrading systems but also ensuring that they work seamlessly together to provide a cohesive security framework. Downtime during the integration process can be a major concern, potentially disrupting data center operations and affecting business continuity. The fear of operational disruptions and the complexity of aligning old and new technologies make some organizations reluctant to adopt modern physical security systems, even when they recognize the necessity. Successful integration often requires collaboration between security vendors and data center operators to avoid costly disruptions and ensure smooth operations.
Market Opportunities:
The Data Center Physical Security Market presents substantial opportunities for growth as organizations increasingly prioritize security to protect their critical infrastructure. The rapid expansion of cloud computing, edge computing, and IoT-driven applications has fueled the demand for data centers, resulting in a corresponding need for advanced physical security solutions. As businesses transition to hybrid cloud environments and scale their operations globally, the deployment of secure, centralized data management becomes essential. This trend opens significant opportunities for security providers to offer innovative solutions that integrate physical and cyber security measures, creating a holistic approach to protecting data centers from both external and internal threats.
Furthermore, advancements in technologies such as artificial intelligence, machine learning, and biometrics create new opportunities for enhancing data center security. AI-driven surveillance systems, facial recognition for access control, and predictive analytics for threat detection offer enhanced protection and operational efficiency. The growing emphasis on regulatory compliance and data privacy laws, such as GDPR and HIPAA, is also creating a demand for more sophisticated security solutions that ensure adherence to these standards. Security providers who can offer scalable, cloud-based, and energy-efficient solutions are well-positioned to capitalize on the growing need for sustainable data center security infrastructure. These advancements not only strengthen security but also enhance the overall operational resilience and efficiency of data centers, providing new growth avenues in this dynamic market.
Market Segmentation Analysis:
By Component
The Data Center Physical Security Market can be segmented by component, which includes hardware, software, and services. Hardware components such as surveillance cameras, biometric scanners, and access control systems account for a significant portion of the market. However, demand for security management software and cloud-based solutions is also increasing as data centers seek integrated, automated security systems.
By Security Type
The market is further segmented by security type, including perimeter security, facility monitoring, and access control. Perimeter security, which includes fencing, barriers, and video surveillance, plays a critical role in preventing unauthorized access. Access control, leveraging technologies like biometrics and smart cards, is essential for regulating entry into restricted areas within the data center.
By End User
Data centers across various industries, such as IT and telecommunications, banking and finance, government, and healthcare, are key end-users of physical security solutions. The increasing reliance on cloud services and stringent regulatory requirements in these sectors drive the need for robust physical security measures to safeguard critical infrastructure.
Segments:
Based on Component
- Hardware
- Software
- Services
Based on Security Type
- Video surveillance
- Monitoring solutions
- Access control solutions
- Others
Based on Data Center Type
- Small data center
- Medium data center
- Large data center
Based on End User
- BFSI
- Healthcare
- Retail & E-commerce
- Media & Entertainment
- IT & telecommunication
- Government & defense
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Data Center Physical Security Market, accounting for 35% of the market in 2024. The region's dominance is driven by the high concentration of data centers, particularly in the United States, where major cloud service providers and hyperscale data center operators are based. The rapid adoption of advanced technologies such as AI, machine learning, and biometric systems for security is also a key factor in the region’s market leadership. In addition, strict data privacy regulations and an increasing number of cyberattacks have prompted organizations in North America to invest heavily in comprehensive physical security measures. The presence of well-established security providers and advanced infrastructure further supports the market’s growth in this region.
Europe
Europe is the second-largest market, holding 25% of the global share in 2024. The region's demand for data center physical security is fueled by the stringent regulatory environment, especially with the General Data Protection Regulation (GDPR), which requires organizations to implement robust security measures to protect data. Countries such as the UK, Germany, and France are leading in adopting advanced security technologies for their data centers. Additionally, the rapid digital transformation and growth of cloud services in Europe are driving the need for enhanced physical security solutions. The growing number of data breaches and concerns about data privacy in the region also contribute to increased investments in physical security infrastructure.
Asia-Pacific
The Asia-Pacific region is expected to witness significant growth in the Data Center Physical Security Market, capturing 20% of the market share in 2024. Countries such as China, India, and Japan are experiencing a surge in data center construction due to the growing demand for cloud services, e-commerce, and digital transformation. The increasing need for secure data management, combined with government initiatives to bolster data security regulations, is driving the demand for advanced physical security solutions in this region. As the region continues to develop its data center infrastructure, the adoption of sophisticated security technologies, including biometric access control and AI-powered surveillance systems, is expected to rise.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for 15% of the global Data Center Physical Security Market in 2024. In Latin America, countries like Brazil and Mexico are seeing increased investments in data centers due to the rise in digital services and cloud adoption. The region’s data center expansion is driving the need for more advanced physical security systems. In the Middle East & Africa, the market is also expanding as governments and businesses focus on digital transformation and invest in secure data infrastructure. The growing awareness of data security, along with increasing cyber threats in both regions, is contributing to the rising demand for physical security solutions.
Key Player Analysis:
- Honeywell International Inc.
- Bosch Sicherheitssysteme GmbH
- Axis Communications AB
- Johnson Controls
- Cisco Systems, Inc.
- Siemens AG
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Schneider Electric SE
- Pelco
- ABB
Competitive Analysis:
The Data Center Physical Security Market is highly competitive, with key players such as Honeywell International Inc., Bosch Sicherheitssysteme GmbH, Axis Communications AB, Johnson Controls, Cisco Systems, Inc., Siemens AG, Hangzhou Hikvision Digital Technology Co., Ltd., Schneider Electric SE, Pelco, and ABB leading the market. These companies are actively competing by offering advanced and integrated security solutions, including AI-powered surveillance, biometric access control, and real-time monitoring systems. Their strong research and development capabilities allow them to innovate and introduce cutting-edge technologies that meet the growing demand for enhanced data center security. Additionally, these players have a global presence, which enables them to cater to diverse regional needs and comply with varying regulatory standards. Strategic partnerships, mergers, and acquisitions further intensify competition as companies seek to expand their product portfolios and market reach. For instance, Johnson Controls has recently partnered with global data center operators to deploy biometric access control systems that enhance physical security while complying with strict data privacy laws. As the demand for physical security in data centers continues to grow, these leading firms are well-positioned to capture significant market share.
Recent Developments:
- In June 2024, Honeywell International Inc. completed its acquisition of Carrier Global Corporation's Global Access Solutions business for USD 4.95 billion. This strategic move strengthens Honeywell’s role as a top security solutions provider, unlocking significant opportunities for accelerated innovation in the growing cloud-based services and solutions market.
- In May 2024, ASPEED Technology, a leader in immersive 360-degree imaging products, partnered with its subsidiary Cupola360 Inc., along with Millitronic and Schneider Electric SE, to introduce an industry-first smart panoramic visual remote management solution for data centers. This cutting-edge solution integrates Schneider Electric's data center sensors and gateways with Cupola360's AI-driven visual management platform, immersive panoramic cameras, and Millitronic’s wireless infrastructure integration.
- In June 2024, Honeywell International Inc. finalized its acquisition of Carrier Global Corporation's Global Access Solutions business for USD 4.95 billion. This strategic acquisition enhances Honeywell's status as a premier security solutions provider, creating substantial opportunities for innovation in the rapidly growing cloud-based services and solutions sector.
- In May 2024, ASPEED Technology, in collaboration with its subsidiary Cupola360 Inc., partnered with Millitronic and Schneider Electric SE to launch an industry-first smart panoramic visual remote management solution for data centers. This innovative solution incorporates Schneider Electric's sensors and gateways with Cupola360's AI-powered visual management platform and Millitronic's wireless infrastructure.
Market Concentration & Characteristics:
The Data Center Physical Security Market is moderately concentrated, with several key players dominating the global landscape. Companies such as Honeywell International Inc., Bosch Sicherheitssysteme GmbH, Cisco Systems, Inc., and Axis Communications AB lead the market due to their technological expertise, comprehensive product portfolios, and global presence. These players focus on continuous innovation, offering integrated solutions that combine advanced technologies like AI-driven surveillance, biometric access control, and real-time monitoring to meet the increasing demand for secure data center environments. The market is characterized by rapid technological advancements, driven by the need to protect data centers from both physical and cyber threats. Increasing regulatory requirements and the rising incidence of data breaches are also shaping the market dynamics. While established players dominate, there is room for new entrants with innovative solutions, particularly in emerging regions where data center infrastructure is expanding rapidly. The competitive landscape encourages continuous improvements in security technologies and solutions.
Report Coverage:
The research report offers an in-depth analysis based on Component, Security Type, Data Center Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing data breaches and cyber threats will drive continued investments in physical security solutions for data centers.
- The demand for AI-powered surveillance and biometric access control systems will rise as organizations seek advanced security technologies.
- The expansion of hyperscale and edge data centers will necessitate enhanced physical security measures to protect critical infrastructure.
- Integration of physical and cybersecurity solutions will become a priority for data centers to create a comprehensive security approach.
- Growing regulatory requirements for data privacy will push organizations to adopt more stringent physical security protocols.
- Energy-efficient and sustainable security solutions will gain importance as businesses focus on reducing operational costs and their carbon footprint.
- The Asia-Pacific region is expected to witness significant growth in physical security investments due to increasing data center construction.
- Collaboration between security providers and data center operators will intensify to create tailored, scalable security solutions.
- Cloud-based physical security solutions will become more popular for real-time monitoring and remote management.
- Continuous technological advancements will lead to the development of more sophisticated and integrated security systems for data centers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Data Center Physical Security Market?
What factors are driving the growth of the Data Center Physical Security Market?
What are the key segments within the Data Center Physical Security Market?
What are some challenges faced by the Data Center Physical Security Market?
Who are the major players in the Data Center Physical Security Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Data Center Physical Security Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Data Center Physical Security Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2209 million → 2032: USD 5964.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Data Center Physical Security Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Data Center Physical Security Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Data Center Physical Security Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Data Center Physical Security Market Drivers
- 3.3 Data Center Physical Security Market Restraints & Challenges
- 3.4 Data Center Physical Security Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Data Center Physical Security Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Data Center Physical Security Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Data Center Physical Security category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Data Center Physical Security Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Data Center Physical Security Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Data Center Physical Security market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Data Center Physical Security Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Data Center Physical Security Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Data Center Physical Security Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Data Center Physical Security (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Data Center Physical Security Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Data Center Physical Security Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Data Center Physical Security Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Data Center Physical Security Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Data Center Physical Security Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Data Center Physical Security Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Data Center Physical Security Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Data Center Physical Security Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Data Center Physical Security Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
