
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Data Center Uninterruptable Power Supply (UPS) Market Size 2023 | USD 5210.10 million |
| Data Center Uninterruptable Power Supply (UPS) Market, CAGR | 4.98% |
| Data Center Uninterruptable Power Supply (UPS) Market Size 2032 | USD 8,068.73 million |
Market Overview
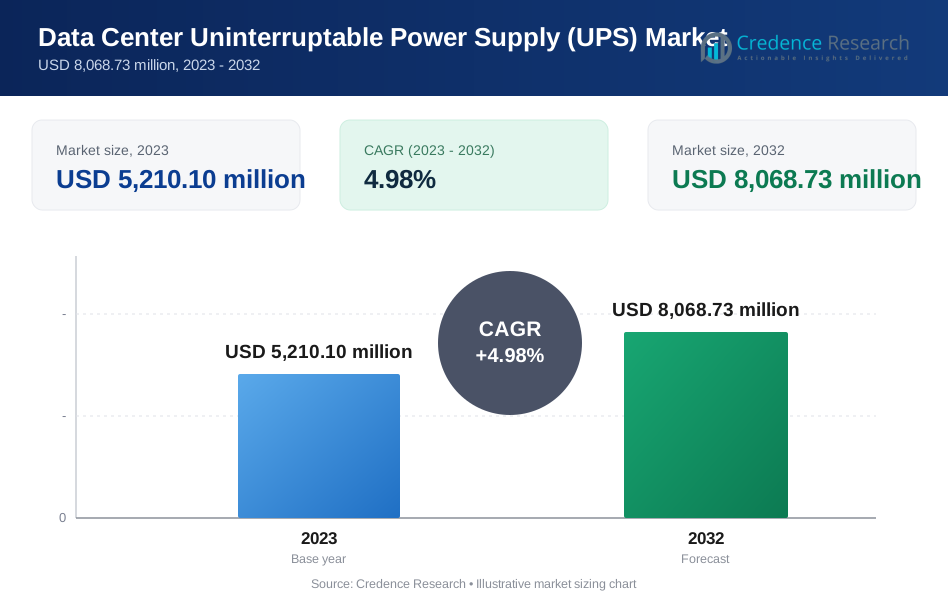
Global Data Center Uninterruptable Power Supply (UPS) market size was valued at USD 5210.10 million in 2023 and is anticipated to reach USD 8,068.73 million by 2032, at a CAGR of 4.98% during the forecast period (2023-2032).
The growth of the Global Data Center Uninterruptible Power Supply (UPS) market is driven by the increasing reliance on data centers for cloud computing, big data, and IoT technologies, which require uninterrupted power to maintain operations. As businesses continue to embrace digital transformation, the demand for reliable and efficient power solutions has surged. Additionally, the need for energy-efficient and eco-friendly UPS systems, driven by growing environmental concerns and regulations, is shaping market trends. Innovations such as modular UPS systems and advancements in lithium-ion batteries are enhancing energy storage, improving efficiency, and reducing maintenance costs. Furthermore, the rise in hyperscale data centers, which demand high-capacity and scalable UPS solutions, is expected to contribute significantly to market expansion. As data centers strive to maintain uptime and mitigate power disruptions, UPS systems have become critical for supporting the growing data load and ensuring smooth, continuous operations.
The Global Data Center Uninterruptible Power Supply (UPS) market is witnessing significant growth across various regions, driven by the increasing demand for reliable power backup solutions in data centers. North America, particularly the U.S., is a dominant market, supported by the presence of major technology companies and hyperscale data centers. The Asia-Pacific region, led by countries like China and India, is also experiencing rapid growth due to the expansion of cloud services and digital infrastructure. Europe is focusing on energy-efficient and sustainable UPS systems, driven by strict environmental regulations. In the Middle East and Africa, emerging markets are investing heavily in data center infrastructure, creating growth opportunities for UPS providers. Key players in the market include Eaton, Schneider Electric, Vertiv Group Corp., Huawei Technologies, and Emerson, which are leading the way with their advanced, scalable, and energy-efficient UPS solutions designed to meet the evolving needs of global data centers.
Market Insights
- The Global Data Center Uninterruptible Power Supply (UPS) market was valued at USD 5,210.10 million in 2023 and is projected to reach USD 8,068.73 million by 2032, growing at a CAGR of 4.98% from 2023 to 2032.
- The increasing demand for data storage and uninterrupted power in data centers is driving market growth.
- The shift toward energy-efficient, modular, and sustainable UPS solutions is a significant trend.
- Growing digitalization and cloud adoption are fueling the demand for high-capacity UPS systems in data centers.
- The market faces challenges like high initial investment costs and ongoing maintenance requirements for UPS systems.
- North America leads the market, followed by the Asia-Pacific region, which is experiencing rapid growth in data center infrastructure.
- Key players in the market include Eaton, Schneider Electric, Vertiv, Huawei Technologies, and Emerson, who are focusing on product innovation and expanding their market presence.
Market Drivers
Growing Demand for Cloud Computing and Data Storage
The increasing adoption of cloud computing, big data analytics, and IoT technologies is one of the primary drivers for the Global Data Center Uninterruptible Power Supply (UPS) market. For instance, the rapid growth in cloud services and IoT applications has significantly increased the need for robust and reliable data storage solutions. Data centers, which are essential for housing vast amounts of digital information, must operate with minimal interruptions. UPS systems ensure that data centers can maintain continuous operations, safeguarding critical data and services from power disruptions.
Technological Advancements in Energy Efficiency
Technological innovations in UPS systems, particularly in energy efficiency and eco-friendly solutions, are boosting market growth. For instance, the introduction of lithium-ion batteries, which offer longer life cycles and greater energy efficiency than traditional lead-acid batteries, is transforming the UPS market. These advanced UPS systems reduce operational costs, lower carbon footprints, and offer better performance in data centers with high power demands. As sustainability becomes a priority for businesses and governments, energy-efficient UPS solutions are becoming increasingly desirable.
Expansion of Hyperscale Data Centers
The rise of hyperscale data centers, which require large-scale infrastructure to handle enormous data volumes, is another key market driver. These data centers are increasingly relying on high-capacity and scalable UPS systems to meet growing power demands. The efficient operation of hyperscale facilities requires advanced power backup solutions capable of supporting a large number of servers and other critical equipment. As the need for large-scale storage and processing power continues to rise, so does the demand for sophisticated UPS systems to ensure uptime and prevent service interruptions.
Rising Importance of Business Continuity and Disaster Recovery
As organizations become more reliant on digital systems, business continuity and disaster recovery have taken center stage. Uninterrupted power is crucial for maintaining operations, particularly in mission-critical environments like data centers. UPS systems help mitigate the risk of downtime caused by power failures, ensuring that data processing, cloud services, and online platforms remain operational. The growing emphasis on protecting digital infrastructure from disruptions is fueling the demand for reliable UPS systems across the global data center industry.
Market Trends
Shift Towards Lithium-Ion UPS Systems
One of the significant trends in the Global Data Center Uninterruptible Power Supply (UPS) market is the increasing adoption of lithium-ion battery-based UPS systems. For instance, these systems offer several advantages over traditional lead-acid batteries, including longer life cycles, higher energy density, and faster charging times. Lithium-ion UPS solutions are also more compact and lightweight, making them ideal for data centers with space and power constraints. As businesses prioritize operational efficiency and sustainability, the demand for lithium-ion UPS systems is expected to continue growing, driving innovation in the industry.
Growing Integration of Modular UPS Systems
Modular UPS systems are becoming increasingly popular in the data center sector due to their scalability and flexibility. These systems allow operators to add or remove power modules as needed, providing a cost-effective solution to meet changing power requirements. Modular UPS units also offer improved redundancy, ensuring higher reliability and uptime. As data centers expand and require more adaptable solutions to cope with fluctuating workloads, modular UPS systems are expected to be a key trend in the market, enabling greater customization and operational efficiency.
Increasing Focus on Energy Efficiency and Sustainability
Energy efficiency and sustainability are becoming major priorities in the data center industry, and this is influencing UPS system design and deployment. Data centers consume significant amounts of energy, and reducing their carbon footprint is crucial for businesses seeking to align with environmental goals and regulatory standards. UPS manufacturers are innovating to create energy-efficient solutions that not only provide reliable backup power but also minimize energy consumption. The trend toward sustainable practices, including the use of renewable energy sources and efficient power backup systems, is expected to shape the future of the UPS market.
Advancements in Remote Monitoring and Predictive Maintenance
Another emerging trend in the UPS market is the integration of remote monitoring and predictive maintenance capabilities. These advancements enable data center operators to monitor UPS systems in real time, identifying potential issues before they result in downtime or failures. Predictive analytics and IoT-based monitoring tools allow for proactive maintenance, reducing the need for costly repairs and enhancing the lifespan of UPS units. As data centers increasingly seek ways to optimize their operations and reduce operational risks, the adoption of smart UPS systems with advanced monitoring features is expected to rise.
Market Challenges Analysis
High Initial Capital and Maintenance Costs
A significant challenge in the Global Data Center Uninterruptible Power Supply (UPS) market is the high initial capital investment and ongoing maintenance costs. For instance, UPS systems, particularly those with advanced technologies like lithium-ion batteries or modular configurations, can be expensive to install. For large-scale data centers, the total cost of purchasing and maintaining UPS systems can be substantial. Additionally, maintenance and operational costs, including battery replacements, monitoring, and system servicing, can add up over time, further straining budgets. The high upfront investment, coupled with the need for periodic maintenance, presents a barrier for smaller organizations or those with limited capital, potentially hindering market growth.
Space and Cooling Requirements for UPS Systems
Another challenge faced by data centers in adopting UPS systems is the considerable space and cooling requirements. Traditional lead-acid battery UPS systems are large and require significant space within the data center, potentially taking up valuable floor area needed for servers and other critical infrastructure. Even newer, more compact lithium-ion battery systems still require careful consideration of available space and cooling solutions. UPS systems generate heat during operation, necessitating efficient cooling to prevent overheating and ensure optimal performance. Data centers in densely populated areas or with limited physical space may find it difficult to meet these requirements without extensive modifications to their infrastructure, making it a challenge for widespread adoption.
Market Opportunities
Growth in Hyperscale Data Centers
One of the key market opportunities for the Global Data Center Uninterruptible Power Supply (UPS) market lies in the rapid expansion of hyperscale data centers. As the demand for cloud services, big data processing, and edge computing continues to surge, hyperscale data centers are becoming increasingly essential. These large-scale facilities require robust power solutions that can handle vast amounts of data traffic and ensure continuous uptime. The need for high-capacity, scalable, and efficient UPS systems to support the infrastructure of hyperscale data centers presents a significant growth opportunity. Manufacturers that can offer modular, high-performance UPS solutions tailored to the unique demands of hyperscale operations are well-positioned to capture a substantial market share.
Advancements in Energy Storage and Green Technologies
Another promising opportunity in the UPS market is the growing emphasis on energy storage and green technologies. As data centers face increasing pressure to adopt sustainable practices, there is a rising demand for energy-efficient UPS systems that minimize environmental impact. Innovations such as the integration of renewable energy sources like solar or wind with UPS systems, along with the use of advanced battery technologies such as lithium-ion, provide an opportunity to meet both operational and environmental goals. Furthermore, energy storage solutions that optimize power consumption during peak and off-peak hours can enhance energy efficiency and reduce operational costs. With sustainability being a key focus for businesses and regulatory bodies, there is significant potential for UPS manufacturers to capitalize on the demand for eco-friendly solutions while contributing to the broader green energy movement.
Market Segmentation Analysis:
By UPS Type:
The Global Data Center Uninterruptible Power Supply (UPS) market is primarily segmented by UPS type, with each offering unique advantages for different data center applications. Standby UPS systems are the most cost-effective and provide basic protection against power outages. They are typically used in smaller data centers with lower power demands. Line Interactive UPS systems are more advanced and can handle moderate power fluctuations, making them suitable for medium-sized data centers that require enhanced reliability without significant additional investment. Double Conversion UPS systems provide the highest level of protection by converting incoming AC power to DC and then back to AC, ensuring clean and stable power delivery. This type is most commonly used in large data centers where uptime is critical, and the potential impact of power disruptions is high. The Others category includes specialized UPS solutions designed for specific applications, such as hybrid systems that combine features of multiple UPS types, catering to niche market segments that require tailored solutions.
By Data Center Size:
The demand for UPS systems also varies based on data center size. Small data centers typically utilize standby or line interactive UPS systems due to their lower power demands and cost constraints. These systems offer sufficient protection for small-scale operations that do not require high-level redundancy or backup capacity. Medium-sized data centers often require more robust UPS solutions, such as line interactive or double conversion systems, to manage moderate loads and ensure higher availability. These systems are designed to accommodate increasing power demands while balancing cost and efficiency. Large data centers, which handle significant data traffic and operate on a larger scale, rely heavily on double conversion UPS systems to ensure uninterrupted power supply and maintain operational continuity. These systems are essential for large-scale operations, where even short periods of downtime can result in substantial financial and operational losses. As the size and complexity of data centers increase, the demand for high-performance UPS systems becomes more critical.
Segments:
Based on UPS Type:
- Standby
- Line Interactive
- Double Conversion
- Others
Based on Data Center Size:
- Small
- Medium
- Large
Based on Industry:
- BFSI
- IT & Telecom
- Healthcare
- Manufacturing
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share in the Global Data Center Uninterruptible Power Supply (UPS) market, accounting for approximately 35% of the total market in 2023. This region’s dominance is driven by the high demand for data centers across various industries, including technology, finance, and healthcare. The U.S., being home to some of the world’s largest data center operators, such as Google, Amazon, and Microsoft, has a significant need for reliable and energy-efficient UPS systems. Furthermore, the rapid expansion of cloud services and big data analytics, coupled with increasing regulatory requirements for data protection, is fueling the adoption of advanced UPS solutions. The growing focus on energy-efficient and sustainable UPS systems, particularly in light of environmental concerns, further contributes to North America's strong position in the market.
Asia-Pacific
Asia-Pacific (APAC) is the fastest-growing region in the Global Data Center UPS market, with an estimated CAGR of 6.2% during the forecast period from 2023 to 2032. This region accounts for approximately 28% of the market share in 2023. The rapid expansion of digital infrastructure, driven by the increasing adoption of cloud computing, IoT, and e-commerce, is a key factor propelling the demand for UPS systems in Asia-Pacific. Countries like China, India, Japan, and South Korea are experiencing a surge in data center development, particularly in emerging markets, which drives the need for reliable power backup solutions. Additionally, the shift toward hyperscale data centers and the rising focus on energy efficiency and sustainability present significant growth opportunities for UPS manufacturers. Governments in the region are also implementing policies to support green energy, further promoting the adoption of advanced, energy-efficient UPS systems.
Europe
Europe holds a market share of around 23% in the Global Data Center UPS market in 2023. The region is experiencing steady growth due to the increasing need for data centers driven by the digital transformation of various industries, including automotive, healthcare, and finance. In Europe, the demand for energy-efficient and environmentally friendly solutions is particularly high, with organizations striving to meet sustainability goals. The growing emphasis on reducing carbon footprints and adhering to stringent environmental regulations has led to a shift towards eco-friendly UPS systems, such as those incorporating lithium-ion batteries. The European Union’s green energy policies and commitment to carbon neutrality further fuel the adoption of sustainable UPS solutions in data centers. Moreover, major data center hubs in countries like Germany, the U.K., and France are contributing to the growing market demand.
Middle East & Africa
The Middle East and Africa (MEA) region represents a smaller portion of the market, with a share of approximately 14% in 2023. However, the region is witnessing significant growth, driven by the increasing investment in digital infrastructure and the rise of data centers in countries like the UAE, Saudi Arabia, and South Africa. The growing demand for cloud-based services, e-commerce, and the digitalization of businesses across the region is creating new opportunities for UPS systems. Furthermore, the MEA region is focusing on diversifying its economy and enhancing technological capabilities, with data centers playing a key role in these efforts. Despite its smaller market share compared to other regions, MEA presents significant untapped potential, particularly with the region’s ongoing efforts to boost its digital transformation and improve energy efficiency across industries.
Key Player Analysis
- Eaton
- Hewlett Packard Enterprise (HPE)
- Lenovo Group
- S&C
- ABB Ltd.
- KSTAR
- EAST
- Zhicheng Champion
- CyberPower
- Socomec
- Delta Electronics, Inc.
- Legrand
- Toshiba International Corporation
- Mitsubishi Electric Corporation
- Vertiv Group Corp.
- Clary Corp.
- Huawei Technologies
- Rittal
- Kohler Company
- Cisco Systems
- ZTE
- Schneider-Electric
- Emerson
- Eksi
- Kehua
- Jonchan
- Piller
- Sendon
- Angid
- Stone
- SORO Electronics
- Baykee
- Gamatronic
- DPC
- Sanke
- Foshan Prostar
- Jeidar
- Hossoni
- ChromaIT
- Yeseong Engineering
Competitive Analysis
The Global Data Center Uninterruptible Power Supply (UPS) market is highly competitive, with several leading players driving innovation and market share. Eaton, Schneider Electric, Vertiv, Huawei Technologies, Emerson, ABB Ltd., Toshiba International Corporation, CyberPower, and Legrand are prominent players in this space. These companies are focused on developing energy-efficient, reliable, and scalable UPS solutions to cater to the growing demand from data centers. Leading companies are focusing on enhancing their product portfolios with energy-efficient and scalable UPS systems designed to support the increasing requirements of data centers. Key trends include the shift toward modular UPS systems, which offer flexibility and easier maintenance, and the integration of lithium-ion batteries to improve energy density and reduce maintenance costs. Moreover, players in the market are focusing on offering intelligent UPS systems with digital connectivity features that allow for real-time monitoring and predictive maintenance. This helps to minimize downtime and optimize energy use. Companies are also pursuing strategic partnerships and collaborations to expand their geographic presence and access new markets, particularly in the Asia-Pacific and Middle East regions, where data center infrastructure is rapidly growing. The market is also seeing a push toward environmentally sustainable solutions, with a focus on reducing the carbon footprint and energy consumption of UPS systems. As demand for more advanced and efficient solutions continues to grow, competition is expected to intensify, with both established players and new entrants innovating to capture market share.
Recent Developments
- In December 2024, Vertiv launched the Vertiv PowerUPS 9000, a compact and energy-efficient uninterruptible power supply (UPS) system featuring high power density. Designed to support various IT applications, from traditional computing to high-density environments, this UPS is available globally in CE and UL models, with power capacities ranging from 250 to 1250 kW per unit.
- In May 2024, ABB unveiled the integration of nickel-zinc (NiZn) batteries into its MegaFlex line of high-power uninterruptible power supply (UPS) solutions designed for data centers and critical power applications. These batteries, sourced from ZincFive, provide a safe, resilient, and sustainable energy storage option compared to conventional battery technologies.
- In December 2023, Eaton launched a new UPS product, named Eaton 93T UPS to deliver stable power for critical applications, such as small data centers and server rooms. This solution is beneficial to industries, including IT sectors, finance, government, and healthcare.
- In July 2023, ABB India’s Electrification business launched a novel UPS solution known as MegaFlex DPA (Decentralized Parallel Architecture) UPS for data centers in the Indian Market. This solution offers notable sustainable power technology with reduced energy losses.
- In April 2023, Schneider Electric launched Easy UPS 3-Phase Modular. This UPS is designed to safeguard critical loads while providing Live Swap functionality.
Market Concentration & Characteristics
The market for Global Data Center Uninterruptible Power Supply (UPS) systems is moderately concentrated, with a few dominant players holding significant market share while several smaller players cater to niche segments. The industry is characterized by high competition, driven by the increasing demand for reliable, efficient, and scalable power solutions in data centers. Leading players focus on product innovation, energy efficiency, and advanced features such as modular systems, lithium-ion battery integration, and intelligent power management to differentiate themselves in the market. As data centers grow in size and complexity, the demand for UPS systems with higher capacities, longer battery life, and improved monitoring capabilities increases. The market is also witnessing an increasing emphasis on sustainability, with companies focusing on reducing energy consumption and carbon footprints by developing eco-friendly UPS solutions. The market characteristics include a strong emphasis on technological advancements, especially the integration of digital features and remote monitoring. Additionally, modular and scalable UPS solutions are becoming a preference for data centers seeking flexibility and ease of maintenance. While large players dominate the high-end and enterprise segments, smaller players are targeting small and medium-sized data centers with cost-effective, reliable solutions. The growing digitalization, cloud services, and e-commerce trends are expected to drive continued market expansion, making the UPS industry a key player in ensuring uninterrupted power supply across data centers globally.
Report Coverage
The research report offers an in-depth analysis based on UPS Type, Data Center Size, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Data Center Uninterruptible Power Supply (UPS) market is expected to continue its growth, driven by the increasing demand for uninterrupted power in data centers.
- Advancements in energy efficiency and sustainability will play a pivotal role in shaping the future of UPS systems.
- The integration of lithium-ion batteries and modular systems will enhance UPS performance and reduce maintenance costs.
- Smart UPS solutions featuring digital connectivity and remote monitoring will become more prevalent in data centers.
- The demand for high-capacity UPS systems will rise as data centers continue to scale and handle larger volumes of data.
- Rising concerns about energy consumption and carbon footprints will lead to a focus on eco-friendly UPS technologies.
- The Asia-Pacific region will experience significant market growth, fueled by expanding data center infrastructure.
- As hyperscale data centers grow, UPS solutions will evolve to support larger and more complex infrastructures.
- Smaller players will focus on offering cost-effective and reliable UPS solutions to cater to medium and small-sized data centers.
- Strategic partnerships and collaborations between UPS manufacturers and data center operators will drive innovation and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Cloud Computing and Data Storage
The proliferation of cloud services, big data analytics, and IoT applications is driving the need for robust, uninterrupted power in data centers, fueling demand for advanced UPS systems to ensure continuous operations and data integrity.
Technological Advancements in Energy Efficiency
Innovations such as lithium-ion batteries and modular UPS architectures are improving energy efficiency, reducing operational costs, and aligning with sustainability goals, making UPS systems more attractive to data center operators.
Growth of Hyperscale Data Centers
The rise of hyperscale data centers, which require high-capacity and scalable UPS solutions to support massive data loads and uptime requirements, is significantly increasing the demand for sophisticated UPS systems.
Emphasis on Business Continuity and Disaster Recovery
As organizations become more reliant on digital infrastructure, the need to prevent downtime and data loss due to power disruptions is intensifying, making reliable UPS systems essential for business continuity and disaster recovery strategies.
Regulatory and Environmental Pressures
Stricter environmental regulations and corporate sustainability initiatives are pushing data centers to adopt energy-efficient and eco-friendly UPS solutions, accelerating the shift toward greener technologies in the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Data Center Uninterruptable Power Supply (UPS) market?
What factors are driving the growth of the Global Data Center Uninterruptable Power Supply (UPS) market?
What are the key segments within the Global Data Center Uninterruptable Power Supply (UPS) market?
What are some challenges faced by the Global Data Center Uninterruptable Power Supply (UPS) market?
Who are the major players in the Global Data Center Uninterruptable Power Supply (UPS) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 BFSI
- 1.2.2 IT & Telecom
- 1.2.3 Healthcare
- 1.2.4 Manufacturing
- 1.2.5 Others
- 1.3 By UPS Type
- 1.3.1 Standby
- 1.3.2 Line Interactive
- 1.3.3 Double Conversion
- 1.3.4 Others
- 1.4 By Data Center Size
- 1.4.1 Small
- 1.4.2 Medium
- 1.4.3 Large
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 5,210.10 million → 2032: USD 8,068.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Center Uninterruptable Power Supply (UPS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Center Uninterruptable Power Supply (UPS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Center Uninterruptable Power Supply (UPS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Center Uninterruptable Power Supply (UPS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Center Uninterruptable Power Supply (UPS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Center Uninterruptable Power Supply (UPS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Center Uninterruptable Power Supply (UPS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Center Uninterruptable Power Supply (UPS) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 5,210.10 million → 2032: USD 8,068.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Center Uninterruptable Power Supply (UPS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI
- 12.3.7.2 IT & Telecom
- 12.3.7.3 Healthcare
- 12.3.7.4 Manufacturing
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By UPS Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Standby
- 12.4.7.2 Line Interactive
- 12.4.7.3 Double Conversion
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Data Center Size - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Small
- 12.5.7.2 Medium
- 12.5.7.3 Large
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Center Uninterruptable Power Supply (UPS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Center Uninterruptable Power Supply (UPS) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Center Uninterruptable Power Supply (UPS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Center Uninterruptable Power Supply (UPS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Eaton
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Schneider Electric
- 18.4 Vertiv Group Corp.
- 18.5 Huawei Technologies
- 18.6 Emerson
- 18.7 ABB Ltd.
- 18.8 Legrand
- 18.9 Toshiba International Corporation
- 18.10 Delta Electronics, Inc.
- 18.11 CyberPower
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

