
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Data Centre Market Size 2023 | USD 324,198.23 million |
| Data Centre Market, CAGR | 6.70% |
| Data Centre Market Size 2032 | USD 607,832.10 million |
Market Overview
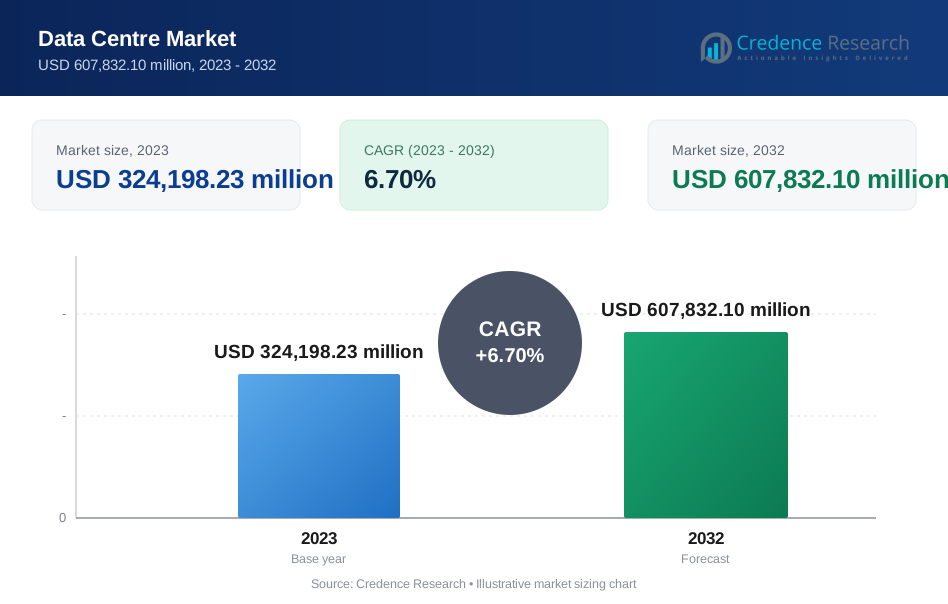
The Global Data Centre Market is projected to grow from USD 324,198.23 million in 2023 to USD 607,832.10 million by 2032, at a compound annual growth rate (CAGR) of 6.70%.
The Global Data Centre Market is driven by the rapid adoption of cloud computing, the surge in digital transformation initiatives, and the increasing need for data storage and processing capabilities across various industries. The growing use of IoT devices, big data analytics, and artificial intelligence applications significantly boosts demand for robust data centre infrastructure. Additionally, the emphasis on data security, compliance with stringent regulations, and disaster recovery solutions further fuels market growth. Trends such as sustainability and energy efficiency are shaping the market, with operators increasingly adopting green technologies and renewable energy sources to reduce environmental impact.
The Global Data Centre Market is led by North America and Europe, which together account for over 50% of the market share due to advanced digital infrastructure, high demand for cloud services, and strong investment climates. Asia-Pacific is rapidly emerging as a key region, driven by increasing digitalization, cloud adoption, and growing internet penetration in countries like China and India. Major players such as IBM Corporation, Cisco Systems, Inc., HPE, and Dell Technologies dominate the market, leveraging their extensive technological expertise and global presence to provide scalable, secure, and efficient data centre solutions across various regions.
Market Drivers
Digitalization and Cloud Adoption
The rapid proliferation of digital devices, IoT, and online services has led to a substantial increase in data generation, significantly impacting the global data centre market. As businesses and consumers increasingly rely on digital platforms, the volume of data being produced and processed continues to grow exponentially. For instance, a survey revealed that companies adopting cloud platforms bring new capabilities to market more quickly, innovate more easily, and scale more efficiently, while also reducing technology risk. This surge in data generation necessitates the development of robust data centre infrastructure to manage and store the vast amounts of information effectively. Furthermore, many businesses are shifting towards cloud-based solutions to enhance operational flexibility and scalability. This widespread migration to the cloud creates a critical need for advanced data centres that can support these cloud services, ensuring seamless and efficient data handling and storage capabilities.
Government Initiatives and Policies
Governments around the world are prioritizing digital transformation, creating a supportive environment for data centre development. Initiatives aimed at fostering a digital economy encourage the establishment of modern data centres that can support the increasing demand for digital services. For instance, the U.S. Government Accountability Office reported that federal agencies closed a total of 96 data centers in fiscal year 2020, with significant cost savings. Additionally, as concerns about data security and privacy escalate, there is a growing need for secure and resilient data centres. Governments are implementing stringent cybersecurity regulations to protect sensitive information from cyber threats, which in turn drives the demand for data centres equipped with advanced security measures. Compliance with these regulations is crucial for businesses to maintain trust and ensure the safety of their data, making the development of secure data centre infrastructure a priority.
Economic Growth and Innovation
The expanding global economy is fueling increased business activity, leading to higher demand for data centre services. As companies grow and expand their operations, their need for reliable data storage and processing capabilities also rises. Moreover, technological advancements in areas such as artificial intelligence, machine learning, and big data analytics are driving the need for powerful data centre infrastructure. These cutting-edge technologies require substantial computing power and data handling capacity, which only well-equipped data centres can provide. The continuous innovation in these fields ensures that the demand for advanced data centre solutions will remain strong, supporting the growth of the global data centre market.
Connectivity and Infrastructure
The expansion of fiber-optic networks globally is enhancing high-speed connectivity, making various regions attractive for data centre development. Reliable and fast internet connections are essential for the efficient functioning of data centres, enabling quick data transfer and access to cloud services. Additionally, the availability of stable and affordable energy sources is critical for the operations of data centres, which are known for their high energy consumption. Ensuring a steady and cost-effective energy supply is vital for maintaining the operational efficiency of data centres, supporting their role in the digital infrastructure. These factors collectively contribute to the growing attractiveness of regions that can offer robust connectivity and energy resources, promoting the expansion of the global data centre market.
Market Trends
Sustainability, Energy Efficiency, and the Rise of Hyperscale Data Centres
In the global data centre market, there is a significant shift towards sustainability and energy efficiency, reflecting a growing commitment to reducing environmental impact. Data centre operators are increasingly focusing on building green data centres that use renewable energy sources, such as solar and wind power, to minimize their carbon footprints. The integration of energy-efficient technologies, including advanced cooling systems and waste heat recovery, helps to reduce power consumption and operational costs, aligning with corporate sustainability goals and regulatory requirements. These efforts not only enhance the environmental responsibility of data centres but also appeal to clients and investors who prioritize eco-friendly practices. For instance, Amazon Web Services (AWS) has announced plans to invest $10 billion to build two data centre complexes in Mississippi to support the growing demand for cloud services. Alongside these trends, the market is witnessing a surge in the development of hyperscale data centres, driven by the demand for cloud services and big data analytics. Hyperscale facilities, operated by major cloud providers, offer vast storage and processing capabilities necessary to handle the ever-increasing volumes of data. These large-scale data centres are strategically located in regions with abundant energy resources and robust connectivity to ensure efficient operations and low latency, making them a critical component of the digital infrastructure. The dual focus on sustainability and scalability is shaping the future of the data centre industry, balancing the need for massive data handling capabilities with environmental stewardship.
Edge Computing, Modular Construction, and Focus on Security and Resilience
The rise of edge computing is transforming the global data centre landscape, driving demand for smaller, decentralized data centres positioned closer to end-users. These edge data centres help to reduce latency and improve the efficiency of data processing, which is crucial for real-time, data-intensive applications such as IoT, AI, and augmented reality. By bringing data storage and processing closer to the source, edge computing supports faster response times and minimizes network congestion, enhancing the user experience. In addition to the growth of edge computing, there is an increasing adoption of modular and prefabricated construction methods in the data centre industry. These approaches enable faster deployment of data centre facilities, reduce construction costs, and offer scalability to meet changing business needs. Modular data centres can be easily expanded or reconfigured, providing a flexible solution that adapts to evolving technological demands. Furthermore, there is a heightened focus on security and resilience, as data centre operators invest in robust cybersecurity measures to protect against growing cyber threats. The importance of disaster recovery is also emphasized, with data centres being designed to withstand natural disasters and other disruptions, ensuring continuous service availability. This comprehensive approach to security and resilience is vital for maintaining trust and reliability in the global data centre infrastructure, supporting the needs of businesses and consumers in an increasingly digital world.
Market Challenges Analysis
Land Availability, Costs, and Energy Challenges
Finding suitable land for large-scale data centres presents a significant challenge, particularly in urban areas where zoning restrictions and high competition for space are common. Limited availability of prime locations not only drives up land prices but also complicates the site selection process, making it costly and time-consuming. For instance, CBRE notes that Northern Virginia remains the world’s largest data center market with 2,132 MW of total inventory, but power availability and bottlenecks are significant challenges. High land costs in desirable areas can significantly impact the overall project budget, limiting the potential for expansion and increasing operational expenses. Additionally, rising energy prices pose a critical concern for data centre operators, as these facilities are inherently energy-intensive. The growing cost of energy directly affects the profitability and sustainability of data centres, compelling operators to seek more efficient energy solutions. Compounding these issues, stricter environmental regulations aimed at reducing carbon emissions add further complexity, as data centres must invest in green technologies and practices to meet sustainability goals. Balancing the need for sustainability with economic viability requires strategic planning and innovation, making it a challenging landscape for data centre operators to navigate.
Infrastructure, Talent Shortages, and Regulatory Uncertainty
Infrastructure constraints pose another set of challenges for the global data centre market. Limited grid capacity in certain regions can restrict the expansion of data centres, hindering their ability to meet the growing demand for data storage and processing capabilities. Ensuring adequate connectivity, including the deployment of comprehensive fiber-optic networks, is essential but can be challenging, particularly in less developed areas, impacting the overall effectiveness and reliability of data centres. In addition to these infrastructure issues, the market faces a shortage of specialized talent required for data centre design, operations, and maintenance. The competition for skilled workers is intense, especially in regions with high demand for technology talent, which can slow down development and affect operational efficiency. Regulatory and policy uncertainty adds another layer of complexity. Changes in government policies, such as adjustments to tax incentives or planning regulations, can create uncertainty for investors and developers, complicating strategic planning and execution. Navigating these regulatory landscapes can be time-consuming and costly, presenting bureaucratic hurdles that delay project approvals and increase risks. Geopolitical risks, including trade tensions, tariffs, and regional instability, further complicate the market, impacting the cost and feasibility of building and operating data centres. These challenges necessitate a proactive approach to infrastructure investment, workforce development, and regulatory compliance to ensure the sustainable growth of the global data centre industry.
Market Segmentation Analysis:
By Type:
The Global Data Centre Market is segmented into several types, including Enterprise, Edge, Colocation, Hyperscale, Managed, and Modular data centres, each catering to different needs. Enterprise data centres are designed to meet the specific requirements of large organizations, offering dedicated infrastructure for robust IT operations. Edge data centres are smaller, decentralized facilities positioned closer to end-users, which helps reduce latency and enhance the performance of real-time applications such as IoT and AI. Colocation data centres provide shared space, power, and cooling, allowing multiple businesses to house their servers securely and efficiently. Hyperscale data centres, typically operated by major cloud providers, offer massive scalability and are essential for supporting the increasing demand for cloud services. Managed data centres offer third-party management of IT infrastructure, enabling companies to outsource their data handling needs. Lastly, Modular data centres offer flexible, scalable solutions that can be rapidly deployed to meet the evolving demands of businesses, providing an agile response to changing market conditions.
By Component:
The market is also categorized based on components, which include Hardware, Data Centre Infrastructure Management Software, and Services. The Hardware segment is crucial and comprises essential components such as Power Systems, Cooling Systems, Racks, Servers, Networking Devices, and other critical infrastructure required for the smooth operation of data centres. Effective power and cooling systems are vital for maintaining optimal operating conditions, while racks, servers, and networking devices ensure the seamless processing and management of vast amounts of data. Data Centre Infrastructure Management Software is divided into Cloud-based and On-premises solutions, providing operators with flexible options for managing and optimizing data centre performance. The Services segment includes a variety of offerings, such as Professional Services, Integration & Implementation, Consulting, Support & Maintenance, and Managed Services. These services are essential for the design, deployment, and ongoing management of data centres, ensuring that they function efficiently and securely, thus supporting the continuous evolution of the global digital landscape.
Segments:
Based on Type:
- Enterprise
- Edge
- Colocation
- Hyperscale
- Managed
- Modular
Based on Component:
- Hardware
- Power Systems
- Cooling Systems
- Racks
- Servers
- Networking Devices
- Others
- Data Centre Infrastructure Management Software
- Cloud-based
- On-premises
- Service
- Professional Services
- Integration & Implementation
- Consulting
- Support & Maintenance
- Managed Services
Based on Size:
- Small
- Mid-Sized
- Large
Based on Tire:
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Industry:
- IT & Telecom
- BFSI
- Manufacturing
- Healthcare
- Government
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global data centre market, accounting for approximately 40% of the total market revenue. The dominance of this region is driven by the presence of numerous technology giants, including major cloud service providers such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud. The United States, in particular, leads the market due to its robust digital infrastructure, high adoption of advanced technologies, and the presence of key financial and technology hubs. Additionally, strong government support for digital transformation and stringent data protection regulations have further fueled the demand for data centres in this region. The continuous investment in expanding existing facilities and building new data centres ensures that North America remains at the forefront of the global data centre market, catering to the growing needs of various industries such as finance, healthcare, and e-commerce.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the global data centre market, holding a substantial market share of around 25%. This growth is primarily attributed to the rapid digitalization across emerging economies such as China, India, and Southeast Asian countries. The region's expanding middle class and increasing internet penetration rates are driving the demand for data-intensive applications, including streaming services, online gaming, and e-commerce. Furthermore, the proliferation of smartphones and other connected devices has led to an exponential increase in data generation, necessitating the development of robust data centre infrastructure. Governments in the region are also actively supporting digital transformation initiatives and providing incentives for data centre investments. Additionally, the region's strategic location, relatively lower operational costs, and the increasing availability of renewable energy sources make Asia-Pacific an attractive destination for data centre operators, positioning it as a key player in the global data centre landscape.
Key Player Analysis
- IBM Corporation
- Cisco System, Inc.
- HPE
- Dell Technologies
- Hitachi Ltd
- NTT Communications
- Schneider Electric
- Comarch SA
- ABB
- Huawei Technologies Co., Ltd
Competitive Analysis
The Global Data Centre Market is highly competitive, with leading players such as IBM Corporation, Cisco Systems, Inc., HPE, Dell Technologies, and Huawei Technologies Co., Ltd. driving market dynamics. These companies leverage their extensive product portfolios, technological expertise, and global networks to offer comprehensive data centre solutions, including cloud services, networking infrastructure, and IT management. Their ability to provide scalable, secure, and energy-efficient solutions makes them preferred partners for enterprises seeking to manage growing data volumes and ensure compliance with stringent data privacy regulations. Additionally, the market sees continuous investment in research and development, leading to innovations in data centre technologies, such as advanced cooling systems, modular designs, and enhanced cybersecurity measures. The competitive landscape is further intensified by strategic partnerships, mergers, and acquisitions, as these leading players seek to expand their market reach, enhance service offerings, and solidify their positions in a rapidly evolving and demanding global market.
Recent Developments
- In August 2024, IBM revealed architecture details for the upcoming IBM Telum® II Processor and IBM Spyre™ Accelerator at Hot Chips 2024. These technologies are designed to significantly scale processing capacity across next-generation IBM Z mainframe systems, helping accelerate the use of traditional AI models and Large Language AI models.
- In June 2024, Cisco announced new AI-powered innovations and investments at Cisco Live 2024. This includes the launch of the Cisco Nexus HyperFabric AI clusters, a new simplified data centre infrastructure solution with NVIDIA for generative AI.
- In June 2024, At HPE Discover 2024, HPE and NVIDIA announced the launch of NVIDIA AI Computing by HPE, a comprehensive portfolio of co-developed AI solutions designed to accelerate the adoption of generative AI in enterprises.
- In May 2024, Dell Technologies announced the Dell AI Factory, providing customers with the infrastructure, solutions, and services needed to quickly adopt and deploy AI at scale. This includes new Dell AI PCs with Copilot+ and advancements in storage, data protection, and networking.
Market Concentration & Characteristics
The Global Data Centre Market exhibits moderate to high market concentration, with a few dominant players holding significant market shares. These key players benefit from their extensive global reach, advanced technological capabilities, and strong financial resources, allowing them to invest heavily in large-scale data centre infrastructures. The market is characterized by high entry barriers, including substantial capital investment requirements, sophisticated technical expertise, and the need to comply with complex regulatory standards across different regions. This creates a competitive advantage for established companies, which leverage their resources to expand capacity, innovate, and maintain high service standards. The market is defined by its focus on scalability, security, and energy efficiency, driven by the increasing demand for cloud services, big data analytics, and digital transformation. Additionally, the growing emphasis on sustainability and the adoption of green technologies further shape the market, ensuring that data centres meet the evolving needs of businesses while addressing environmental concerns. This combination of factors solidifies the market's resilience and growth potential in the digital age.
Report Coverage
The research report offers an in-depth analysis based on Type, Component, Size, Tire, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Data Centre Market is expected to continue growing due to the increasing demand for cloud services and digital transformation across industries.
- The adoption of edge computing will rise, driving the need for smaller, decentralized data centres closer to end-users to reduce latency.
- Sustainability will become a key focus, with more data centres integrating renewable energy sources and energy-efficient technologies to minimize their environmental impact.
- The expansion of hyperscale data centres will be significant, driven by major cloud providers seeking to accommodate growing data storage and processing needs.
- Investment in advanced cybersecurity measures will increase as data security concerns become more prominent in the face of rising cyber threats.
- Governments will continue to invest in digital infrastructure, including data centres, to support economic growth and technological innovation.
- The trend towards modular and prefabricated data centre construction will grow, enabling faster deployment and greater flexibility in scaling operations.
- Connectivity improvements, such as expanding fiber-optic networks, will enhance data centre efficiency and reliability, supporting global data traffic growth.
- Data sovereignty and compliance with local regulations will drive demand for localized data centres, ensuring data remains within specific geographical boundaries.
- Advances in artificial intelligence and automation will improve data centre management, optimizing operational efficiency and reducing costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digitalization and Cloud Adoption
The rapid proliferation of digital devices, IoT, and online services is generating massive volumes of data, necessitating robust data centre infrastructure. Businesses are increasingly migrating to cloud-based solutions for greater flexibility and scalability, driving demand for advanced data centres that can support these services.
Government Initiatives and Policies
Governments worldwide are prioritizing digital transformation and implementing stringent data security regulations, which require secure, resilient, and compliant data centre infrastructure. These policies encourage investment in modern data centres to support the growing digital economy and ensure data protection.
Economic Growth and Technological Innovation
Expanding global business activity and advancements in AI, machine learning, and big data analytics are increasing the need for powerful data centre infrastructure. These technologies require substantial computing power and storage, fueling demand for scalable and efficient data centres.
Connectivity and Infrastructure Expansion
The global rollout of fiber-optic networks and improvements in energy availability are making more regions viable for data centre development. Reliable high-speed connectivity and stable, affordable energy supplies are critical for efficient data centre operations, supporting market expansion.
Sustainability and Energy Efficiency
Growing environmental concerns and regulatory pressures are pushing data centre operators to adopt green technologies and renewable energy sources. The focus on sustainability and energy-efficient operations is shaping investment decisions and driving the development of next-generation, eco-friendly data centres.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Data Centre Market?
What factors are driving the growth of the Global Data Centre Market?
What are the key segments within the Global Data Centre Market?
What are some challenges faced by the Global Data Centre Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Size
- 1.2.1 Small
- 1.2.2 Mid-Sized
- 1.2.3 Large
- 1.3 By Type
- 1.3.1 Enterprise
- 1.3.2 Edge
- 1.3.3 Colocation
- 1.3.4 Hyperscale
- 1.3.5 Managed
- 1.3.6 Modular
- 1.4 By Industry
- 1.4.1 IT & Telecom
- 1.4.2 BFSI
- 1.4.3 Manufacturing
- 1.4.4 Healthcare
- 1.4.5 Government
- 1.4.6 Others
- 1.5 By Component
- 1.5.1 Hardware
- 1.5.2 Data Centre Infrastructure Management Software
- 1.5.3 Service
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 324,198.23 million → 2032: USD 607,832.10 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Centre Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Centre Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Centre Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Centre Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Centre Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Centre Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Centre Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Centre Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 324,198.23 million → 2032: USD 607,832.10 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Centre Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Size - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small
- 12.3.7.2 Mid-Sized
- 12.3.7.3 Large
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enterprise
- 12.4.7.2 Edge
- 12.4.7.3 Colocation
- 12.4.7.4 Hyperscale
- 12.4.7.5 Managed
- 12.4.7.6 Modular
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Industry - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 IT & Telecom
- 12.5.7.2 BFSI
- 12.5.7.3 Manufacturing
- 12.5.7.4 Healthcare
- 12.5.7.5 Government
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Component - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hardware
- 12.6.7.2 Data Centre Infrastructure Management Software
- 12.6.7.3 Service
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Centre End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Centre Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Centre Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Centre Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cisco Systems, Inc.
- 18.4 HPE
- 18.5 Dell Technologies
- 18.6 Hitachi Ltd
- 18.7 NTT Communications
- 18.8 Schneider Electric
- 18.9 Comarch SA
- 18.10 ABB
- 18.11 Huawei Technologies Co., Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

