
Market Overview:
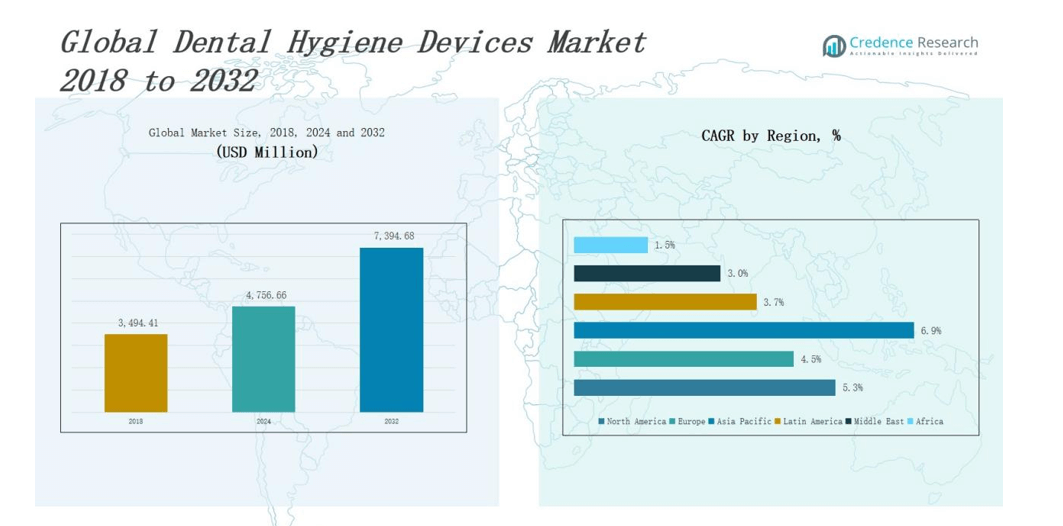
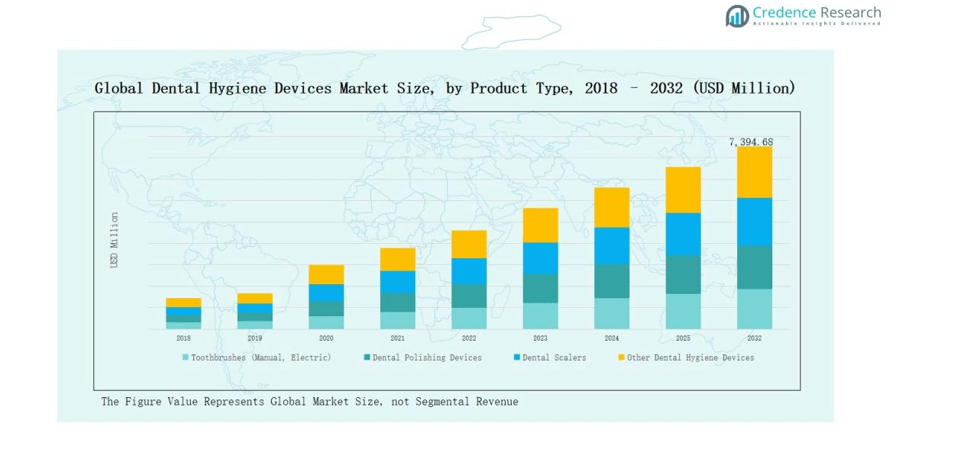
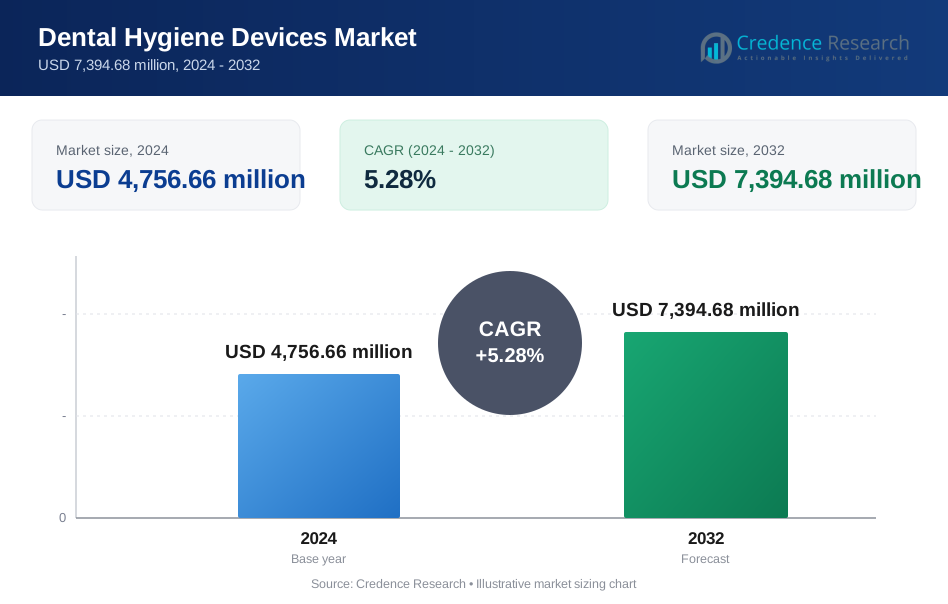
Dental Hygiene Devices Market size was valued at USD 3,494.41 million in 2018 to USD 4,756.66 million in 2024 and is anticipated to reach USD 7,394.68 million by 2032, at a CAGR of 5.28% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dental Hygiene Devices Market Size 2024 | USD 4,756.66 million |
| Dental Hygiene Devices Market, CAGR | 5.28% |
| Dental Hygiene Devices Market Size 2032 | USD 7,394.68 million |
The Dental Hygiene Devices Market is shaped by prominent players such as Dentsply Sirona, Procter & Gamble (Oral-B), Koninklijke Philips (Sonicare), Colgate-Palmolive, Water Pik, Sunstar Suisse (GUM), Lion Corporation, Church & Dwight, Panasonic, Truly International Holdings, and Dr Fresh. These companies compete through innovation, product diversification, and strong global distribution networks. Procter & Gamble, Philips, and Colgate-Palmolive lead with strong consumer trust and extensive electric and manual toothbrush portfolios, while Panasonic and Water Pik drive premium adoption with advanced oral irrigators and electronic solutions. Regionally, North America emerged as the leading market in 2024, commanding a 39% share, supported by high oral health awareness, advanced dental care infrastructure, and early adoption of smart hygiene devices.
Market Insights
- The Dental Hygiene Devices Market grew from USD 3,494.41 million in 2018 to USD 4,756.66 million in 2024 and will reach USD 7,394.68 million by 2032.
- Key players include Dentsply Sirona, Procter & Gamble (Oral-B), Philips (Sonicare), Colgate-Palmolive, Water Pik, Sunstar Suisse, Lion Corporation, Church & Dwight, Panasonic, Truly International Holdings, and Dr Fresh.
- Toothbrushes dominated with 42% share in 2024, while polishing devices and scalers held 25%, and other hygiene devices including flossers and irrigators captured 33%.
- Retail pharmacies led distribution with 48% share in 2024, followed by online pharmacies at 32% and hospital pharmacies at 20%, with online channels gaining momentum.
- North America commanded 39% share in 2024, Europe held 24%, and Asia Pacific 19%, while Latin America (4%), Middle East (2%), and Africa (1%) contributed modestly.
Market Segment Insights
By Product Type
Toothbrushes accounted for the largest share of 42% in 2024, driven by their widespread use in daily oral care routines. Within this category, manual toothbrushes remain the most common due to affordability and ease of availability. However, electric toothbrushes are steadily gaining ground, supported by rising consumer awareness of advanced plaque removal and gum health benefits. Dental polishing devices and dental scalers collectively held 25% of the market, with growth fueled by professional dental practices and home-use kits for preventive care. Other dental hygiene devices, including flossers and irrigators, captured the remaining 33%, benefitting from product innovation and consumer demand for complete oral care solutions.
- For instance, the dental polishing device and scaler market is expanding with companies like Den-Mat and Seago Group leading professional dental care segments. Meanwhile, oral irrigators such as Waterpik are growing in home-use kits with technologically advanced designs.
By Distribution Channel
Retail pharmacies led the market with a 48% share in 2024, reflecting their strong presence in urban and semi-urban regions and the consumer preference for immediate product access. Online pharmacies followed with 32% share, supported by the expansion of e-commerce platforms, rising discounts, and convenience of home delivery. Hospital pharmacies accounted for 20%, largely linked to professional recommendations and post-treatment device prescriptions. The steady rise of online channels is expected to challenge retail dominance, particularly as digital health platforms promote dental hygiene products directly to consumers.
- For instance, Amazon reported over 300 million active customer accounts worldwide, with Oral-B electric toothbrushes ranking among its top-selling personal care devices.
Market Overview
Rising Prevalence of Oral Diseases
The increasing prevalence of dental issues such as cavities, periodontal disease, and oral infections strongly drives the dental hygiene devices market. Growing sugar consumption, poor dietary habits, and tobacco use are fueling oral health problems globally. According to the WHO, untreated dental caries remain one of the most common health conditions. This rising burden has led to heightened awareness regarding preventive care, boosting demand for toothbrushes, scalers, and other hygiene devices. Preventive oral care is now viewed as a cost-effective way to reduce treatment expenses.
- For instance, Philips Sonicare DiamondClean models, like the 9000 and 9300 series with specific brush heads, have been clinically shown to remove up to 10 times more plaque than a manual brush, and improve gum health in as little as two weeks.
Growing Consumer Awareness of Preventive Oral Care
Heightened consumer awareness regarding oral health maintenance is fueling device adoption. Rising access to dental health information through social media campaigns and professional recommendations encourages individuals to adopt effective hygiene practices. Governments and organizations promote oral care awareness through school programs and public campaigns, further boosting demand. Electric toothbrushes and advanced oral irrigators are increasingly viewed as superior solutions to prevent plaque and gingivitis. This shift toward preventive care over corrective treatments has created consistent demand across both developed and emerging economies.
- For instance, Waterpik’s Aquarius Water Flosser has been shown in independent studies to remove up to 99.9% of plaque from treated areas, demonstrating its strong preventive role in reducing oral health risks.
Technological Advancements in Dental Hygiene Devices
Continuous innovation in dental hygiene devices significantly drives market growth. Electric toothbrushes now integrate smart sensors, pressure monitoring, and app connectivity, offering personalized oral care. Similarly, ultrasonic dental scalers and compact polishing devices provide enhanced cleaning efficiency. Manufacturers are investing in research to create more user-friendly, eco-friendly, and cost-efficient products. These advancements not only improve patient outcomes but also increase consumer willingness to spend on premium devices. The trend is particularly strong in urban regions where consumers seek convenience and advanced features.
Key Trends & Opportunities
Surge in Online Distribution Channels
commerce platforms present strong opportunities for growth in dental hygiene devices. Online pharmacies and direct-to-consumer websites are capturing rising demand due to convenience, better price comparisons, and discount offerings. Subscription models for toothbrushes and refills are also gaining popularity, ensuring steady revenue streams. The trend is especially prominent in Asia-Pacific and North America, where digital adoption is high. As consumers increasingly prefer doorstep delivery, manufacturers are strengthening their online presence through partnerships with leading marketplaces and expanding brand-owned digital platforms.
- For instance, Colgate's digital investment in Brazil led to a 496% year-over-year increase in average monthly sell-out value on its B2B marketplace for dentists, alongside a 908% year-to-date growth in first-party data acquisition.
Sustainability and Eco-Friendly Product Development
An emerging trend in the dental hygiene devices market is the shift toward sustainable and eco-friendly products. Rising environmental concerns are leading manufacturers to design biodegradable toothbrushes, recyclable packaging, and energy-efficient electric devices. Bamboo-based brushes and refillable floss cartridges are gaining traction among eco-conscious consumers. Governments and regulatory agencies are also encouraging sustainability initiatives in consumer products. This growing preference for green solutions is creating new opportunities for players to differentiate themselves and capture market share among environmentally responsible buyers.
- For instance, Colgate introduced its "Colgate Keep" toothbrush in 2021, which uses a reusable aluminum handle and replaceable brush heads to reduce plastic waste.
Key Challenges
High Cost of Advanced Devices
The cost of advanced devices such as electric toothbrushes and ultrasonic scalers limits adoption, particularly in low-income and developing regions. While these products offer superior cleaning and long-term oral health benefits, affordability remains a major barrier. Many consumers continue to rely on low-cost manual toothbrushes, slowing the penetration of innovative products. Companies face the challenge of balancing innovation with affordability to expand their reach. Price sensitivity in emerging economies continues to restrict the growth potential of premium dental hygiene devices.
Lack of Access in Rural and Underdeveloped Areas
Limited access to dental hygiene devices in rural and underdeveloped regions remains a significant challenge. Weak distribution networks, low dental awareness, and economic constraints restrict product penetration. Populations in remote areas often rely on traditional methods or neglect oral hygiene altogether, contributing to a high prevalence of dental diseases. Manufacturers and healthcare organizations must address this gap by introducing cost-effective products and expanding outreach programs. Without improved access, large segments of the global population remain underserved, constraining overall market expansion.
Competition from Low-Cost Alternatives
The widespread availability of counterfeit and low-cost alternatives presents a major challenge for branded players. Local manufacturers often provide cheaper products that attract price-sensitive consumers but compromise on quality and durability. This undermines consumer trust and puts pressure on global brands to justify their higher prices. Strong competition from unregulated products also impacts profit margins and hinders premium device adoption. Companies must strengthen quality assurance, consumer education, and regulatory compliance to reduce the impact of low-cost substitutes on market growth.
Regional Analysis
North America
North America held the largest share of 39% in 2024, valued at USD 2,077.23 million. The region’s growth is supported by high awareness of oral health, advanced dental care infrastructure, and the widespread adoption of electric toothbrushes and polishing devices. Strong presence of leading players such as Procter & Gamble, Philips, and Colgate-Palmolive further reinforces market expansion. Favorable reimbursement policies for dental procedures and a growing elderly population with higher oral care needs also contribute. With a CAGR of 5.3%, North America will remain dominant, reaching USD 3,238.12 million by 2032.
Europe
Europe captured 24% of the market share in 2024, with revenues at USD 1,270.59 million. The market benefits from strong preventive care adoption, government-backed dental health initiatives, and robust consumer awareness. Countries like Germany, the UK, and France drive demand due to advanced oral care practices and high disposable incomes. Electric toothbrush adoption is particularly strong in Western Europe. However, Eastern Europe lags due to lower affordability. The region is projected to grow at a CAGR of 4.5%, reaching USD 1,856.93 million by 2032, maintaining its position as the second-largest market.
Asia Pacific
Asia Pacific accounted for 19% share in 2024, valued at USD 997.45 million. The region shows the fastest growth, with a CAGR of 6.9%, driven by urbanization, growing middle-class spending, and increased awareness of oral health. China, India, and Japan dominate due to large populations and rapid adoption of advanced hygiene devices. Expanding e-commerce platforms also drive accessibility in emerging markets. Manufacturers are investing in affordable electric toothbrushes to capture price-sensitive consumers. By 2032, Asia Pacific is forecast to reach USD 1,755.02 million, becoming a key growth hub for global players.
Latin America
Latin America held a 4% share in 2024, valued at USD 226.64 million. The market is supported by rising demand for preventive oral care, particularly in Brazil and Argentina, where urban populations drive higher consumption. However, limited affordability and unequal healthcare access constrain adoption. Multinational players are entering through partnerships with local distributors to improve penetration. Growth is steady at a CAGR of 3.7%, with the market expected to reach USD 312.70 million by 2032. Latin America’s role will remain modest compared to other global regions.
Middle East
The Middle East represented 2% of the market in 2024, valued at USD 118.60 million. Demand is concentrated in GCC countries, where rising disposable incomes and strong investments in healthcare support adoption of premium devices. Israel and Turkey also contribute through improved oral care awareness and product availability. However, economic disparities across the region slow overall growth. With a CAGR of 3.0%, the market is forecast to reach USD 154.80 million by 2032. Despite its small base, premiumization in dental hygiene devices offers niche opportunities in this region.
Africa
Africa held the smallest share of 1% in 2024, valued at USD 66.16 million. Limited awareness, weak distribution networks, and low affordability restrict market expansion. Most demand is concentrated in South Africa and Egypt, where urban populations are more exposed to oral health campaigns and branded products. The rest of Africa relies heavily on basic and low-cost devices. With a CAGR of only 1.5%, the market is projected to reach USD 77.11 million by 2032. Without targeted outreach and affordable product lines, Africa will continue to represent a minor share of the global market.
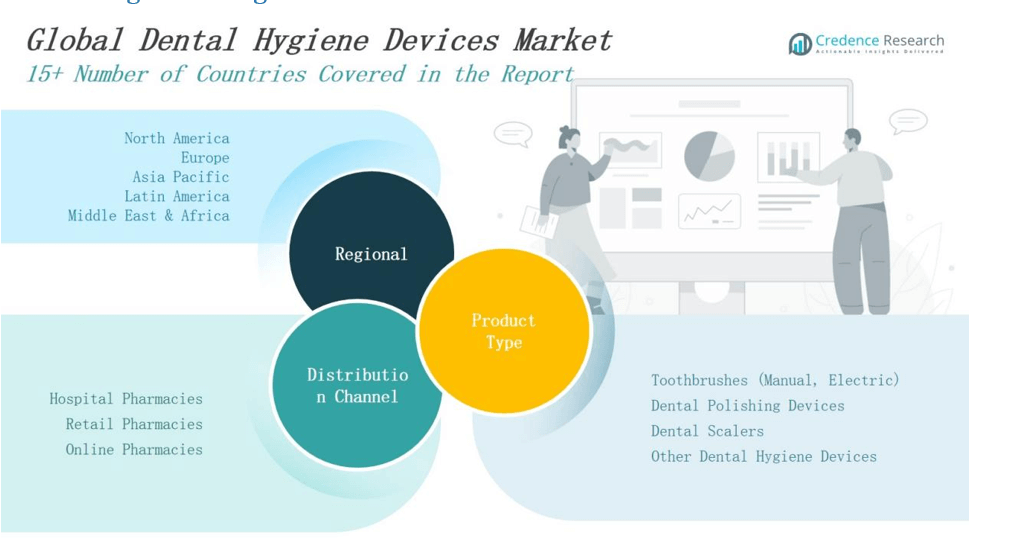
Market Segmentations:
By Product Type
- Toothbrushes
- Manual
- Electric
- Dental Polishing Devices
- Dental Scalers
- Other Dental Hygiene Devices
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The dental hygiene devices market is moderately consolidated, with a mix of global leaders and regional players competing on product innovation, brand strength, and distribution networks. Key companies such as Procter & Gamble (Oral-B), Colgate-Palmolive, Koninklijke Philips (Sonicare), and Dentsply Sirona dominate through strong portfolios of manual and electric toothbrushes, along with advanced oral irrigators and polishing devices. Panasonic and Water Pik strengthen competition with premium electric solutions, while Sunstar Suisse (GUM) and Lion Corporation focus on preventive care products tailored to Asia. Church & Dwight and Dr Fresh maintain a strong presence in affordable segments, supported by wide retail availability. Competitive strategies revolve around launching smart, eco-friendly devices, expanding e-commerce channels, and pursuing partnerships with dental professionals for brand credibility. Intense price competition from local manufacturers and counterfeit products remains a key challenge, pushing global players to emphasize quality, innovation, and consumer education to sustain long-term market leadership.
Key Players
- Dentsply Sirona
- Procter & Gamble Co. (Oral-B)
- Koninklijke Philips NV (Sonicare)
- Colgate-Palmolive Company
- Water Pik, Inc.
- Sunstar Suisse SA (GUM)
- Lion Corporation
- Church & Dwight Co., Inc.
- Panasonic Corporation
- Truly International Holdings Ltd.
- Dr Fresh, LLC
Recent Developments
- In October 2024, Royal Philips partnered with Aspen Dental, the largest branded dental clinic network in the U.S., to offer Philips Sonicare products like ExpertClean toothbrush and Cordless Power Flosser at over 1,100 locations enhancing in-office and at-home oral care.
- In January 2025, Philips introduced the Sonicare 5000–7000 series featuring adaptive brushing technology, 62,000 sonic movements per minute, and optical sensors for improved plaque removal.
- In March 2025, Solventum partnered with SprintRay to deliver same-day digital dentistry restoration solutions, following multiple product launches in 2024 including 3D-printed aligner attachments and fluoride treatments.
- In February 2025, Oral-B released the iO2 electric toothbrush in Germany, a simplified model with advanced iO technology designed to help manual brush users transition to electric brushing.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for electric toothbrushes will continue to rise with growing awareness of advanced oral care.
- Online sales channels will expand rapidly as e-commerce platforms strengthen their dental care portfolios.
- Eco-friendly and biodegradable products will gain wider acceptance among environmentally conscious consumers.
- Smart dental devices with app integration and sensors will become mainstream in developed markets.
- Emerging economies will drive growth as awareness campaigns and urbanization boost adoption.
- Preventive oral care will gain priority over corrective treatments, increasing demand for hygiene devices.
- Partnerships between dental professionals and manufacturers will shape product recommendations and consumer trust.
- Product innovation will focus on affordability to capture price-sensitive consumers in developing regions.
- Premiumization will grow in urban centers where consumers seek advanced features and better outcomes.
- Strong competition from local and private-label brands will challenge established players’ market dominance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dental Hygiene Devices Market, and what is its projected size in 2032?
Which Dental Hygiene Devices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dental Hygiene Devices Market?
Who are the major players in the Dental Hygiene Instrument Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dental Hygiene Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dental Hygiene Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,756.66 million → 2032: USD 7,394.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dental Hygiene Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dental Hygiene Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dental Hygiene Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dental Hygiene Devices Market Drivers
- 3.3 Dental Hygiene Devices Market Restraints & Challenges
- 3.4 Dental Hygiene Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dental Hygiene Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dental Hygiene Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dental Hygiene Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dental Hygiene Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dental Hygiene Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dental Hygiene Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dental Hygiene Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dental Hygiene Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dental Hygiene Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dental Hygiene Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dental Hygiene Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dental Hygiene Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dental Hygiene Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dental Hygiene Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dental Hygiene Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dental Hygiene Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dental Hygiene Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dental Hygiene Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dental Hygiene Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
