
Market Overview
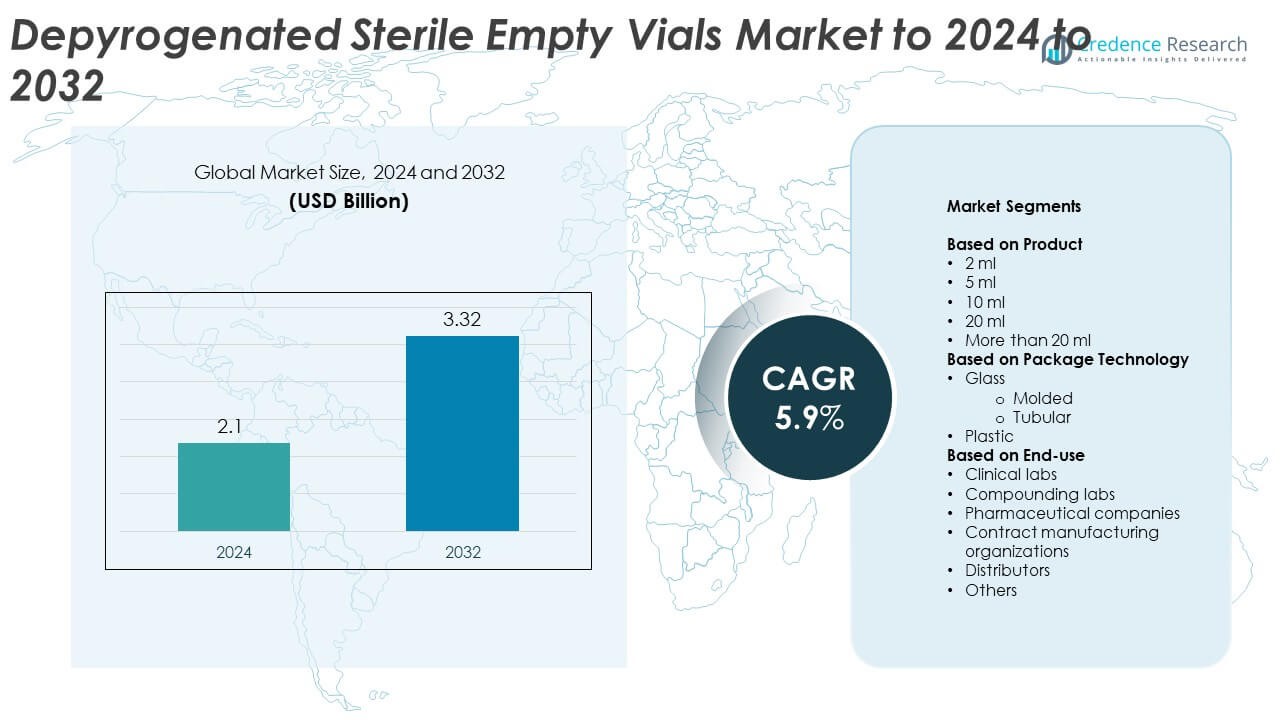
Depyrogenated Sterile Empty Vials Market size was valued at USD 2.1 billion in 2024 and is anticipated to reach USD 3.32 billion by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Depyrogenated Sterile Empty Vials Market Size 2024 | USD 2.1 Billion |
| Depyrogenated Sterile Empty Vials Market, CAGR | 5.9% |
| Depyrogenated Sterile Empty Vials Market Size 2032 | USD 3.32 Billion |
The Depyrogenated Sterile Empty Vials Market is characterized by strong competition among major players such as Gerresheimer, Thermo Fisher Scientific, SGD Pharma, Stevanato, Corning, Nipro PharmaPackaging, DWK Life Sciences, Datwyler, SCHOTT, and APG Pharma. These companies focus on expanding sterile vial production capacities, improving automation, and adopting advanced depyrogenation technologies to meet rising regulatory and quality demands. North America dominated the global market in 2024 with a 38% share, driven by a robust pharmaceutical manufacturing base, advanced biologics production, and stringent sterility standards. Europe followed with 29%, supported by expanding vaccine and biosimilar manufacturing facilities.
Market Insights
- The Depyrogenated Sterile Empty Vials Market was valued at USD 2.1 billion in 2024 and is projected to reach USD 3.32 billion by 2032, growing at a CAGR of 5.9%.
- Growing biologics, vaccines, and injectable drug production are key drivers boosting the demand for sterile and depyrogenated vials.
- The market is witnessing trends toward automation, ready-to-use vial formats, and eco-friendly packaging innovations enhancing sterility assurance.
- Competition remains strong among leading manufacturers focusing on quality, capacity expansion, and technological advancements to meet global pharmaceutical standards.
- North America dominated with a 38% share in 2024, followed by Europe with 29%, while Asia Pacific held 23%; the 10 ml vial segment led overall product demand due to its high suitability for injectables and biologics.
Market Segmentation Analysis:
By Product
The 10 ml vials segment dominated the Depyrogenated Sterile Empty Vials Market in 2024, accounting for around 34% of total revenue. These vials are widely used in injectable formulations and vaccines due to their optimal fill volume and compatibility with automated filling systems. The growing production of biologics and COVID-19 booster doses increased demand for this size. Smaller vials such as 2 ml and 5 ml are gaining traction for clinical samples, while 20 ml and larger options serve bulk drug packaging needs in contract manufacturing and hospital compounding applications.
- For instance, AstraZeneca supplies Vaxzevria in 5 mL multidose vials.
By Package Technology
Glass vials remained the dominant category, capturing approximately 78% of the market share in 2024. Within glass packaging, tubular glass vials outperformed molded variants due to their superior clarity, dimensional consistency, and resistance to thermal stress during depyrogenation. Pharmaceutical manufacturers prefer tubular vials for sterile injectable drugs and biologics requiring high purity. Plastic vials are expanding gradually, driven by their lightweight and shatter-resistant benefits. However, concerns regarding extractables and leachables limit plastic adoption in sensitive drug formulations.
- For instance, Corning and a partner launched a tubing plant sized for 13,000 tonnes a year, enough for about 2.2 billion vials annually by 2025/26.
By End-use
Pharmaceutical companies held the largest share of about 41% in the Depyrogenated Sterile Empty Vials Market in 2024. This dominance stems from large-scale vaccine production, biologics development, and stringent regulatory needs for sterile packaging. Contract manufacturing organizations (CMOs) also form a growing segment as pharma firms increasingly outsource sterile filling operations. Clinical and compounding labs contribute steadily, driven by diagnostic testing and personalized medication compounding. Distributors and other medical facilities maintain moderate demand for ready-to-fill depyrogenated vials to streamline supply chains and reduce contamination risks.
Key Growth Drivers
Rising Demand for Biologics and Vaccines
The rapid expansion of biologics, biosimilars, and vaccines has significantly boosted the need for depyrogenated sterile empty vials. These vials ensure product safety by eliminating endotoxins, which is vital for injectable formulations. Global immunization campaigns and advancements in mRNA-based therapies have further increased production volumes, particularly in developed pharmaceutical markets. Manufacturers are expanding vial sterilization capacities to meet the surge in biopharmaceutical demand, making this one of the most influential growth drivers for the market.
- For instance, Serum Institute of India reports over 1.75 billion Covishield doses administered, underscoring sustained vial demand.
Stringent Regulatory Standards for Sterility Assurance
Growing emphasis on product sterility by regulatory authorities such as the FDA and EMA has strengthened demand for depyrogenated packaging. Pharmaceutical companies are required to comply with strict endotoxin and microbial contamination limits for parenteral products. This drives investments in validated depyrogenation equipment and sterile vial production facilities. Companies prioritize validated, ready-to-use vials to reduce contamination risks and meet regulatory expectations, positioning sterility compliance as a primary growth catalyst in this market.
- For instance, SCHOTT Pharma supplies adaptiQ® RTU vials packaged to ISO 21882, the standard for sterile packaged ready-for-filling glass vials. The dimensions of this packaging are harmonized with ISO 11040-7, the standard for prefilled syringe packaging, which allows for enhanced compatibility on sterile filling lines.
Expansion of Contract Manufacturing Services
The growing outsourcing trend in pharmaceutical and biotechnology sectors supports market expansion. Contract manufacturing organizations (CMOs) increasingly adopt depyrogenated sterile vials to handle multiple client products safely and efficiently. Rising small and mid-sized biotech firms, lacking in-house sterile filling infrastructure, prefer CMOs for cost-effective and compliant production. This shift strengthens vial demand across global facilities, driving sustained market growth. The rising volume of biologics and specialty injectables magnifies this driver’s impact across regions.
Key Trends & Opportunities
Shift Toward Ready-to-Use and Pre-Sterilized Vials
Pharmaceutical firms are transitioning toward ready-to-use (RTU) depyrogenated vials to minimize contamination and reduce production time. RTU vials eliminate the need for on-site washing, depyrogenation, and sterilization processes. This approach aligns with lean manufacturing trends and improves operational efficiency. The rising adoption of isolator-based filling systems further supports this shift, as companies prioritize flexible and contamination-free vial handling solutions.
- For instance, West Pharmaceutical Services lists SCHOTT adaptiQ 10 mL RTU vials at 48 vials per nest and six tubs per carton for fast, clean changeovers.
Growing Adoption of Automation and Smart Packaging Lines
Automation in sterile packaging lines is reshaping vial production. Integration of robotic systems, automated inspection, and traceability technologies ensures quality consistency and regulatory compliance. Manufacturers are adopting digital monitoring tools to control depyrogenation and sterilization cycles more precisely. This trend improves output quality while reducing labor costs and human error, creating new opportunities for advanced vial production facilities globally.
- For instance, the Antares Vision Group's VRI-VI series of automatic visual inspection systems for small volume parenterals, including vials, can inspect various product contents, including liquids, suspensions, emulsions, and freeze-dried products. The machine is designed for 100% quality checks.
Key Challenges
High Capital Costs for Sterile Production Facilities
Establishing depyrogenated sterile vial production requires significant investment in cleanroom infrastructure, validated depyrogenation tunnels, and inspection systems. High setup and maintenance costs create barriers for small and mid-sized manufacturers. Moreover, stringent validation requirements and periodic audits increase operational expenses. These financial challenges limit new entrants and slow capacity expansion, especially in emerging markets with limited access to advanced sterilization technologies.
Supply Chain and Material Constraints
The market faces challenges due to fluctuations in high-quality borosilicate glass and pharmaceutical-grade polymer supply. Limited raw material availability, coupled with growing demand from vaccine and biologics production, causes procurement delays. Additionally, transportation restrictions and energy costs affect global vial supply consistency. Such material constraints can disrupt manufacturing schedules and hinder timely delivery to pharmaceutical clients, posing a persistent challenge for vial producers.
Regional Analysis
North America
North America held the largest share of around 38% in the Depyrogenated Sterile Empty Vials Market in 2024. The region’s strong pharmaceutical manufacturing base and high adoption of injectable biologics drive market demand. The United States leads due to its advanced sterile packaging standards, well-established regulatory framework, and expanding biologics pipeline. Major pharmaceutical and biotech companies are investing in advanced sterilization and filling technologies to ensure contamination-free drug packaging. Canada contributes steadily, supported by government funding in vaccine production and increasing adoption of pre-sterilized packaging formats in pharmaceutical operations.
Europe
Europe accounted for about 29% of the global Depyrogenated Sterile Empty Vials Market in 2024. The market benefits from growing investments in biologics, generics, and vaccine development. Germany, France, and the United Kingdom are the key contributors, supported by strong pharmaceutical R&D infrastructure and stringent quality regulations. The rising focus on sterile injectable formulations and expansion of aseptic filling lines drive regional growth. European vial manufacturers are also adopting automation and eco-friendly packaging technologies, ensuring compliance with European Medicines Agency (EMA) sterilization standards and sustainability initiatives in pharmaceutical packaging.
Asia Pacific
Asia Pacific captured nearly 23% of the Depyrogenated Sterile Empty Vials Market in 2024, driven by rapid expansion in biopharmaceutical production and clinical research. China, India, and Japan lead regional growth due to increasing vaccine output and government support for local drug manufacturing. Contract manufacturing organizations are strengthening their vial sterilization capacities to serve multinational pharmaceutical clients. Rising healthcare investments and the availability of low-cost manufacturing facilities also make the region a key outsourcing hub for sterile vial production. Demand is expected to grow further with the rising export of injectable drugs.
Latin America
Latin America represented approximately 6% of the Depyrogenated Sterile Empty Vials Market in 2024. The region is experiencing steady growth supported by improving pharmaceutical production capacities in Brazil and Mexico. Rising vaccination campaigns, expanding generic drug markets, and increasing imports of pre-sterilized vials from North America contribute to demand. Domestic manufacturers are gradually upgrading their filling and depyrogenation processes to comply with global safety standards. Despite infrastructure limitations, government-backed healthcare programs and foreign collaborations are boosting sterile packaging adoption in regional pharmaceutical and diagnostic industries.
Middle East & Africa
The Middle East & Africa accounted for about 4% of the global Depyrogenated Sterile Empty Vials Market in 2024. The market is growing as healthcare infrastructure and local pharmaceutical production improve across the Gulf countries and South Africa. Rising imports of sterile vials and vaccines, coupled with government investments in healthcare manufacturing, support steady expansion. The United Arab Emirates and Saudi Arabia are emerging as key distribution hubs. However, limited local manufacturing and high dependency on imported raw materials continue to constrain large-scale production within the region.
Market Segmentations:
By Product
- 2 ml
- 5 ml
- 10 ml
- 20 ml
- More than 20 ml
By Package Technology
- Glass
- Molded
- Tubular
- Plastic
By End-use
- Clinical labs
- Compounding labs
- Pharmaceutical companies
- Contract manufacturing organizations
- Distributors
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Depyrogenated Sterile Empty Vials Market is highly competitive, with major players such as Gerresheimer, Thermo Fisher Scientific, SGD Pharma, Stevanato, Corning, Nipro PharmaPackaging, DWK Life Sciences, Datwyler, SCHOTT, and APG Pharma leading the landscape. These companies focus on expanding sterile vial manufacturing capacities, enhancing automation, and integrating advanced depyrogenation technologies to meet rising pharmaceutical standards. Strategic collaborations with biotech and pharmaceutical firms help strengthen global supply chains and ensure compliance with stringent regulatory norms. Manufacturers are also investing in research to improve vial durability, thermal stability, and contamination resistance. Growing demand for ready-to-use and pre-sterilized vials has encouraged the development of innovative packaging solutions with traceability features. Regional players are entering partnerships and adopting flexible manufacturing models to serve evolving market needs efficiently. Overall, competition centers on quality assurance, technological advancement, and large-scale production capabilities to meet the increasing demand for sterile packaging solutions.
Key Player Analysis
- Gerresheimer
- Thermo Fisher Scientific
- SGD Pharma
- Stevanato
- Corning
- Nipro PharmaPackaging
- DWK Life Sciences
- Datwyler
- SCHOTT
- APG Pharma
Recent Developments
- In 2025, Stevanato Group introduced a new line of depyrogenated nested vials that are compatible with robotic aseptic filling systems.
- In 2024, Gerresheimer introduced a new line of eco-friendly, depyrogenated vials to enhance sustainability efforts in the pharmaceutical supply chain
- In 2023, Datwyler introduced Ready-for-Sterilization (RFS) Combiseals, which are compatible with RTU filling operations.
Report Coverage
The research report offers an in-depth analysis based on Product, Package Technology, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for ready-to-use depyrogenated vials will rise due to sterile filling efficiency.
- Biologic and vaccine expansion will continue driving large-scale sterile vial production.
- Automation in depyrogenation and inspection systems will enhance process reliability.
- Contract manufacturing organizations will strengthen their sterile packaging capacities.
- Use of eco-friendly and lightweight vial materials will gain industry attention.
- Advanced glass formulations will improve durability and contamination resistance.
- Pharmaceutical firms will adopt digital tracking for vial sterilization validation.
- Regional manufacturers in Asia Pacific will expand exports to global clients.
- Collaborations between vial makers and pharma companies will increase supply resilience.
- Innovation in pre-sterilized vial packaging formats will boost market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Depyrogenated Sterile Empty Vials Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Depyrogenated Sterile Empty Vials Market projected to grow between 2025 and 2032?
Which Depyrogenated Sterile Empty Vials Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Depyrogenated Sterile Empty Vials Market?
Who are the leading companies in the Depyrogenated Sterile Empty Vials Market?
Which region commanded the largest share of the Depyrogenated Sterile Empty Vials Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.1 billion → 2032: USD 3.32 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Depyrogenated Sterile Empty Vials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Depyrogenated Sterile Empty Vials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Depyrogenated Sterile Empty Vials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Depyrogenated Sterile Empty Vials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Depyrogenated Sterile Empty Vials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Depyrogenated Sterile Empty Vials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Depyrogenated Sterile Empty Vials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Depyrogenated Sterile Empty Vials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.1 billion → 2032: USD 3.32 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Depyrogenated Sterile Empty Vials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Depyrogenated Sterile Empty Vials Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Depyrogenated Sterile Empty Vials Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Depyrogenated Sterile Empty Vials Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

