
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Dental Services Market Size 2024 | USD 381621.5 million |
| Dental Services Market, CAGR | 6.5% |
| Dental Services Market Size 2032 | USD 631581.93 million |
Market Overview:
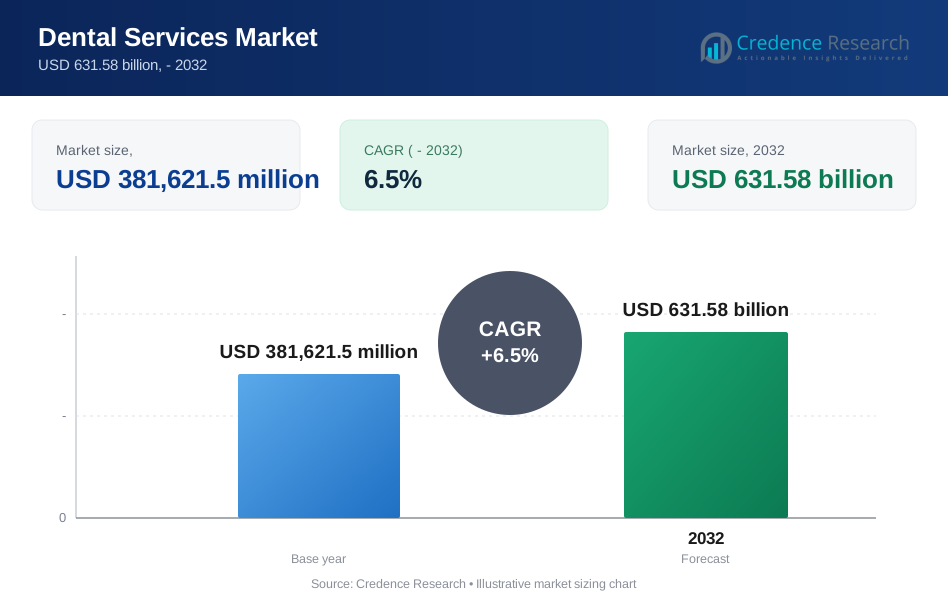
The Dental Services Market is projected to grow from USD 381621.5 million in 2024 to an estimated USD 631581.93 million by 2032, with a compound annual growth rate (CAGR) of 6.5% from 2024 to 2032.
The market's growth drivers are multifaceted and rooted in a variety of factors. A significant driver is the increasing prevalence of dental disorders, including periodontal disease, tooth decay, and oral cancers, which collectively elevate the demand for a wide range of dental services. Technological advancements in dental care have transformed treatment procedures, with innovations like 3D printing, CAD/CAM systems, and laser dentistry improving the precision, speed, and effectiveness of dental treatments. This technological evolution has led to better patient outcomes and reduced chair-time, thereby enhancing patient satisfaction. Rising disposable incomes and changing lifestyles have also contributed to the surge in demand for cosmetic dental procedures, such as teeth whitening, veneers, and orthodontics, as consumers seek aesthetic enhancements. Furthermore, governmental initiatives and awareness campaigns focused on promoting oral health, combined with supportive insurance schemes and reimbursement options, have encouraged greater patient engagement and routine dental checkups, contributing to market expansion.
Regionally, North America holds a dominant share of the dental services market, driven by a well-established healthcare infrastructure, high oral health awareness, and a strong presence of key market players. The United States leads in dental expenditure, supported by comprehensive insurance coverage and rapid adoption of cutting-edge dental procedures and technologies. Europe follows closely, characterized by a network of highly specialized dental clinics and practitioners, as well as a strong focus on both preventive and aesthetic dental care. The Asia-Pacific region, however, is projected to witness the highest CAGR during the forecast period due to rising healthcare investments, expanding middle-class populations, and increased emphasis on oral health awareness. Countries such as China, India, and Japan are at the forefront of this growth, driven by a surge in demand for advanced dental treatments and government-backed oral health campaigns.
Market Drivers:
Rising Prevalence of Dental Disorders and Aging Population:
One of the primary drivers of the dental services market is the increasing prevalence of dental disorders worldwide. Conditions such as periodontal disease, dental caries, and oral cancers are becoming more common due to changing lifestyles, dietary habits, and inadequate oral hygiene practices in various regions. For example, the World Health Organization (WHO) reported that nearly 3.5 billion people are affected by oral diseases globally, indicating a significant public health challenge. As awareness about oral health grows, there is a significant increase in patient visits to dental clinics for preventive care and treatments. Furthermore, the global aging population has a considerable impact on the demand for dental services. According to the American Dental Association (ADA), older individuals often require specialized dental treatments, such as dentures, implants, and periodontic care, making geriatric dentistry a critical segment within the market.
Technological Advancements in Dental Care:
Technological advancements in dentistry have transformed how dental services are delivered and have significantly boosted market growth. Innovations like computer-aided design and computer-aided manufacturing (CAD/CAM) systems, digital X-rays, 3D printing, and laser dentistry have enhanced the accuracy and efficiency of dental procedures. These technologies improve diagnostic capabilities, reduce procedure times, and enable more personalized treatment plans, enhancing patient outcomes and satisfaction. Minimally invasive procedures facilitated by these technologies have also become more popular, encouraging patients who were previously hesitant about dental care to seek treatment. The integration of artificial intelligence (AI) in diagnostics and patient management is further revolutionizing the market, providing data-driven insights to improve patient care and operational efficiencies.
Growing Demand for Cosmetic and Aesthetic Dentistry:
Another key driver of the dental services market is the growing demand for cosmetic and aesthetic dentistry. As people become more conscious of their appearance and seek to enhance their smiles, there has been a surge in demand for procedures such as teeth whitening, veneers, braces, and aligners. Social media influence and the desire for aesthetic appeal have led to increased consumer spending on these elective procedures. Additionally, advancements in cosmetic dental materials and techniques, such as the use of translucent braces and natural-looking veneers, have further attracted patients. This rise in cosmetic dentistry is also fueled by improved economic conditions and increasing disposable incomes, making these services more accessible to a broader demographic.
Government Initiatives and Supportive Reimbursement Policies:
Government initiatives and supportive reimbursement policies aimed at promoting oral health have played a pivotal role in driving market growth. In many countries, public health campaigns emphasize the importance of preventive care; for instance, the Centers for Disease Control and Prevention (CDC) has launched initiatives to improve access to dental care among underserved populations. Governments have invested in providing access to dental care in underserved areas; for instance, according to the Health Resources & Services Administration (HRSA), over 60 million people live in areas with shortages of dental professionals. Additionally, the expansion of insurance coverage for dental procedures has reduced out-of-pocket expenses for patients, encouraging more individuals to seek regular dental care. As healthcare policies continue to prioritize oral health, the dental services market is expected to see sustained growth in the coming years.
Market Trends:
Growing Adoption of Teledentistry and Digital Solutions:
The dental services market is witnessing a marked increase in the adoption of teledentistry and digital solutions, a trend that has gained traction particularly since the COVID-19 pandemic. Teledentistry enables remote consultations and follow-ups, offering a convenient and accessible option for patients. This digital transformation has allowed dentists to provide consultations, diagnose minor conditions, and monitor post-treatment progress from a distance, improving patient engagement and accessibility to dental care, especially in rural or underserved regions. Moreover, the incorporation of advanced digital tools, such as electronic health records (EHR) and artificial intelligence-driven diagnostic aids, is streamlining clinical workflows and enhancing decision-making in dental practices.
Rise of Minimally Invasive and Painless Procedures:
Minimally invasive and painless dental procedures are gaining significant traction within the market, driven by patient preferences for more comfortable and less anxiety-inducing experiences. Advances in laser dentistry, air abrasion, and biologically compatible materials have made it possible for dentists to perform precise, minimally invasive procedures with less discomfort and faster recovery times. For instance, dental lasers have shown success rates ranging from 80% to 95% over 5 to 10 years. This trend has led to greater patient satisfaction and increased willingness to undergo dental treatments, thereby boosting overall demand for dental services. Additionally, painless procedures have played a crucial role in alleviating dental anxiety, which has historically deterred many patients from seeking timely care.
Increased Focus on Preventive Dental Care:
There is a noticeable shift in the dental services market towards preventive care as healthcare providers and patients alike recognize the long-term benefits of maintaining oral health. Regular checkups, cleanings, fluoride treatments, and sealants are becoming more popular as people seek to prevent costly and invasive dental procedures down the line. This trend has been further supported by educational campaigns and initiatives from public health organizations emphasizing the importance of oral hygiene. Preventive care programs offered by dental insurance providers have also encouraged patients to adopt regular checkup habits, ensuring sustained demand for routine dental visits and procedures.
Expansion of Dental Tourism in Emerging Markets:
Dental tourism has emerged as a significant trend in the market, driven by cost-effective treatments and shorter wait times in countries known for their high-quality dental care. Patients from regions such as North America and Western Europe increasingly travel to destinations in Asia, Latin America, and Eastern Europe to receive dental procedures at a fraction of the cost. For example, Mexico accounts for 25% of all dental tourists globally. These countries have invested heavily in state-of-the-art facilities and well-trained professionals to cater to international patients. The growing popularity of dental tourism is not only reshaping the competitive landscape but also contributing to the overall expansion of the global dental services market, with a focus on delivering comprehensive and value-based care for cost-conscious consumers.
Market Restraints and Challenges:
High Costs of Dental Procedures:
One of the major restraints facing the dental services market is the high cost associated with many dental procedures. Complex procedures such as implants, orthodontic treatments, and cosmetic surgeries often involve substantial expenses, which can deter patients without sufficient insurance coverage. The cost barrier is further exacerbated in regions with limited public healthcare funding for dental services, making affordability a pressing challenge for many patients. For uninsured or underinsured populations, the out-of-pocket expense can be prohibitive, limiting access to necessary care and contributing to health disparities in oral health outcomes.
Limited Access in Rural and Underserved Areas:
Access to dental services remains a significant challenge in rural and underserved regions, where there is often a shortage of dental professionals and infrastructure. This geographic disparity limits the availability of timely care, resulting in unmet needs and delayed treatments. In many developing countries, low-income populations face limited access to basic and preventive dental care, which can lead to more severe oral health issues over time. This lack of equitable access not only restrains market growth but also highlights the need for targeted initiatives to bridge the gap in dental service availability.
Regulatory Challenges and Compliance Requirements:
The dental services market operates under stringent regulations and compliance requirements that vary across different regions. Meeting these standards, which include safety protocols, infection control measures, and professional licensing requirements, can be both complex and costly for dental practices. The constant need to adhere to evolving regulations may limit market entry for new players and increase operational burdens on existing practices. Additionally, regulatory complexities in cross-border dental tourism markets further complicate operations, creating compliance-related hurdles that can impact service offerings and growth opportunities.
Patient Anxiety and Perception Issues:
Dental anxiety and negative perceptions about dental visits continue to pose challenges in the market. Many patients delay or avoid treatment due to fear or unpleasant past experiences, which reduces the frequency of preventive care visits and hinders timely intervention. While advances in painless procedures are helping address this issue, overcoming deeply rooted anxieties remains a long-term challenge for the industry. Addressing patient perceptions through effective communication, patient education, and modern treatment approaches is crucial for improving service adoption rates.
Market Segmentation Analysis:
The dental services market is segmented by procedure, service, gender, and end user.
By procedure, the market is divided into cosmetic and non-cosmetic dentistry. Cosmetic dentistry, including teeth whitening, veneers, and smile makeovers, is experiencing robust demand due to growing aesthetic awareness. Non-cosmetic dentistry focuses on essential treatments like restorative and preventive care, which continue to account for a significant share of the market.
By service, the market includes dental implants, orthodontics, periodontics, root canal (endodontics), laser dentistry, dentures, oral and maxillofacial surgery, and smile makeovers, among others. Dental implants and orthodontics hold considerable market shares due to the rising prevalence of tooth loss and malocclusions. Cosmetic dentistry services, such as veneers and teeth whitening, remain highly sought after, driven by aesthetic concerns. Periodontics and endodontics continue to grow as the demand for complex dental treatments rises. Laser dentistry is also gaining traction, offering minimally invasive options for various procedures.
By gender, the market is segmented into male and female populations. Women often seek aesthetic dental services more frequently than men, driving demand for cosmetic procedures. However, essential treatments and preventive care services are widely adopted across both genders.
By end user, dental clinics account for a dominant share due to their accessibility, specialization, and advanced treatment options. Hospitals also play a significant role, especially for complex oral surgeries and multidisciplinary treatments, with their comprehensive infrastructure enhancing service availability.
Segmentation:
By Procedure
- Cosmetic Dentistry
- Non-Cosmetic Dentistry
By Service
- Dental Implants
- Orthodontics
- Periodontics
- Root Canal - Endodontics
- Cosmetic Dentistry
- Laser Dentistry
- Dentures
- Oral and Maxillofacial Surgery
- Smile Makeover
- Others
By Gender
- Male
- Female
By End User
- Dental Clinics
- Hospitals
Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds a prominent share of the global dental services market, accounting for a significant portion of market revenue. In 2023, it was estimated that the region contributed approximately 35% of the market share. The United States leads in this region, driven by a well-established healthcare system, high awareness of oral health, and a robust insurance structure covering dental procedures. The adoption of cutting-edge technologies such as CAD/CAM systems and 3D printing further bolsters the demand for dental services in North America. Preventive and cosmetic dentistry are major growth segments, fueled by strong consumer demand and aesthetic preferences.
Europe represents another key region in the global dental services market, accounting for around 25% of the total market share. The region benefits from a dense network of highly qualified dental practitioners and state-of-the-art facilities. Countries such as Germany, the United Kingdom, and France have strong oral healthcare infrastructure, with a focus on preventive and restorative services. Dental tourism also contributes to the European market, as patients from neighboring regions seek high-quality care at more affordable rates compared to their home countries. Moreover, rising awareness campaigns around oral health and supportive reimbursement policies have positively impacted market growth.
The Asia-Pacific region is expected to experience the fastest growth over the forecast period and currently accounts for roughly 20% of the market share. Increasing disposable incomes, a growing middle-class population, and heightened awareness about oral health are key factors driving growth. Countries like China, India, and Japan are at the forefront of this expansion, with government-backed initiatives to promote oral health and increased investments in healthcare infrastructure. The demand for cosmetic dentistry, orthodontics, and implants is rising rapidly in the region, reflecting the changing consumer preferences for enhanced aesthetic appeal.
Latin America and the Middle East & Africa represent smaller portions of the global market, with shares of approximately 10% and 10%, respectively. Latin America’s market is driven by the growing popularity of dental tourism, particularly in countries like Mexico and Brazil, which offer high-quality care at lower costs. Meanwhile, the Middle East & Africa region is experiencing growth driven by rising healthcare investments, increasing oral health awareness, and efforts to improve dental care accessibility in urban and rural areas. However, challenges such as limited access to advanced facilities and uneven healthcare coverage remain constraints to the market's growth in these regions.
Key Player Analysis:
- Abano Healthcare Group Limited
- Apollo White Dental
- Aspen Dental Management Inc.
- Axis Dental
- Coast Dental
- Dental Service Group
- Gentle Dental of New England
- Integrated Dental Holdings
- InterDent, Inc.
- National Health Service England
- Pacific Dental Service
- The British United Provident Association Limited
Competitive Analysis:
The dental services market is highly competitive, characterized by a mix of private practices, specialized dental clinics, and hospitals offering a wide range of treatments. Major market players focus on technological advancements, such as digital dentistry and minimally invasive procedures, to differentiate their services and attract patients. Consolidation is occurring through mergers and acquisitions as large dental service organizations (DSOs) expand their networks to offer integrated care solutions and capitalize on economies of scale. Prominent players in the market include Aspen Dental, Dental Care Alliance, and Smile Brands, which continue to grow through strategic partnerships and service diversification. Smaller, specialized clinics remain competitive by offering niche treatments, such as cosmetic or pediatric dentistry. The market’s competitive dynamics are also influenced by technological innovations and consumer demand for enhanced, personalized, and convenient dental care, driving players to innovate and refine service delivery models.
Recent Developments:
- In April 2024, Smartee launched its new S8 clear aligners designed to correct severe cases of Class II malocclusion.
- In April 2024, the dental clinic chain MDC Asia Link Bhd partnered with UCrest Bhd to digitize UCrest’s dental clinic operations using Internet of Medical Things (IoMT) and artificial intelligence (AI) via iMedic platforms.
- In April 2024, Espire Dental, a rapidly growing, elite multi-specialty group practice, announced the acquisition of Gregory S. Hulings, DDS, expanding its presence with a new practice in Texas.
Market Concentration & Characteristics:
The dental services market is fragmented, with numerous players, including private practitioners, dental service organizations (DSOs), clinics, and hospitals. While independent practitioners and small clinics dominate local markets, large DSOs and corporate chains are gaining market share due to their ability to offer integrated care solutions, access advanced technology, and achieve operational efficiencies. Market consolidation is increasing, as major players seek growth through acquisitions and partnerships, particularly in urban areas with high demand for specialized care. The market is characterized by strong consumer demand for technologically advanced, minimally invasive, and cosmetic procedures, driving continuous innovation among service providers. Personalized care and patient convenience remain central to competitiveness, encouraging providers to invest in digital solutions, such as teledentistry and AI-driven diagnostics. Regulatory compliance and high service standards further influence market dynamics, shaping competitive differentiation strategies and growth opportunities.
Report Coverage:
The research report offers an in-depth analysis based on By Procedure, By Service, By Gender and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for cosmetic dentistry will drive market growth as more consumers seek aesthetic enhancements.
- Technological advancements, such as AI-driven diagnostics and 3D printing, will enhance service accuracy and patient outcomes.
- Expansion of teledentistry and digital solutions will improve accessibility and convenience for patients, especially in remote areas.
- Increasing prevalence of dental disorders will sustain demand for preventive and restorative services.
- Aging populations worldwide will elevate the need for geriatric dental care, including implants and dentures.
- Dental tourism will continue to grow, fueled by cost-effective, high-quality treatments in emerging markets.
- Minimally invasive and pain-free procedures will attract more patients, reducing dental anxiety barriers.
- Government initiatives and supportive policies will encourage greater oral health awareness and market penetration.
- Consolidation through mergers and acquisitions will create larger, integrated networks and competitive advantages.
- Continued investments in digital innovations will reshape service delivery models and boost patient engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Dental Disorders and Aging Population
The rising incidence of dental diseases such as periodontal disease, tooth decay, and oral cancers, combined with a growing elderly population that requires specialized dental care, is significantly boosting demand for dental services globally.
Technological Advancements in Dental Care
Innovations like 3D printing, CAD/CAM systems, and laser dentistry are improving the precision, speed, and effectiveness of dental treatments, leading to better patient outcomes and greater adoption of advanced dental procedures.
Growing Demand for Cosmetic and Aesthetic Dentistry
Changing lifestyles, higher disposable incomes, and increased aesthetic awareness are driving more consumers to seek cosmetic dental procedures such as teeth whitening, veneers, and orthodontics, expanding the market for elective dental services.
Government Initiatives and Supportive Reimbursement Policies
Public health campaigns, expanded insurance coverage, and government investments in oral health are making dental care more accessible and affordable, encouraging routine checkups and preventive care across broader populations.
Expansion of Teledentistry and Digital Solutions
The adoption of teledentistry and digital health tools is improving access to dental consultations and follow-ups, particularly in underserved and remote areas, thereby expanding the reach and convenience of dental services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the dental services market?
What will be the market size of the dental services market by 2032?
What are the key drivers of growth in this market?
4Which region is expected to see the highest growth rate?
What are the challenges facing the dental services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Gender
- 1.2.1 Male
- 1.2.2 Female
- 1.3 By Service
- 1.3.1 Dental Implants
- 1.3.2 Orthodontics
- 1.3.3 Periodontics
- 1.3.4 Root Canal - Endodontics
- 1.3.5 Laser Dentistry
- 1.3.6 Dentures
- 1.3.7 Oral and Maxillofacial Surgery
- 1.3.8 Smile Makeover
- 1.3.9 Others
- 1.4 By End User
- 1.4.1 Dental Clinics
- 1.4.2 Hospitals
- 1.5 By Procedure
- 1.5.1 Cosmetic Dentistry
- 1.5.2 Non-Cosmetic Dentistry
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 381,621.5 million → 2032: USD 631.58 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dental Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dental Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Dental Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Dental Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dental Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dental Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dental Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dental Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 381,621.5 million → 2032: USD 631.58 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dental Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Gender - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Male
- 12.3.6.2 Female
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Dental Implants
- 12.4.6.2 Orthodontics
- 12.4.6.3 Periodontics
- 12.4.6.4 Root Canal - Endodontics
- 12.4.6.5 Laser Dentistry
- 12.4.6.6 Dentures
- 12.4.6.7 Oral and Maxillofacial Surgery
- 12.4.6.8 Smile Makeover
- 12.4.6.9 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Dental Clinics
- 12.5.6.2 Hospitals
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Procedure - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Cosmetic Dentistry
- 12.6.6.2 Non-Cosmetic Dentistry
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dental Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dental Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dental Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dental Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aspen Dental Management Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Pacific Dental Services
- 18.4 Abano Healthcare Group Limited
- 18.5 Apollo White Dental
- 18.6 InterDent, Inc.
- 18.7 Gentle Dental of New England
- 18.8 Integrated Dental Holdings
- 18.9 Coast Dental
- 18.10 Dental Service Group
- 18.11 The British United Provident Association Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

