
Market Overview:
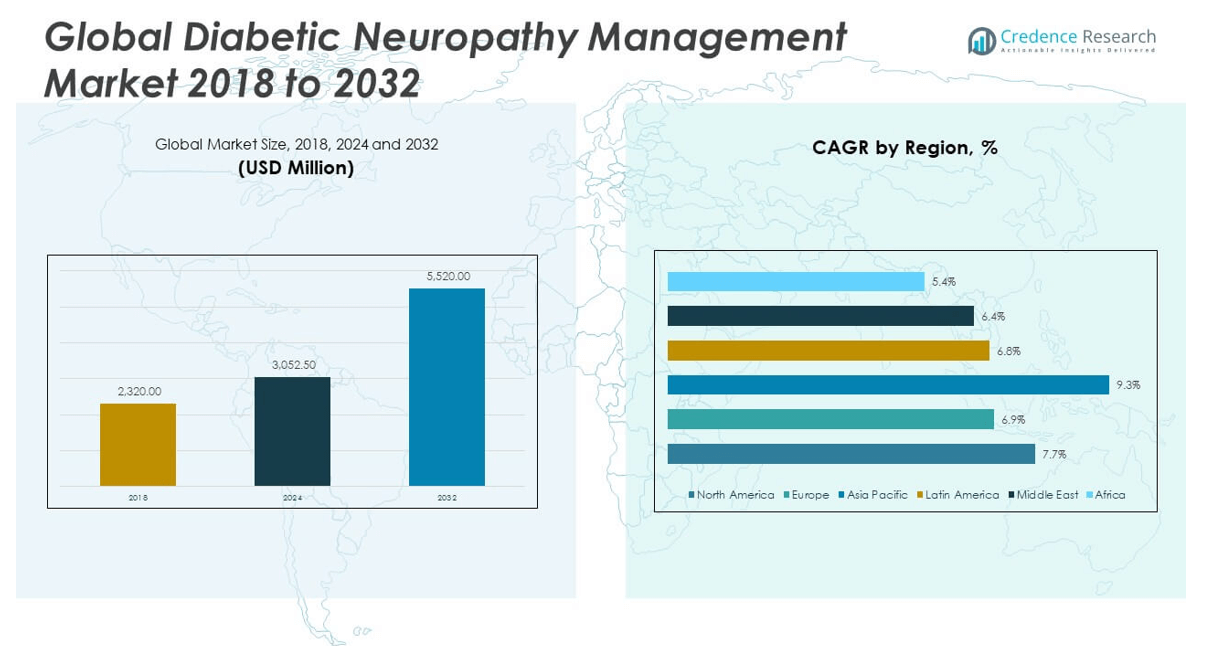
The Global Diabetic Neuropathy Management Market size was valued at USD 2,320.00 million in 2018 to USD 3,052.50 million in 2024 and is anticipated to reach USD 5,520.00 million by 2032, at a CAGR of 7.72% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Diabetic Neuropathy Management Market Size 2024 | USD 3,052.50 million |
| Diabetic Neuropathy Management Market, CAGR | 7.72% |
| Diabetic Neuropathy Management Market Size 2032 | USD 5,520.00 million |
The market is driven by the rising global prevalence of diabetes and growing awareness of diabetic complications such as neuropathy. Healthcare providers are increasingly emphasizing early diagnosis and pain management, while technological advancements in drug delivery systems and diagnostics enhance treatment outcomes. The shift toward personalized medicine and the development of targeted therapies also contribute to market expansion. Furthermore, strong support from government initiatives, coupled with increasing investment in R&D by pharmaceutical companies, encourages the introduction of novel therapeutics and management devices tailored to diabetic neuropathy.
North America leads the diabetic neuropathy management market, supported by high healthcare spending, advanced diagnostic infrastructure, and a large diabetic population. Europe follows closely due to its strong regulatory support and focus on diabetes care. The Asia Pacific region is emerging rapidly, driven by the growing burden of diabetes in countries like India and China, improved healthcare access, and rising awareness. Latin America and the Middle East & Africa show moderate growth potential, supported by expanding healthcare infrastructure and gradual adoption of diabetic care practices across urban populations.
Market Insights:
- The Global Diabetic Neuropathy Management Market was valued at USD 3,052.50 million in 2024 and is projected to reach USD 5,520.00 million by 2032, growing at a CAGR of 7.72%.
- Rising diabetes incidence, particularly among aging and urban populations, is driving increased demand for neuropathy diagnosis and treatment.
- Advancements in non-opioid pain management therapies are improving patient outcomes and expanding treatment options.
- Limited awareness and underdiagnosis in low- and middle-income regions hinder early intervention and market penetration.
- North America leads the market with 43% share, supported by advanced healthcare infrastructure and strong reimbursement systems.
- Asia Pacific is the fastest-growing region due to expanding diabetic population, healthcare access, and government-led chronic care initiatives.
- Europe holds a strong position with integrated care models and public health frameworks focused on chronic disease management.
Market Drivers:
Rising Diabetes Prevalence Across Aging and Urban Populations Fuels Therapeutic Demand:
The increasing global burden of diabetes significantly drives the Global Diabetic Neuropathy Management Market. Aging populations and sedentary urban lifestyles contribute to the rising incidence of type 2 diabetes. Early onset of diabetes in younger populations elevates lifetime risk for neuropathy complications. Healthcare systems in developed countries focus on managing chronic complications, with neuropathy receiving increased clinical attention. Pharmaceutical firms invest heavily in pain relief and nerve regeneration therapies. Early diagnosis and proactive disease monitoring gain traction with better screening protocols. Governments promote awareness campaigns to reduce diabetic complications. These dynamics directly boost the need for targeted neuropathy treatment solutions.
- For instance, Pfizer’s Lyrica (pregabalin) achieved FDA approval for diabetic peripheral neuropathic pain and has since reached over 15 million prescriptions in the United States, reflecting broad clinical adoption for neuropathy symptom control.
Expanding Healthcare Access and Reimbursement Structures Encourage Treatment Uptake:
Access to healthcare has improved in low- and middle-income regions, enabling more patients to seek diagnosis and management for diabetic neuropathy. Public health programs and insurance schemes in Asia Pacific and Latin America now include chronic disease management. Reimbursement policies in North America and Europe increasingly cover neuropathy medications and diagnostic procedures. The Global Diabetic Neuropathy Management Market benefits from consistent inclusion of branded and generic therapies in formularies. Patients are more likely to adhere to prescribed treatments when out-of-pocket costs decline. Governments and insurers recognize the long-term cost savings of early neuropathy treatment. Policy frameworks continue evolving to support integrated diabetic care. These shifts make management solutions more accessible and financially viable.
Ongoing Drug Development for Neuropathic Pain Targets Underlying Disease Mechanisms:
Pharmaceutical innovation plays a key role in strengthening the Global Diabetic Neuropathy Management Market. Companies develop therapies that not only alleviate pain but also modify nerve damage progression. Novel mechanisms, including sodium channel blockers and nerve growth factor inhibitors, enter advanced clinical stages. Regulatory agencies grant fast-track designations for promising therapies. Strong industry pipelines reflect growing demand for treatments with better efficacy and fewer side effects. Partnerships between biotech firms and academic institutions accelerate discovery. Neuromodulation technologies and combination therapies add diversity to treatment strategies. These advancements position the market for strong therapeutic expansion over the next decade.
Increased Diagnostic Capabilities and Technological Integration Elevate Disease Management:
Improved diagnostic tools enhance identification and classification of diabetic neuropathy. Point-of-care devices and nerve conduction studies become more prevalent in primary care. The Global Diabetic Neuropathy Management Market gains from early-stage detection, allowing for timely intervention. Artificial intelligence supports risk stratification and monitoring through electronic health records. Integration of wearable sensors enables real-time symptom tracking. Telemedicine platforms provide remote access to specialists, increasing diagnosis in underserved regions. Health systems adopt digital tools to coordinate multidisciplinary care. The convergence of diagnostics and digital health strengthens comprehensive disease management protocols.
Market Trends
Integration of Digital Health Platforms Reshapes Patient Monitoring and Treatment Compliance:
The Global Diabetic Neuropathy Management Market is witnessing a surge in digital health integration across patient care pathways. Wearable devices track symptoms such as pain levels and sleep disturbances. Mobile health apps support medication reminders and facilitate symptom diaries. Providers utilize real-time data to optimize treatment decisions and follow-ups. Remote monitoring tools reduce the need for frequent in-person visits. AI algorithms identify treatment noncompliance and flag patients for early intervention. Health IT systems streamline communication between primary physicians and specialists. Digital platforms increase accessibility in remote and rural areas. These digital trends enhance outcomes and reduce healthcare system burden.
- For instance, Medtronic’s Guardian Connect system demonstrated 98.5% data transmission reliability in real-world studies, and reduced unscheduled clinic visits among monitored type 2 diabetes patients by 42% over 12 months.
Shift Toward Non-Opioid Neuropathic Pain Management Gains Regulatory and Clinical Support:
Global trends indicate a decisive movement toward non-opioid-based pain relief in diabetic neuropathy. Physicians prefer prescribing medications with minimal dependency risk. The Global Diabetic Neuropathy Management Market reflects this change with rising uptake of antidepressants, anticonvulsants, and topical agents. Clinical guidelines emphasize safer long-term options over conventional opioids. Public health initiatives discourage opioid usage, encouraging adoption of alternative therapies. Innovation in cannabinoids and capsaicin-based formulations opens new frontiers. Regulatory agencies prioritize approval pathways for low-abuse potential drugs. Hospitals integrate pain management specialists into diabetes care teams. This trend reshapes the competitive landscape for pharmaceutical developers.
- For instance, in 2022, Grünenthal’s Qutenza (capsaicin 8% patch) received expanded FDA labeling for diabetic peripheral neuropathic pain, and post-approval surveillance reports documented over 100,000 patients treated with zero identified cases of abuse or dependence.
Growing Use of Personalized and Pharmacogenomic-Based Treatment Regimens:
The move toward precision medicine transforms the diabetic neuropathy treatment paradigm. Clinicians increasingly tailor therapies based on genetic and metabolic profiles. The Global Diabetic Neuropathy Management Market adopts pharmacogenomic insights to optimize dosage and drug selection. Biomarkers predict patient response to various medications, improving efficacy and minimizing adverse effects. Biobanks and clinical databases support large-scale research in this domain. Personalized care strategies improve patient satisfaction and long-term outcomes. Diagnostic labs offer advanced panels for nerve-related genetic variants. Pharmaceutical pipelines include biomarker-driven trials for better market fit. Precision medicine advances redefine treatment customization.
Integration of Rehabilitation and Multidisciplinary Pain Clinics in Standard Care Models:
Healthcare systems incorporate physical therapy, occupational therapy, and psychological counseling into neuropathy care pathways. Multidisciplinary pain clinics address complex cases of diabetic neuropathy. The Global Diabetic Neuropathy Management Market aligns with this trend by supporting holistic care solutions. Hospitals form dedicated neuropathy clinics combining neurologists, pain specialists, and endocrinologists. These clinics improve patient quality of life beyond pharmacological approaches. Rehabilitation centers offer targeted exercises to preserve nerve function and mobility. Psychological interventions address depression and anxiety linked to chronic pain. Health insurers recognize value-based care from multidisciplinary models. This trend reinforces whole-person treatment frameworks.
Market Challenges Analysis:
Limited Disease Awareness and Underdiagnosis Delay Timely Intervention in Emerging Economies:
Despite growing diabetes prevalence, limited awareness about diabetic neuropathy persists in several developing regions. Patients often normalize symptoms like numbness or tingling and delay seeking medical advice. The Global Diabetic Neuropathy Management Market faces constraints in areas where screening infrastructure is weak. General practitioners may lack training in early neuropathy identification, leading to misdiagnosis or undertreatment. Low-income patients often prioritize acute health needs over chronic condition management. Educational outreach remains inconsistent across rural and peri-urban zones. Cultural stigma surrounding neurological conditions also hinders proactive care. These factors restrict early detection, contributing to disease progression and poor quality of life.
Regulatory Complexities and Drug Approval Delays Slow Therapeutic Advancement:
Therapies targeting diabetic neuropathy must meet stringent efficacy and safety standards across global markets. Regulatory agencies demand extensive clinical validation, especially for pain-modifying drugs. The Global Diabetic Neuropathy Management Market encounters delays due to trial complexities and high placebo response rates in pain studies. Pharmaceutical firms face challenges navigating country-specific approval processes. Inconsistent international guidelines complicate global commercialization strategies. Smaller biotech companies struggle with funding long-term trials. Post-marketing surveillance requirements further delay widespread adoption. These regulatory and commercial hurdles create barriers to innovation and timely patient access to advanced therapies.
Market Opportunities:
Emerging Healthcare Infrastructure and Rising Diabetes Awareness in Asia Pacific and Latin America:
The Global Diabetic Neuropathy Management Market sees strong opportunities in emerging regions with growing diabetic populations. Healthcare infrastructure expansion in countries like India, Brazil, and Indonesia supports broader access to diagnostics and treatment. Governments run awareness programs targeting diabetes complications. Pharmaceutical companies enter these markets with localized manufacturing and distribution. Public-private partnerships enhance affordability and rural outreach. These dynamics create substantial long-term growth prospects for neuropathy-focused solutions.
Strategic Collaborations and Pipeline Diversification Expand Innovation Scope:
Biopharma collaborations, academic partnerships, and licensing agreements drive innovation in the Global Diabetic Neuropathy Management Market. Companies diversify their R&D pipelines with novel targets and delivery mechanisms. Investment in combination therapies and regenerative approaches widens market potential. Cross-border research initiatives and digital health alliances support scalable, global treatment models. These collaborations enable faster innovation and broader geographic reach.
Market Segmentation Analysis:
By Device
The Global Diabetic Neuropathy Management Market features a diverse range of device-based solutions. Electrical stimulation devices lead the segment due to their wide use in non-invasive pain relief. Neurostimulation devices are expanding rapidly, supported by technological innovations and long-term efficacy in managing chronic symptoms. Nerve conduction testing devices are vital for early-stage diagnostics and widely used in clinical settings. Other devices, including portable monitoring systems and biofeedback units, support ongoing care and patient self-management.
- For instance, Boston Scientific’s Spectra WaveWriter spinal cord stimulator reported in published trials a 70% pain relief response rate at 12 months among diabetic neuropathy patients, making it a leading choice for device-based interventions.
By Application
Peripheral neuropathy represents the dominant application segment, reflecting its high incidence among diabetic patients. Autonomic neuropathy is gaining focus as screening for internal organ-related complications becomes more widespread. Proximal neuropathy sees slower growth but benefits from increased awareness and better differentiation through advanced imaging. Mononeuropathy remains a smaller niche with limited diagnosis but shows potential as diagnostic precision improves.
- For instance, Roche’s Elecsys® Neurodegeneration Assay enabled biomarkers in diabetic patients during a 2023 multicenter study, as reported in Roche’s official research summary and validated in the Journal of Clinical Investigation.
By End Use
Hospitals remain the primary end-use segment, driven by access to multidisciplinary teams, diagnostic infrastructure, and specialized equipment. Home healthcare is the fastest-growing segment, supported by patient preference for home-based care and the rise of wearable and portable devices. Other end uses include outpatient clinics, physiotherapy centers, and specialty pain management facilities, which are increasingly integrating diabetic neuropathy solutions into their service offerings.
Segmentation:
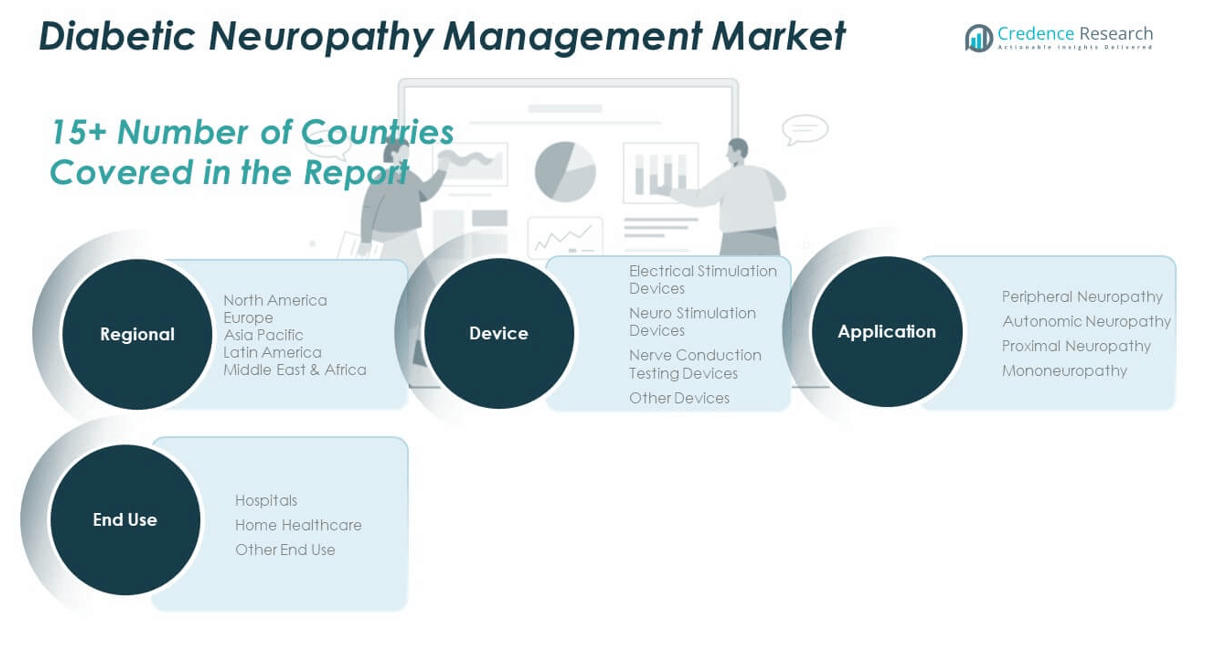
By Device
- Electrical Stimulation Devices
- Neuro Stimulation Devices
- Nerve Conduction Testing Devices
- Other Devices
By Application
- Peripheral Neuropathy
- Autonomic Neuropathy
- Proximal Neuropathy
- Mononeuropathy
By End Use
- Hospitals
- Home Healthcare
- Other End Use
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Diabetic Neuropathy Management Market size was valued at USD 1,009.20 million in 2018 to USD 1,314.39 million in 2024 and is anticipated to reach USD 2,374.16 million by 2032, at a CAGR of 7.7% during the forecast period. North America accounted for approximately 43% market share in 2024. North America dominates the Global Diabetic Neuropathy Management Market due to its advanced healthcare systems and strong awareness of diabetic complications. High prevalence of type 2 diabetes, especially in the U.S., drives consistent demand for neuropathy care. Health insurers support coverage of medications, diagnostics, and specialist consultations. Pharmaceutical firms maintain a strong commercial presence with ongoing product launches and clinical trials. Patients benefit from structured chronic care pathways and wide access to multidisciplinary pain management centers. Research institutions collaborate with industry to develop targeted non-opioid therapeutics. Digital health tools and remote monitoring enhance treatment outcomes and patient engagement. The region sustains its lead through innovation, policy support, and extensive provider networks.
Europe
The Europe Global Diabetic Neuropathy Management Market size was valued at USD 547.52 million in 2018 to USD 689.17 million in 2024 and is anticipated to reach USD 1,168.87 million by 2032, at a CAGR of 6.9% during the forecast period. Europe accounted for approximately 22.6% market share in 2024. Europe holds a significant share of the Global Diabetic Neuropathy Management Market due to strong public health systems and chronic disease frameworks. Countries such as Germany, France, and the UK lead in diabetic neuropathy research and care delivery. Universal healthcare systems ensure timely diagnosis and access to approved therapies. Regional guidelines support evidence-based prescribing of non-opioid pain management drugs. Hospitals and specialty clinics provide multidisciplinary services tailored for neuropathy patients. Pharmaceutical companies benefit from centralized procurement and transparent regulatory pathways. Population aging contributes to the rising incidence of diabetes and associated complications. Europe's market growth remains steady due to robust infrastructure and focus on patient outcomes.
Asia Pacific
The Asia Pacific Global Diabetic Neuropathy Management Market size was valued at USD 466.78 million in 2018 to USD 647.27 million in 2024 and is anticipated to reach USD 1,316.52 million by 2032, at a CAGR of 9.3% during the forecast period. Asia Pacific accounted for approximately 21.2% market share in 2024. Asia Pacific is the fastest-growing region in the Global Diabetic Neuropathy Management Market, driven by rising diabetes incidence and improving healthcare access. China and India, with large diabetic populations, offer vast opportunities for neuropathy treatment expansion. Urbanization and lifestyle changes increase the rate of diabetes complications across Southeast Asia. Governments invest in early detection programs and chronic disease management campaigns. Public and private hospitals upgrade diagnostic and pain management capabilities. Pharmaceutical companies form local partnerships to strengthen distribution and reduce treatment costs. Digital health platforms extend care delivery to underserved rural areas. The region advances rapidly with scalable care models and growing health investment.
Latin America
The Latin America Global Diabetic Neuropathy Management Market size was valued at USD 150.34 million in 2018 to USD 195.94 million in 2024 and is anticipated to reach USD 329.38 million by 2032, at a CAGR of 6.8% during the forecast period. Latin America accounted for approximately 6.4% market share in 2024. Latin America demonstrates moderate growth in the Global Diabetic Neuropathy Management Market, supported by improved awareness and evolving healthcare policies. Brazil and Mexico lead the region in diabetic patient populations and healthcare expenditure. Governments prioritize chronic disease management in public health agendas. Hospitals and pharmacies expand availability of neuropathy medications and diagnostics. Cost remains a barrier in rural and low-income communities, affecting access and adherence. International health organizations support outreach and education programs. Telemedicine adoption gains momentum to bridge care delivery gaps. The region continues to expand through targeted public-private initiatives and infrastructure upgrades.
Middle East
The Middle East Global Diabetic Neuropathy Management Market size was valued at USD 93.26 million in 2018 to USD 115.36 million in 2024 and is anticipated to reach USD 189.37 million by 2032, at a CAGR of 6.4% during the forecast period. Middle East accounted for approximately 3.8% market share in 2024. The Middle East shows steady development in the Global Diabetic Neuropathy Management Market due to rising diabetes prevalence linked to lifestyle factors. Gulf Cooperation Council (GCC) countries invest heavily in non-communicable disease prevention and specialty care. National healthcare plans support diabetes screening and treatment for associated complications. Urban centers such as Dubai and Riyadh feature advanced diagnostic and therapeutic facilities. Pharmaceutical imports ensure availability of neuropathy drugs, while local production remains limited. Private healthcare providers play a major role in managing chronic pain conditions. Awareness programs educate the public on the risks of untreated diabetic neuropathy. Continued growth depends on expanding access beyond metropolitan areas.
Africa
The Africa Global Diabetic Neuropathy Management Market size was valued at USD 52.90 million in 2018 to USD 90.37 million in 2024 and is anticipated to reach USD 141.69 million by 2032, at a CAGR of 5.4% during the forecast period. Africa accounted for approximately 3% market share in 2024. Africa represents an emerging market within the Global Diabetic Neuropathy Management Market. Diabetes prevalence is rising due to rapid urbanization, changing diets, and limited preventive care. Healthcare infrastructure remains underdeveloped in many regions, affecting access to diagnostics and long-term management. Public health systems prioritize infectious diseases, delaying investment in chronic care. International aid agencies and NGOs provide training, medications, and screening tools in targeted areas. Urban centers like Johannesburg and Nairobi see gradual improvement in neuropathy treatment availability. Language, literacy, and transportation remain barriers to patient education and adherence. Market growth relies on systemic healthcare improvements and stronger policy frameworks.
Key Player Analysis:
- Medtronic
- Nevro Corp.
- NeuroMetrix, Inc.
- Abbott
- Boston Scientific Corporation
- Neuralace
- Fremslife S.r.l. P.I.
- DyAnsys Inc.
- Impeto Medical
Competitive Analysis:
The Global Diabetic Neuropathy Management Market features moderate competition with key players focusing on product innovation, clinical trials, and non-invasive device development. Companies like Medtronic, Abbott, Boston Scientific, and Nevro Corp. lead through extensive R&D investments and robust product portfolios. Emerging players such as NeuroMetrix, Neuralace, and DyAnsys Inc. introduce wearable and neurostimulation-based solutions, targeting unmet clinical needs. Strategic collaborations between biotech firms and research institutions accelerate the commercialization of advanced therapies. Market participants compete on device efficacy, regulatory approvals, and geographic expansion. It continues to attract new entrants driven by rising diabetic prevalence and demand for safer, non-opioid treatments.
Recent Developments:
- In June 2025, Medtronic announced the upcoming launch of MiniMed, the planned new company focusing on diabetes care. Additionally, Medtronic introduced the Simplera Sync™ disposable, all-in-one glucose sensor for diabetes management, which is set for limited launch in Fall 2025. Simplera Sync™ features no-fingerstick operation and a streamlined insertion process, supporting patient use and clinical workflow.
- In May 2025, NeuroMetrix, Inc. was officially acquired by electroCore. The acquisition brings NeuroMetrix’s Quell platform-a wearable neuromodulation device for chronic pain (including neuropathy)-into electroCore’s portfolio. The transaction is part of a broader strategy, with NeuroMetrix planning to separately sell its DPNCheck point-of-care neuropathy diagnostic business ahead of closing.
- In February 2024, Nevro Corp. announced a global expert consensus statement supporting its high-frequency (10kHz) spinal cord stimulation (SCS) therapy-the Nevro HFX system-for refractory painful diabetic neuropathy. This recognition follows their device’s FDA approval and reinforces its validated effectiveness and growing clinical adoption for diabetic neuropathy management.
Market Concentration & Characteristics:
The Global Diabetic Neuropathy Management Market is moderately fragmented, with a mix of multinational medical device companies and niche technology innovators. It features strong product pipelines, frequent technological upgrades, and a growing focus on wearable neurostimulation solutions. Barriers to entry include regulatory hurdles, device certification costs, and clinical validation requirements. It is characterized by a shift toward digital health integration, patient-centric therapies, and personalized pain management protocols. Leading firms differentiate through global distribution networks and therapy-specific expertise.
Report Coverage:
The research report offers an in-depth analysis based on device type, application, and end use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising diabetes incidence will sustain long-term demand for early neuropathy diagnosis and intervention.
- Advancements in wearable and neuromodulation devices will transform non-invasive treatment delivery.
- Regulatory support for non-opioid pain management will accelerate adoption of safer therapies.
- Precision medicine and pharmacogenomics will enable personalized drug regimens and targeted outcomes.
- Expanding healthcare access in emerging economies will unlock new growth opportunities.
- Integration of AI and remote monitoring will enhance symptom tracking and treatment optimization.
- Multidisciplinary care models will drive holistic neuropathy management strategies.
- Collaborations between biotech firms and academic institutions will fuel innovation in drug development.
- Growing awareness campaigns will improve early-stage diagnosis and treatment adherence.
- Market consolidation may increase through mergers and acquisitions among key players.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Diabetes Prevalence
The increasing incidence of diabetes, particularly among aging and urban populations, is leading to a higher number of patients at risk for neuropathy, thereby driving demand for early diagnosis and effective management solutions.
Advancements in Non-Opioid Pain Management Therapies
The development and clinical adoption of non-opioid therapies, such as anticonvulsants, antidepressants, and neurostimulation devices, are expanding treatment options and improving patient outcomes while addressing regulatory and public health concerns about opioid use.
Expansion of Healthcare Access and Reimbursement
Improved healthcare infrastructure and broader insurance coverage in both developed and emerging markets are making neuropathy diagnostics and treatments more accessible and affordable, encouraging higher treatment uptake and adherence.
Technological Integration and Digital Health Adoption
The integration of wearable devices, telemedicine, and AI-driven monitoring tools is enhancing early detection, real-time symptom tracking, and personalized care, which collectively improve disease management and patient engagement.
Ongoing Pharmaceutical and Device Innovation
Strong investment in R&D by pharmaceutical and medical device companies is resulting in novel therapeutics, targeted drug delivery systems, and advanced diagnostic tools, fueling market growth and addressing unmet clinical needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Diabetic Neuropathy Management Market?
What are the key segments within the Global Diabetic Neuropathy Management Market?
What are some challenges faced by the Global Diabetic Neuropathy Management Market?
Who are the major players in the Global Diabetic Neuropathy Management Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Device
- 1.2.1 Electrical Stimulation Devices
- 1.2.2 Neuro Stimulation Devices
- 1.2.3 Nerve Conduction Testing Devices
- 1.2.4 Other Devices
- 1.3 By End Use
- 1.3.1 Hospitals
- 1.3.2 Home Healthcare
- 1.3.3 Other End Use
- 1.4 By Application
- 1.4.1 Peripheral Neuropathy
- 1.4.2 Autonomic Neuropathy
- 1.4.3 Proximal Neuropathy
- 1.4.4 Mononeuropathy
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,052.50 million → 2032: USD 5,520.00 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Diabetic Neuropathy Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Diabetic Neuropathy Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Diabetic Neuropathy Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Diabetic Neuropathy Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Diabetic Neuropathy Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Diabetic Neuropathy Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Diabetic Neuropathy Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Diabetic Neuropathy Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,052.50 million → 2032: USD 5,520.00 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Diabetic Neuropathy Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Device - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electrical Stimulation Devices
- 12.3.7.2 Neuro Stimulation Devices
- 12.3.7.3 Nerve Conduction Testing Devices
- 12.3.7.4 Other Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Home Healthcare
- 12.4.7.3 Other End Use
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Peripheral Neuropathy
- 12.5.7.2 Autonomic Neuropathy
- 12.5.7.3 Proximal Neuropathy
- 12.5.7.4 Mononeuropathy
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Diabetic Neuropathy Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Diabetic Neuropathy Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Diabetic Neuropathy Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Diabetic Neuropathy Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nevro Corp.
- 18.4 NeuroMetrix, Inc.
- 18.5 Abbott
- 18.6 Boston Scientific Corporation
- 18.7 Neuralace
- 18.8 Fremslife S.r.l. P.I.
- 18.9 DyAnsys Inc.
- 18.10 Impeto Medical
- 18.11 electroCore
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

