
Market overview
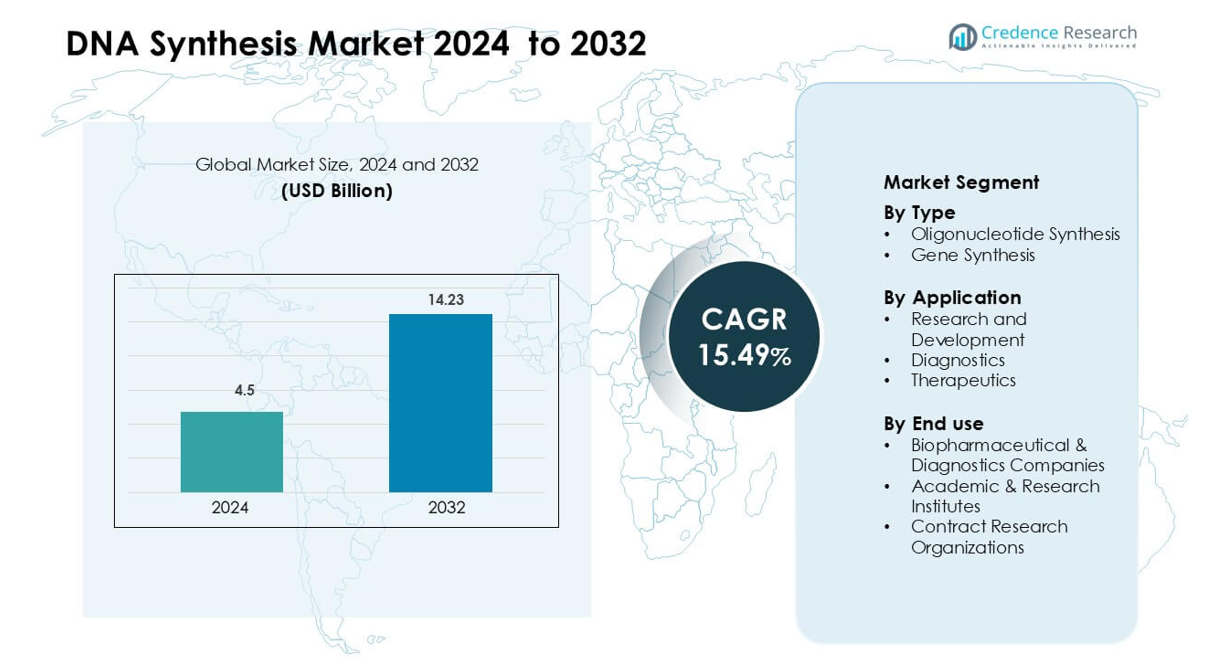
DNA Synthesis Market was valued at USD 4.5 billion in 2024 and is anticipated to reach USD 14.23 billion by 2032, growing at a CAGR of 15.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| DNA Synthesis Market Size 2024 | USD 4.5 billion |
| DNA Synthesis Market, CAGR | 15.49% |
| DNA Synthesis Market Size 2032 | USD 14.23 billion |
The DNA synthesis market includes strong participants such as GenScript, Eton Bioscience, Quintara Biosciences, Eurofins Scientific, Twist Bioscience, Integrated DNA Technologies, IBA Lifesciences, Thermo Fisher Scientific, BIONEER Corporation, and LGC Biosearch Technologies, each competing through advanced platforms, improved accuracy, and faster turnaround. These companies focus on high-fidelity oligonucleotides, complex gene constructs, and scalable synthesis services that support diagnostics, therapeutics, and synthetic biology programs. They also expand global reach through partnerships with biotech firms and research institutes. North America leads the market with a 38% share, driven by strong R&D funding, genomic initiatives, and early adoption of automated DNA assembly technologies.
Market Insights
- The DNA synthesis market reached USD 4.5 billion in 2024 and is set to grow at a 15.49 % CAGR through 2032, supported by rising demand for high-fidelity oligos, genes, and synthetic constructs across research and clinical use.
- Strong growth stems from higher adoption of synthetic biology, expanded genomic research, and increasing use of DNA-based tools in diagnostics and therapy development, driving steady demand for oligonucleotide synthesis, which holds the largest segment share.
- Key trends include automation, high-throughput assembly, and AI-driven sequence optimization, which improve accuracy and reduce turnaround time while supporting large-scale design programs.
- Competition intensifies as global players invest in quality control, GMP-ready services, and advanced synthesis platforms to meet needs across pharma, biotech, and research institutes, while cost pressure and error limitations remain key restraints.
- North America leads with a 38% share, followed by Europe and Asia-Pacific, while R&D applications dominate due to heavy primer, probe, and gene construct consumption.
Market Segmentation Analysis
By Type
Oligonucleotide Synthesis dominates the DNA synthesis market with 39.98% share in 2024. Demand stays strong because oligonucleotides support PCR primers, probes, sequencing, and gene editing workflows. High use in molecular diagnostics and routine research drives repeat orders and volume growth. Gene Synthesis forms the second key segment, serving custom constructs, gene fragments, and gene libraries. This segment benefits from synthetic biology programs, vaccine development, and engineered cell lines. Shorter turnaround times and higher accuracy further support adoption of complex gene constructs.
- For instance, Integrated DNA Technologies (IDT) was founded as a startup by Dr. Joseph A. Walder in 1987. The company experienced rapid growth, and within its first decade, it grew from 10 synthesizing machines to more than 500, shipping an average of 75,000 custom oligonucleotides per day to more than 82,000 customers worldwide.
By Application
Research and Development is the leading segment with 44.96% market share in 2024. This leadership reflects large genomics projects, functional studies, and early drug discovery programs. Laboratories order high volumes of primers, probes, and synthetic constructs for cloning and pathway work. Diagnostics represent a fast growing application as molecular tests and NGS panels expand. Demand rises especially across oncology, infectious disease, and reproductive health testing. Therapeutics use grows with gene and cell therapies, DNA vaccines, and oligonucleotide-based drugs.
- For instance, Twist Bioscience’s silicon‑based DNA synthesis platform is capable of synthesizing 9,600 genes in a single run on one chip, enabling high‑throughput variant library generation for drug discovery.
By End use
Biopharmaceutical and Diagnostics Companies hold the largest share at 42.03% in 2024. These organizations drive demand through extensive therapeutic pipelines, biomarker research, and companion diagnostics. They require scalable, GMP grade synthesis, strong quality systems, and regulatory compliant documentation. Academic and Research Institutes form a substantial customer base for basic and translational research. These institutes support projects in genetics, synthetic biology, and novel therapeutic discovery. Contract Research Organizations grow quickly as sponsors outsource discovery programs, assays, and preclinical studies.
Key Growth Drivers
Growing Adoption of Synthetic Biology Programs
The rapid expansion of synthetic biology programs drives strong demand for DNA synthesis services. Research teams design custom genes, metabolic pathways, and regulatory elements to develop engineered microbes, advanced therapeutics, and bio-based materials. These projects require accurate, scalable, and rapid DNA construction, which boosts orders for oligonucleotides, long DNA fragments, and fully assembled genes. Many companies now integrate automated assembly platforms and high-throughput screening tools, which increases the volume of constructs needed each month. Wider use of CRISPR workflows also supports this growth because gene editing experiments depend on guide RNAs and donor templates produced through DNA synthesis. As global investment in synthetic biology grows, biotechnology companies, academic labs, and start-ups continue to adopt DNA synthesis as a core tool for innovation and product development across healthcare, agriculture, and industrial biotechnology.
- For instance, Synbio Technologies reports having synthesised over 10 billion bases and optimized more than 500 000 codons to support complex synthetic biology workflows.
Expansion of Precision Medicine and Genomic Research
Precision medicine efforts increase DNA synthesis demand as researchers target disease-specific mutations and patient-level biomarkers. Laboratories design custom primers, probes, and gene panels for next-generation sequencing workflows, which require constant replenishment of high-quality oligonucleotides. Pharma companies also use synthetic DNA to validate drug targets, model genetic variations, and study disease pathways. Growth in rare disease research accelerates demand further because personalized therapies often need custom gene constructs and optimized DNA sequences. Many hospitals and diagnostic labs expand genetic testing services, which pushes procurement of synthetic DNA for assay development. As governments fund genomic initiatives and sequencing costs continue to fall, healthcare systems adopt more DNA-based tools, increasing long-term use of DNA synthesis across both research and clinical settings.
- For instance, Integrated DNA Technologies offers synthetic genes from 25 bp to 5 kb delivered with 100% sequence verification and a guaranteed delivery turnaround of 8 business days for up to 500 bp and 12 days for 501‑5000 bps.
Rising Pipeline of Gene and Cell Therapy Candidates
The growing pipeline of gene and cell therapy candidates acts as a major driver of the DNA synthesis market. Developers need synthetic promoters, enhancers, coding sequences, and regulatory elements to construct therapeutic vectors. CAR-T, AAV-based therapies, and in vivo gene editing programs rely heavily on precise DNA synthesis to ensure safety and efficacy. Companies scale manufacturing and preclinical studies, which raises the need for GMP-compliant, error-free sequences. As more therapies enter clinical trials, demand rises for large-scale gene constructs, quality-controlled plasmids, and custom oligonucleotides used in vector engineering and analytical testing. Continued investment in advanced therapies ensures stable and long-term growth for DNA synthesis providers, especially those offering high-fidelity synthesis, rapid turnaround, and regulatory support for clinical-grade DNA.
Key Trend and Opportunity
Increasing Automation and High-Throughput DNA Assembly
Automation shapes the next phase of DNA synthesis by boosting speed, accuracy, and volume. Companies adopt robotic liquid handlers, microfluidic systems, and machine-learning-based error correction tools to assemble complex genes faster. High-throughput platforms now support parallel synthesis of hundreds to thousands of constructs, enabling faster screening for bioengineering, drug discovery, and metabolic pathway optimization. Miniaturized reaction formats also reduce reagent use and lower cost per base. As providers integrate cloud-based design tools and AI-driven sequence optimization, customers gain greater control over construct design and turnaround times. Automation helps scale synthetic biology programs, accelerates R&D cycles, and supports industrial-level DNA manufacturing.
- For instance, Twist Multiplexed Gene Fragments product supports pools of up to 500 base‑pairs in length, with variant pools starting at 1,000 sequences in parallel.
Growth of DNA-Based Vaccines and Immunotherapy
DNA-based vaccines and immunotherapies create strong opportunities for synthesis companies. Researchers require custom antigen sequences, codon-optimized genes, and plasmid backbones for preclinical and clinical studies. mRNA vaccine platforms also use synthetic DNA templates during transcription, which increases upstream demand. Many biotech firms now explore DNA vaccines for infectious diseases, oncology, and emerging pathogens. Regulatory momentum, combined with global investment in rapid-response vaccine platforms, increases orders for high-quality and GMP-ready DNA. This opportunity strengthens as countries invest in biodefense and pandemic preparedness programs, expanding the need for scalable DNA production.
- For instance, VGXI, Inc. has built a facility capable of manufacturing plasmid DNA at concentrations up to 10 mg/mL and supercoiling purity >95 % to support GMP‑grade vaccine production.
Rising Use of DNA Synthesis in Agriculture and Industrial Biotechnology
Agriculture and industrial biotech sectors adopt DNA synthesis for crop engineering, microbial strain enhancement, and metabolic pathway design. Synthetic DNA enables creation of stress-tolerant crops, improved nutrient profiles, and faster-growing plant varieties. Industrial players engineer microbes to produce biofuels, enzymes, bio-plastics, and specialty chemicals, all of which require optimized gene constructs and regulatory sequences. As companies shift from fossil-based to bio-based production, they rely more on synthetic genes and pathway rewiring. The agricultural sector also increases use of gene-editing tools, which boosts the need for primers, guides, and donor templates. These developments expand the application base for DNA synthesis beyond healthcare.
Key Challenge
High Cost of Complex and Large-Scale DNA Constructs
Despite strong demand, high synthesis costs limit adoption of complex and long DNA constructs. Long sequences require multiple assembly steps, error-correction cycles, and validation processes that increase production expenses. Many academic labs and smaller biotech firms struggle to afford large gene constructs or rapid-turnaround synthesis services. Price sensitivity slows uptake of industrial-scale or pathway-level projects where hundreds of sequences are required. Although automation lowers cost over time, the gap between demand and affordability remains a major obstacle. Cost burdens also impact early-stage research teams that rely on grant-based funding, making it difficult to scale experiments that require high-fidelity or customized DNA.
Technical Limitations in Error Rates and Sequence Complexity
DNA synthesis still faces challenges related to sequence accuracy, GC-rich regions, repeats, and secondary structures. Complex sequences often produce higher error rates, requiring additional screening and quality control. These limitations slow project timelines, increase production steps, and restrict the types of genes that can be synthesized at scale. Some therapeutic and industrial applications demand near-perfect accuracy and long, stable constructs, which current synthesis chemistry cannot always deliver. Providers work to reduce error frequency and expand sequence compatibility, but technical constraints continue to affect turnaround time and cost. These challenges reduce efficiency for researchers engineering new biological pathways or therapeutic constructs.
Regional Analysis
North America
North America leads the DNA synthesis market with an estimated 38% share, driven by strong investment in genomics, synthetic biology, and gene therapy programs. The region benefits from advanced research infrastructure, large pharmaceutical pipelines, and early adoption of automated DNA assembly systems. U.S. laboratories and biotech firms generate high demand for oligonucleotides, gene fragments, and clinical-grade constructs used in diagnostics and therapeutic development. Expanding precision medicine initiatives, growing sequencing output, and rising venture capital funding further strengthen regional growth. Canada supports additional demand through government-funded genomics projects and expanding academic research networks.
Europe
Europe holds about 27% market share, supported by active genomic research programs, strong regulatory frameworks, and advanced biotechnology clusters. Countries such as Germany, the U.K., and France drive regional demand with well-established pharmaceutical industries and growing investments in synthetic biology. Research centers use DNA synthesis for molecular diagnostics, vaccine development, and engineered cell lines. EU programs focused on bioeconomy expansion and precision medicine further increase adoption. The region also benefits from academic-industry partnerships that accelerate gene-editing research, metabolic engineering, and high-throughput DNA assembly.
Asia-Pacific
Asia-Pacific captures nearly 24% market share, fueled by rapid growth in genomics, diagnostics, and biopharma manufacturing. China, Japan, South Korea, India, and Singapore expand DNA synthesis use across drug discovery, gene-editing research, and clinical testing laboratories. Government-led genome projects, expanding sequencing capacity, and rising investment in synthetic biology accelerate demand. Several regional companies invest in automation and high-throughput synthesis technologies, driving competitive pricing and faster turnaround. APAC’s growing biotechnology workforce and expanding CRO sector make the region a strong hub for outsourced DNA synthesis services.
Latin America
Latin America holds around 6% market share, driven by rising adoption of molecular diagnostics, infectious disease testing, and academic genomic research. Brazil, Mexico, and Argentina lead regional activity with growing investments in biotechnology infrastructure and research institutes. Expanding public health programs increase demand for synthetic primers and probes used in PCR and sequencing workflows. Partnerships with international suppliers support access to high-quality DNA constructs. Although investment levels remain lower than major markets, demand grows steadily as clinical testing expands and universities adopt more synthetic biology tools.
Middle East & Africa
The Middle East & Africa region accounts for nearly 5% market share, supported by expanding healthcare modernization and growing interest in genomic medicine. Countries such as the UAE, Saudi Arabia, and South Africa lead adoption, focusing on precision diagnostics, infectious disease research, and academic genomics programs. Infrastructure development in clinical laboratories raises demand for basic oligonucleotides and sequencing-related constructs. Regional initiatives promoting biotechnology education and innovation also support gradual market expansion. Growth remains moderate due to limited manufacturing capabilities, but rising investment in healthcare research strengthens long-term potential.
Market Segmentations:
By Type
- Oligonucleotide Synthesis
- Gene Synthesis
By Application
- Research and Development
- Diagnostics
- Therapeutics
By End use
- Biopharmaceutical & Diagnostics Companies
- Academic & Research Institutes
- Contract Research Organizations
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the DNA synthesis market features a mix of global biotechnology firms, specialized synthesis providers, and high-throughput technology innovators that focus on precision, scale, and turnaround speed. Companies compete by offering advanced oligonucleotide synthesis, large gene constructs, and GMP-grade materials that support diagnostics, therapeutics, and synthetic biology research. Many providers invest in automation, microfluidics, and enzyme-based synthesis platforms to improve accuracy and reduce cycle times. Partnerships with pharmaceutical companies, academic institutes, and contract research organizations strengthen service portfolios and expand geographic reach. Firms also enhance online ordering systems, sequence optimization tools, and custom design platforms to improve user experience. Growing demand for long DNA fragments, high-fidelity constructs, and error-corrected sequences drives continuous product upgrades. Competitors aim to differentiate through quality control strength, scalability, and regulatory compliance to support rising applications in gene therapy, vaccine development, and advanced genomic research.
Key Player Analysis
- GenScript
- Eton Bioscience, Inc.
- Quintara Biosciences
- Eurofins Scientific
- Twist Bioscience
- Integrated DNA Technologies, Inc.
- IBA Lifesciences GmbH
- Thermo Fisher Scientific, Inc.
- BIONEER CORPORATION
- LGC Biosearch Technologies
Recent Developments
- In January 2025, Eton Bioscience expanded its sequencing portfolio with whole-plasmid nanopore sequencing. The service uses Oxford Nanopore MinION and EPI2ME workflows to deliver Q30+ assemblies for synthetic biology and DNA-writing projects.
- In June 2024, GenScript Biotech Corporation launched its FLASH Gene gene-synthesis service with flat-rate pricing. The service delivers sequence-verified plasmid constructs in four business days for advanced biologics R&D
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as synthetic biology research grows across healthcare and industrial biotech.
- Demand will rise for long, complex, and error-corrected DNA constructs that support advanced engineering.
- Automation will scale high-throughput synthesis and lower turnaround times for custom sequences.
- Enzyme-based DNA synthesis methods will gain wider adoption due to higher accuracy and fewer chemical steps.
- Clinical-grade DNA will see strong uptake as more gene and cell therapy programs enter trials.
- AI-driven design tools will improve sequence optimization and reduce failure rates in complex genes.
- DNA-based vaccines and immunotherapies will boost orders for codon-optimized constructs and plasmid templates.
- CROs will increase their share by supporting outsourced discovery and preclinical projects.
- Regional manufacturing hubs will expand to shorten supply chains and improve delivery speed.
- Cost reduction efforts will improve access for academic labs and early-stage biotech companies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Adoption of Synthetic Biology Programs
The rapid expansion of synthetic biology initiatives is driving demand for DNA synthesis, as researchers require custom genes, regulatory elements, and metabolic pathways for engineered organisms, advanced therapeutics, and bio-based materials. Automated assembly and high-throughput screening tools further increase the volume of DNA constructs needed.
Expansion of Precision Medicine and Genomic Research
Precision medicine and genomic research are fueling the need for synthetic DNA, as laboratories design custom primers, probes, and gene panels for next-generation sequencing and disease-specific biomarker studies. This trend is reinforced by falling sequencing costs and increased funding for genomic initiatives.
Rising Pipeline of Gene and Cell Therapy Candidates
The development of gene and cell therapies is a major growth driver, with companies requiring synthetic promoters, enhancers, and coding sequences for therapeutic vectors. The need for GMP-compliant, error-free DNA constructs grows as more therapies enter clinical trials and manufacturing scales up.
Increasing Automation and High-Throughput DNA Assembly
Automation technologies, including robotic liquid handlers and microfluidic systems, are enabling faster, more accurate, and higher-volume DNA synthesis. This supports large-scale synthetic biology projects and reduces turnaround times, making DNA synthesis more accessible for research and industrial applications.
Growth of DNA-Based Vaccines and Immunotherapy
The rise of DNA-based vaccines and immunotherapies is boosting demand for custom antigen sequences, codon-optimized genes, and plasmid backbones. Global investment in rapid-response vaccine platforms and pandemic preparedness is expanding the need for scalable, high-quality DNA synthesis.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for DNA Synthesis Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is DNA Synthesis Market projected to grow between 2025 and 2032?
Which oligonucleotide type segment will post the highest CAGR in the forecast period?
Who are the major players in the global DNA synthesis market?
What are the major market drivers of the DNA synthesis industry?
What are the major market restraints of the DNA synthesis industry?
What are the major market opportunities of the DNA synthesis industry?
Who are the leading companies in DNA Synthesis Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Oligonucleotide Synthesis
- 1.2.2 Gene Synthesis
- 1.3 By End use
- 1.3.1 Biopharmaceutical & Diagnostics Companies
- 1.3.2 Academic & Research Institutes
- 1.3.3 Contract Research Organizations
- 1.4 By Application
- 1.4.1 Research and Development
- 1.4.2 Diagnostics
- 1.4.3 Therapeutics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4.5 billion → 2032: USD 14.23 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global DNA Synthesis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global DNA Synthesis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global DNA Synthesis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global DNA Synthesis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global DNA Synthesis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global DNA Synthesis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global DNA Synthesis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global DNA Synthesis Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4.5 billion → 2032: USD 14.23 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global DNA Synthesis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oligonucleotide Synthesis
- 12.3.7.2 Gene Synthesis
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Biopharmaceutical & Diagnostics Companies
- 12.4.7.2 Academic & Research Institutes
- 12.4.7.3 Contract Research Organizations
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Research and Development
- 12.5.7.2 Diagnostics
- 12.5.7.3 Therapeutics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global DNA Synthesis End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global DNA Synthesis Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global DNA Synthesis Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global DNA Synthesis Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GenScript
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eton Bioscience, Inc.
- 18.4 Quintara Biosciences
- 18.5 Eurofins Scientific
- 18.6 Twist Bioscience
- 18.7 Integrated DNA Technologies, Inc.
- 18.8 IBA Lifesciences GmbH
- 18.9 Thermo Fisher Scientific, Inc.
- 18.10 BIONEER CORPORATION
- 18.11 LGC Biosearch Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

