
Market Overview:
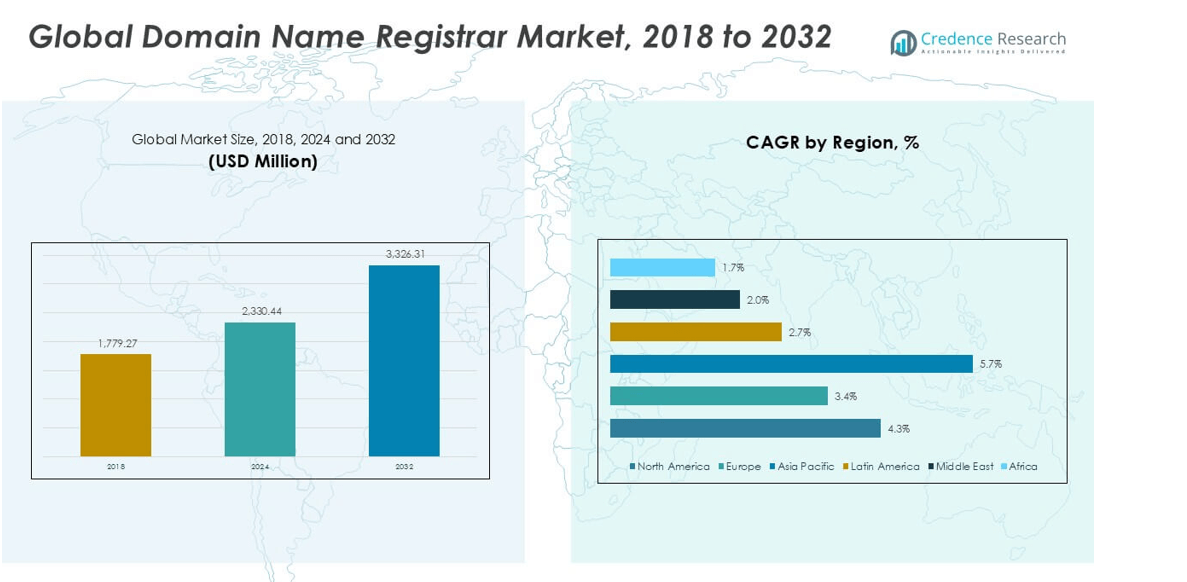
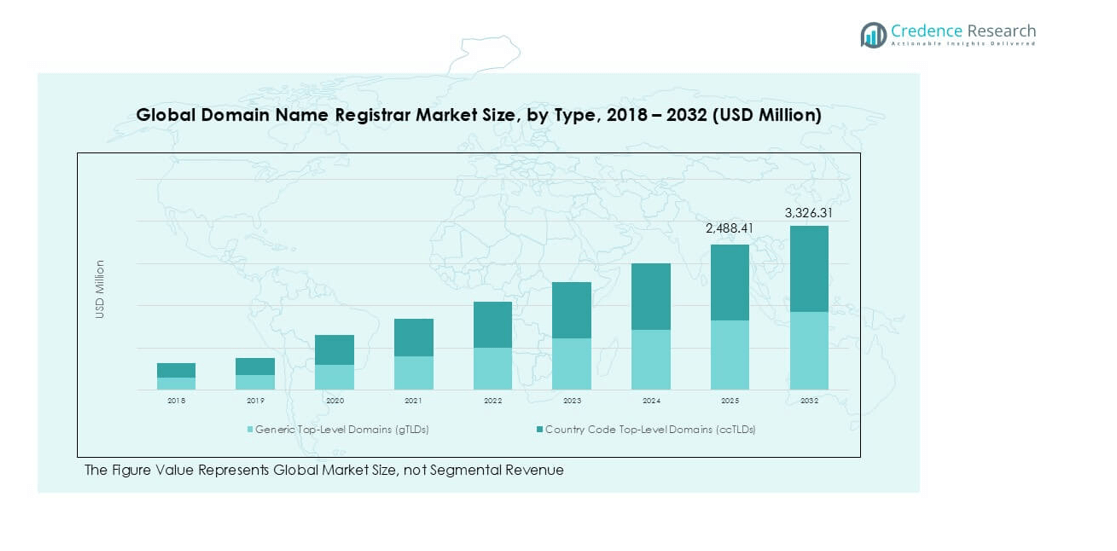
The Domain Name Registrar market size was valued at USD 1,779.27 million in 2018 and reached USD 2,330.44 million in 2024. It is anticipated to reach USD 3,326.31 million by 2032, growing at a CAGR of 4.23% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Domain Name Registrar Market Size 2024 | USD 2,330.44 million |
| Domain Name Registrar Market, CAGR | 4.23% |
| Domain Name Registrar Market Size 2032 | USD 3,326.31 million |
The domain name registrar market is driven by leading players including GoDaddy, Namecheap, Google Domains, 1&1 IONOS, Tucows, Network Solutions, BigRock, Bluehost, HostGator, DreamHost, and Gandi. These companies dominate through extensive domain portfolios, competitive pricing, and value-added services such as hosting, SSL, and privacy protection. GoDaddy maintains a strong leadership position with a broad customer base, while Namecheap and Google Domains expand influence with affordable and integrated solutions. Regionally, North America held the largest share at 41.1% in 2024, supported by advanced digital infrastructure and strong enterprise adoption, followed by Europe at 26.5% and Asia Pacific at 22.8%, highlighting the global distribution of market strength.
Market Insights
- The Domain Name Registrar market was valued at USD 2,330.44 million in 2024 and is projected to reach USD 3,326.31 million by 2032, expanding at a CAGR of 4.23%.
- Growth is driven by rising internet penetration, SME digitization, and increasing e-commerce adoption, which boost demand for domain registrations, renewals, and transfers globally.
- Market trends highlight the dominance of gTLDs with over 60% share, while niche domains like .tech and .ai are gaining popularity; domain registration remains the largest service type segment with more than 45% share.
- Competition is intense with major players such as GoDaddy, Namecheap, Google Domains, 1&1 IONOS, and Tucows focusing on bundled offerings like hosting, SSL, and privacy protection to retain customers in a price-sensitive market.
- Regionally, North America leads with 41.1% share in 2024, followed by Europe at 26.5% and Asia Pacific at 22.8%, while Latin America, the Middle East, and Africa show steady but smaller contributions.
Market Segmentation Analysis:
By Type
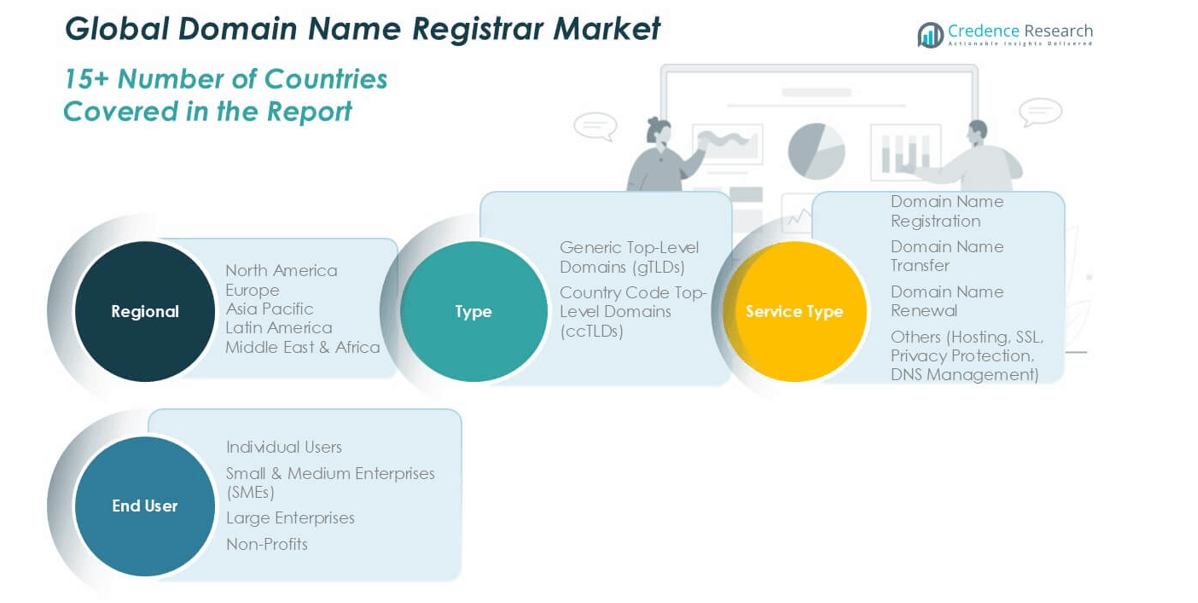
The domain name registrar market is segmented into Generic Top-Level Domains (gTLDs) and Country Code Top-Level Domains (ccTLDs). gTLDs held the dominant share of over 60% in 2024, driven by global adoption, ease of recognition, and brand flexibility across industries. Businesses and individuals prefer gTLDs such as .com, .org, and .net for credibility and visibility in global markets. In contrast, ccTLDs maintain strong relevance in localized branding and country-specific digital presence, with steady growth supported by regional e-commerce expansion and regulatory policies encouraging domestic domain usage.
- For instance, GoDaddy reported managing over 84 million domain names in 2023, with .com alone representing more than 50 million registrations under its portfolio.
By Service Type
Within service types, domain name registration emerged as the leading sub-segment, accounting for more than 45% share in 2024. The rise of digital transformation, increasing new website launches, and startups seeking online presence fueled this dominance. Domain transfers and renewals followed, benefitting from customer migration between registrars and long-term website maintenance needs. Additional services such as hosting, SSL certificates, and privacy protection gained traction as value-added offerings, with enterprises adopting bundled solutions to secure and optimize online operations, further expanding registrar revenue streams beyond initial domain registrations.
- For instance, in 2023, Namecheap added approximately 1.74 million new domain registrations and gained over 1.11 million new customers. While the company's "supplementary product portfolio" of additional services such as hosting and SSL certificates performed well, it is inaccurate to claim that it bundled these specific services to over 1 million customers during the year.
By End User
Among end users, small and medium enterprises (SMEs) captured the largest share, holding over 40% of the market in 2024. SMEs drive growth as they rapidly adopt digital platforms for e-commerce, marketing, and customer engagement. Cost-effective registration services and easy domain management tools encourage this segment’s leadership. Large enterprises also contribute significantly, leveraging domain portfolios for brand protection and global visibility. Individual users remain active in personal websites, freelancing, and blogging, while non-profits register domains to promote outreach and fundraising efforts, contributing to steady growth across all user categories.
Market Overview
Rising Internet Penetration and Digital Adoption
The surge in global internet users has significantly boosted demand for domain registrations. Businesses, startups, and individuals are increasingly building digital identities, leading to sustained growth in domain acquisitions. Countries in Asia-Pacific, Africa, and Latin America are witnessing rapid digital adoption, further expanding the customer base for registrars. The adoption of smartphones and affordable connectivity has accelerated website creation for e-commerce, education, and social engagement. As internet penetration deepens, more organizations consider online presence vital, fueling consistent growth in the domain registrar market worldwide.
- For instance, GoDaddy reported managing over 84 million domain names in 2023, with more than 1.5 million new registrations coming from India and Brazil as internet adoption surged in these markets.
E-commerce Expansion and Online Branding Needs
The rapid growth of e-commerce is a major driver of domain registrations. Companies across industries prioritize building strong digital brands, which requires secure, credible, and easily recognizable domains. SMEs and new ventures, in particular, fuel demand for affordable domain services. Registrars benefit from renewals and premium domain purchases as businesses seek unique names for competitive visibility. The rising importance of brand protection online has also pushed enterprises to secure multiple extensions and variants of their domains. These factors collectively strengthen the market’s expansion in the coming years.
- For instance, Shopify powered over 2.1 million live stores by the end of 2023 through its e-commerce platform. While Shopify offers an integrated domain service, the 2.1 million figure refers to the number of active stores, not the number of domains registered directly through its service.
Integration of Value-Added Services
Domain name registrars increasingly offer bundled solutions such as hosting, SSL certificates, email services, and DNS management. These value-added services enhance security, performance, and customer convenience, creating higher retention rates and additional revenue streams. SMEs and enterprises prefer all-in-one solutions to streamline online operations and reduce costs. Growing cybersecurity concerns drive demand for privacy protection and secure domain management. Registrars that invest in integrated digital platforms gain a competitive advantage, attracting long-term clients. The move from standalone domain registration to a service ecosystem is a strong growth catalyst.
Key Trends & Opportunities
Growing Demand for gTLDs and Niche Domains
Generic Top-Level Domains (gTLDs) such as .com, .org, and .net dominate registrations, but new niche domains like .tech, .shop, and .ai are rapidly gaining traction. Businesses adopt specialized extensions to enhance branding relevance and differentiate themselves in competitive markets. Tech startups, e-commerce firms, and AI-driven companies are especially driving demand for these niche domains. The ICANN approval process for new extensions is also creating opportunities for innovation in digital identity. This diversification trend provides registrars with wider offerings to target niche industries and customer groups effectively.
- For instance, the .ai registry reported more than 354,000 active .ai domain registrations in 2023, driven largely by global AI startups and enterprises adopting the extension for brand positioning.
SME Digitization and Regional Market Growth
Small and medium enterprises are the fastest-growing customer base for domain registrars, particularly in Asia-Pacific and Africa. Governments support SME digitization through incentives, training, and digital inclusion programs. Regional ccTLD adoption is also increasing, as businesses prefer localized domains to build trust among domestic customers. Affordable pricing models and flexible service packages create opportunities for registrar growth in developing economies. This trend positions registrars to expand their footprint by aligning offerings with SME needs and supporting localized domain adoption in high-growth emerging markets.
Key Challenges
Rising Cybersecurity Threats and Domain Abuse
The domain registrar market faces increasing risks from phishing, malware distribution, and domain hijacking. Cybercriminals exploit weak registration processes, creating challenges for maintaining trust. Registrars must invest in stronger authentication, DNS security extensions (DNSSEC), and advanced monitoring tools to counter these threats. Compliance with evolving global regulations on privacy and cybersecurity further increases operational complexity. Failure to address these risks undermines customer confidence and can result in financial penalties, reputational damage, and customer attrition, making cybersecurity a significant challenge for market players.
Intense Price Competition and Market Saturation
The market is highly competitive, with numerous registrars offering low-cost domain services to attract customers. This price war reduces profit margins and limits the ability of smaller players to scale operations. Bundled services are becoming essential for differentiation, but heavy investment in infrastructure and customer support strains resources. Additionally, market saturation in mature regions like North America and Europe slows new domain growth. Registrars must innovate beyond price competitiveness to sustain growth, making differentiation through service quality, security, and customer experience a pressing challenge.
Regional Analysis
North America
North America dominated the domain name registrar market in 2024 with a 41.1% share, reaching USD 959.44 million from USD 740.59 million in 2018. The region is projected to grow at a CAGR of 4.3%, attaining USD 1,373.43 million by 2032. Strong demand comes from the U.S. and Canada, driven by mature internet infrastructure, e-commerce adoption, and enterprises expanding digital identities. Large enterprises actively invest in brand protection and domain portfolios, supporting market expansion. The presence of leading registrars and the growing demand for security-enhanced services further strengthen North America’s leadership position.
Europe
Europe captured a 26.5% market share in 2024, with revenue rising from USD 491.69 million in 2018 to USD 620.17 million. The market is expected to reach USD 831.97 million by 2032, growing at a CAGR of 3.4%. Widespread digital transformation initiatives, GDPR-driven privacy demands, and e-commerce adoption drive market momentum. European businesses increasingly register domains under both gTLDs and ccTLDs, reflecting strong regional and cross-border branding. Germany, the U.K., and France lead the adoption, while emerging Eastern European markets offer growth potential. Regulatory compliance remains a defining factor shaping registrar strategies across the region.
Asia Pacific
Asia Pacific accounted for a 22.8% market share in 2024, valued at USD 532.46 million, up from USD 377.82 million in 2018. The market is forecast to expand at the fastest CAGR of 5.7%, reaching USD 851.93 million by 2032. The region’s growth is fueled by rising internet penetration, SME digitization, and strong demand for localized ccTLDs in countries like China and India. Government-led digitalization programs further encourage domain registrations. Affordable pricing models and a growing startup ecosystem make Asia Pacific a high-growth region, with increasing adoption across both enterprises and individual users.
Latin America
Latin America represented a 4.8% share of the global domain name registrar market in 2024, with revenue increasing from USD 87.40 million in 2018 to USD 113.11 million. The market is expected to grow at a CAGR of 2.7%, reaching USD 143.62 million by 2032. Brazil and Mexico drive the majority of demand, supported by expanding e-commerce, fintech services, and digital marketing adoption. SMEs and individual users fuel growth through affordable domain registrations, although price sensitivity remains high. Slow but steady regional digital transformation ensures consistent adoption, albeit at a lower growth pace compared to other regions.
Middle East
The Middle East captured a 2.6% market share in 2024, reaching USD 60.19 million from USD 50.24 million in 2018. The region is projected to achieve USD 72.60 million by 2032, growing at a CAGR of 2.0%. Domain name adoption is supported by government-led smart city projects, rising internet penetration, and investments in digital infrastructure. The UAE and Saudi Arabia are the largest markets, emphasizing domain registrations to support online services and e-commerce growth. However, the market remains smaller compared to global leaders due to limited SME penetration and relatively slower digital adoption in other countries.
Africa
Africa accounted for a 1.9% market share in 2024, with revenue growing from USD 31.53 million in 2018 to USD 45.07 million. The market is anticipated to reach USD 52.75 million by 2032, reflecting a CAGR of 1.7%. South Africa, Nigeria, and Kenya are the key contributors, supported by rising mobile internet usage and growing demand for localized ccTLDs. Despite these drivers, growth remains modest due to infrastructure gaps and lower digital maturity across several countries. Affordability and government-led digital inclusion programs are expected to drive gradual expansion, though Africa remains the smallest regional market globally.
Market Segmentations:
By Type
- Generic Top-Level Domains (gTLDs)
- Country Code Top-Level Domains (ccTLDs)
By Service Type
- Domain Name Registration
- Domain Name Transfer
- Domain Name Renewal
- Others (Hosting, SSL, Privacy Protection, DNS Management)
By End User
- Individual Users
- Small & Medium Enterprises (SMEs)
- Large Enterprises
- Non-Profits
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The domain name registrar market is highly competitive, led by players such as GoDaddy, Namecheap, Google Domains, 1&1 IONOS, Tucows, Network Solutions, BigRock, Bluehost, HostGator, DreamHost, and Gandi. These companies compete on pricing, domain availability, bundled services, and customer support. GoDaddy remains a dominant force with a broad product portfolio and strong global presence, while Namecheap attracts SMEs with affordable registrations and privacy-focused services. Google Domains leverages its ecosystem integration, and 1&1 IONOS emphasizes enterprise-grade hosting solutions. Regional players like BigRock and Gandi strengthen competition with localized offerings. The market is witnessing consolidation, with registrars expanding through acquisitions and partnerships to increase customer base and domain portfolios. Value-added services such as SSL certificates, hosting, and privacy protection have become key differentiators to retain customers in a price-sensitive environment. Increasing demand for cybersecurity, multi-domain management, and specialized gTLDs further intensifies competition, pushing registrars to innovate beyond core registration services.
Key Player Analysis
- GoDaddy
- Namecheap
- Google Domains
- 1&1 IONOS
- Tucows
- Network Solutions
- BigRock
- Bluehost
- HostGator
- DreamHost
- Gandi
Recent Developments
- In February 2024, Registered Agents Inc. (RAI) bought controversial domain registrar Epik in order to expand its service offerings to small businesses and entrepreneurs. Epik, the host of the 8chan and Parler domains, has been bought again.
- In January 2024, MeitY unveiled a domain registration platform for educational organizations. The Ministry of Electronics and Information Technology has established an integrated website for educational institutions. The ERNET portal will provide educational institutions with domain registration, DNS, and value-added services such as Website as a Service (WaaS) and Learning Management as a Service (LMaaS).
Report Coverage
The research report offers an in-depth analysis based on Type, Service Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with growing demand for digital identities across industries.
- SMEs will remain the fastest-growing end-user segment due to rising online presence.
- gTLDs will continue to dominate, while niche domains such as .ai and .tech gain traction.
- Domain registration will sustain leadership among service types, supported by continuous new website launches.
- Bundled services like hosting, SSL, and DNS management will drive higher customer retention.
- Cybersecurity and privacy protection will emerge as critical differentiators among registrars.
- Asia Pacific will witness the highest growth rate, driven by digital adoption and startup activity.
- North America will maintain leadership with advanced infrastructure and enterprise demand.
- Price competition will push registrars to innovate in value-added solutions beyond registration.
- Strategic partnerships and acquisitions will shape market consolidation and global expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Domain Name Registrar market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Domain Name Registrar market projected to grow between 2025 and 2032?
Which Domain Name Registrar market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Domain Name Registrar market?
Who are the leading companies in the Domain Name Registrar market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Domain Name Registrar Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Domain Name Registrar Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,330.44 million → 2032: USD 3,326.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Domain Name Registrar Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Domain Name Registrar Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Domain Name Registrar Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Domain Name Registrar Market Drivers
- 3.3 Domain Name Registrar Market Restraints & Challenges
- 3.4 Domain Name Registrar Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Domain Name Registrar Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Domain Name Registrar Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Domain Name Registrar category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Domain Name Registrar Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Domain Name Registrar Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Domain Name Registrar market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Domain Name Registrar Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Domain Name Registrar Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Domain Name Registrar Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Domain Name Registrar (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Domain Name Registrar Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Domain Name Registrar Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Domain Name Registrar Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Domain Name Registrar Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Domain Name Registrar Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Domain Name Registrar Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Domain Name Registrar Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Domain Name Registrar Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Domain Name Registrar Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
