
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Dry Room Dehumidifier Market Size 2024 | USD 377 million |
| Dry Room Dehumidifier Market, CAGR | 10.40% |
| Dry Room Dehumidifier Market Size 2032 | USD 831.94 million |
Market Overview:
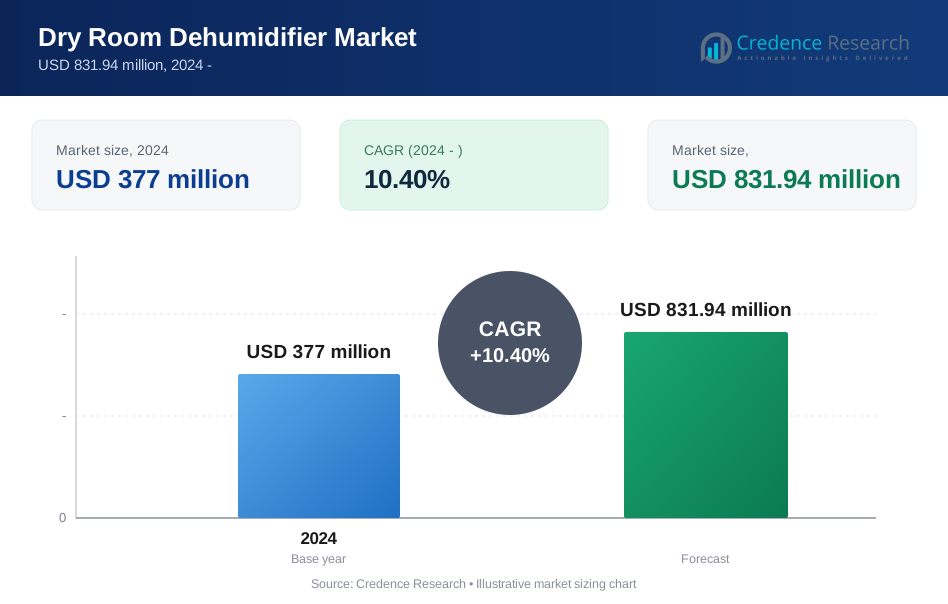
The global dry room dehumidifier market is anticipated to experience significant growth, with a market size projected to rise from USD 377 million in 2024 to USD 831.94 million by 2032, representing a compound annual growth rate (CAGR) of 10.40% over the forecast period. This growth is driven by the increasing demand for moisture control in various industrial applications, particularly in battery manufacturing, pharmaceuticals, and electronics, where precision in humidity levels is crucial. Dry room dehumidifiers are essential for maintaining low humidity environments, thereby ensuring product quality, preventing moisture-induced defects, and extending the shelf life of sensitive materials.
Key drivers for the market include the expansion of the electric vehicle (EV) industry, which relies heavily on lithium-ion battery production. Battery manufacturing facilities require dry rooms with stringent humidity controls, fueling demand for high-capacity dehumidifiers. Additionally, the electronics sector, particularly in semiconductor manufacturing, is growing rapidly and necessitates ultra-low humidity environments to prevent condensation and corrosion. Furthermore, as pharmaceutical and biotechnology sectors expand globally, especially in emerging economies, the need for reliable dehumidification solutions for R&D and production environments continues to grow. Government regulations and industry standards, such as GMP (Good Manufacturing Practice) for pharmaceuticals, also drive adoption, as companies prioritize moisture control to ensure compliance and quality assurance.
Regionally, North America and Asia-Pacific dominate the market for dry room dehumidifiers. North America holds a substantial share due to its advanced manufacturing infrastructure and strong presence in pharmaceutical and battery manufacturing industries. The United States, in particular, leads in technological innovation, fueling demand for advanced dehumidification solutions. Meanwhile, the Asia-Pacific region is expected to witness the highest growth rate, primarily driven by increasing investments in electric vehicle manufacturing and the expansion of the semiconductor industry in countries such as China, Japan, and South Korea. The presence of major electronics and battery manufacturers in this region, combined with favorable government initiatives to support manufacturing growth, significantly contributes to the demand for dry room dehumidifiers. Europe also represents a strong market, particularly within pharmaceutical and food industries that require stringent moisture control to maintain product quality and regulatory compliance.
Market Drivers:
Growing Demand from the Electric Vehicle (EV) Sector:
As the global EV market expands, so does the need for lithium-ion batteries, which are highly sensitive to moisture. Dry room dehumidifiers play a crucial role in maintaining optimal humidity levels required for battery production. For instance, Tesla and Panasonic’s gigafactories heavily invest in advanced dehumidification systems to ensure precise environmental conditions in their battery manufacturing facilities. A report from the International Energy Agency (IEA) projects that EV sales will increase significantly by 2030, underscoring the importance of dry room dehumidifiers in meeting production demands.
Increasing Stringency in Pharmaceutical Manufacturing Standards:
The pharmaceutical industry requires controlled environments to ensure product quality and compliance with regulatory standards such as the Good Manufacturing Practices (GMP). Excess humidity can lead to contamination and compromised shelf life of sensitive pharmaceutical products. For example, companies like Pfizer have installed advanced dehumidification systems in their production facilities to comply with FDA regulations on humidity control. According to the World Health Organization (WHO), maintaining low humidity levels is essential in pharmaceutical production to prevent microbial contamination and ensure drug efficacy.
Rapid Growth in the Electronics and Semiconductor Industries:
The electronics industry, especially in semiconductor manufacturing, relies on dry room environments to prevent moisture-related defects in sensitive components. Companies such as Intel and Samsung have invested in state-of-the-art dry room dehumidifiers to protect against condensation and corrosion during the production of microchips. The Semiconductor Industry Association reports that global semiconductor sales reached record highs in recent years, highlighting the ongoing need for robust dehumidification solutions to maintain quality control in electronics manufacturing.
Expansion of Cleanroom Requirements in Biotechnology and R&D:
The biotechnology sector has witnessed increased demand for cleanrooms equipped with dehumidification systems to support research and development of biological products. Moisture control is critical for maintaining sterility and preventing contamination in lab environments. For instance, government-funded research facilities like the National Institutes of Health (NIH) require strict environmental controls, including dry room dehumidifiers, to ensure precise experimental conditions. As biotechnology continues to expand, the demand for advanced humidity control solutions in R&D facilities is expected to grow, driven by both government regulations and industry standards.
Market Trends:
Shift Toward Energy-Efficient Dehumidifiers:
Energy efficiency has become a primary focus for manufacturers of dry room dehumidifiers as industries prioritize reducing operational costs and meeting sustainability goals. Companies are developing advanced dehumidifiers that consume less power while maintaining high performance. For instance, Munters, a global leader in climate control solutions, has introduced energy-saving dehumidifiers that utilize innovative rotor technology to enhance efficiency. A U.S. Department of Energy (DOE) report emphasizes the benefits of energy-efficient systems, noting that businesses can achieve substantial cost savings by adopting such technology in industrial processes.
Adoption of IoT-Enabled Dehumidification Systems:
The integration of the Internet of Things (IoT) with dehumidification systems allows for real-time monitoring and enhanced control over humidity levels, improving operational efficiency and reducing downtime. Companies like Honeywell have developed IoT-enabled dehumidifiers that provide remote monitoring capabilities and predictive maintenance alerts. According to a McKinsey report, IoT technology can increase industrial productivity by up to 25%, and its application in humidity control is particularly valuable for industries that require stringent environmental conditions, such as pharmaceutical manufacturing and electronics.
Growth in Demand for Modular and Scalable Dehumidification Solutions:
Industries are increasingly favoring modular dehumidification systems that offer scalability to match their changing production needs. This trend is especially prevalent in the semiconductor and EV battery manufacturing sectors, where production capacity can fluctuate based on market demands. For instance, Hitachi has developed scalable dehumidification solutions that allow manufacturers to adjust capacity as needed. A survey by the International Society for Pharmaceutical Engineering (ISPE) found that over 60% of surveyed facilities seek modular solutions to optimize space and operational flexibility in controlled environments.
Increased Focus on Environmental Sustainability:
Environmental sustainability is driving innovation in dehumidifier technology, with companies striving to minimize waste and use eco-friendly materials. Manufacturers are adopting sustainable practices, such as using recyclable materials and incorporating energy-efficient components in their products. For example, Trotec has launched dehumidifiers that use eco-friendly refrigerants to minimize environmental impact. Additionally, the European Union’s REACH regulation encourages industries to adopt sustainable practices by limiting hazardous substances, further promoting the use of eco-friendly materials in dry room dehumidifiers to comply with environmental standards.
Market Challenges Analysis:
High Initial Costs and Maintenance Requirements:
The installation and maintenance costs of dry room dehumidifiers are significant, often posing a financial barrier for small and medium-sized enterprises (SMEs). These systems require substantial upfront investment, with high-capacity units often priced at a premium due to their advanced features. Additionally, routine maintenance, such as filter replacements and system calibration, adds to the total cost of ownership. The U.S. Environmental Protection Agency (EPA) has highlighted that regular maintenance is essential for dehumidifiers to operate efficiently, which can further strain operational budgets for smaller companies that may struggle to justify these ongoing expenses.
Environmental Impact and Regulatory Compliance:
Dry room dehumidifiers often use refrigerants that can contribute to greenhouse gas emissions if not managed properly, raising concerns about their environmental impact. Governmental bodies, such as the European Union (EU) and the EPA, have implemented stringent regulations under programs like the EU’s F-Gas Regulation, which aims to reduce the use of hydrofluorocarbons (HFCs) in refrigeration and air conditioning systems. Compliance with these environmental regulations requires companies to adopt eco-friendly refrigerants and improve waste management practices, which can increase production costs and limit profitability, especially for smaller firms.
Limited Awareness in Emerging Markets:
In many developing regions, awareness about the benefits of dry room dehumidifiers remains limited, slowing market penetration. Industries in regions like Southeast Asia and parts of Latin America may not fully recognize the advantages of precise humidity control, which can impact adoption rates. Additionally, these markets often have lower regulatory enforcement compared to developed countries, with less stringent requirements for environmental control in manufacturing processes. As a result, companies in these regions may lack the incentive to invest in high-performance dehumidification systems, limiting the market’s growth potential in emerging economies.
Supply Chain Disruptions and Raw Material Volatility:
The dry room dehumidifier market is susceptible to supply chain disruptions, which can delay production and increase costs. For instance, the COVID-19 pandemic highlighted vulnerabilities in global supply chains, impacting the availability of essential components like compressors and filters. Fluctuations in raw material prices, especially for metals and specialized polymers used in dehumidifier manufacturing, further challenge manufacturers' ability to control costs. According to the U.S. Department of Commerce, supply chain resilience is crucial for mitigating these risks, as ongoing disruptions may hinder production capacity and reduce market competitiveness.
Market Segmentation Analysis:
By Type
The dry room dehumidifier market is segmented by type into desiccant and refrigerant dehumidifiers. Desiccant dehumidifiers, which use a drying agent to absorb moisture, are favored for their ability to maintain extremely low humidity levels, making them ideal for applications in lithium battery and pharmaceutical manufacturing. On the other hand, refrigerant dehumidifiers, which operate through a cooling coil, are used in moderate humidity settings, such as food processing and storage. The versatility of these types allows industries to select the appropriate solution based on specific environmental requirements.
By Technology
The market is further segmented by technology into fixed and portable dehumidifiers. Fixed dehumidifiers are installed permanently in facilities that require consistent, long-term humidity control, such as battery production plants. Portable dehumidifiers are designed for flexibility and mobility, making them suitable for applications where temporary humidity control is needed. Recent advancements have enhanced the efficiency and reliability of both fixed and portable systems, with IoT-enabled models gaining popularity for remote monitoring and control capabilities.
By End User
The end-user segmentation of the market includes industries such as electronics, pharmaceuticals, food processing, and lithium-ion battery manufacturing. Electronics and semiconductor industries heavily utilize dry room dehumidifiers to prevent moisture-related defects in microchip and circuit production. The pharmaceutical sector relies on precise humidity control to meet regulatory standards and ensure product integrity. In lithium-ion battery manufacturing, which has witnessed rapid growth due to the expanding electric vehicle market, dry room dehumidifiers are essential for maintaining controlled environments. This diverse end-user base underscores the critical role of dehumidification solutions across industries requiring precision moisture control to ensure quality and compliance.
Segmentation:
By Type- Desiccant Dehumidifiers
- Refrigerant Dehumidifiers
- Thermoelectric Dehumidifiers
- Others
- Closets
- Bathrooms
- Laundries
- Others
- Residential
- Commercial
- Industrial
- Institution
- Others
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds a significant share of the dry room dehumidifier market, driven primarily by the United States and Canada. The region accounts for around 35% of the global market share, supported by a robust presence in industries such as pharmaceuticals, electronics, and battery manufacturing, where strict humidity control is essential. The U.S., in particular, has implemented stringent regulations through agencies like the Environmental Protection Agency (EPA) to ensure optimal environmental standards, which boosts demand for advanced dehumidification solutions. Additionally, North American manufacturers focus on energy-efficient dehumidifiers to reduce operational costs, contributing to the steady growth of the market in this region.
Europe
Europe represents one of the largest markets for dry room dehumidifiers, with an approximate market share of 25%. The European Union’s emphasis on sustainability and environmental regulations drives the adoption of advanced dehumidification systems in sectors such as pharmaceuticals, food processing, and automotive. Countries like Germany, the United Kingdom, and France are key contributors, with Germany leading due to its established industrial base and commitment to quality standards. The European Green Deal and the REACH regulations have further promoted the use of eco-friendly materials and energy-efficient technologies. This focus on compliance and sustainability supports continued market growth across the region.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for dry room dehumidifiers, capturing around 30% of the global share. The region’s growth is fueled by rapid industrialization and significant investments in electric vehicle (EV) battery manufacturing and semiconductor production, particularly in China, Japan, and South Korea. China, as a leading manufacturer, benefits from government incentives promoting clean energy and technological advancements, which enhances demand for dry room dehumidifiers in its expanding industrial sector. Additionally, countries like India and South Korea are seeing increased adoption in pharmaceuticals and electronics due to rising infrastructure and manufacturing activities.
Latin America
Latin America holds a smaller share of the global market, estimated at approximately 5%, but shows potential for growth due to expanding industrial and manufacturing sectors in countries like Brazil and Mexico. The region’s warm and humid climate creates a natural demand for dehumidification solutions in food processing and pharmaceuticals. Mexico’s commitment to developing its manufacturing sector, coupled with favorable government policies, supports gradual adoption of advanced dehumidification technologies. However, limited awareness and lower regulatory enforcement in some areas may restrict more rapid growth.
Middle East and Africa
The Middle East and Africa collectively account for around 5% of the dry room dehumidifier market. High temperatures and humidity levels make dehumidification critical, particularly in countries like the United Arab Emirates, Saudi Arabia, and South Africa, where industries are focusing on maintaining product quality in food processing and pharmaceuticals. The UAE, for example, has made substantial investments in industrial infrastructure, supporting the demand for dehumidifiers. Although the region’s market share is modest, the need for high-quality production standards and regulatory developments is expected to drive gradual growth in the coming years.
Key Player Analysis:
- Munters Group AB
- Bry-Air Inc.
- DehuTech AB
- Therma-Stor LLC
- Trotec GmbH
- Condair Group AG
- Aprilaire
- Desert Aire Corp
- Hannover Klima GmbH
- Stulz Air Technology Systems, Inc.
Competitive Analysis:
The dry room dehumidifier market is characterized by moderate to high competition, with a few key players such as Munters Group AB, Bry-Air Inc., and DehuTech AB holding a significant market share due to their advanced product offerings and robust distribution networks. These companies maintain a competitive edge by focusing on energy-efficient and technologically advanced dehumidifiers that cater to industries requiring precise humidity control, including pharmaceuticals, electronics, and battery manufacturing. Many competitors emphasize innovation, integrating IoT and automation features into their dehumidification systems to enhance monitoring and operational efficiency. Smaller firms and new entrants tend to focus on niche applications or cost-effective solutions to gain market traction, while larger firms invest heavily in R&D to enhance product performance and sustainability. Additionally, strategic mergers and partnerships are common as companies seek to expand their market presence and offer comprehensive solutions to end-users globally.
Recent Developments:
- In September 2022, Bry-Air launched "BryShield," a product specifically designed for small server rooms to prevent electronic corrosion by removing gaseous contaminants. This product, compact and ceiling-mounted, aligns with the company's goal to offer targeted dehumidification solutions for specialized applications.
- In November 2022, Munters expanded its desiccant dehumidification capabilities by acquiring Hygromedia and Rotor Source. This acquisition strengthens Munters' position in the market, particularly in providing solutions for industrial processes that require precise humidity control, such as lithium battery manufacturing and electronics production.
- In February 2022, DehuTech introduced an upgraded version of its DT-210 desiccant dehumidifier. The new design features a cost-effective casing and improved fan technology, which enhances durability and operational efficiency, catering to users who need reliable performance under high temperature conditions in dry room environments.
- In August 2022, Bry-Air partnered with Airtho Cleanroom Products to provide a 55,000-square-foot dry room facility for the iM3NY lithium-ion gigafactory in Endicott, U.S. This partnership underscores Bry-Air's commitment to supporting the growing electric vehicle (EV) battery industry by offering specialized dehumidification solutions critical to lithium-ion battery manufacturing.
Market Concentration & Characteristics:
The dry room dehumidifier market is moderately concentrated, with a few prominent players such as Munters Group, Bry-Air, and DehuTech AB leading due to their advanced technologies and established presence in high-demand sectors like pharmaceuticals, lithium battery manufacturing, and electronics. These companies emphasize product innovation, such as IoT integration and energy-efficient designs, to meet stringent humidity control requirements across various industries. While larger firms dominate the market due to their extensive R&D capabilities and global reach, smaller and regional players also contribute, primarily by offering specialized solutions or cost-competitive products. The market is characterized by a strong focus on technological advancements, sustainability, and regulatory compliance, with a growing trend toward modular and scalable systems. Strategic acquisitions and partnerships are common as companies aim to expand their portfolios and enhance market presence. Overall, competition centers around product efficiency, technological innovation, and adherence to industry-specific standards.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for dry room dehumidifiers is expected to grow as industries prioritize moisture control, particularly in sectors like pharmaceuticals.
- Advancements in energy-efficient technologies will drive product development, as manufacturers seek to reduce operational costs and meet sustainability goals.
- The integration of IoT-enabled systems will enhance remote monitoring and predictive maintenance, leading to higher efficiency and reduced downtime in industrial applications.
- Increasing investment in the EV sector, especially in lithium-ion battery production, will significantly boost the demand for high-performance dry room dehumidifiers.
- The Asia-Pacific region will likely experience the fastest growth, driven by rapid industrialization, government incentives, and expanding infrastructure projects in countries like China, Japan, and India.
- Europe will see continued adoption of dry room dehumidifiers, propelled by stringent environmental regulations and the need for compliance with sustainability targets in manufacturing.
- Modular and scalable dehumidifier systems are expected to gain traction, allowing industries to adjust capacity according to production needs and space constraints.
- Rising awareness about the importance of air quality and moisture control in emerging markets will support gradual adoption.
- Strategic partnerships and acquisitions will remain prevalent as companies aim to expand their product portfolios and strengthen their market presence globally.
- As industries face increased regulatory scrutiny, compliance-focused dehumidifiers that meet industry-specific standards will become a key differentiator for market leaders.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of the Electric Vehicle (EV) Industry
The rapid growth of the EV sector is driving demand for lithium-ion batteries, which require ultra-low humidity environments for safe and efficient production. Dry room dehumidifiers are essential in battery manufacturing facilities to maintain strict moisture control, directly fueling market growth.
Stringent Pharmaceutical Manufacturing Standards
Pharmaceutical production must comply with regulations such as GMP, which mandate precise humidity control to ensure product quality and prevent contamination. The need to meet these standards is increasing adoption of advanced dehumidification systems in pharmaceutical manufacturing and R&D environments.
Growth in Electronics and Semiconductor Manufacturing
The electronics and semiconductor industries require dry room environments to prevent moisture-induced defects and corrosion in sensitive components. As global demand for semiconductors and advanced electronics rises, so does the need for high-performance dry room dehumidifiers.
Adoption of Energy-Efficient and IoT-Enabled Solutions
Industries are increasingly seeking energy-efficient and IoT-enabled dehumidifiers to reduce operational costs and enable real-time monitoring. This trend is driving innovation and encouraging the replacement of older systems with advanced, efficient models.
Regulatory and Sustainability Pressures
Environmental regulations, such as the EU’s REACH and F-Gas regulations, are pushing manufacturers to adopt eco-friendly refrigerants and sustainable practices. Compliance with these standards is accelerating the adoption of modern, environmentally responsible dehumidification technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the dry room dehumidifier market?
What factors are driving the growth of the dry room dehumidifier market?
What are some challenges faced by the dry room dehumidifier market?
Who are the major players in the dry room dehumidifier market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Desiccant Dehumidifiers
- 1.2.2 Refrigerant Dehumidifiers
- 1.2.3 Thermoelectric Dehumidifiers
- 1.2.4 Others
- 1.3 By End User
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
- 1.3.4 Institution
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Closets
- 1.4.2 Bathrooms
- 1.4.3 Laundries
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 377 million → 2032: USD 831.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dry Room Dehumidifier Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dry Room Dehumidifier Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dry Room Dehumidifier Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dry Room Dehumidifier Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dry Room Dehumidifier Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dry Room Dehumidifier Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dry Room Dehumidifier Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dry Room Dehumidifier Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 377 million → 2032: USD 831.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dry Room Dehumidifier Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Desiccant Dehumidifiers
- 12.3.7.2 Refrigerant Dehumidifiers
- 12.3.7.3 Thermoelectric Dehumidifiers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.7.4 Institution
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Closets
- 12.5.7.2 Bathrooms
- 12.5.7.3 Laundries
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dry Room Dehumidifier End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dry Room Dehumidifier Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dry Room Dehumidifier Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dry Room Dehumidifier Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Munters Group AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bry-Air Inc.
- 18.4 DehuTech AB
- 18.5 Therma-Stor LLC
- 18.6 Trotec GmbH
- 18.7 Condair Group AG
- 18.8 Aprilaire
- 18.9 Desert Aire Corp
- 18.10 Hannover Klima GmbH
- 18.11 Stulz Air Technology Systems, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
