
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
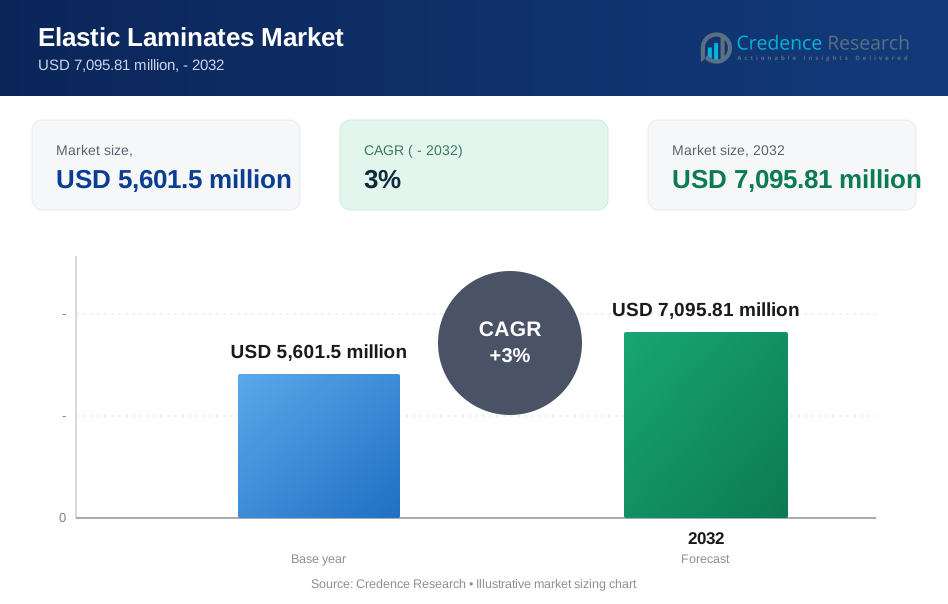
| Elastic Laminates Market Size 2023 | USD 5,601.5 Million |
| Elastic Laminates Market, CAGR | 3% |
| Elastic Laminates Market Size 2032 | USD 7,095.81 Million |
Market Overview
The Global Elastic Laminates Market is projected to grow from USD 5,601.5 million in 2023 to an estimated USD 7,095.81 million by 2032, registering a compound annual growth rate (CAGR) of 3% during the forecast period from 2024 to 2032. This steady growth is attributed to the increasing demand for elastic laminates in hygiene products, medical applications, and industrial goods.
Key drivers of the market include the rising need for advanced hygiene products, such as diapers and feminine care items, which require elastic laminates for superior comfort and fit. Additionally, trends such as sustainability and lightweight material designs are fostering innovation in recyclable and eco-friendly elastic laminates. The increasing application of these materials in the medical sector, particularly for wound care and surgical drapes, further boosts market demand. Enhanced product performance, combined with evolving consumer preferences, is expected to sustain growth over the forecast period.
Geographically, North America and Europe hold significant market shares due to high hygiene standards and advanced healthcare infrastructure. Meanwhile, Asia-Pacific is projected to experience the fastest growth, driven by population expansion, rising disposable income, and increased awareness of hygiene. Key players shaping the market include Schweitzer-Mauduit International Inc., Berry Global Group Inc., Pantex International S.p.A., Mondi Group plc, and Exxon Mobil Corp, among others. These companies focus on strategic collaborations, innovation, and sustainability to maintain their competitive edge.
Market Drivers
Growing Demand for Hygiene Products
The rising demand for hygiene products such as baby diapers, adult incontinence products, and feminine care items is a major driver for the global elastic laminates market. Elastic laminates are integral to these products, offering superior stretchability, comfort, and fit, which are essential features for end users. The increasing awareness of hygiene and sanitation, particularly in developing regions, has significantly boosted the consumption of these products. For instance, the hygiene segment is projected to account for 81.40% of the global market share in 2024, highlighting its dominance and the critical role elastic laminates play in enhancing product performance and comfort. Additionally, the growth of the elderly population worldwide has amplified the need for adult incontinence products, further propelling the demand for elastic laminates. Consumer preferences for improved product performance and comfort are encouraging manufacturers to develop advanced laminates that meet these requirements, fueling market growth.
Expansion of Medical and Healthcare Applications
The medical and healthcare industry plays a critical role in driving the elastic laminates market. These materials are widely used in medical applications, such as surgical drapes, wound care dressings, and disposable medical apparel. The need for high-performance, breathable, and skin-friendly materials in medical products has spurred innovation in elastic laminates. The ongoing global focus on healthcare infrastructure enhancement and preparedness—especially in light of pandemics and infectious disease outbreaks—has increased the demand for medical-grade materials. For example, a substantial rise in the use of elastic laminates in medical applications underscores their importance in providing flexibility and barrier properties.
Sustainability and Technological Innovations
Environmental concerns and the push for sustainable products have significantly influenced the elastic laminates market. Manufacturers are investing in research and development to create recyclable, biodegradable, and eco-friendly laminates that align with global sustainability goals. Innovations such as lightweight laminates and materials with enhanced durability are helping to reduce resource consumption and waste. Moreover, advancements in production technologies, such as the use of bio-based polymers and advanced manufacturing techniques, have improved the efficiency and quality of elastic laminates. This shift towards recyclable and biodegradable materials is evident as companies increasingly adopt lightweight laminates that reduce resource consumption while addressing environmental concerns and meeting the evolving demands of end-users for sustainable and high-performing materials.
Rising Population and Economic Growth in Emerging Markets
Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East & Africa, are driving the growth of the elastic laminates market. These regions are experiencing rapid population growth, urbanization, and economic development, leading to increased disposable income and higher living standards. As a result, there is a growing demand for hygiene products, medical supplies, and industrial goods that utilize elastic laminates. Governments and organizations in these regions are also promoting hygiene awareness and healthcare access, further boosting market demand. The untapped potential in these markets provides significant opportunities for manufacturers to expand their presence and cater to a broader consumer base.
Market Trends
Shift Towards Sustainable and Eco-Friendly Laminates
One of the most prominent trends in the Global Elastic Laminates Market is the increasing emphasis on sustainability. Manufacturers are focusing on developing recyclable, biodegradable, and eco-friendly elastic laminates to meet rising environmental concerns and stringent regulations. For instance, the increasing consumer demand for eco-friendly products has led manufacturers to innovate with materials such as bio-based polymers. Companies are now developing elastic laminates that not only meet performance standards but also adhere to environmental regulations, resulting in a notable rise in the production of recyclable and biodegradable options. This shift is evidenced by the fact that several leading manufacturers have reported a substantial increase in investments directed toward sustainable practices, with some companies allocating over $100 million annually to research and development focused on eco-friendly materials. The demand for sustainable materials is driven by heightened consumer awareness about environmental preservation and the need to reduce the ecological footprint of disposable products, such as diapers and feminine hygiene products. This shift has led to the adoption of bio-based polymers and advanced manufacturing processes that minimize waste and resource consumption. Companies are also investing in creating lightweight laminates without compromising on performance, addressing both cost-efficiency and sustainability. As governments worldwide advocate for greener practices, this trend is expected to shape product innovation and market strategies significantly.
Growing Adoption of Advanced Manufacturing Technologies
The adoption of advanced manufacturing technologies is another notable trend reshaping the elastic laminates market. Techniques such as multi-layer extrusion and nonwoven fabric bonding are enhancing the quality, functionality, and efficiency of elastic laminates. For example, one major player in the industry has implemented automation processes that have reduced production times by approximately 30%, while simultaneously improving product consistency and reducing waste. These technologies enable the production of laminates with improved elasticity, breathability, and durability, meeting the rising consumer demand for high-performance products. Additionally, advancements in automation and digitization are streamlining production processes, reducing operational costs, and ensuring consistent quality. Innovations like customized laminates tailored to specific applications in hygiene, medical, and industrial sectors are gaining traction. The integration of smart technologies into production lines also facilitates real-time monitoring and optimization, allowing manufacturers to respond dynamically to market needs and regulatory requirements.
Market Restraints and Challenges
High Production Costs and Limited Access to Raw Materials
One of the primary challenges in the Global Elastic Laminates Market is the high production costs associated with advanced manufacturing processes and raw material procurement. Elastic laminates are often made using specialized materials such as polymers and nonwoven fabrics, which can be expensive and subject to price volatility. Additionally, the increasing focus on sustainability has necessitated the development of bio-based and recyclable laminates, further driving up research and production expenses. Manufacturers, particularly in developing regions, face difficulties accessing premium raw materials, which hampers their ability to produce competitive, high-quality products. These cost-related challenges may discourage smaller market players from entering or scaling their operations, thereby affecting the overall market growth.
Environmental Concerns and Regulatory Pressures
Despite efforts toward sustainability, the elastic laminates industry faces ongoing challenges from environmental concerns and strict regulatory requirements. Many elastic laminates, especially those used in disposable hygiene products, contribute to waste accumulation and pose environmental risks if not properly disposed of or recycled. Governments and organizations are implementing stringent guidelines to minimize plastic waste and encourage the adoption of sustainable materials, which places additional compliance burdens on manufacturers. Adapting to these regulations requires significant investment in research, development, and process adjustments, which can strain resources, particularly for smaller players. Furthermore, consumer advocacy for eco-friendly alternatives continues to grow, pressuring companies to innovate rapidly or risk losing market share.
Market Segmentation Analysis
By Type
Propylene-based elastomers dominate the market due to their flexibility, durability, and lightweight properties, making them ideal for hygiene applications like diapers and adult incontinence products. Their recyclability aligns with the growing focus on sustainability, further driving demand. Ethylene-based elastomers are gaining traction for their versatility and cost-effectiveness, widely used in applications requiring a balance of stretchability and breathability, particularly in hygiene and medical sectors with increasing healthcare needs. Meanwhile, styrene-block copolymers (SBCs), though a smaller segment, play a critical role in medical applications due to their thermal stability, elasticity, and ease of processing, making them essential for products like wound care dressings and surgical drapes. The demand for all these elastomers continues to grow, supported by advancements in technology and heightened awareness of high-performance materials.
By Application
The application segment of the global elastic laminates market is led by the hygiene sector, driven by the rising demand for baby diapers, feminine care products, and adult incontinence items, where elastic laminates enhance comfort, fit, and leakage protection. Population growth and increased hygiene awareness, particularly in emerging markets, further fuel this segment's expansion. The medical segment is also experiencing robust growth, with elastic laminates being extensively used in surgical drapes, wound care, and disposable medical apparel due to their breathability and barrier properties, which ensure hygiene and prevent cross-contamination. Additionally, the market sees contributions from other applications, including protective clothing, packaging, and automotive components, where the unique stretchability, durability, and thermal resistance of elastic laminates support their use in diverse industrial and specialty products.
Segments
Based on type
- Propylene-based elastomers
- Ethylene-based elastomers
- Styrene-block copolymers
Based on Application
- Hygiene
- Medical
- Other
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (30%)
North America holds a substantial share of the global elastic laminates market, accounting for approximately 30% of the total market revenue. The region's growth is driven by advanced healthcare infrastructure and high consumer demand for hygiene products such as diapers, adult incontinence items, and feminine care products. The presence of key players, continuous innovation, and significant investments in sustainable materials further bolster the region's dominance. Additionally, increasing awareness about eco-friendly products aligns with regional sustainability goals, fostering the adoption of biodegradable elastic laminates.
Europe (25%)
Europe captures around 25% of the global market share, with countries like Germany, France, and the UK leading the way. Stringent environmental regulations and a strong focus on sustainability drive the demand for recyclable and bio-based elastic laminates in this region. The mature healthcare sector and growing adoption of advanced hygiene products contribute significantly to the market's growth. Moreover, Europe's established industrial base supports the development of high-performance laminates for both medical and industrial applications.
Key players
- Schweitzer-Mauduit International Inc.
- Berry Global Group Inc.
- Pantex International S.p.A.
- Aplix S.A.
- Golden Phoenix Fiberwebs Inc.
- Tredegar Corporation
- Mondi Group plc
- Neos Italia Srl
- Exxon Mobil Corp
- Kraton Corporation
Competitive Analysis
The Global Elastic Laminates Market is characterized by intense competition among established players and emerging regional manufacturers. Companies like Schweitzer-Mauduit International Inc., Berry Global Group Inc., and Mondi Group plc hold a significant market share due to their robust R&D capabilities and diversified product portfolios. Sustainability has become a competitive differentiator, with players such as Kraton Corporation and Tredegar Corporation investing heavily in eco-friendly and bio-based solutions. Exxon Mobil Corp and Aplix S.A. leverage their strong global distribution networks and expertise in material sciences to maintain market leadership. Smaller players like Neos Italia Srl and Golden Phoenix Fiberwebs Inc. focus on niche applications and cost-effective production. Strategic partnerships, mergers, and acquisitions remain common tactics to enhance market presence, while technological innovation drives product differentiation across applications in hygiene, medical, and industrial sectors.
Recent Developments
- In September 2023, Berry Global announced the launch of a new line of sustainable elastic laminates designed for hygiene products, emphasizing their commitment to reducing plastic waste and enhancing recyclability.
- In August 2023, Pantex announced the expansion of its production facilities in Italy to increase capacity for elastic laminates, aiming to meet rising demand in the hygiene sector.
- In June 2023, Aplix launched a new range of elastic laminates integrated with fastening technologies aimed at improving product performance in personal care applications.
- In October 2023, Golden Phoenix Fiberwebs unveiled a new series of biodegradable elastic laminates targeted at the feminine hygiene market, focusing on sustainability.
- In January 2024, Kraton Corporation introduced a new line of bio-based elastomers designed specifically for use in elastic laminates, aiming to improve performance while reducing environmental impact.
Market Concentration and Characteristics
The Global Elastic Laminates Market exhibits a moderately concentrated structure, with a mix of well-established multinational corporations and regional players. Key market participants such as Schweitzer-Mauduit International Inc., Berry Global Group Inc., and Mondi Group plc dominate due to their extensive product portfolios, strong R&D investments, and global distribution networks. The market is characterized by high entry barriers, including significant capital requirements and the need for advanced manufacturing technologies. Additionally, the focus on sustainability and compliance with stringent environmental regulations intensifies competition among key players. Despite the dominance of leading companies, smaller regional manufacturers are gaining traction by offering cost-efficient and niche solutions. The market is dynamic, with trends like sustainability, technological advancements, and product customization shaping its evolution across diverse applications in hygiene, medical, and industrial sectors.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global elastic laminates market is projected to grow steadily, reaching an estimated USD 7,095.81 million by 2032, driven by rising demand in hygiene and medical sectors.
- Sustainability will remain a key focus, with manufacturers investing in biodegradable and recyclable laminates to align with environmental regulations and consumer preferences.
- The adoption of advanced manufacturing technologies, such as multi-layer extrusion and automation, will enhance production efficiency and product quality across applications.
- Asia-Pacific, Latin America, and the Middle East & Africa are expected to witness significant growth, driven by rising disposable incomes, population growth, and increased hygiene awareness.
- The medical sector will play a pivotal role in driving demand, with elastic laminates being increasingly used in surgical drapes, wound care products, and protective medical apparel.
- Lightweight elastic laminates with superior elasticity and durability will gain traction, especially in hygiene products where comfort and performance are critical.
- Manufacturers will seek cost-effective raw materials and production techniques to address challenges related to high production costs and price-sensitive markets.
- Demand for tailored laminates will grow as industries seek customized solutions for specific applications in packaging, automotive, and industrial sectors.
- Companies will prioritize compliance with evolving environmental and safety regulations, driving innovation in sustainable and high-performance materials.
- Partnerships, mergers, and acquisitions will rise as market players aim to expand their geographical presence, enhance product offerings, and stay competitive in the evolving market landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Elastic Laminates Market in 2023 and 2032, and what is the CAGR?
What are the key applications of elastic laminates driving market growth?
Which region is expected to witness the fastest growth in the market?
How are sustainability trends influencing the elastic laminates market?
Who are the key players in the Global Elastic Laminates Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Elastic Laminates Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Elastic Laminates Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 5,601.5 million → 2032: USD 7,095.81 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Elastic Laminates Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Elastic Laminates Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Elastic Laminates Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Elastic Laminates Market Drivers
- 3.3 Elastic Laminates Market Restraints & Challenges
- 3.4 Elastic Laminates Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Elastic Laminates Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Elastic Laminates Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Elastic Laminates category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Elastic Laminates Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Elastic Laminates Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Elastic Laminates market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Elastic Laminates Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Elastic Laminates Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Elastic Laminates Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Elastic Laminates (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Elastic Laminates Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Elastic Laminates Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Elastic Laminates Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Elastic Laminates Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Elastic Laminates Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Elastic Laminates Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Elastic Laminates Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Elastic Laminates Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Elastic Laminates Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
