
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Environmental Technology Market Size 2024 | USD 676,105 Million |
| Environmental Technology Market, CAGR | 4.75% |
| Environmental Technology Market Size 2032 | USD 980,045 Million |
Market Overview
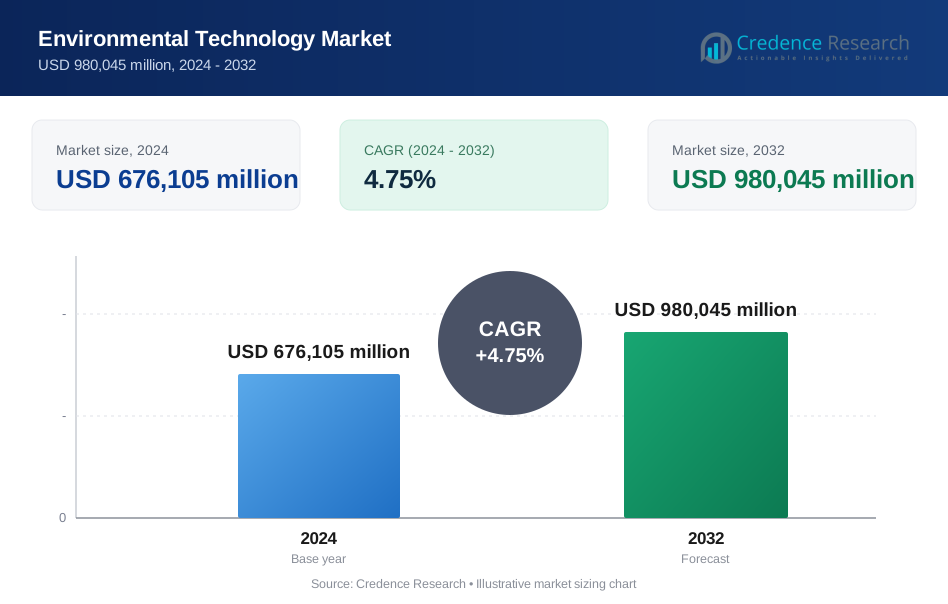
The Environmental Technology Market is projected to grow from USD 676,105 million in 2024 to USD 980,045 million by 2032, at a compound annual growth rate (CAGR) of 4.75%.
The Environmental Technology Market is driven by increasing regulatory pressures and growing public awareness regarding sustainability and environmental protection. Innovations in waste management, renewable energy, and pollution control technologies are gaining traction as governments and organizations seek to reduce their carbon footprints. Additionally, the rise of smart technologies and IoT solutions is facilitating more efficient resource management and energy usage. Trends toward circular economies and sustainable practices are further accelerating the adoption of environmental technologies, making them integral to future development and economic growth. This convergence of factors underscores a robust market trajectory.
The Environmental Technology Market is witnessing significant growth across various regions, with North America and Europe leading in market share due to stringent environmental regulations and technological advancements. Key players like Veolia, SUEZ, and Thermo Fisher Scientific in North America, alongside European leaders such as Total S.A. and Climeworks, are driving innovation and sustainable practices. The Asia-Pacific region is rapidly emerging, fueled by urbanization and increasing awareness of environmental issues, with companies like Hitachi Zosen and Thermax Ltd. making notable contributions. This dynamic landscape highlights the competitive nature of the global environmental technology sector.
Market Drivers
Government Regulations and Policies
Government regulations play a pivotal role in shaping the Environmental Technology Market. Stricter environmental standards are being implemented worldwide to protect public health and the environment, creating a conducive environment for sustainable innovations. For instance, the EPA’s policy for innovative environmental technologies at federal facilities promotes the development and application of new technologies for pollution prevention and remediation. Additionally, policies aimed at reducing carbon emissions, such as carbon taxes and renewable energy mandates, are significantly boosting the demand for cleaner technologies. The influence of the United Nations' Sustainable Development Goals (SDGs) further reinforces this trend, guiding governmental policies and corporate strategies toward sustainable outcomes.
Corporate Social Responsibility (CSR)
As sustainability becomes a central tenet of business operations, companies are increasingly prioritizing corporate social responsibility (CSR). The recognition of sustainability's importance to brand reputation is driving firms to adopt eco-friendly practices. Moreover, environmental risks, including regulatory fines and supply chain disruptions, are compelling organizations to embrace sustainable methods. Investor pressure is also on the rise, as stakeholders demand that companies address environmental, social, and governance (ESG) issues, thus prompting increased investments in sustainable technologies.
Growing Environmental Concerns
Rising global temperatures, extreme weather events, and increasing sea levels have heightened awareness of the urgent need for sustainable solutions. Climate change is now a critical driver behind the demand for environmental technologies. In addition, pollution-be it air, water, or soil-continues to pose significant challenges, pushing stakeholders toward innovative technologies that can effectively mitigate these issues. Furthermore, resource depletion, particularly of finite resources like water and minerals, necessitates the development and implementation of efficient usage and recycling technologies, driving growth in this sector.
Technological Advancements
Technological advancements are transforming the Environmental Technology Market. Breakthroughs in renewable energy, energy storage, water treatment, and waste management are enhancing the efficiency and cost-effectiveness of sustainable solutions. Additionally, the integration of Internet of Things (IoT) and artificial intelligence (AI) allows for real-time monitoring and optimization of environmental systems. Nanotechnology is also making strides, developing advanced materials and processes for applications such as water purification and pollution remediation, thereby paving the way for innovative environmental solutions.
Market Trends
Increased Focus on Circular Economy and Renewable Energy Advancements
The shift toward a circular economy is gaining momentum as organizations prioritize waste reduction and resource recovery. Technologies aimed at minimizing waste generation are increasingly being adopted, including innovative waste-to-energy plants, advanced recycling techniques, and sustainable packaging solutions. For instance, the Circulars Accelerator, led by Accenture, is supporting innovators like Biohm, which creates building materials from mushrooms and food waste. Companies are also focusing on product lifecycles, designing items with longer lifespans, reusability, and recyclability to mitigate environmental impact. This proactive approach not only reduces waste but also aligns with consumer demand for sustainable practices. Simultaneously, advancements in renewable energy are transforming the energy landscape. Solar and wind energy have become more cost-effective than traditional fossil fuels, driving widespread adoption across various sectors. Coupled with significant progress in battery technology, efficient energy storage solutions are now available, addressing the intermittency challenges associated with renewable sources. Emerging technologies such as wave, tidal, and geothermal energy are also gaining attention as viable clean energy alternatives, further diversifying the renewable energy portfolio.
Digitalization, Water Innovations, and Sustainable Agriculture
Digitalization and IoT integration are playing a crucial role in enhancing sustainability efforts, particularly in smart city initiatives. Environmental technologies are being incorporated into these projects to improve resource management, reduce pollution, and promote sustainability. IoT devices are increasingly used to monitor environmental parameters, optimize operational efficiency, and enable predictive maintenance, which collectively enhance urban living conditions. Additionally, innovations in water and wastewater treatment are addressing growing concerns over water scarcity and quality. Advanced treatment technologies, such as membrane filtration, reverse osmosis, and advanced oxidation processes, are improving wastewater management. Solutions like desalination and rainwater harvesting are becoming essential in regions facing significant water challenges. Furthermore, sustainable agriculture practices are evolving with precision agriculture technologies, including drones and data analytics, which enable more efficient farming. Urban areas are witnessing a rise in vertical farming techniques, reducing the environmental footprint of traditional agriculture. Together, these trends illustrate a comprehensive commitment to sustainability across multiple sectors, emphasizing the critical role of innovative technologies in addressing environmental challenges.
Market Challenges Analysis
High Initial Investment and Regulatory Uncertainty
One of the primary challenges facing the environmental technology market is the high initial investment required for implementation. Capital costs can be substantial, presenting a significant barrier for smaller businesses and developing countries that may lack the necessary financial resources. For instance, a survey conducted by the International Energy Agency (IEA) highlighted that the upfront costs for renewable energy projects are often prohibitive for small enterprises. Although the long-term environmental benefits of these technologies are well-documented, achieving a quick return on investment (ROI) remains challenging, particularly for projects with extended payback periods. This financial hurdle can dissuade potential investors and slow the adoption of innovative solutions. Compounding this issue is regulatory uncertainty, where frequent changes in environmental policies can create an unpredictable investment landscape. Businesses must navigate the complexities of adhering to diverse and evolving regulations, which can lead to increased compliance costs, particularly for those operating across multiple jurisdictions. This uncertainty can stifle innovation, as companies may hesitate to invest in new technologies when future regulations remain unclear.
Technological Maturity and Consumer Adoption Challenges
Technological maturity also presents significant obstacles in the environmental technology sector. Many emerging technologies are still in their early development stages, limiting their scalability and commercial viability. Ensuring the reliability and efficiency of these innovations, especially under demanding environmental conditions, poses additional challenges for manufacturers. Furthermore, consumer adoption of environmental technologies requires overcoming barriers related to awareness and education. Consumers often need to be informed about the long-term benefits of sustainable products and services to counteract initial cost hesitations. Additionally, addressing misconceptions surrounding these technologies is crucial for encouraging broader acceptance. Beyond individual consumer challenges, supply chain issues complicate the sourcing of sustainable materials, particularly in emerging markets. Manufacturing processes must also align with environmental goals, adding another layer of complexity. Moreover, competition from traditional industries can hinder growth; established players may resist adopting new technologies due to economic interests and fears of job displacement. As such, overcoming these multifaceted challenges is essential for advancing the environmental technology market and achieving sustainable development objectives.
Market Segmentation Analysis:
By Component:
The Environmental Technology Market is segmented into two primary components: solutions and services. Solutions encompass a wide range of innovative technologies designed to address environmental challenges. These include advanced systems for wastewater treatment, water purification management, and pollution control. Services complement these solutions, providing essential support in areas such as wastewater and water treatment, resource recovery, and industrial remediation. Companies increasingly seek consulting and engineering services to optimize their environmental impact and achieve compliance with regulations. The integration of these components allows organizations to adopt comprehensive strategies that not only enhance operational efficiency but also contribute to sustainable resource management. As awareness of environmental issues continues to grow, the demand for both solutions and services is expected to rise, driving further investments in innovative technologies.
By Application:
The Environmental Technology Market can also be analyzed based on various applications, which include wastewater treatment, water purification management, sewage treatment, and pollution monitoring. These applications are vital for mitigating environmental degradation and ensuring public health. Wastewater treatment technologies are critical for converting wastewater into reusable resources, while water purification management systems focus on delivering clean drinking water. Additional applications such as solid waste treatment and energy generation from waste are gaining traction, reflecting the shift towards circular economy principles. Moreover, pollution monitoring technologies are increasingly essential for measuring and managing emissions, including dust and gas dissipation. Applications like precision cooling and crop monitoring further illustrate the versatility of environmental technologies across different sectors. As regulatory pressures and environmental concerns intensify, the adoption of these applications is poised to increase, supporting the overall growth of the market.
Segments:
Based on Component:
- Solutions
- Services (wastewater & water treatment, resource recovery, consulting & engineering, industrial remediation, water utility)
Based on Application:
- Wastewater treatment
- Water purification management
- Sewage treatment
- Pollution monitoring
- Dust emissions
- Dry steaming
- Gas dissolution
- Precision cooling
- Solid waste treatment
- Energy source for power generation and fuel
- Others (crop monitoring, soil monitoring/ soil analysis, and fire detection)
Based on Technological Solutions:
- Waste valorization/ recycling & composting
- Greentech/renewable energy (wind energy, photovoltaics, and geothermal energy)
- Desalination
- Bioremediation
- Green hydrogen
- Carbon capture, utilization & storage (ccus)
- Others (air pollution monitoring, otec, biofuels and ocean plastic)
Based on Vertical:
- Residential/municipal
- Industrial transportation & logistics
- Power, energy & utilities
- Manufacturing
- Retail & consumer goods
- Construction & building materials
- Government & defense
- Oil & gas
- Others (law enforcement, healthcare & life sciences)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The Environmental Technology Market holds a significant share in North America, accounting for approximately 35% of the global market. This dominance is driven by stringent environmental regulations and a growing emphasis on sustainability among consumers and businesses. The United States, in particular, has implemented comprehensive policies aimed at reducing greenhouse gas emissions and promoting renewable energy sources. Key players in the region are investing heavily in innovative technologies for water purification, wastewater treatment, and pollution control. The presence of advanced infrastructure and robust research and development initiatives further enhances the market's growth potential. Additionally, the rising awareness of climate change and its impacts has prompted governments and organizations to adopt environmentally friendly practices, thereby fueling demand for advanced environmental technologies.
Asia-Pacific
The Asia-Pacific region is emerging as a dynamic force in the Environmental Technology Market, with a market share exceeding 25%. Rapid urbanization, population growth, and increasing industrial activities have led to heightened environmental challenges, prompting countries like China and India to prioritize sustainable solutions. Governments are implementing stringent regulations to address pollution and resource depletion, driving investments in technologies for wastewater treatment and solid waste management. Moreover, the rising demand for clean drinking water and effective waste management systems is accelerating the adoption of advanced environmental technologies. As the region continues to develop economically, there is a growing focus on integrating sustainable practices into industrial processes and urban planning. This trend is expected to further boost the market, making Asia-Pacific a crucial area for future developments in environmental technology.
Key Player Analysis
- Veolia (France)
- Carbon Engineering (Canada)
- Biffa (UK)
- Covanta Holding Corporation (US)
- TRC Companies, Inc. (US)
- Carbon Clean (UK)
- Total S.A. (France)
- AECOM (US)
- Skrap (India)
- Intelex (Canada)
- Thermo Fisher Scientific Inc. (US)
- Waste Connections (US)
- Geo-Cleanse International, Inc. (US)
- Arcadis N.V. (Netherlands)
- Xylem, Inc. (US)
- Hitachi Zosen Corporation (Japan)
- Recycling Technologies (UK)
- C-Capture (UK)
- Sunfire GmbH (Germany)
- Climeworks (Switzerland)
- CarbonCure Technologies Inc. (Canada)
- Cypher Environmental (Canada)
- SUEZ (US)
- Engie Impact (US)
- Ivey International Inc. (Canada)
- Svante Inc. (Canada)
- BacTech Inc. (Canada)
- Thermax Ltd. (India)
- REMONDIS SE & Co. KG (Germany)
- Tandem Technical (Canada)
- RecyGlo (Myanmar)
- Recycle Track Systems (US)
- Vital Waste (India)
- GEM Enviro Management Pvt. Ltd (India)
- UnBound Chemicals (Canada)
- Pycno (UK)
- Saahas Zero Waste (India)
- Trade Genomics (US)
Competitive Analysis
The competitive landscape of the Environmental Technology Market is characterized by several prominent players focused on innovation and sustainable solutions. Key companies such as AECOM, Veolia, SUEZ, Thermo Fisher Scientific Inc., and Total S.A. are at the forefront, each leveraging advanced technologies to address environmental challenges. Leading companies are focused on developing advanced solutions to address pressing environmental challenges such as pollution, waste management, and resource conservation. They leverage cutting-edge technologies, including IoT and AI, to enhance operational efficiency and deliver sustainable outcomes. Collaboration with governmental bodies and compliance with stringent regulations further drive their market strategies. Moreover, the emphasis on sustainability and corporate social responsibility has led these companies to invest in research and development, ensuring they stay ahead of emerging trends. The competitive environment is dynamic, with firms striving to differentiate themselves through unique product offerings and comprehensive service solutions tailored to diverse customer needs.
Recent Developments
- In June 2024, AECOM and Aquatech announced an agreement to accelerate the deployment of PFAS destruction technology.
- In June 2024, Biffa acquired Hazrem Environmental Ltd, aligning with its strategic growth ambitions.
- In October 2023, Veolia North America completed the acquisition of U.S. Industrial Technologies, expanding its hazardous waste treatment business
- In June 2023, TRC Companies acquired Gladstein, Neandross & Associates (GNA), expanding its climate solutions with sustainable transportation technologies.
Market Concentration & Characteristics
The Environmental Technology Market exhibits moderate concentration, characterized by a mix of established players and emerging companies. Leading firms dominate key segments, leveraging their technological expertise and extensive distribution networks to capture significant market shares. The industry is marked by rapid innovation, driven by the urgent need to address environmental issues such as pollution and resource depletion. Companies invest heavily in research and development to create advanced solutions that align with evolving regulatory standards and consumer expectations. Additionally, the market features a variety of specialized firms that focus on niche applications, enhancing the competitive landscape. The emphasis on sustainability and corporate responsibility fosters collaboration between businesses and governmental organizations, further shaping market dynamics. Overall, the Environmental Technology Market reflects a blend of competitive intensity and collaborative opportunities, positioning itself for continued growth as global environmental concerns escalate.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Technological Solutions, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Environmental Technology Market is expected to witness robust growth driven by increasing global environmental concerns.
- Innovations in renewable energy technologies will continue to enhance cost-effectiveness and adoption rates.
- The circular economy model will gain traction, promoting waste reduction and resource recovery initiatives.
- Government regulations focused on sustainability will create more opportunities for technological advancements.
- Digitalization and IoT integration will improve efficiency in monitoring and managing environmental systems.
- Investments in water treatment technologies will rise as water scarcity becomes a critical issue globally.
- Carbon capture and storage solutions will evolve, playing a vital role in mitigating climate change impacts.
- Corporate sustainability initiatives will drive demand for environmentally friendly products and services.
- Increased collaboration between private and public sectors will facilitate the development of innovative solutions.
- The focus on environmental, social, and governance (ESG) criteria will influence investment decisions and corporate strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Regulations and Policies
Stricter environmental standards and policies, such as carbon taxes and renewable energy mandates, are compelling organizations to adopt advanced environmental technologies to comply with legal requirements and avoid penalties.
Corporate Social Responsibility (CSR) and ESG Pressure
Companies are increasingly prioritizing sustainability to enhance brand reputation and meet investor expectations, leading to greater investment in eco-friendly technologies and solutions.
Growing Environmental Concerns
Rising awareness of climate change, pollution, and resource depletion is driving demand for technologies that mitigate environmental impact and promote sustainable resource use.
Technological Advancements
Innovations in areas like IoT, AI, renewable energy, and advanced water treatment are making environmental technologies more efficient and cost-effective, accelerating their adoption across industries.
Shift Toward Circular Economy
The move toward circular economy models is encouraging the adoption of technologies that enable waste reduction, resource recovery, and sustainable product lifecycles, further fueling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Environmental Technology Market?
What factors are driving the growth of the Environmental Technology Market?
What are the key segments within the Environmental Technology Market?
What are some challenges faced by the Environmental Technology Market?
Who are the major players in the Environmental Technology Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vertical
- 1.2.1 Residential/municipal
- 1.2.2 Industrial transportation & logistics
- 1.2.3 Power, energy & utilities
- 1.2.4 Manufacturing
- 1.2.5 Construction & building materials
- 1.2.6 Government & defense
- 1.3 By Component
- 1.3.1 Solutions
- 1.3.2 Services (wastewater & water treatment, resource recovery, consulting & engineering, industrial remediation, water utility)
- 1.4 By Application
- 1.4.1 Wastewater treatment
- 1.4.2 Water purification management
- 1.4.3 Sewage treatment
- 1.4.4 Pollution monitoring
- 1.4.5 Solid waste treatment
- 1.4.6 Energy source for power generation and fuel
- 1.5 By Technological Solution
- 1.5.1 Waste valorization/recycling & composting
- 1.5.2 Greentech/renewable energy (wind, photovoltaics, geothermal)
- 1.5.3 Desalination
- 1.5.4 Bioremediation
- 1.5.5 Green hydrogen
- 1.5.6 Carbon capture, utilization & storage (CCUS)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 676,105 million → 2032: USD 980,045 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Environmental Technology Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Environmental Technology Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Environmental Technology Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Environmental Technology Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Environmental Technology Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Environmental Technology Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Environmental Technology Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Environmental Technology Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 676,105 million → 2032: USD 980,045 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Environmental Technology Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vertical - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential/municipal
- 12.3.7.2 Industrial transportation & logistics
- 12.3.7.3 Power, energy & utilities
- 12.3.7.4 Manufacturing
- 12.3.7.5 Construction & building materials
- 12.3.7.6 Government & defense
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solutions
- 12.4.7.2 Services (wastewater & water treatment, resource recovery, consulting & engineering, industrial remediation, water utility)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wastewater treatment
- 12.5.7.2 Water purification management
- 12.5.7.3 Sewage treatment
- 12.5.7.4 Pollution monitoring
- 12.5.7.5 Solid waste treatment
- 12.5.7.6 Energy source for power generation and fuel
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technological Solution - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Waste valorization/recycling & composting
- 12.6.7.2 Greentech/renewable energy (wind, photovoltaics, geothermal)
- 12.6.7.3 Desalination
- 12.6.7.4 Bioremediation
- 12.6.7.5 Green hydrogen
- 12.6.7.6 Carbon capture, utilization & storage (CCUS)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Environmental Technology End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Environmental Technology Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Environmental Technology Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Environmental Technology Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Veolia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SUEZ
- 18.4 Thermo Fisher Scientific Inc.
- 18.5 Total S.A.
- 18.6 Climeworks
- 18.7 Hitachi Zosen Corporation
- 18.8 AECOM
- 18.9 Biffa
- 18.10 TRC Companies, Inc.
- 18.11 Xylem, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

