
Market Overview
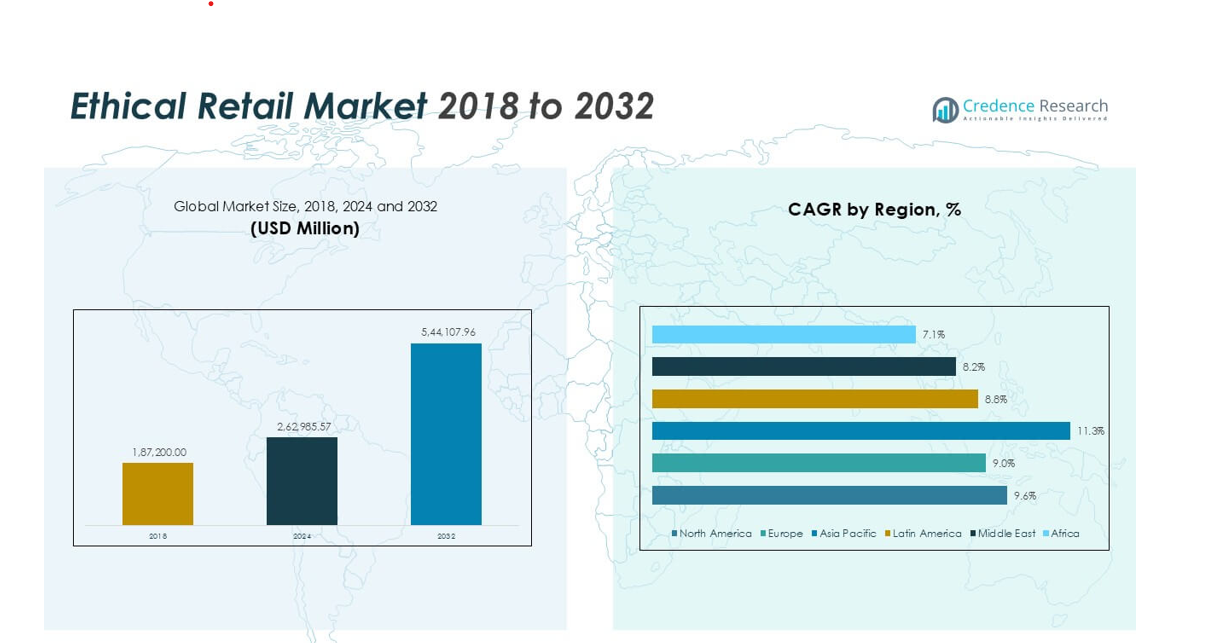
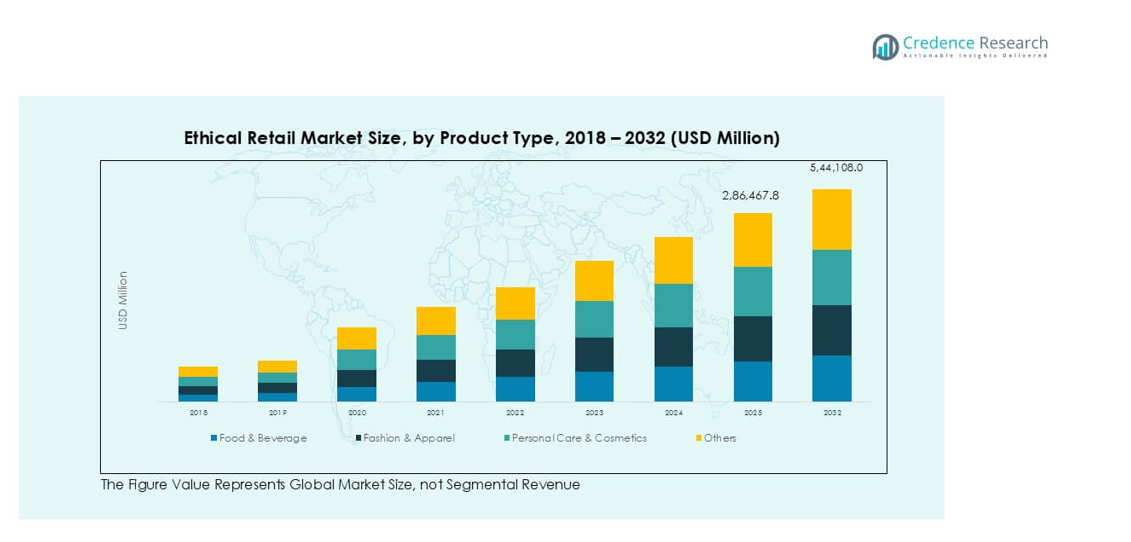
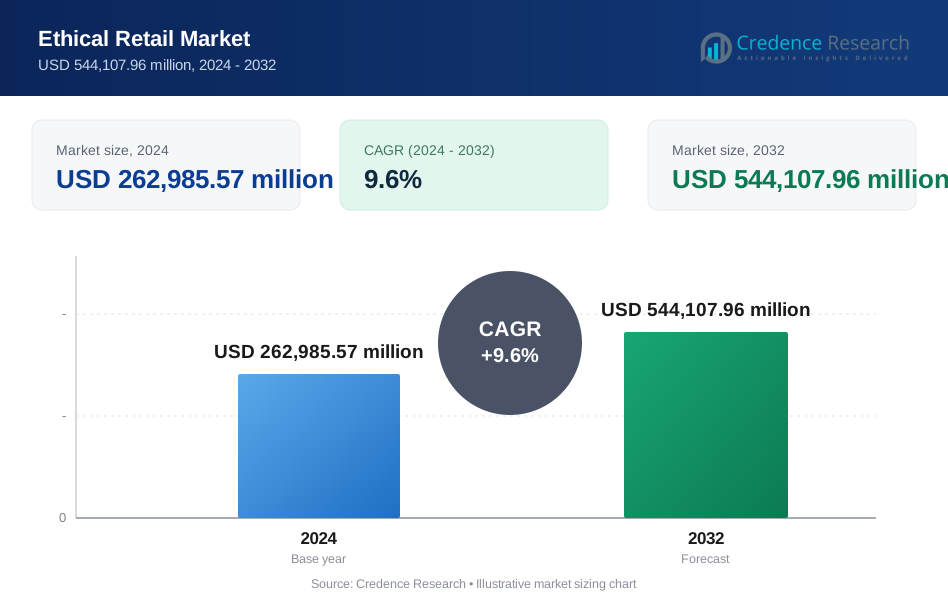
The Ethical Retail market size was valued at USD 187,200.00 million in 2018, increasing to USD 262,985.57 million in 2024, and is anticipated to reach USD 544,107.96 million by 2032, at a CAGR of 9.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ethical Retail Market Size 2024 | USD 262,985.57 million |
| Ethical Retail Market, CAGR | 9.60% |
| Ethical Retail Market Size 2032 | USD 544,107.96 million |
Top players in the ethical retail market include The Co-operative Group, Marks & Spencer, Patagonia, Ben & Jerry’s, Trader Joe’s, Seventh Generation, Lush Fresh Handmade Cosmetics, Eileen Fisher, Unilever, and Nestlé. These companies compete by emphasizing sustainability, fair trade, cruelty-free practices, and eco-friendly packaging. Europe leads the global market with 33% share in 2024, driven by strict regulations and high consumer awareness, while North America follows with 32% share, supported by advanced retail infrastructure. Asia Pacific holds 20% share and is the fastest-growing region, expanding at a CAGR of 11.3% due to rising middle-class demand and e-commerce penetration.
Market Insights
- The Ethical Retail market was valued at USD 262,985.57 million in 2024 and is projected to reach USD 544,107.96 million by 2032, growing at a CAGR of 9.6%.
- Rising consumer demand for sustainable, fair-trade, and eco-friendly products is the key driver, with food & beverage leading the type segment at nearly 40% share in 2024.
- Market trends highlight the growth of plant-based products, circular economy practices, and premiumization of ethical goods, especially in fashion and personal care.
- The competitive landscape includes The Co-operative Group, Marks & Spencer, Patagonia, Unilever, and Nestlé, with strategies focused on transparency, ethical sourcing, and expanding sustainable product portfolios.
- Europe dominated the market with 33% share in 2024, followed by North America at 32% and Asia Pacific at 20%, the latter being the fastest-growing region; Millennials and Gen Z accounted for over 55% share among demographics, while online retail led with 45% share by distribution channel.
Market Segmentation Analysis:
By Type
The food & beverage segment held the largest share of the ethical retail market in 2024, representing nearly 40%. Its dominance stems from growing consumer preference for organic, fair-trade, and sustainably sourced food items. Rising demand for plant-based products and eco-friendly packaging continues to strengthen this category. Fashion & apparel followed closely, benefiting from the rising adoption of sustainable textiles and slow-fashion practices. Personal care & cosmetics, home & lifestyle products, and others remain important but secondary, largely driven by niche consumer preferences for cruelty-free, natural, and responsibly sourced goods.
- For instance, Nestlé launched a plant-based meat facility in Tianjin, China in 2020, with an annual production capacity of 8,000 metric tons to serve Asia’s growing ethical food demand
By Consumer Demographics
Millennials and Gen Z dominated the ethical retail market in 2024, accounting for over 55% share. These groups are highly conscious buyers who actively prioritize sustainability, transparency, and ethical sourcing in their purchase decisions. They prefer brands with clear environmental and social responsibility commitments, driving demand for eco-friendly and fair-trade products. Gen X holds a moderate share, with a focus on value and authenticity in sustainable offerings. Baby Boomers contribute the smallest portion, though their interest in health-focused and organic products continues to provide steady demand growth in specific categories like food and wellness.
- For instance, Patagonia’s Worn Wear program repaired over 100,000 garments in 2022, directly appealing to young consumers seeking sustainable reuse options.
By Distribution Channel
Online retail and e-commerce emerged as the leading distribution channel, securing nearly 45% market share in 2024. The shift is driven by younger consumers’ digital-first purchasing behavior and the availability of wide product choices online. Supermarkets and hypermarkets remain strong contributors, offering accessibility and trust in certified sustainable products. Specialty stores continue to attract niche buyers seeking premium ethical brands, while convenience stores maintain smaller yet growing adoption in urban areas. Other formats, such as community-based retail and farmer markets, add diversity, particularly where consumers prioritize traceability and direct engagement with sustainable producers.
Market Overview
Rising Consumer Demand for Sustainable Products
Growing consumer awareness of environmental and social issues is a major driver of ethical retail. Shoppers increasingly seek products that are eco-friendly, cruelty-free, and sourced responsibly. Millennials and Gen Z, in particular, emphasize values-driven consumption, creating strong demand for sustainable brands. Companies are responding with organic food, plant-based alternatives, fair-trade apparel, and low-impact packaging. This shift is reshaping the competitive landscape, as retailers must adapt product lines to meet sustainability expectations. Transparency in sourcing and production now influences purchase decisions, and brands showcasing certifications or clear ethical practices gain higher trust. The steady rise of this conscious consumer base ensures long-term growth for ethical retail across industries.
- For instance, Beyond Meat's business is centered on producing and supplying plant-based protein to major retailers worldwide, addressing consumer demand for sustainable consumption. In 2022, the company reported a revenue of $418.9 million, though it faced market challenges that year, including a net loss and a decline in product volume.
Government Policies and Regulatory Support
Supportive regulations and global sustainability initiatives are fueling growth in the ethical retail sector. Governments across North America, Europe, and Asia are implementing policies that promote sustainable production and consumption. Regulations like the EU Green Deal, bans on single-use plastics, and stricter labor laws push retailers toward ethical compliance. Incentives for renewable energy use, recyclable packaging, and sustainable sourcing further boost adoption. Ethical certification standards, including Fair Trade and Organic labels, add credibility, driving higher consumer acceptance. Retailers adopting these practices not only meet regulatory standards but also strengthen brand reputation. The growing alignment of ethical retail with government-backed sustainability goals positions the market for strong expansion.
- For instance, Tesco did announce a goal to remove one billion pieces of plastic from its UK business by the end of 2020 and has reported achieving significant reductions by that time and beyond.
Digital Transformation and E-Commerce Expansion
The rise of e-commerce platforms has accelerated the growth of ethical retail globally. Online channels allow retailers to highlight transparency by showcasing product origins, certifications, and sustainability commitments directly to consumers. Social media also plays a critical role in shaping consumer perception, as ethically conscious brands leverage storytelling to attract younger audiences. Direct-to-consumer (DTC) platforms and digital marketplaces enable niche sustainable brands to compete with established retailers. Subscription models for eco-friendly goods, along with digital loyalty programs, further strengthen consumer engagement. As online retail continues to expand, digital visibility and ethical branding will drive stronger consumer connections and higher sales in the ethical retail space.
Key Trends & Opportunities
Growing Popularity of Circular Economy Practices
Circular economy principles are becoming a defining trend in the ethical retail market. Retailers are adopting practices such as recycling programs, resale platforms, and take-back schemes to extend product lifecycles. In fashion, second-hand and rental models are gaining traction, supported by digital platforms. Food retailers are adopting zero-waste packaging and upcycled ingredients to reduce environmental impact. These practices not only appeal to environmentally conscious consumers but also create opportunities for cost savings and brand differentiation. Retailers investing in circular solutions strengthen sustainability credentials and capture emerging demand for waste-reduction initiatives.
- For instance, H&M's garment collection initiative collected over 15,000 tons of textiles in 2022. However, the vast majority of these textiles were not recycled into new T-shirts, and the initiative has been criticized as greenwashing.
Expansion of Plant-Based and Ethical Food Choices
Plant-based food and beverages represent one of the fastest-growing opportunities in ethical retail. Consumers are shifting away from animal-based products toward healthier and environmentally friendly alternatives. Retailers offering plant-based dairy, meat substitutes, and organic produce see increasing market traction. Ethical sourcing in beverages such as coffee, tea, and cocoa also drives demand, particularly for fair-trade certified products. Restaurants, supermarkets, and e-commerce channels are expanding plant-based offerings, tapping into both vegan and flexitarian consumers. This trend not only supports sustainable farming but also strengthens the position of food as the leading segment in ethical retail.
Premiumization and Brand Differentiation
Premium ethical products are gaining popularity as consumers equate sustainability with quality and exclusivity. Brands offering responsibly sourced raw materials, artisanal production, and eco-friendly packaging are positioned as premium choices. This creates opportunities for retailers to differentiate themselves and command higher price points. In fashion, sustainable luxury apparel is becoming a key focus, while in personal care, natural and cruelty-free cosmetics drive premium demand. As consumer willingness to pay more for ethical products rises, premiumization is shaping new growth strategies across ethical retail categories.
Key Challenges
High Cost of Sustainable Production
One of the biggest challenges in ethical retail is the high cost of producing sustainable goods. Ethical sourcing, eco-friendly packaging, and compliance with certification standards often raise operational expenses. Smaller retailers and emerging brands struggle with scalability, as they lack resources to absorb higher costs. This creates price gaps between ethical and conventional products, limiting adoption among cost-sensitive consumers. For retailers, balancing affordability with ethical standards remains a key challenge. Unless supply chain efficiencies and technology reduce costs, widespread consumer adoption may face barriers, especially in developing markets where affordability drives purchase behavior.
Greenwashing and Lack of Standardization
Greenwashing poses a major challenge in the ethical retail market, as some brands make misleading claims about sustainability. Without clear global standards, consumers face difficulty distinguishing authentic ethical products from deceptive marketing. This erodes trust and slows adoption, particularly among skeptical buyers. While certifications like Fair Trade and Organic help build credibility, their limited scope and regional variations create inconsistencies. Retailers that fail to back claims with evidence risk reputational damage. Establishing global standards and improving transparency across supply chains will be critical to overcoming greenwashing and sustaining growth in the ethical retail sector.
Regional Analysis
North America
North America accounted for the largest share of the ethical retail market in 2024, valued at USD 84,311.59 million, rising from USD 60,840.00 million in 2018. The market is projected to reach USD 174,169.94 million by 2032, expanding at a CAGR of 9.6%. The region held nearly 32% share in 2024, driven by strong consumer awareness and advanced retail infrastructure. Increasing demand for organic food, sustainable fashion, and fair-trade products supports growth. Government regulations promoting eco-friendly packaging and corporate responsibility also enhance adoption across retail categories, strengthening North America’s leadership in the market.
Europe
Europe captured the second-largest share of the ethical retail market in 2024, generating USD 88,566.35 million, up from USD 64,958.40 million in 2018. By 2032, the market is expected to reach USD 175,612.29 million, recording a CAGR of 9.0%. The region represented about 33% share in 2024, supported by strict regulatory frameworks such as the EU Green Deal and widespread adoption of fair-trade practices. High consumer preference for sustainable apparel, eco-label cosmetics, and organic food continues to drive expansion. Europe’s strong institutional backing and consumer-driven sustainability focus make it a pivotal market for ethical retail.
Asia Pacific
Asia Pacific emerged as the fastest-growing region, valued at USD 52,556.56 million in 2024, rising from USD 35,380.80 million in 2018. It is forecasted to reach USD 123,132.07 million by 2032, growing at a CAGR of 11.3%. The region accounted for nearly 20% share in 2024, fueled by rapid urbanization, rising disposable incomes, and increasing sustainability awareness among younger consumers. Expanding e-commerce platforms further accelerate access to ethical products, especially in China, India, and Southeast Asia. Strong demand for plant-based food and sustainable personal care products positions Asia Pacific as a major growth driver for the global market.
Latin America
Latin America recorded a market size of USD 20,746.93 million in 2024, compared to USD 14,882.40 million in 2018, and is expected to reach USD 40,465.30 million by 2032. The region is growing at a CAGR of 8.8% and held around 8% share in 2024. Ethical retail adoption is rising, driven by growing consumer awareness of fair-trade coffee, cocoa, and organic produce. Brazil and Mexico lead the market, supported by expanding retail networks and local sustainability initiatives. Despite challenges in affordability, increasing interest in eco-friendly and socially responsible brands supports steady regional growth.
Middle East
The Middle East ethical retail market was valued at USD 9,360.58 million in 2024, up from USD 7,113.60 million in 2018, and is projected to reach USD 17,468.86 million by 2032. The market is expanding at a CAGR of 8.2% and captured about 4% share in 2024. Growth is supported by rising demand for sustainable luxury fashion, organic food, and eco-friendly lifestyle products, especially in Gulf Cooperation Council (GCC) countries. Increasing government focus on sustainability in line with Vision 2030 strategies is further driving demand, although high costs of ethical goods remain a barrier for mass adoption.
Africa
Africa represented the smallest share of the ethical retail market in 2024, with USD 7,443.56 million, up from USD 4,024.80 million in 2018. By 2032, the market is expected to reach USD 13,259.50 million, growing at a CAGR of 7.1%. The region accounted for nearly 3% share in 2024. Growth is supported by rising interest in fair-trade agricultural exports and eco-conscious local products. South Africa leads regional adoption, with gradual expansion in Nigeria and Kenya through e-commerce. However, limited purchasing power and lack of awareness pose challenges. Still, Africa presents untapped opportunities for sustainable retail models in the long term.
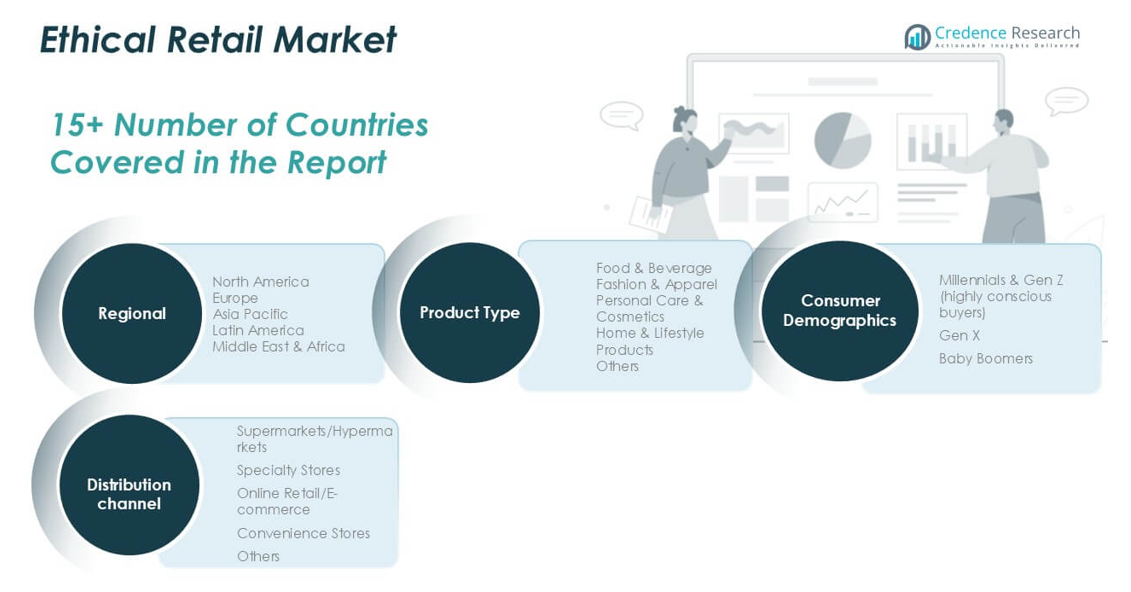
Market Segmentations:
By Type
- Food & Beverage
- Fashion & Apparel
- Personal Care & Cosmetics
- Home & Lifestyle Products
- Others
By Consumer Demographics
- Millennials & Gen Z (highly conscious buyers)
- Gen X
- Baby Boomers
By Distribution Channel
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Retail/E-commerce
- Convenience Stores
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the ethical retail market is shaped by a mix of multinational corporations, specialty retailers, and purpose-driven brands. Leading players such as The Co-operative Group, Marks & Spencer, Patagonia, Ben & Jerry’s, Trader Joe’s, and Seventh Generation, Inc. have built strong reputations by aligning business models with sustainability and social responsibility. Companies like Lush Fresh Handmade Cosmetics and Eileen Fisher emphasize transparency, cruelty-free practices, and ethical sourcing, while global giants such as Unilever and Nestlé expand their sustainable product lines to meet rising consumer demand. Competition centers on differentiation through eco-friendly packaging, fair-trade certifications, and digital storytelling to engage ethically conscious buyers. Smaller niche brands leverage authenticity and direct-to-consumer channels to compete with established players. Strategic partnerships, product innovation, and expansion into emerging markets remain critical for growth. As consumer expectations for sustainability continue to rise, ethical credibility and brand trust have become the most decisive competitive factors.
Key Player Analysis
- The Co-operative Group
- Marks & Spencer
- Patagonia, Inc.
- Ben & Jerry’s Homemade, Inc.
- Trader Joe’s
- Seventh Generation, Inc.
- Lush Fresh Handmade Cosmetics
- Eileen Fisher, Inc.
- Unilever (Sustainable Living Brands)
- Nestlé (Ethical & Sustainable Product Lines)
Recent Developments
- In September 2025, Ben & Jerry’s Homemade, Inc. Co-founder Jerry Greenfield resigned, citing loss of the brand’s independent social mission under Unilever.
- In August 2025, Marks & Spencer (M&S) announced a £340 million investment to build a new, automated National Distribution Centre (NDC) in Northamptonshire, England.
- In August 2025, Marks & Spencer launched a secondhand clothing store on eBay; donors get £5 vouchers; Oxfam gets share.
- In June 2025, the Co-operative Group announced it will phase out sourcing from 17 countries linked to human-rights abuses (e.g. Israel, Russia).
Report Coverage
The research report offers an in-depth analysis based on Type, Consumer Demographics, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The ethical retail market will continue to expand steadily with strong global demand.
- Food and beverage products will remain the dominant category driven by sustainable sourcing.
- Millennials and Gen Z will lead future purchases, shaping market direction with conscious choices.
- Online retail will grow further as digital-first consumers seek transparency and convenience.
- Circular economy practices such as recycling and resale will gain wider adoption across segments.
- Premiumization of ethical products will create opportunities for higher margins and brand differentiation.
- Regulatory frameworks will tighten, pushing retailers toward stricter sustainability compliance.
- Emerging markets in Asia Pacific will see rapid growth due to rising incomes and awareness.
- Competition will intensify as global corporations and niche brands expand sustainable portfolios.
- Trust and authenticity will remain critical, making transparency and verified claims essential for growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ethical Retail market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ethical Retail market projected to grow between 2025 and 2032?
Which Ethical Retail market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ethical Retail market?
Who are the leading companies in the Ethical Retail market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 262,985.57 million → 2032: USD 544,107.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Ethical Retail Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Ethical Retail Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Ethical Retail Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Ethical Retail Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Ethical Retail Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Ethical Retail Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Ethical Retail Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Ethical Retail Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 262,985.57 million → 2032: USD 544,107.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Ethical Retail Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Ethical Retail Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Ethical Retail Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Ethical Retail Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.