
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Addiction Treatment Market Size 2023 | USD 2,436.26 million |
| Europe Addiction Treatment Market, CAGR | 5.89% |
| Europe Addiction Treatment Market Size 2032 | USD 4,140.86 million |
Market Overview
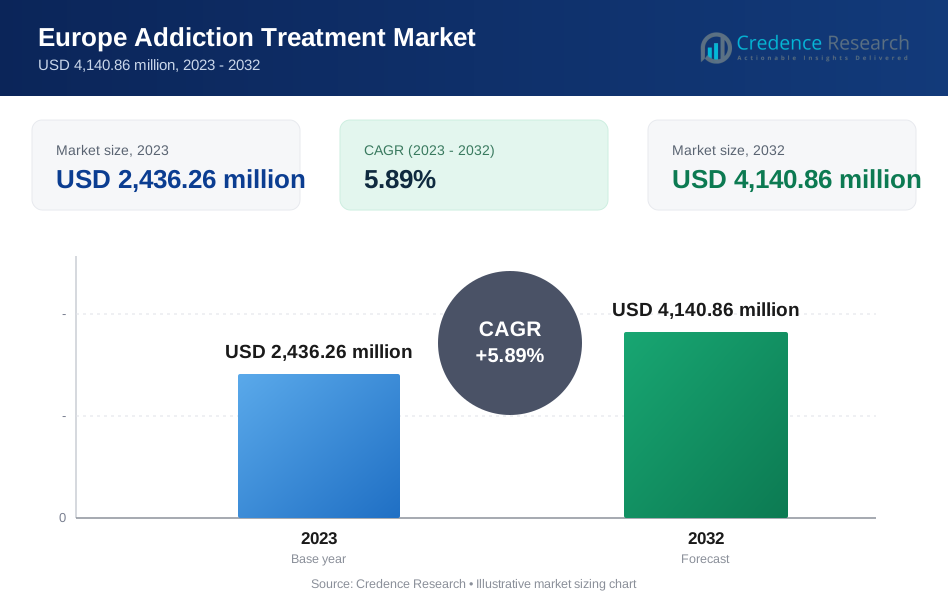
The Europe Addiction Treatment Market is projected to grow from USD 2,436.26 million in 2023 to an estimated USD 4,140.86 million by 2032, with a compound annual growth rate (CAGR) of 5.89% from 2024 to 2032. This growth is driven by increasing awareness of mental health issues, improved access to treatment facilities, and rising government initiatives to combat addiction.
Several factors drive this growth, including the increasing prevalence of substance abuse disorders and advancements in treatment methodologies. The integration of technology in treatment programs, such as telemedicine and mobile health applications, has enhanced the reach and effectiveness of addiction treatments. Additionally, a growing societal acceptance of seeking help for addiction problems and the destigmatization of mental health issues contribute to market expansion.
Geographically, Western Europe holds the largest market share, primarily due to the high availability of advanced healthcare infrastructure and supportive government policies. Key players in the market include prominent organizations such as Acadia Healthcare, Universal Health Services, and Pinnacle Treatment Centers. These companies are focused on expanding their services and improving treatment outcomes through innovative approaches and strategic partnerships, ensuring sustained growth in the Europe Addiction Treatment Market.
Market Drivers
Increasing Prevalence of Substance Abuse Disorders
The rising incidence of substance abuse disorders across Europe is a primary driver of the addiction treatment market. For instance, it was estimated that 5.5 percent of the global population between the ages of 15 and 64 years used an illicit drug in 2019. Substance abuse, encompassing alcohol, illicit drugs, and prescription medications, is becoming increasingly prevalent, impacting individuals and societies. According to the European Monitoring Centre for Drugs and Drug Addiction (EMCDDA), millions of Europeans are affected by substance use disorders, necessitating comprehensive treatment and rehabilitation services. The increasing number of affected individuals has created a substantial demand for addiction treatment services, ranging from detoxification to long-term rehabilitation programs. Moreover, the complexity of substance abuse disorders, which often co-occur with mental health issues such as depression and anxiety, further intensifies the need for integrated treatment approaches. The dual diagnosis of mental health and addiction issues requires specialized care, prompting healthcare providers to develop and offer multifaceted treatment programs. This rising demand for comprehensive care drives the expansion and sophistication of addiction treatment facilities across Europe
Advancements in Treatment Methodologies and Technologies
Innovations in treatment methodologies and the integration of advanced technologies have significantly contributed to the growth of the Europe addiction treatment market. Traditional treatment approaches, such as inpatient and outpatient rehabilitation programs, have evolved to incorporate evidence-based practices, ensuring more effective and personalized care for individuals battling addiction. The use of cognitive-behavioral therapy (CBT), motivational interviewing (MI), and other therapeutic techniques has proven effective in addressing the underlying causes of addiction and promoting long-term recovery. In addition to therapeutic advancements, technology has played a pivotal role in transforming addiction treatment. Telemedicine and mobile health applications have emerged as valuable tools in extending the reach of treatment services. These technologies enable healthcare providers to offer remote consultations, continuous monitoring, and real-time support to individuals undergoing treatment. Telemedicine, in particular, has gained traction in rural and underserved areas, where access to specialized addiction treatment services may be limited. For instance, despite a rapid increase in telemedicine visits for substance use disorder from 2010–2017, the overall use rates remain low. By leveraging technology, treatment providers can ensure that more individuals receive timely and effective care, thereby driving market growth.
Government Initiatives and Policy Support
Government initiatives and policy support have been instrumental in shaping the addiction treatment landscape in Europe. Recognizing the societal and economic impact of substance abuse, governments across Europe have implemented comprehensive strategies to combat addiction and promote recovery. These initiatives include increased funding for addiction treatment programs, public awareness campaigns, and the establishment of regulatory frameworks to ensure the quality and accessibility of treatment services. For instance, the European Union (EU) has adopted various policies aimed at reducing the harm caused by substance abuse and improving the availability of treatment services. The EU’s Action Plan on Drugs, which outlines strategic priorities and actions for addressing drug-related issues, emphasizes the importance of treatment and rehabilitation. National governments have also introduced measures to expand access to addiction treatment, such as subsidizing treatment costs and supporting the development of community-based services. These policy efforts create a conducive environment for the growth of the addiction treatment market, as they enhance the availability and affordability of treatment options for individuals in need.
Growing Societal Acceptance and Destigmatization of Addiction
Societal attitudes towards addiction and mental health have undergone a significant transformation in recent years, contributing to the growth of the addiction treatment market. Historically, addiction was often stigmatized, leading to social exclusion and reluctance among individuals to seek help. However, increasing public awareness and education about addiction as a medical condition have led to greater acceptance and understanding. Campaigns by non-governmental organizations (NGOs), healthcare providers, and advocacy groups have played a crucial role in destigmatizing addiction. These efforts emphasize that addiction is a treatable condition and encourage individuals to seek professional help without fear of judgment. As societal attitudes shift, more people are willing to pursue treatment, resulting in higher demand for addiction treatment services. This growing acceptance not only supports market expansion but also fosters a more supportive and inclusive environment for individuals undergoing treatment.
Market Trends
Integration of Digital Health Technologies
One of the most significant trends shaping the European Addiction Treatment Market is the integration of digital health technologies into treatment programs. The adoption of telemedicine, mobile health applications, and digital platforms has revolutionized the way addiction treatment services are delivered. Telemedicine, for instance, enables healthcare providers to offer remote consultations and continuous monitoring, making it easier for patients to access care regardless of their geographic location. This is particularly beneficial in rural and underserved areas where access to specialized addiction treatment services may be limited. According to the Substance Abuse and Mental Health Services Administration (SAMHSA), the percentage of mental health facilities offering telemedicine services increased from 38% in 2019 to 68.7% in 2021. The National Institute on Alcohol Abuse and Alcoholism (NIAAA) also highlights the promise of digital health technologies in addressing alcohol misuse among youth, with interventions like SafERteens showing reduced alcohol-related consequences and severe aggression in the year following the intervention.
Mobile health applications are also gaining popularity, offering a range of functionalities such as virtual therapy sessions, appointment scheduling, medication reminders, and real-time support. These apps provide patients with convenient tools to manage their recovery, stay connected with their healthcare providers, and track their progress. The use of digital platforms allows for the collection and analysis of patient data, enabling personalized treatment plans and improving overall treatment outcomes. The COVID-19 pandemic has accelerated the adoption of these technologies, as restrictions on in-person interactions have highlighted the need for remote care solutions. This trend is expected to continue, driving innovation and improving accessibility in the addiction treatment market.
Emphasis on Holistic and Integrated Treatment Approaches
Another notable trend in the European addiction treatment market is the growing emphasis on holistic and integrated treatment approaches. Traditional addiction treatment is often focused primarily on detoxification and abstinence. However, there is an increasing recognition that successful addiction treatment must address the comprehensive needs of the individual, including physical, psychological, and social aspects. A study found that around 85% of therapists draw on multiple therapeutic traditions in their treatment, demonstrating the appeal of holistic approaches. This holistic approach involves integrating various therapeutic modalities to provide a more rounded and effective treatment experience.
Treatment programs are increasingly incorporating mental health services, recognizing the high comorbidity between addiction and mental health disorders such as depression, anxiety, and PTSD. By addressing these co-occurring disorders concurrently, treatment providers can improve patient outcomes and reduce the risk of relapse. Additionally, there is a growing focus on incorporating complementary therapies such as mindfulness, yoga, nutrition counseling, and exercise programs into addiction treatment plans. These therapies support overall well-being and help individuals develop healthy coping mechanisms.
Family involvement is also becoming a crucial component of addiction treatment, as supportive family dynamics can significantly enhance recovery outcomes. Family therapy sessions and educational programs help families understand addiction, improve communication, and provide a supportive environment for the individual in recovery. The emphasis on holistic and integrated treatment approaches reflects a broader understanding of addiction as a multifaceted condition necessitating comprehensive and personalized care strategies. This trend is likely to persist, driving the development of more effective and patient-centered addiction treatment programs in Europe.
Market Restraints and Challenges
Limited Access to Treatment Facilities
One of the primary challenges facing the Europe Addiction Treatment Market is the limited access to treatment facilities. Despite the growing recognition of addiction as a significant public health issue, many regions, particularly rural and underserved areas, lack adequate addiction treatment infrastructure. This geographical disparity means that individuals in need of treatment often have to travel long distances to access specialized services, which can be a significant barrier to seeking help. Additionally, the availability of treatment facilities is often constrained by funding limitations. Public healthcare systems across Europe are under significant financial strain, and addiction treatment services frequently compete for resources with other critical healthcare needs. This competition can result in insufficient funding for addiction treatment programs, leading to long waiting times and reduced capacity to accept new patients. The lack of accessible and adequately funded treatment facilities impedes the ability of individuals to receive timely and effective care, posing a significant challenge to the market’s growth.
Stigma and Societal Barriers
Stigma and societal barriers continue to be substantial restraints in the Europe Addiction Treatment Market. Despite progress in public awareness and acceptance, addiction remains highly stigmatized, which can deter individuals from seeking treatment. The fear of judgment, discrimination, and social exclusion can prevent people from acknowledging their addiction and accessing the help they need. This stigma is particularly pronounced in certain cultures and communities where addiction is viewed as a moral failing rather than a medical condition. Furthermore, societal attitudes towards addiction can influence policy and funding decisions, often leading to insufficient support for addiction treatment services. The stigma associated with addiction can result in a lack of political will to prioritize addiction treatment, affecting the allocation of resources and the development of supportive policies. Moreover, healthcare professionals themselves can sometimes hold stigmatizing attitudes, which can impact the quality of care provided to individuals with addiction. Addressing these societal barriers requires ongoing public education, advocacy, and efforts to reshape perceptions of addiction as a treatable medical condition. Overcoming these challenges is essential to improving access to and the effectiveness of addiction treatment services in Europe.
Market Segmentation Analysis
By Treatment Type
The Europe addiction treatment market comprises several significant segments, including alcohol, tobacco/nicotine, opioid, and other substances addiction treatments. Alcohol addiction treatment is driven by the rising prevalence of alcohol use disorders and increased awareness of its harmful effects, incorporating therapies like behavioral counseling, detoxification, and medication-assisted treatment for long-term recovery. Tobacco/nicotine addiction treatment has grown through public health campaigns and smoking cessation programs, utilizing nicotine replacement therapies, prescription medications, and behavioral therapies. The opioid addiction treatment segment is rapidly expanding due to the ongoing opioid crisis, offering medication-assisted treatments (MAT) such as methadone, buprenorphine, and naltrexone, along with counseling services. Additionally, treatments for addictions to substances like cannabis, stimulants, and sedatives are in demand, addressing the specific challenges of each substance use disorder.
By Drug Type
In the Europe Addiction Treatment Market, several key medications are utilized to address various substance use disorders. Bupropion and Varenicline are essential in smoking cessation programs, reducing nicotine cravings and withdrawal symptoms, with Varenicline also decreasing the pleasure associated with smoking. Acamprosate and Disulfiram are pivotal in alcohol addiction treatment; Acamprosate helps maintain abstinence by reducing cravings, while Disulfiram deters alcohol consumption by causing unpleasant reactions. Naltrexone is versatile, used in both alcohol and opioid addiction treatments to block euphoric effects and reduce substance desire. Methadone and Buprenorphine, crucial in medication-assisted treatment (MAT) for opioid addiction, manage withdrawal symptoms and cravings, with Buprenorphine offering a safer profile. Nicotine replacement products, like patches and gums, are also widely used to control nicotine intake and alleviate withdrawal. Additionally, other medications tailored to specific addiction needs further enhance treatment efficacy.
Segments
Based on Treatment Type
- Alcohol Addiction Treatment
- Tobacco/Nicotine Addiction Treatment
- Opioid Addiction Treatment
- Other Substances Addiction Treatment
Based on Drug Type
- Bupropion
- Varenicline
- Acamprosate
- Disulfiram
- Naltrexone
- Methadone
- Buprenorphine
- Nicotine Replacement Products
- Others
Based on Treatment Center
- Outpatient Treatment Centers
- Residential Treatment Centers
- Inpatient Treatment Centers
Based on Distribution Channel
- Hospitals Pharmacies
- Medical Stores
- Others
Based on Region
- Western Europe
- Northern Europe
- Southern Europe
- Eastern Europe
Regional Analysis
Western Europe (45%):
Western Europe holds the largest market share in the Europe addiction treatment market, accounting for approximately 45% of the overall market. This region's dominance can be attributed to several factors, including the presence of advanced healthcare infrastructure, high healthcare expenditure, and strong government initiatives aimed at addressing substance abuse. Countries like Germany, France, and the United Kingdom are at the forefront, offering comprehensive treatment programs and well-established rehabilitation centers. The availability of a wide range of treatment options, from inpatient and outpatient services to specialized therapy and medication-assisted treatments, ensures that individuals receive tailored care suited to their specific needs.
Northern Europe (25%):
Northern Europe accounts for around 25% of the Europe addiction treatment market. This region is characterized by a robust public health system and proactive government policies that support addiction treatment and recovery. Countries such as Sweden, Norway, and Denmark have implemented extensive harm reduction strategies and public awareness campaigns to combat substance abuse. The integration of digital health technologies, such as telemedicine and mobile health apps, has further enhanced access to treatment services, particularly in remote and underserved areas. The emphasis on holistic and patient-centered approaches in addiction treatment programs also contributes to the market's growth in Northern Europe.
Key players
- Teva Pharmaceutical Industries Ltd.
- Pfizer, Inc.
- Alkermes Plc.
- Glenmark Pharmaceuticals
- GSK plc
- Johnson & Johnson Services, Inc.
- Novartis AG
- Perrigo Company plc
- Cipla
- Reddy's Laboratories Limited
- Hikma Pharmaceuticals Plc.
- Indivior Inc.
- Mylan N.V.
- Eli Lilly and Company
- Camurus AB
Competitive Analysis
The Europe addiction treatment market is characterized by intense competition among key players striving to enhance their market presence and treatment offerings. Companies like Teva Pharmaceutical Industries Ltd., Pfizer, Inc., and Johnson & Johnson Services, Inc. lead the market through their extensive portfolios of addiction treatment medications and therapies. These companies invest significantly in research and development to innovate and improve treatment efficacy. Indivior Inc. and Alkermes Plc. focus on specialized addiction treatments, particularly in opioid dependency, leveraging their expertise to capture significant market share. Novartis AG and GSK plc contribute through their robust distribution networks and strong brand recognition. Smaller players like Camurus AB and Glenmark Pharmaceuticals are also making strides by introducing novel treatment solutions. The competitive landscape is further intensified by strategic collaborations, mergers, and acquisitions aimed at expanding market reach and enhancing service capabilities. This dynamic environment drives continuous advancements and improvements in addiction treatment options available in Europe.
Recent Developments
In June 2021, AELIS FARMA, a biotechnology company specializing in brain disorder treatments, announced a strategic partnership and option license agreement with INDIVIOR PLC. This collaboration aims to address severe consequences of cannabis use disorders (CUD), including cannabis-induced psychosis (CIP).
In June 2021, Terveystalo Healthcare acquired a 72% shareholding in Feelgood Svenska AB. The acquisition included a recommended mandatory offer of SEK 5.7 per share, strengthening Terveystalo's position in the healthcare market.
In June 2021, The Ridge announced the opening of a new facility dedicated to providing exclusive private treatment for individuals suffering from drug and alcohol addiction. This new center aims to offer specialized care and support to those in need.
On May 14, 2024, Lifespan Health System launched a new addiction treatment program called Addiction Care Today. This initiative offers walk-in and same-day appointments for individuals seeking immediate help for substance use disorders, aiming to provide timely and accessible care.
On February 9, 2024, the Union Council of Ministers announced the opening of 41 addiction treatment facilities in Delhi. These centers will provide free treatment, counseling, and medications to individuals struggling with substance addiction, aiming to improve access to essential services.
In May 2023, Camurus AB, a Swedish biopharmaceutical company, announced that the U.S. Food and Drug Administration (FDA) approved Brixadi (buprenorphine) extended-release injection for subcutaneous use. This medication is intended to treat moderate to severe opioid use disorder (OUD), offering a new option for patients seeking treatment.
Market Concentration and Characteristics
The Europe Addiction Treatment Market is characterized by a moderate to high market concentration, with several key players dominating the industry. Major pharmaceutical companies such as Teva Pharmaceutical Industries Ltd., Pfizer, Inc., and Johnson & Johnson Services, Inc., hold significant market shares due to their extensive product portfolios and robust research and development capabilities. The market is distinguished by its diverse range of treatment options, including medication-assisted treatments (MAT), behavioral therapies, and digital health solutions. There is a strong emphasis on innovation and the integration of advanced technologies to enhance treatment efficacy and accessibility. Additionally, the market is supported by substantial government initiatives and policies aimed at reducing substance abuse and improving public health outcomes. The competitive landscape is dynamic, with ongoing mergers, acquisitions, and strategic collaborations shaping the market's evolution.
Report Coverage
The research report offers an in-depth analysis based on Treatment Type, Drug Type, Treatment Center, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Governments across Europe are expected to increase funding for addiction treatment programs, enhancing the availability and quality of services.
- The adoption of telemedicine will continue to grow, providing remote access to treatment services and reducing barriers for individuals in rural and underserved areas.
- Innovations in medication-assisted treatments (MAT) will lead to more effective and personalized therapies, improving recovery rates for patients with substance use disorders.
- The incorporation of holistic and complementary therapies, such as mindfulness and nutrition counseling, will become more prevalent, addressing the comprehensive needs of patients.
- Outpatient treatment services are anticipated to expand, offering flexible and cost-effective options for individuals seeking addiction treatment while maintaining their daily routines.
- There will be a stronger emphasis on addressing co-occurring mental health disorders in addiction treatment, ensuring integrated care for better patient outcomes.
- Increased public awareness campaigns will continue to destigmatize addiction, encouraging more individuals to seek help and support for their substance use disorders.
- The use of artificial intelligence and data analytics in addiction treatment will enhance patient monitoring, treatment personalization, and outcome prediction.
- Strategic collaborations between healthcare providers, pharmaceutical companies, and non-governmental organizations will drive the development and dissemination of effective treatment modalities.
- Supportive regulatory frameworks will facilitate the approval and implementation of new treatment methods and medications, accelerating the adoption of advanced addiction treatment solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Europe Addiction Treatment Market?
What factors are driving the growth of the addiction treatment market in Europe?
How is technology influencing addiction treatment in Europe?
What role do government initiatives play in the addiction treatment market?
Who are some of the key players in the Europe Addiction Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Addiction Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Addiction Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,436.26 million → 2032: USD 4,140.86 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Addiction Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Addiction Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Addiction Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Addiction Treatment Market Drivers
- 3.3 Europe Addiction Treatment Market Restraints & Challenges
- 3.4 Europe Addiction Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Addiction Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Addiction Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Addiction Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Addiction Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Addiction Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Addiction Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Addiction Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Addiction Treatment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Addiction Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Addiction Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Addiction Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Addiction Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Addiction Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Addiction Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Addiction Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Addiction Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Addiction Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Addiction Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Addiction Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
