
Market Overview:
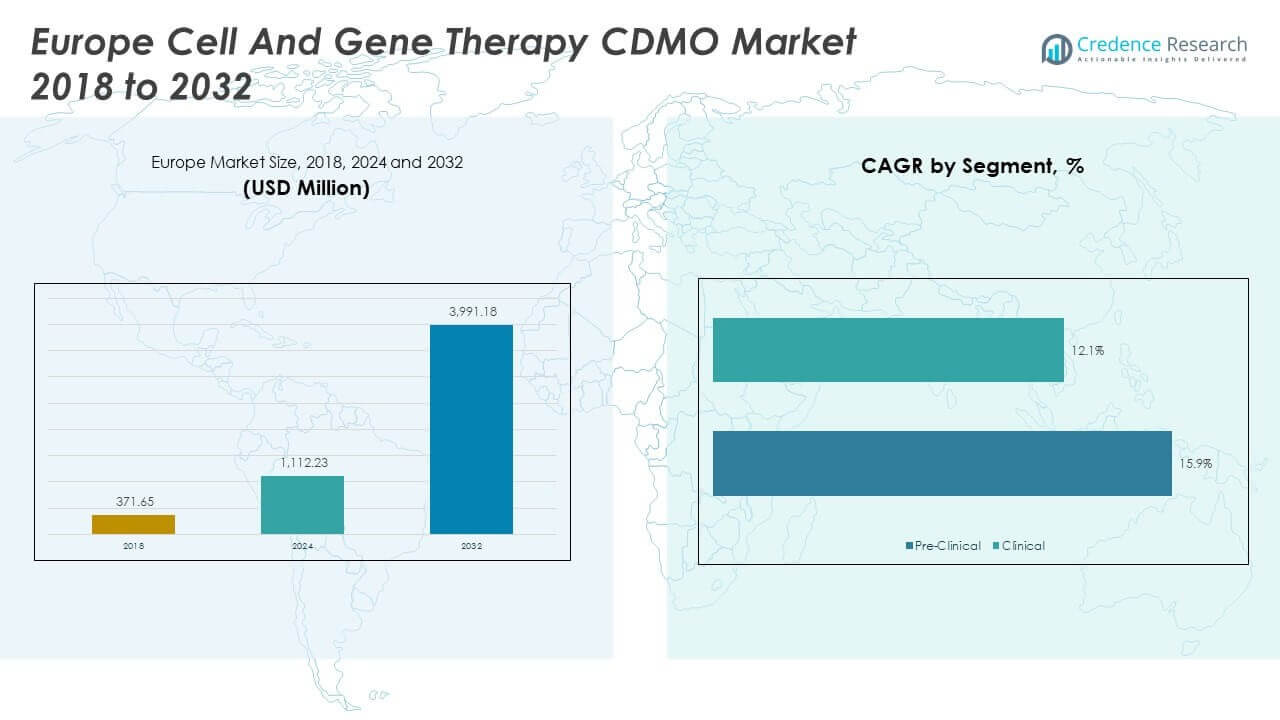
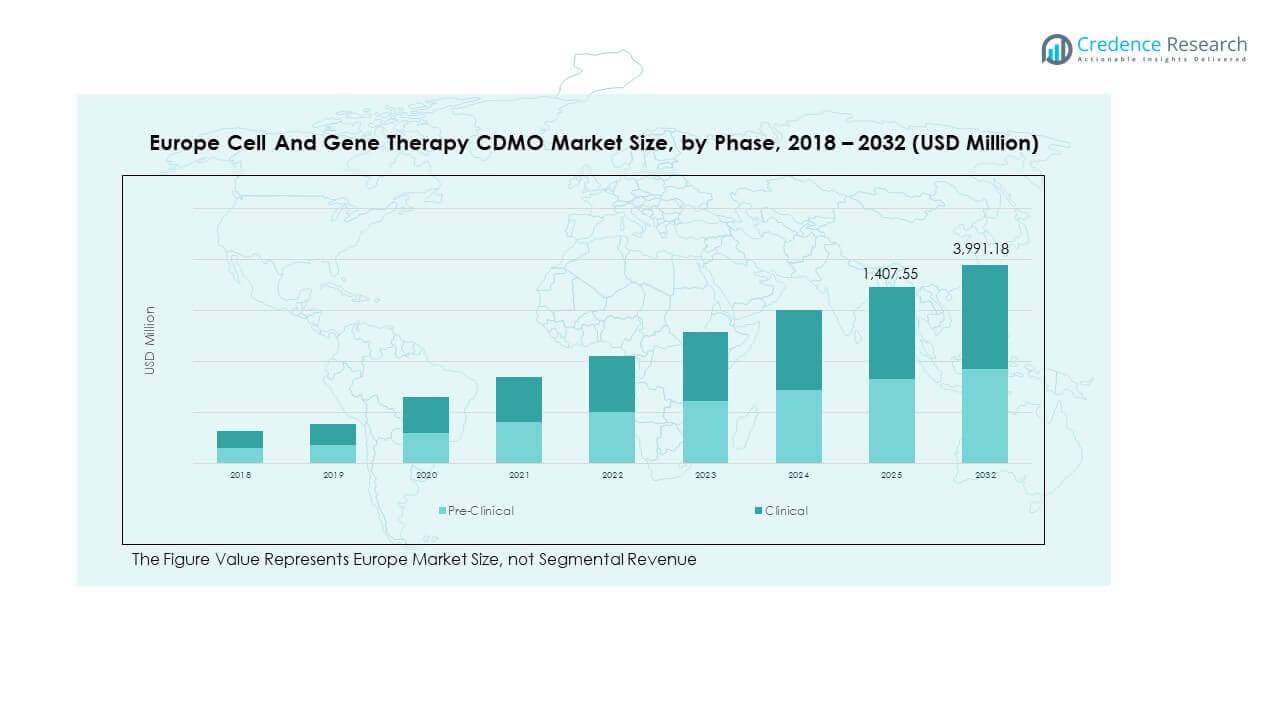
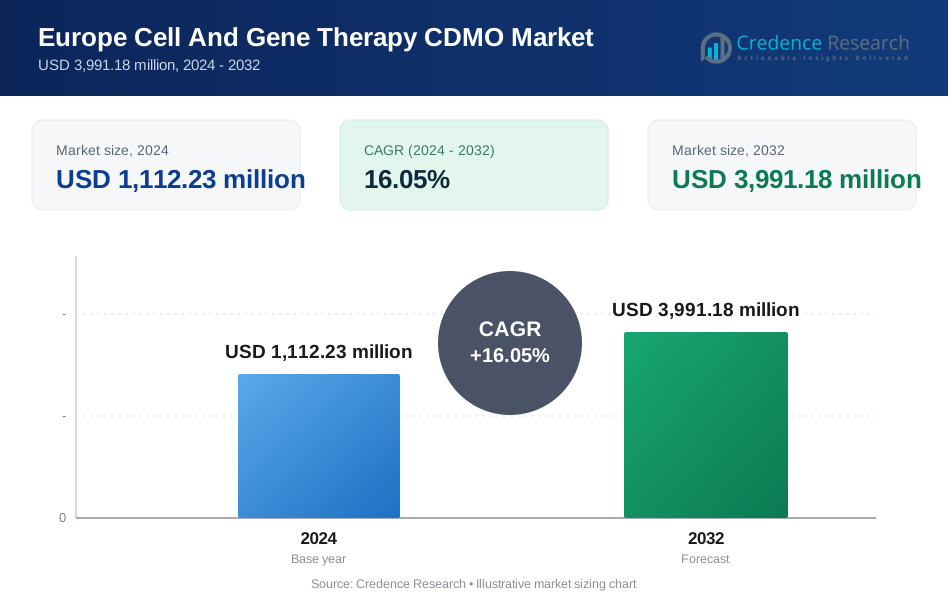
The Europe Cell and Gene Therapy CDMO Market size was valued at USD 371.65 million in 2018, reaching USD 1,112.23 million in 2024, and is anticipated to attain USD 3,991.18 million by 2032, registering a CAGR of 16.05% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Cell and Gene Therapy CDMO Market Size 2024 | USD 1,112.23 Million |
| Europe Cell and Gene Therapy CDMO Market, CAGR | 16.05% |
| Europe Cell and Gene Therapy CDMO Market Size 2032 | USD 3,991.18 Million |
The market is expanding due to rising demand for advanced therapies targeting rare and chronic diseases. Increased investments in R&D, government support, and technological advancements in cell expansion, vector manufacturing, and GMP compliance drive strong growth. Pharmaceutical and biotech companies are increasingly outsourcing to CDMOs for cost efficiency, scalability, and regulatory expertise. The shift toward personalized medicine and the rise of innovative therapies, such as CAR-T and gene-modified cell treatments, are further strengthening the market trajectory.
Geographically, Western Europe, led by Germany, the United Kingdom, and France, dominates the market owing to established biopharmaceutical clusters, advanced infrastructure, and significant clinical trial activity. Emerging markets in Eastern Europe are gaining traction due to growing government funding and lower operational costs, attracting global CDMOs. Southern European countries are also showing rising adoption, driven by increasing collaborations with global pharma and research institutions. This regional landscape highlights both established leaders and emerging hubs that are shaping future growth.
Market Insights:
- The Europe Cell and Gene Therapy CDMO Market was valued at USD 371.65 million in 2018, reached USD 1,112.23 million in 2024, and is projected to attain USD 3,991.18 million by 2032, growing at a CAGR of 16.05%.
- Western Europe led with 52% share in 2024, supported by advanced biotech clusters in Germany, the UK, and France, while Southern Europe held 21% due to cost-efficient outsourcing, and Eastern Europe contributed 15%, leveraging low-cost manufacturing and government incentives.
- Northern Europe, with a 12% share, represents the fastest-growing subregion, driven by strong academic research ecosystems in Sweden and Denmark and innovation in rare disease therapies.
- The clinical phase accounted for 78% share in 2024, highlighting the dominance of late-stage trials and scaling needs across oncology and neurological applications.
- The pre-clinical phase held 22% share, supported by early-stage biotech firms relying on CDMOs for feasibility studies and regulatory preparation.
Market Drivers
Rising demand for advanced therapies across multiple therapeutic areas creates momentum for CDMO services
The growth of advanced therapies is creating significant momentum across multiple indications. Increasing prevalence of rare genetic disorders and cancers is expanding the need for specialized treatment options. Governments and healthcare providers are supporting programs that promote early adoption of cell and gene therapies. Pharmaceutical and biotechnology companies are moving towards outsourcing to achieve efficiency and compliance. The Europe Cell And Gene Therapy CDMO Market benefits from a strong regulatory environment that encourages innovation. Rising investment in oncology, neurology, and immunology strengthens the adoption of contract development services. It enables CDMOs to expand capacities, improve scalability, and offer advanced platforms for therapeutic manufacturing. The rising number of clinical trials across Europe also drives consistent demand for specialized expertise.
- For instance, in August 2025 Minaris Advanced Therapies opened a new GMP cell and gene therapy manufacturing facility in Taufkirchen (near Munich), Germany. The site features six Grade B/A cleanrooms, one convertible Grade C cleanroom, dedicated process development and QC labs, cryopreservation and storage facilities, and 224 m² of expansion space, all designed to support streamlined technology transfer and both clinical and commercial production.
Expanding pharmaceutical outsourcing partnerships enhance scalability and reduce operational risks
Pharmaceutical companies are forming partnerships with CDMOs to streamline complex processes. These collaborations enable faster development cycles and minimize financial risks linked to infrastructure investment. Companies are focusing on strengthening product pipelines without diverting resources to in-house facilities. The Europe Cell And Gene Therapy CDMO Market gains momentum as outsourcing offers access to established expertise. It provides flexibility to adjust production capacity in line with shifting demand. CDMOs deliver advanced manufacturing solutions, quality control frameworks, and compliance assurance under strict regulatory guidelines. The trust in CDMOs grows with their ability to deliver consistent performance. Strategic alliances allow both emerging biotech and established pharma to achieve faster commercialization of therapies.
- For instance, Evotec's J POD biologics manufacturing facility in Toulouse, France, has been customized and dedicated entirely to Sandoz since July 2024, marking a key advancement in their partnership. Under a proposed agreement, Sandoz aims to acquire the Toulouse site leveraging Evotec’s continuous manufacturing platform through a sale valued at around US$ 300 million.
Supportive regulatory frameworks encourage compliance and market expansion across the region
Strong regulations in Europe are guiding the progress of advanced therapy manufacturing. Regulatory authorities encourage innovation while ensuring safety standards are strictly met. Harmonized guidelines across member countries create a favorable environment for CDMOs. The Europe Cell and Gene Therapy CDMO Market benefits from regulatory clarity that reduces delays. It provides confidence to investors and sponsors regarding long-term market sustainability. CDMOs with GMP-certified facilities gain preference from companies seeking compliant production. Regulatory support helps streamline clinical trials and accelerate approvals for advanced therapies. The presence of Pan-European initiatives promotes a unified growth environment for the industry.
Investment in research infrastructure drives technological advancements in therapeutic manufacturing
Strong investments in research centers and biotech hubs support innovation in cell and gene therapies. Public and private funding is enhancing infrastructure for clinical trials and R&D activities. Academic institutions collaborate with CDMOs to accelerate translational research into market-ready therapies. The Europe Cell And Gene Therapy CDMO Market benefits from a dense network of innovation clusters. It creates opportunities for faster adaptation of new manufacturing technologies. CDMOs are investing in automation, process optimization, and AI-enabled monitoring systems. These developments reduce error rates, improve yields, and ensure higher scalability. Investments in infrastructure also strengthen Europe’s global position in advanced therapy manufacturing.
Market Trends
Expansion of viral vector production capacity supports rapid growth of therapeutic pipelines
Viral vectors are essential for the delivery of many gene therapies. Growing demand has pushed CDMOs to expand vector manufacturing capacity across Europe. Large-scale facilities are being developed to meet the surge in clinical programs. The Europe Cell And Gene Therapy CDMO Market reflects this trend as CDMOs invest heavily. It is driving the adoption of scalable vector technologies such as suspension cell cultures. Standardization of vector platforms improves consistency and supports faster approvals. Companies are also deploying modular facilities for greater production flexibility. These expansions secure the supply chain for both clinical and commercial therapies.
- For instance, Oxford Biomedica’s Oxbox facility in Oxford, UK, currently operates four GMP viral vector production suites and two fill–finish suites, while its fully funded Phase Two expansion adds large-scale bioreactor capacity at 500 L, 1,000 L, and up to 2,000 L, strengthening both clinical and commercial manufacturing capability in Europe.
Growing integration of digital technologies enhances efficiency in therapeutic development
Digital transformation is reshaping CDMO operations across Europe. Companies are deploying AI-driven platforms for predictive modeling and process optimization. The Europe Cell And Gene Therapy CDMO Market highlights this trend with adoption of cloud-based monitoring systems. It supports better resource planning and enhances compliance tracking. Digital twins and smart analytics are applied to optimize batch yields. Companies use data insights to reduce downtime and streamline operations. Automation combined with robotics improves consistency in high-complexity manufacturing. These technology integrations help CDMOs deliver reliable and scalable outcomes.
- For instance, Sartorius offers its Umetrics® data analytics solutions, including SIMCA® and SIMCA®-online, which integrate advanced multivariate analysis and real-time process monitoring to optimize bioprocess control and improve consistency across CDMO manufacturing operations.
Rising focus on personalized medicine reshapes manufacturing priorities for CDMOs
The trend toward personalized medicine is influencing how CDMOs manage production. Increasing adoption of CAR-T and autologous therapies requires flexible and adaptive processes. The Europe Cell And Gene Therapy CDMO Market evolves with this demand for individualized solutions. It challenges CDMOs to shift from bulk production models to patient-specific manufacturing. Specialized logistics and rapid turnaround times are becoming critical success factors. The emphasis on small batch sizes pushes development of advanced scheduling systems. Partnerships with healthcare providers and clinics strengthen personalized therapy delivery. The growing focus on tailored treatments continues to reshape industry operations.
Cross-border collaborations create new growth opportunities and knowledge sharing
Collaborations across Europe are fostering knowledge exchange and resource sharing. Academic institutions, biotech firms, and CDMOs are building joint projects to accelerate growth. The Europe Cell and Gene Therapy CDMO Market demonstrates this trend through multiple international partnerships. It is leading to standardized processes and broader access to advanced technologies. Collaborations also reduce the financial burden on smaller biotech companies. Shared infrastructure models improve efficiency and ensure better access to expertise. Cross-border initiatives also support clinical trials that require diverse patient recruitment. These collaborations contribute to the region’s competitive position in global markets.
Market Challenges Analysis
High costs and complex manufacturing requirements create barriers for new entrants and smaller firms
The market faces significant challenges from the high cost of infrastructure and equipment. Manufacturing advanced therapies requires specialized cleanrooms, bioreactors, and analytical systems. Smaller biotech firms often lack the financial resources to invest in such capabilities. The Europe Cell and Gene Therapy CDMO Market addresses this gap, but cost pressures remain high. It leads to increased outsourcing dependency, which can strain CDMO capacity. The complexity of scaling personalized therapies also adds operational hurdles. Companies must maintain strict GMP standards while dealing with variable demand. These challenges create barriers that limit participation from smaller players.
Skilled workforce shortages and supply chain constraints hinder seamless growth across regions
The demand for highly skilled professionals in advanced therapy manufacturing exceeds supply. CDMOs face difficulties recruiting specialists in cell biology, molecular genetics, and process engineering. The Europe Cell and Gene Therapy CDMO Market experiences delays when workforce shortages affect timelines. It also suffers from supply chain bottlenecks for viral vectors and raw materials. Global disruptions increase risks for therapy developers relying on timely delivery. Quality assurance professionals are also in short supply, adding pressure on compliance teams. Training initiatives exist, but they require time to create an impact. These workforce and supply challenges limit efficiency and scalability across Europe.
Market Opportunities
Expanding partnerships with global biopharma companies create growth prospects for CDMOs in Europe
Collaborations with global biopharma leaders are creating new opportunities for CDMOs. Multinational firms prefer European partners for access to advanced facilities and regulatory compliance. The Europe Cell and Gene Therapy CDMO Market gains momentum from these partnerships. It positions CDMOs to expand service portfolios and secure long-term contracts. Demand for scalable manufacturing and rapid development cycles drives sustained collaborations. Strategic alliances with North American and Asian firms enhance market penetration. These opportunities strengthen Europe’s role in global therapy development.
Increasing focus on emerging therapeutic areas boosts demand for specialized CDMO services
Emerging therapeutic areas such as regenerative medicine and rare disease treatment are expanding. CDMOs with expertise in novel platforms are well positioned to capture demand. The Europe Cell and Gene Therapy CDMO Market benefits from its strong innovation ecosystem. It encourages new service models that address evolving therapeutic needs. CDMOs are adopting flexible manufacturing to support smaller, specialized pipelines. Growing funding for early-stage biotech ventures boosts outsourcing opportunities. These conditions create an attractive environment for market expansion across Europe.
Market Segmentation Analysis:
The Europe Cell and Gene Therapy CDMO Market demonstrates strong segmentation by phase, type, and indication, reflecting diverse demand drivers.
By phase, pre-clinical services hold steady importance due to early research requirements, while the clinical segment dominates revenue share with rising trial activity and regulatory submissions. It highlights the growing reliance of biotech firms on CDMOs for complex, large-scale clinical production.
- For instance, Amatsigroup, part of Eurofins CDMO, in France provides contract development and manufacturing services that support biotech and pharmaceutical companies from preclinical stages through Phase III clinical trials, strengthening early-stage research and clinical manufacturing in Europe.
By type, gene therapy is segmented into ex-vivo and in-vivo approaches. Ex-vivo therapies lead due to their precision and established clinical success, particularly in hematological disorders, while in-vivo approaches are gaining traction with advancements in vector delivery. Gene-modified cell therapies form a significant segment, with CAR T-cell therapies at the forefront due to their commercialized adoption in oncology. Emerging modalities like CAR-NK and TCR-T therapies are gaining visibility through early-stage clinical trials. Other categories remain niche but present opportunities for diversification.
By indication, oncology accounts for the largest share, driven by the widespread adoption of CAR T-cell therapies and pipeline investments. Infectious diseases follow with renewed interest in viral vector-based therapies for unmet needs. Neurological disorders represent a growing segment with promising advances in gene replacement therapies targeting conditions such as Parkinson’s and rare neuromuscular diseases. Rare diseases collectively form a strong opportunity area due to orphan drug incentives and high unmet clinical demand, while other indications sustain moderate growth across therapeutic niches. This segmentation underscores the market’s broad applicability and dynamic growth potential across Europe.
- For example, EUROAPI’s collaboration with Priothera targets manufacturing of mocravimod for blood cancers representing both oncology focus and CDMO reliance for clinical supply in Europe.
Segmentation:
By Phase
- Pre-Clinical
- Clinical
By Type
- Gene Therapy
- Ex-Vivo
- In-Vivo
- Gene-Modified Cell Therapy
- CAR T-Cell Therapies
- CAR-NK Cell Therapy
- TCR-T Cell Therapy
- Others
- Others
By Indication
- Oncology
- Infectious Diseases
- Neurological Disorders
- Rare Diseases
- Others
Regional Analysis:
Western Europe holds the dominant position in the Europe Cell and Gene Therapy CDMO Market, accounting for nearly 52% market share in 2024. Countries such as Germany, the United Kingdom, and France drive this leadership due to advanced biopharmaceutical infrastructure and a strong base of clinical trials. Germany benefits from its established biotech clusters and government-backed R&D programs, while the UK leverages its innovation hubs like the Cell and Gene Therapy Catapult. France contributes with increasing investments in manufacturing capacity and international collaborations. It remains the region with the highest concentration of CDMOs offering both pre-clinical and commercial services. Western Europe’s leadership is reinforced by regulatory clarity and strong academic-industry partnerships.
Southern Europe secures close to 21% market share, with Italy and Spain emerging as important contributors. The region benefits from rising investments in biopharma infrastructure and expanding clinical research networks. Italy demonstrates strong activity in regenerative medicine and cell therapy development, while Spain shows growth through collaborations between hospitals and biotech firms. Southern Europe continues to attract outsourcing contracts due to cost advantages compared to Western Europe. It plays a growing role in bridging local innovation with global biopharma demand. The region shows potential for becoming a secondary hub as CDMOs expand into newer geographies to reduce capacity pressure in established markets.
Eastern Europe and Northern Europe collectively account for 27% market share, split into 15% and 12%, respectively. Eastern Europe is emerging as a cost-effective outsourcing destination, with countries such as Poland and Hungary offering attractive incentives for biotech manufacturing. It provides opportunities for small and mid-sized biotech firms seeking affordable CDMO partnerships. Northern Europe, led by countries like Sweden and Denmark, benefits from strong academic research ecosystems and government-backed innovation clusters. It supports niche therapeutic development, particularly in rare diseases and advanced clinical programs. The region shows a growing preference for sustainable manufacturing practices and digitalized operations. It is strengthening its position by aligning with global CDMOs for cross-border collaborations.
Key Player Analysis:
- AGC Biologics
- WuXi Advanced Therapies
- Oxford Biomedica
- Novasep
- Recipharm
- CEVEC Pharmaceuticals
- Bayer AG
- Cell and Gene Therapy Catapult
- BioElpida
- Cell Medica
Competitive Analysis:
The Europe Cell And Gene Therapy CDMO Market is shaped by a diverse set of global and regional players competing across innovation, capacity, and service specialization. Leading companies such as AGC Biologics, WuXi Advanced Therapies, and Oxford Biomedica dominate through extensive manufacturing capabilities and integrated service portfolios. These players invest heavily in viral vector production, cell expansion technologies, and GMP-certified facilities to secure long-term contracts with biopharma firms. It demonstrates strong competition among established CDMOs, where technological advancement and regulatory expertise provide a clear advantage. Regional players such as Novasep, Recipharm, and BioElpida enhance competition by offering flexible and niche services tailored for small and mid-sized biotech firms. Strategic initiatives, including facility expansions, partnerships with academic institutes, and acquisitions, strengthen their positions in the market. It reflects a trend where both global giants and regional specialists are targeting oncology and rare disease pipelines, creating intense rivalry. CDMOs differentiate themselves through scalability, turnaround times, and ability to support personalized medicine development. Competitive intensity is further fueled by increasing demand for cost-effective solutions, encouraging players to adopt digital platforms and automation to boost efficiency.
Recent Developments:
- In May 2025, eXmoor Pharma, a leading CDMO in cell and gene therapy, entered into a strategic partnership with KU Leuven, one of Europe’s top academic institutions. The collaboration aims to develop a proprietary AAV producer cell line for scalable vector production as part of a newly established cell and gene therapy hub in Leuven, Belgium.
- In May 2025, Minaris Advanced Therapies was launched following a major merger between Minaris Regenerative Medicine and WuXi Advanced Therapies, establishing itself as a prominent global partner for cell therapy development, manufacturing, and contract testing dedicated to advanced therapies.
- In April 2025, AGC Biologics announced the official launch of its new Cell and Gene Technologies Division. This expansion is intended to focus on and elevate the company's cell and gene therapy manufacturing capabilities, supporting the increasing demand and innovation within the sector.
- In February 2025, PHC Corporation partnered with CCRM to jointly develop advanced T-cell expansion culture processes, furthering cell and gene therapy manufacturing innovation and capabilities in Europe.
Report Coverage:
The research report offers an in-depth analysis based on Phase, Type and Indication. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Europe Cell and Gene Therapy CDMO Market will expand as demand for advanced therapies rises across oncology, neurology, and rare diseases.
- Outsourcing partnerships will strengthen, with biopharma companies relying on CDMOs for clinical trial support and commercial manufacturing.
- Viral vector production will remain a strategic focus, with CDMOs investing in scalable and modular platforms.
- Digital technologies, including AI-driven analytics and process automation, will enhance efficiency and reduce production risks.
- Personalized medicine will drive small-batch, patient-specific manufacturing, increasing the need for adaptive CDMO capabilities.
- Regulatory clarity and harmonized frameworks across Europe will encourage investment and accelerate therapy approvals.
- Regional hubs in Western Europe will consolidate leadership, while Eastern Europe emerges as a cost-effective outsourcing base.
- Strategic collaborations between CDMOs, academic institutions, and biotech firms will accelerate innovation and clinical success.
- Sustainability and eco-friendly manufacturing practices will gain traction as environmental compliance becomes a priority.
- Competitive intensity will increase through mergers, acquisitions, and facility expansions, shaping a consolidated yet dynamic market landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Advanced Therapy Pipelines
The increasing prevalence of rare genetic disorders, cancers, and chronic diseases is driving pharmaceutical and biotech companies to develop more cell and gene therapies, boosting demand for specialized CDMO services to support clinical and commercial manufacturing.
Outsourcing for Cost Efficiency and Scalability
Pharmaceutical and biotech firms are increasingly outsourcing cell and gene therapy development and manufacturing to CDMOs to reduce operational risks, access regulatory expertise, and scale production efficiently without heavy capital investment in in-house facilities.
Technological Advancements in Manufacturing
Investments in automation, digitalization, and advanced bioprocessing technologies by CDMOs are improving yields, reducing errors, and enabling the production of complex therapies such as CAR-T and gene-modified cell treatments, making Europe a competitive hub for advanced therapy manufacturing.
Supportive Regulatory Environment
Harmonized and clear regulatory frameworks across Europe encourage innovation, streamline clinical trial approvals, and provide confidence to investors and sponsors, accelerating the adoption and commercialization of cell and gene therapies.
Growth of Personalized Medicine
The shift toward personalized, patient-specific therapies such as autologous CAR-T treatments is increasing the need for flexible, small-batch manufacturing capabilities, prompting CDMOs to adapt their operations and expand their service offerings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Cell And Gene Therapy CDMO Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Cell And Gene Therapy CDMO Market projected to grow between 2024 and 2032?
Which Europe Cell And Gene Therapy CDMO Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Cell And Gene Therapy CDMO Market?
Who are the leading companies in the Europe Cell And Gene Therapy CDMO Market?
Which region commanded the largest share of the Europe Cell And Gene Therapy CDMO Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Gene Therapy - Ex-Vivo
- 1.2.2 Gene Therapy - In-Vivo
- 1.2.3 Gene-Modified Cell Therapy - CAR T-Cell Therapies
- 1.2.4 Gene-Modified Cell Therapy - CAR-NK Cell Therapy
- 1.2.5 Gene-Modified Cell Therapy - TCR-T Cell Therapy
- 1.2.6 Others
- 1.3 By Phase
- 1.3.1 Pre-Clinical
- 1.3.2 Clinical
- 1.4 By Indication
- 1.4.1 Oncology
- 1.4.2 Infectious Diseases
- 1.4.3 Neurological Disorders
- 1.4.4 Rare Diseases
- 1.4.5 Others
- 1.5 By Region (Europe)
- 1.5.1 Western Europe
- 1.5.2 Southern Europe
- 1.5.3 Eastern Europe
- 1.5.4 Northern Europe
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,112.23 million → 2032: USD 3,991.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Cell And Gene Therapy CDMO Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Cell And Gene Therapy CDMO Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Cell And Gene Therapy CDMO Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Cell And Gene Therapy CDMO Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Cell And Gene Therapy CDMO Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Cell And Gene Therapy CDMO Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Cell And Gene Therapy CDMO Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Cell And Gene Therapy CDMO Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,112.23 million → 2032: USD 3,991.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Cell And Gene Therapy CDMO Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gene Therapy - Ex-Vivo
- 12.3.7.2 Gene Therapy - In-Vivo
- 12.3.7.3 Gene-Modified Cell Therapy - CAR T-Cell Therapies
- 12.3.7.4 Gene-Modified Cell Therapy - CAR-NK Cell Therapy
- 12.3.7.5 Gene-Modified Cell Therapy - TCR-T Cell Therapy
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Phase - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pre-Clinical
- 12.4.7.2 Clinical
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Infectious Diseases
- 12.5.7.3 Neurological Disorders
- 12.5.7.4 Rare Diseases
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (Europe) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Western Europe
- 12.6.7.2 Southern Europe
- 12.6.7.3 Eastern Europe
- 12.6.7.4 Northern Europe
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Cell And Gene Therapy CDMO Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Cell And Gene Therapy CDMO Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Cell And Gene Therapy CDMO Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 AGC Biologics
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 WuXi Advanced Therapies
- 17.4 Oxford Biomedica
- 17.5 Novasep
- 17.6 Recipharm
- 17.7 CEVEC Pharmaceuticals
- 17.8 Bayer AG
- 17.9 Cell and Gene Therapy Catapult
- 17.10 BioElpida
- 17.11 Cell Medica
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

