
Efficiency rules and AI halls reset airflow budgets
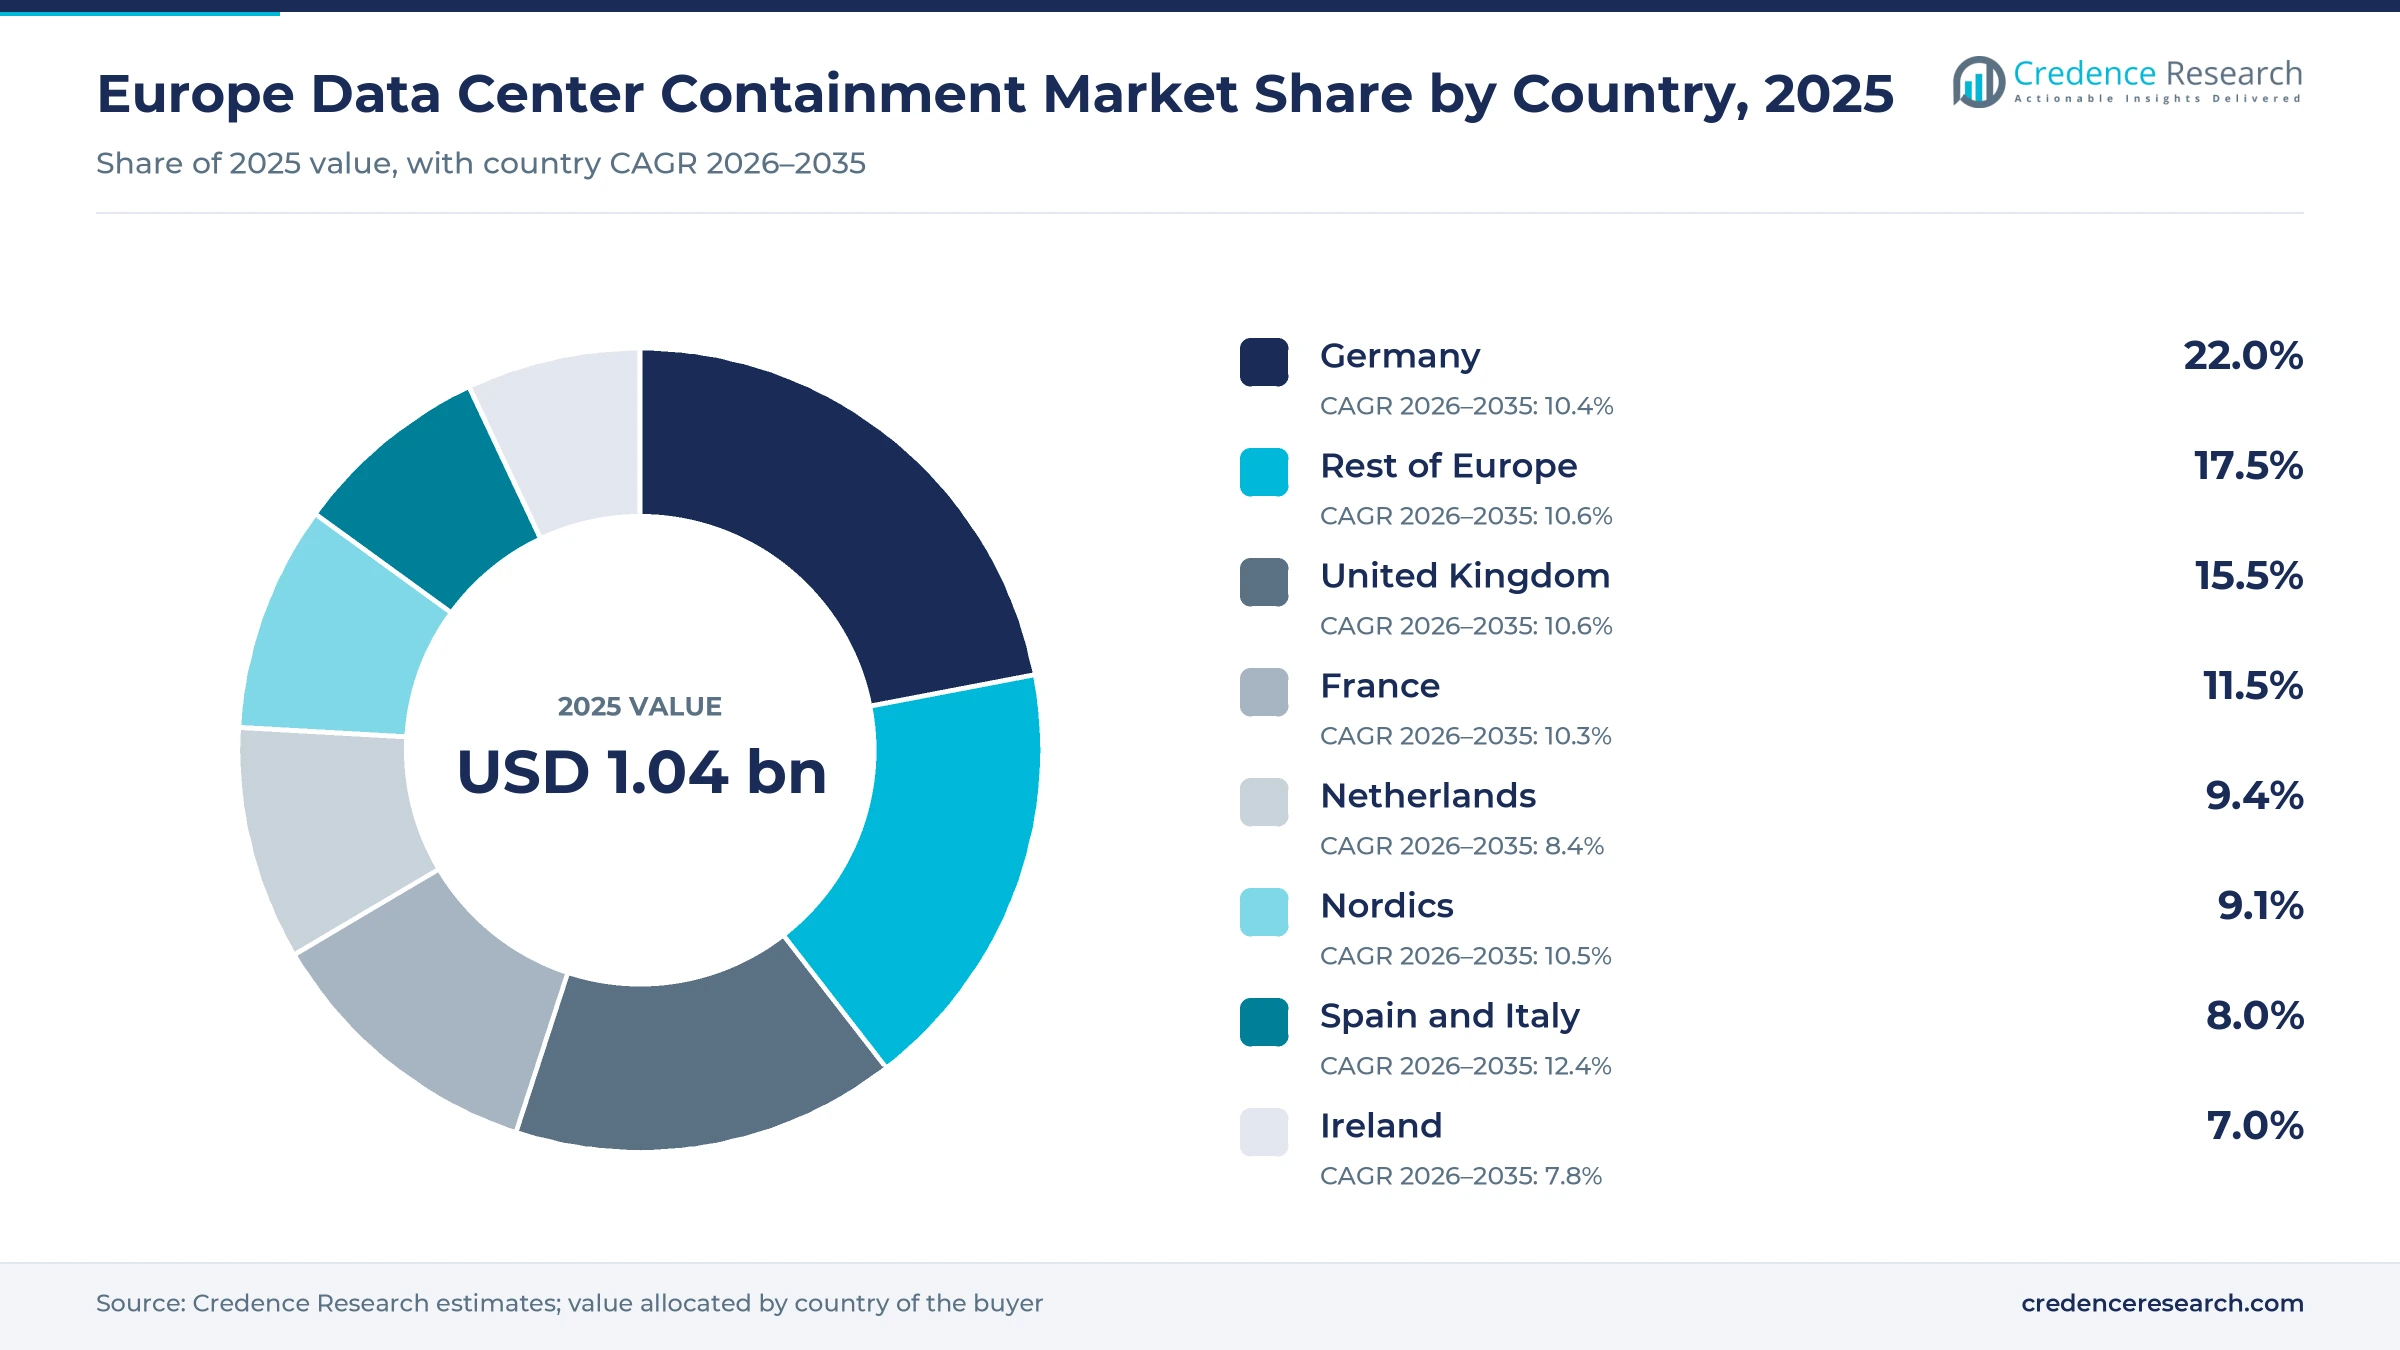
The Europe data center containment market was valued at USD 1.04 billion in 2025 and is projected to increase from USD 1.14 billion in 2026 to USD 2.77 billion by 2035, registering a CAGR of 10.32% during 2026–2035. Spending comes from colocation landlords fitting out new suites in Frankfurt, London, Paris, Amsterdam and Dublin, hyperscale and sovereign cloud providers building their own campuses, and enterprises resealing older server rooms to meet energy rules. Germany held the largest country share, 22.0% in 2025, because Frankfurt is the largest interconnection hub and German law sets the strictest efficiency caps. Spain and Italy are the fastest-growing area at 12.4% a year as Madrid and Milan absorb projects that cannot find power in the northern hubs. The main commercial change is the hybrid hall, where liquid-cooled AI racks share rooms with air-cooled servers, so containment is now specified together with liquid loops.
Aisle enclosures, chimneys and in-row pods are counted
This report sizes annual spending in Europe on physical systems that separate hot exhaust air from cold supply air around server racks. It counts hot aisle and cold aisle enclosures with doors, roof panels and end panels, rack-based chimney ducts, enclosed pods built around in-row coolers, and the blanking and sealing parts and installation work sold with them.
Room cooling plant, liquid cooling loops and the racks themselves are excluded unless they are sold as part of an enclosed pod. Buyers include colocation operators, hyperscale and cloud providers, enterprises and public bodies, and most buy through fit-out contractors, rack makers or specialist installers rather than directly from manufacturers.

Europe Data Center Containment Market Insights
- The Europe data center containment market was worth USD 1.04 billion in 2025 and is forecast to reach USD 2.77 billion by 2035, growing at 10.32% a year during 2026–2035.
- Germany held 22.0% of 2025 spending, while Spain and Italy grow fastest at 12.4% a year as Madrid and Milan add capacity.
- Hot Aisle Containment systems took 37.0% of 2025 spending, because German law caps the PUE of new halls and requires them to reuse waste heat.
- FLAP-D markets held about 3.8 GW of live capacity in the first half of 2026, with 1.4 GW under construction, according to JLL.
- Schneider Electric, Vertiv and Eaton all bought cooling or rack makers in 2025 and 2026 to sell complete white-space rows.
Hot aisle systems lead while in-row pods grow fastest
Why do hot aisle systems take the largest share?
Based on containment type, the market is categorized into hot aisle containment, cold aisle containment, rack-based chimney containment and in-row cooling containment. Hot Aisle Containment led with 37.0% of 2025 spending, because ducted hot aisles return the warm air that heat reuse needs, and under the current German act, halls opening from July 2026 must reuse at least 10% of their energy, rising to 20% for halls opening after July 2028. In-row Cooling Containment grows fastest at 11.6% a year as operators add cooling next to AI racks, which Siemens says already routinely exceed 100 kW per rack.
Why do colocation operators buy most enclosures?
Based on data center type, the market is categorized into hyperscale, enterprise, cloud, colocation and other data centers. Colocation Data Center facilities led with 44.0% of 2025 spending because landlords fit out suites for many tenants with different rack loads, and CBRE expected European colocation take-up to reach a record 855 MW in 2025. Hyperscale Data Center facilities grow fastest at 11.8% a year as cloud providers build their own campuses, with AWS putting more than EUR 7.8 billion into its European Sovereign Cloud in Brandenburg, Germany.
Why do modular kits lead and hybrid designs gain?
Based on arrangement, the market is categorized into hybrid, modular, rigid and other containment designs. Modular Containment kits led with 43.0% of 2025 spending, because they bolt onto existing racks, and members of the Climate Neutral Data Centre Pact committed to bring existing halls to an annual PUE of 1.3 in cool climates by January 2030. Hybrid Containment designs, which combine fixed frames with liquid pipework, grow fastest at 11.8% a year, as operators fit rear-door coolers to existing rows, an approach described in the trends below.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Containment Type | Hot Aisle Containment | 37.0% | In-row Cooling Containment | 11.6% |
| By Data Center Type | Colocation Data Center | 44.0% | Hyperscale Data Center | 11.8% |
| By Arrangement | Modular Containment | 43.0% | Hybrid Containment | 11.8% |
Low-cost panels sit beside larger installed projects
Containment is priced in two ways that give buyers very different bills. Small components such as blanking panels, brush strips and gap panels sell from catalogs at list prices of about £110 to £290, while full aisle enclosures are quoted per project and include doors, roof panels, cable seals and installation. Project prices rise with ceiling height, fire suppression interfaces and the number of rack widths in a row. Specialist installers earn better margins on surveys, fire integration and maintenance than on panels, which explains why rack makers bundle containment with racks and power distribution to protect their share of each order.
| Item or service | Typical price or fee | Basis |
|---|---|---|
| Eziblank Wall single 48U gap system, 600 mm to 800 mm | £289.80 ex VAT per unit | Comms Express list price, November 2026 |
| Eziblank blanking panels, 10 x 6U pack | £128.76 ex VAT per pack | Comms Express list price, November 2026 |
| Ezibrush 1U brush panel, 19 inch | £110.68 ex VAT per unit | Comms Express list price, November 2026 |
| Full aisle enclosure, installed | About EUR 1,500 to EUR 3,000 per rack position | Credence Research estimate from component prices and project scopes |
| Enclosed in-row cooled pod, frame and doors | About EUR 15,000 to EUR 40,000 per pod | Credence Research estimate from project scopes, excluding coolers |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Reporting rules, PUE caps and new halls lift orders
EU reporting rules make airflow losses visible
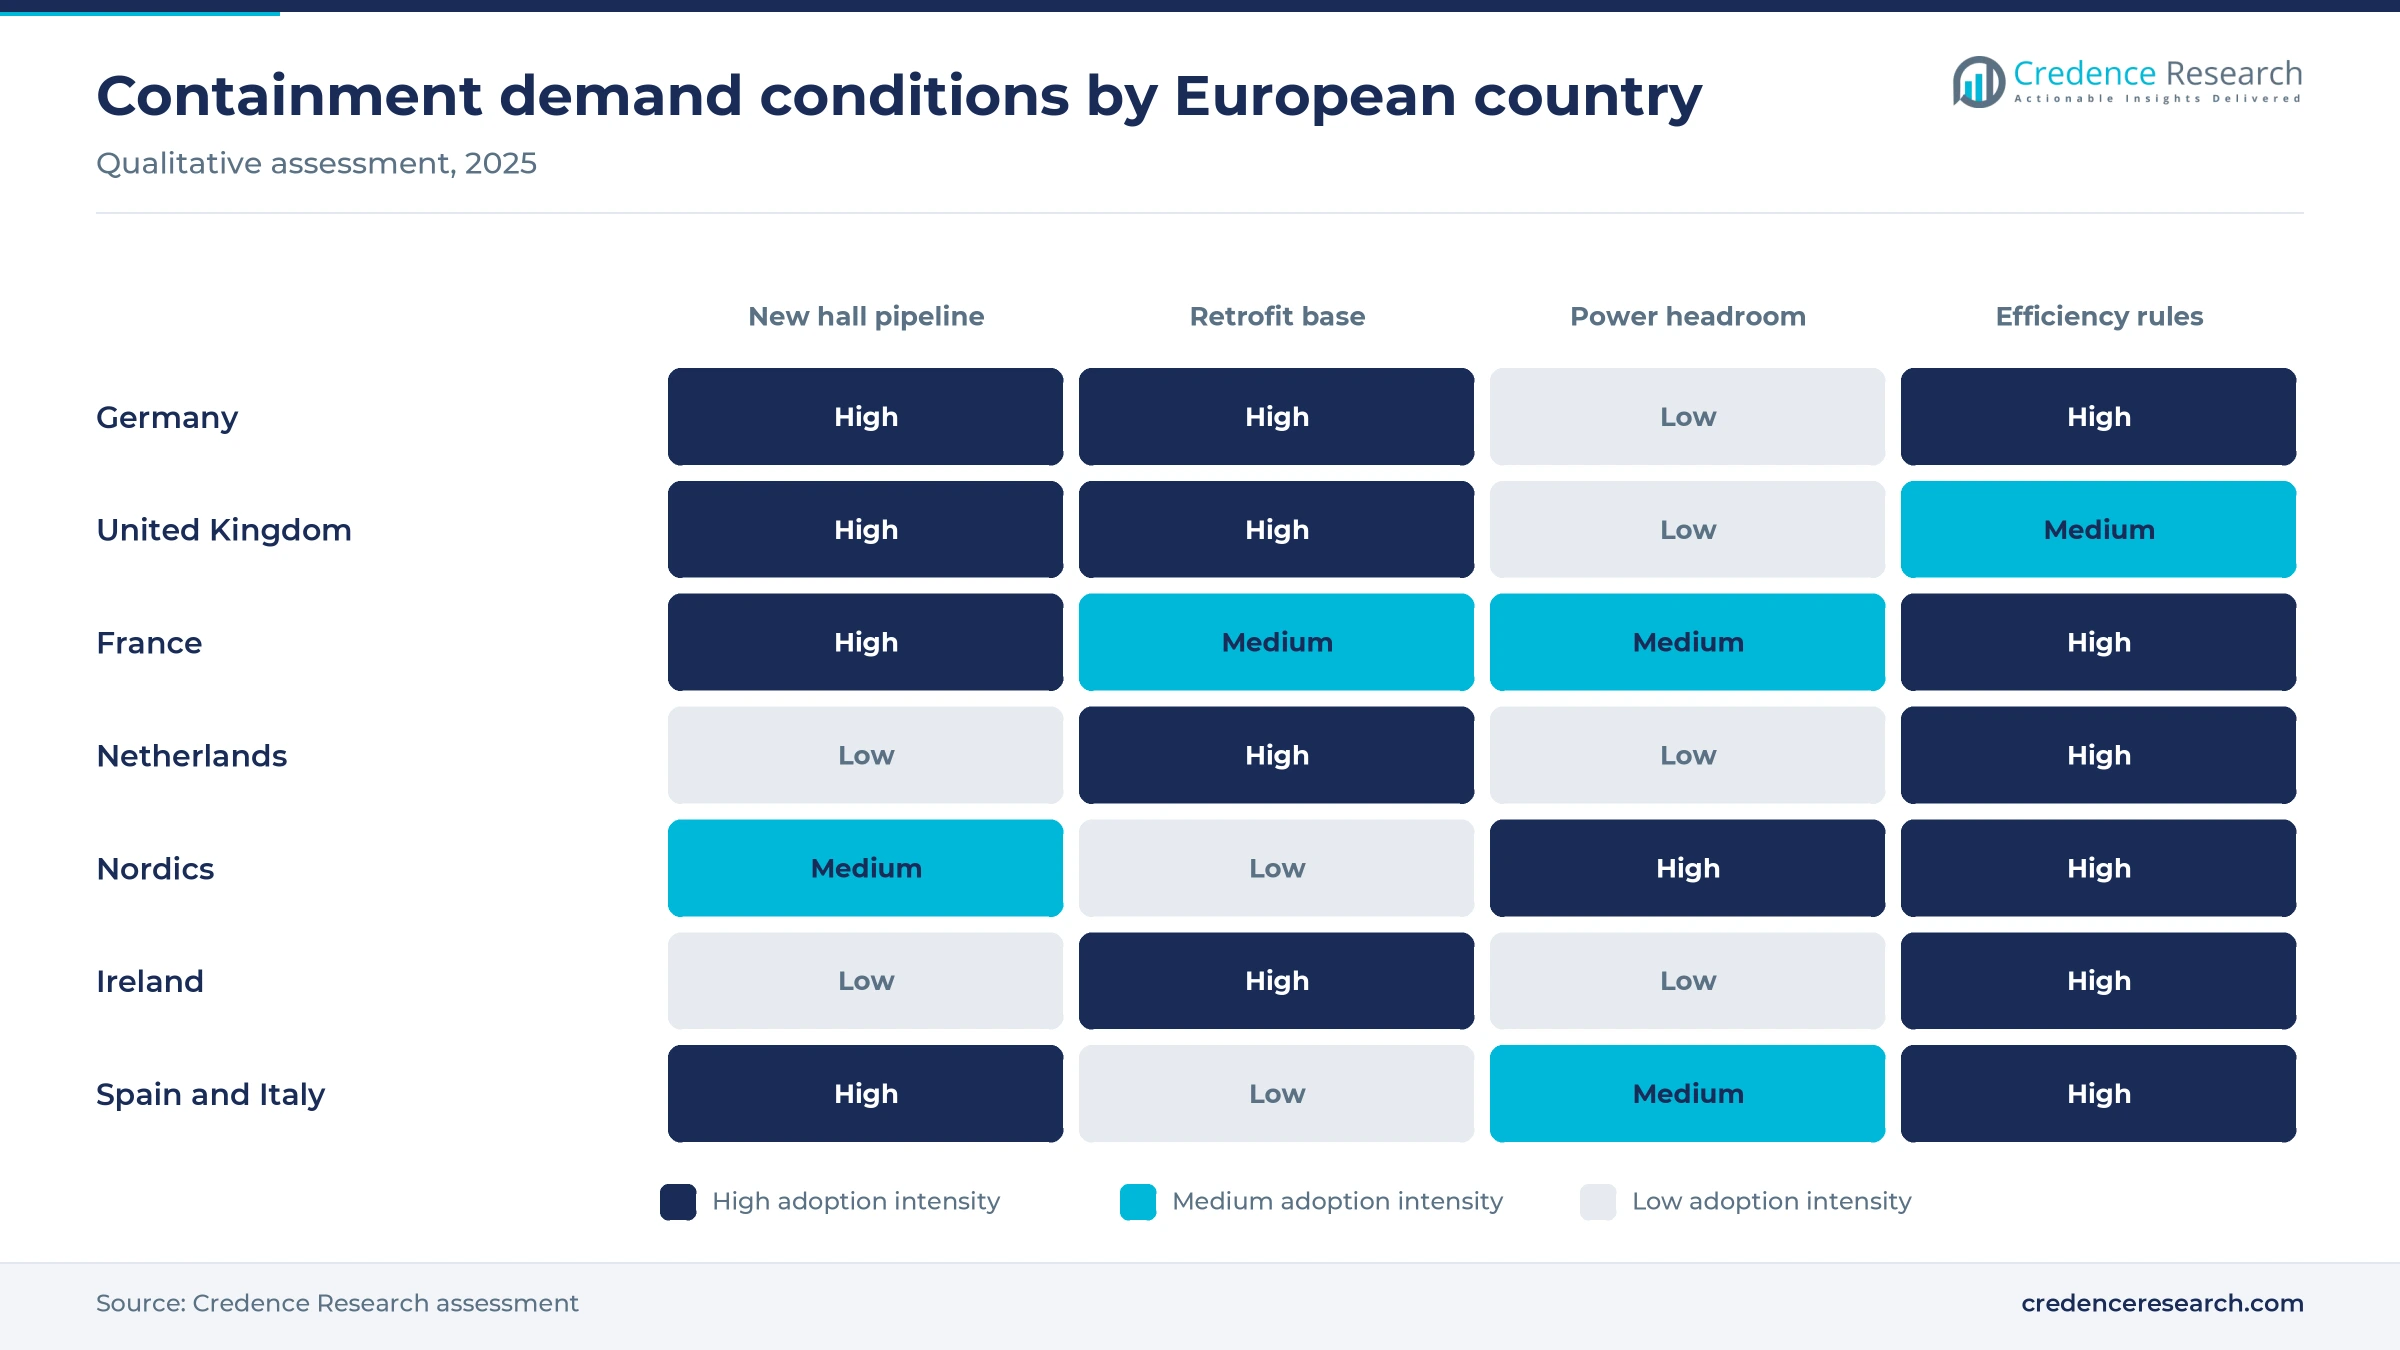
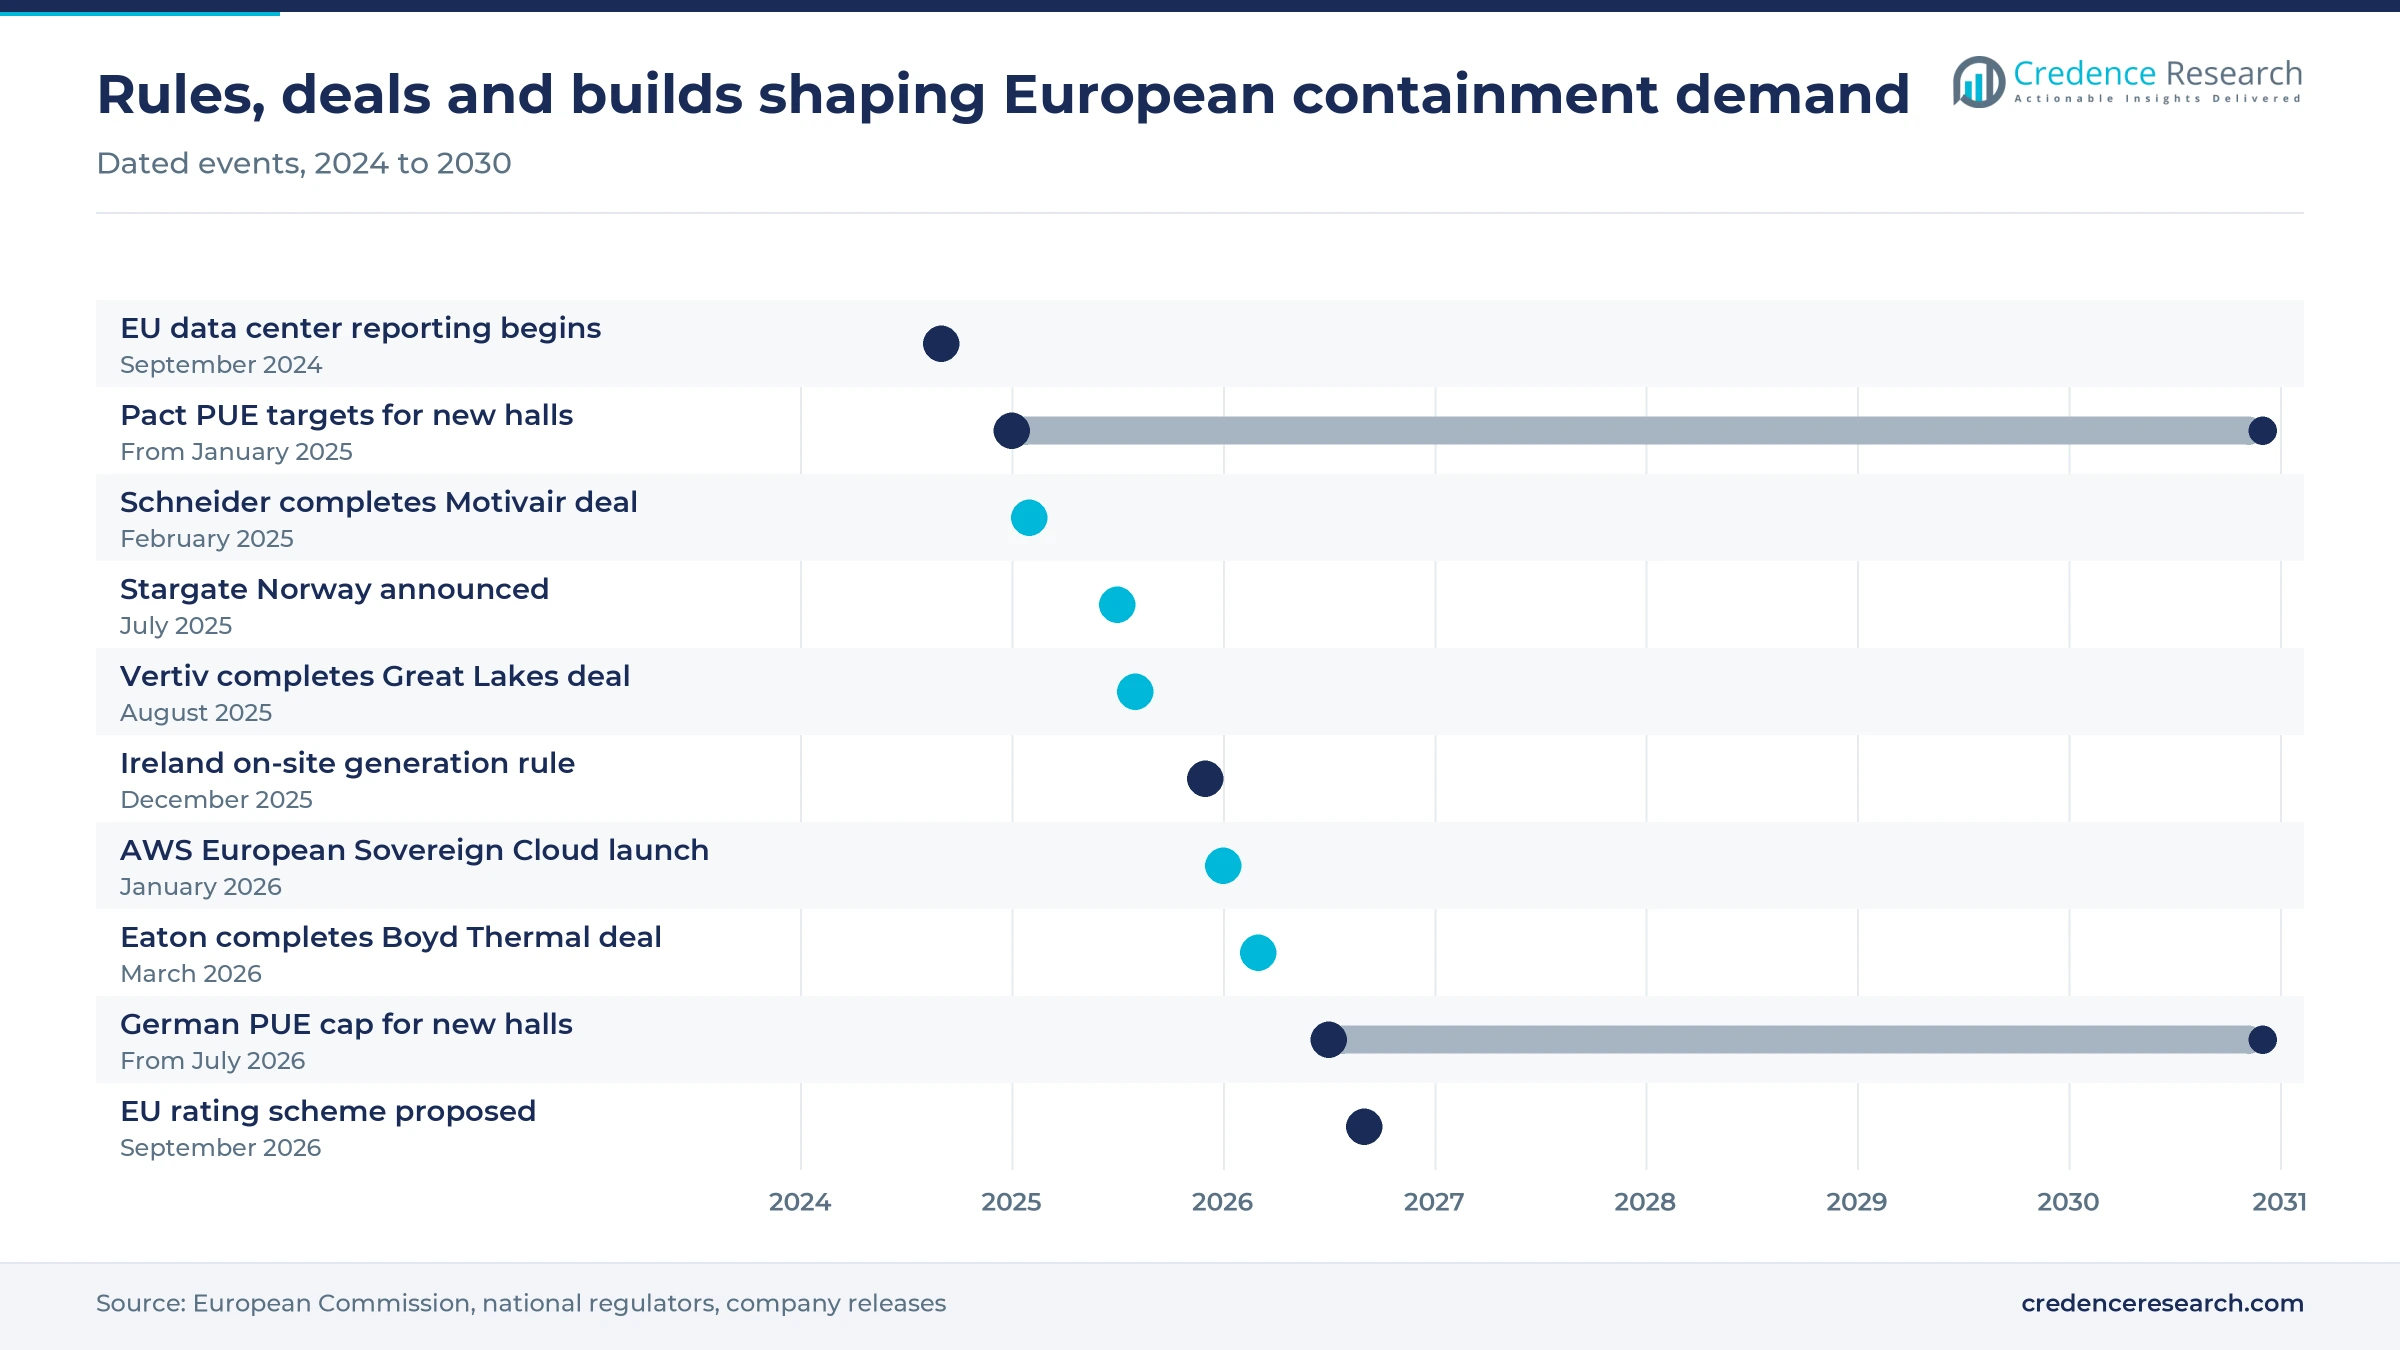
European rules now force operators to publish the efficiency figures that poorly sealed aisles damage. Under Delegated Regulation 2024/1364, operators with an IT load of at least 500 kW had to report 24 indicators, including energy use, by Sept. 15, 2024, and again by May 15, 2025. The Commission proposed a common rating scheme for data centers above 500 kW in September 2026, with the first labels expected in 2027. Members of the Climate Neutral Data Centre Pact also committed new halls to an annual PUE of 1.3 in cool climates and 1.4 in warm climates from January 2025. Published scores reward cheap fixes first, which favors containment kits over replacing cooling plant.
German efficiency caps turn containment into a rule
Germany, the largest country market, writes efficiency targets into law, which makes tight air separation close to mandatory. The Energy Efficiency Act in force requires halls of 300 kW or more that open from July 1, 2026 to reach a PUE of 1.2, according to a White & Case summary. A ministerial draft published on April 9, 2026 would ease that cap to 1.3 and relax targets for existing halls, according to Orrick. The ministerial draft had still not been adopted by November 2026. Bitkom counted 2,980 MW of German data center IT capacity in 2025, up 9% in a year. Even the looser draft cap is hard to meet without sealed aisles, so retrofit specialists with German crews gain under either version.
Tight colocation supply keeps new suites in demand
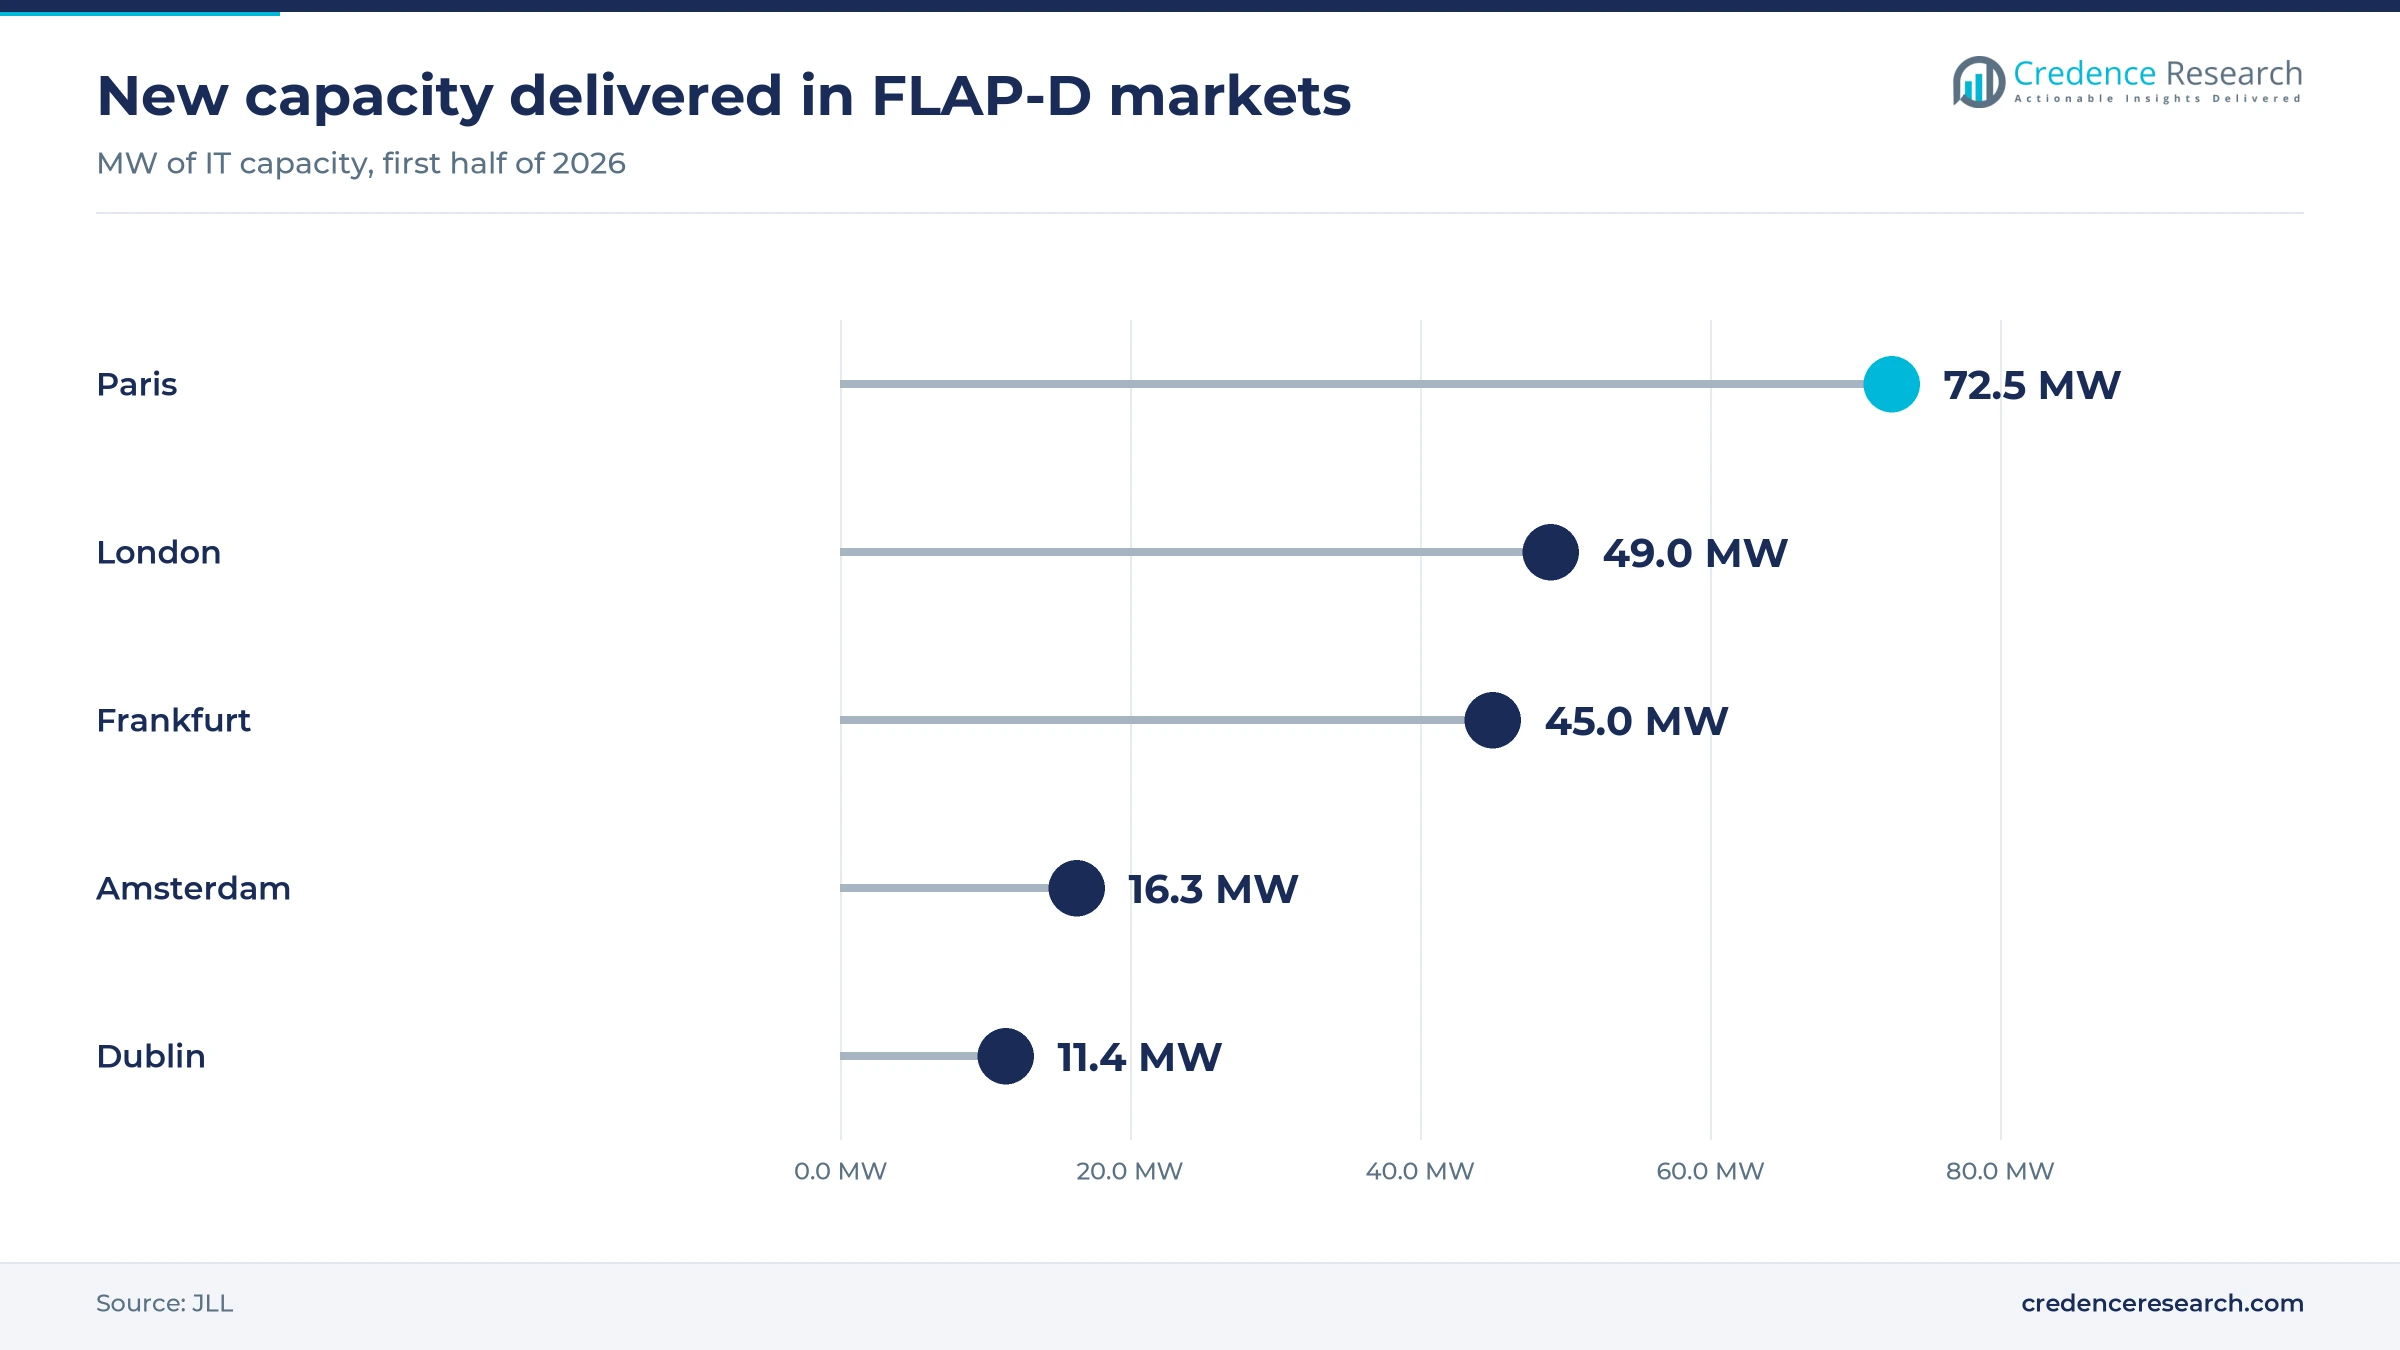
Every new colocation suite needs its own enclosures, so the pace of new capacity sets the base of demand. JLL counted about 3.8 GW of live capacity in the FLAP-D markets in the first half of 2026, with 1.4 GW under construction. Colocation vacancy of 6.4% in the second quarter of 2026 keeps enclosure demand tied closely to each new building. CBRE reported 699 MW of colocation take-up in 2024 and said demand would exceed new supply for a third straight year. Low vacancy means tenants commit before suites are finished, so landlords order enclosures earlier in each build.
AI rack densities push air separation to its limits
Graphics processor racks produce far more heat than the cabinets that older halls were designed for, which makes tight air separation essential for the air-cooled share of each hall. Schneider Electric said in September 2025 that the industry is moving past 140 kW per rack. Bitkom expects German AI capacity to rise from 530 MW to 2,020 MW by 2030, or about 40% of national capacity. The EU had 19 AI Factories in 16 countries in setup by late 2025, according to the Commission. Suppliers that design enclosures around liquid manifolds and residual air loads win these suites, a shift that favors In-row Cooling Containment growth.
Hybrid liquid and air halls reshape enclosure design
Hybrid liquid and air halls shift enclosure design
Operators are shifting from all-air rooms to hybrid suites that mix liquid-cooled AI racks with air-cooled servers, which changes what containment must do. Schneider Electric took a controlling interest in liquid cooling maker Motivair in February 2025, and its range now spans coolant distribution units from 105 kW to 2.5 MW. Legrand fitted ColdLogik rear-door heat exchangers at the NorthC site near Basel, Switzerland, in November 2025, and NorthC reported an energy cut of about 80%. Containment still controls residual heat from racks that keep fans. Suppliers of direct-to-chip cooling loops and enclosure makers increasingly design these suites together, a pattern that favors Hybrid Containment.
Power and rack groups buy specialists to sell whole rows
Large electrical groups are shifting toward selling racks, containment, cooling and power as one row package, which narrows the room for stand-alone panel suppliers. Vertiv completed its purchase of Great Lakes Data Racks and Cabinets, which has plants in the U.S. and Europe, for about USD 200 million in August 2025. Eaton completed its USD 9.5 billion acquisition of Boyd Thermal in March 2026 to add liquid cooling. Siemens and Rittal formed a partnership in March 2026 to standardize power distribution for IEC markets, with first customer projects under way, and Siemens expects rack power density to rise by more than 10 times by 2030. Operators buying through pan-European frameworks favor these packages, while independent installers face more price pressure.
Heat reuse targets reward tightly sealed hot aisles
Rules that require waste heat reuse create an opening for hot aisle systems, because only well-sealed aisles return air at stable, usable temperatures. The German heat reuse share of 10% to 20% for new halls, noted in the segment analysis, applies from July 2026 under the current act. The Commission's rating scheme proposal of September 2026 would also score how much waste heat each site reuses. The Commission estimates that reusing about half of EU data center waste heat could meet the heating demand of four million households. OpenAI and Nscale plan to offer surplus heat from the Narvik campus in Norway to local low-carbon businesses. Enclosure suppliers that work with heat network designers and precision cooling equipment makers gain a stronger case with operators and municipalities.
Southern and sovereign AI campuses open new orders
Power shortages in the northern hubs create an opening in southern Europe and in public AI campuses, where large halls will need enclosures from the first day. Cushman & Wakefield said in June 2026 that Madrid could reach 1,105 MW of capacity by 2030. JLL expects greenfield land to rise from 8% to 39% of the new pipeline, because AI campuses need more space and power. The EU has also called for up to seven AI Gigafactories, each with more than 100,000 advanced AI processors. Installers that set up crews in Spain, Italy and secondary markets can win these packages before larger competitors arrive.
Liquid cooling and grid limits cap air-side spending
Direct liquid cooling lowers air-side content per MW
Halls that remove most heat through liquid loops need less air containment for each megawatt of IT load. Stargate Norway, a 230 MW campus announced in July 2025, plans a sealed liquid loop that brings coolant directly to the chips. Schneider Electric's ChilledDoor rear-door unit cools racks of up to 75 kW without an enclosed aisle. Suppliers that sell enclosures by rack count are most exposed in AI training halls, so they need to sell residual air control with the liquid system.
Grid limits delay or block hall fit-outs
Containment is installed near the end of a build, so power limits delay enclosure orders as well. Ireland's energy regulator ruled in December 2025 that new data centers must provide on-site generation or storage covering 100% of their import capacity before ramping up. The Noord-Holland province bars new hyperscale campuses for the duration of its 2025 to 2027 strategy. Installers concentrated in Dublin and Amsterdam are most exposed, and they need to follow projects toward Spain, Italy and the Nordics.
Rising land and power costs squeeze fit-out budgets
Developers pay more for powered land before they reach the fit-out stage, which leaves less room in budgets for premium enclosures. JLL put prime powered land in the FLAP-D markets at EUR 2.26 million per MW in 2026, 82% more than the EUR 1.24 million of 2021. Developers respond by value-engineering white space, choosing simpler cold aisle kits over ducted hot aisle systems. Suppliers of premium enclosures are most exposed, unless they show lower fan and chiller bills.
Cheap catalog parts cap retrofit prices
Simple retrofit parts are sold through distributors at low list prices, which limits what installers can charge for basic sealing work. With a 1U brush panel listed at £110.68 before VAT in November 2026, as the pricing table shows, facility teams can seal gaps themselves without hiring a contractor. Small installers that rely on panel sales are most exposed, so they protect margins with surveys, thermal mapping and maintenance contracts.
Germany leads while Spain and Italy grow fastest
| Country | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Germany | 228.0 | 22.0% | 10.4% |
| Rest of Europe | 181.3 | 17.5% | 10.6% |
| United Kingdom | 160.6 | 15.5% | 10.6% |
| France | 119.2 | 11.5% | 10.3% |
| Netherlands | 97.4 | 9.4% | 8.4% |
| Nordics | 94.3 | 9.1% | 10.5% |
| Spain and Italy | 82.9 | 8.0% | 12.4% |
| Ireland | 72.5 | 7.0% | 7.8% |
Germany leads on Frankfurt capacity and strict caps
Germany held a 22.0% share of 2025 spending and grows at 10.4% a year. The Frankfurt area holds just over 1,100 MW, more than a third of German capacity, according to Bitkom and its colocation vacancy was only 3.1% in the second quarter of 2026, according to JLL. Bitkom also counted record investment of EUR 12 billion in IT hardware and EUR 3.5 billion in buildings and technical infrastructure in 2025. The PUE caps noted above, in their current or drafted form, mean almost every new German hall is designed with ducted aisles from the start.
The United Kingdom adds suites around London
The United Kingdom held a 15.5% share of 2025 spending and grows at 10.6% a year. London delivered 49 MW of new capacity in the first half of 2026, with vacancy of 7.4%, according to JLL. Most new suites are fitted out by colocation landlords for many tenants, which favors modular kits that can be moved when tenants change. Tenant churn in older London halls also triggers resealing work, so retrofit kits keep selling even where grid limits slow new sites. The U.K. sits outside EU reporting rules, so U.K. operators will not face the planned EU label from 2027.
France gains from large AI investment pledges
France held an 11.5% share of 2025 spending and grows at 10.3% a year. Paris delivered 72.5 MW in the first half of 2026, the most of any FLAP-D market, with vacancy of 8.0%, according to JLL. The French presidency said in February 2025 that more than EUR 109 billion of infrastructure investment had been announced at the AI Action Summit, and it pointed investors to suitable sites for data center projects. Nuclear power gives French halls a low-carbon supply, so buyers judge enclosures mainly on PUE gains and fit with liquid cooling.
The Netherlands slows under cluster and grid limits
The Netherlands held a 9.4% share of 2025 spending and grows at 8.4% a year, among the slowest rates in Europe. Amsterdam delivered only 16.3 MW in the first half of 2026, according to JLL. In Noord-Holland, new data centers above 2,000 square meters or 5 MVA may only be built in designated clusters, and 88 such sites were operating in early 2024. With little new space, Dutch demand shifts toward retrofits that improve efficiency in existing halls, which favors cold aisle kits and blanking parts.
Spain and Italy grow fastest on new southern hubs
Spain and Italy held an 8.0% share of 2025 spending and are the fastest-growing area at 12.4% a year. JLL said in October 2026 that Milan had 230 MW and Madrid 165 MW of installed capacity, the two largest markets outside FLAP-D. Spain's operational capacity grew about 9% in a year, according to Cushman & Wakefield, and more than half of Spanish power already comes from renewables. Warm summers make tight air separation more valuable here, because free cooling hours are fewer than in northern Europe.
The Nordics attract liquid-cooled AI campuses
The Nordics held a 9.1% share of 2025 spending and grow at 10.5% a year. OpenAI, Nscale and Aker plan 230 MW for Stargate Norway in Narvik, with a target of 100,000 NVIDIA GPUs by the end of 2026 and room for another 290 MW. Cheap renewable power and cold air favor large training halls, which tend to use liquid cooling, so air containment content per MW is lower than in Frankfurt colocation suites. Nordic demand will depend on how many enterprise and colocation rows stay air-cooled.
Ireland holds a large base but faces power limits
Ireland held a 7.0% share of 2025 spending and grows at 7.8% a year, the slowest rate in this report. Data centers used 23% of metered electricity in Ireland in 2025, up from 5% in 2015, with consumption rising from 6,973 GWh in 2024 to 7,663 GWh, according to the CSO. Dublin delivered 11.4 MW in the first half of 2026. The on-site generation rule noted above slows new halls, so Irish spending relies more on retrofits in the existing hyperscale and colocation base.
Rest of Europe follows sovereign cloud expansion
The rest of Europe, including Switzerland, Belgium, Poland, Austria and Portugal, held a 17.5% share of 2025 spending and grows at 10.6% a year. AWS announced in January 2026 that it plans sovereign Local Zones in Belgium, the Netherlands and Portugal. The rear-door retrofit near Basel noted in the trends shows how Swiss operators upgrade older halls for AI loads without a full rebuild. Demand here arrives in smaller orders from enterprise, public sector and regional colocation buyers, which favors modular kits sold through distributors.
Cooling deals and sovereign cloud builds in 2025-26
| Development | Status and market relevance |
|---|---|
| In February 2025, Schneider Electric completed its purchase of a controlling interest in Motivair, a maker of liquid cooling systems. | Acquisition completed; Motivair units were launched as a combined liquid cooling range in September 2025. |
| In August 2025, Vertiv completed its acquisition of Great Lakes Data Racks and Cabinets for about USD 200 million. | Acquisition completed; it adds rack plants in the U.S. and Europe to the Vertiv white space range. |
| In November 2025, Legrand completed a rear-door cooling upgrade at the NorthC Münchenstein site near Basel, Switzerland. | Completed and operational; the site is now equipped for AI and HPC loads. |
| In January 2026, AWS launched its European Sovereign Cloud in Brandenburg, Germany, backed by more than EUR 7.8 billion of investment. | Operational launch; Local Zones in Belgium, the Netherlands and Portugal are planned. |
| In March 2026, Eaton completed its USD 9.5 billion acquisition of Boyd Thermal, a maker of liquid cooling and thermal systems. | Acquisition completed; it adds liquid cooling to Eaton racks, containment and power products. |
Panels, chimneys and in-row pods trade cost and density
- Ducted hot aisle enclosures capture exhaust air at rack level and return it to cooling plant, which keeps the room at supply temperature and suits heat recovery.
- Cold aisle kits enclose the supply side with doors and roof panels, which suits retrofits of raised-floor rooms at the lowest installed cost.
- Rack chimneys duct hot air from single cabinets into a ceiling plenum, which suits mixed rooms where full aisles cannot be closed.
- In-row cooled pods place coolers between racks inside a sealed row, which supports higher loads without changing the room plant.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Rack makers and cooling specialists compete on fit
Competition in the Europe data center containment market turns on how well suppliers fit enclosures to existing racks, fire systems and cooling plant, more than on panel prices alone. Schneider Electric, Vertiv, Rittal, Legrand and Eaton compete by bundling containment with racks, power distribution and monitoring on pan-European frameworks, and each has added liquid cooling or rack capacity through acquisitions since 2025. STULZ and Airedale compete through in-row coolers built into enclosed pods, while Huawei sells prefabricated rows and prefabricated modules with integrated aisles. Conteg, PRISM DCS and EDP Europe win retrofit and custom work through short lead times and site surveys. Specialists also gain where enclosures must fit racks from several makers in older halls.
How is the supply side organized and where do margins sit?
Supply is organized in three layers that often overlap on large projects. Global power and rack groups such as Schneider Electric, Vertiv, Rittal, Legrand, Eaton and Huawei sell containment as part of complete rows with racks, power distribution and monitoring. Cooling makers such as STULZ and Airedale supply the in-row units around which enclosed pods are built. Regional manufacturers such as Conteg, PRISM DCS and Eziblank maker EDP Europe sell custom panels, retrofit kits and caging. Entry barriers are low for simple panels but higher for fire-rated roofs and hybrid suites, so margins sit with integrators and service work rather than commodity panels.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Schneider Electric SE | Full-line supplier | APC NetShelter aisle containment, racks, Motivair liquid cooling and prefabricated rooms |
| Vertiv Holdings Co | Full-line supplier | Aisle containment, racks and cooling for colocation and hyperscale halls |
| Rittal GmbH & Co. KG | Rack and cooling manufacturer | Aisle containment, racks and in-row liquid cooling packages made in Germany |
| Legrand SA (Minkels, USystems) | Rack and containment manufacturer | Minkels customized containment and USystems ColdLogik rear-door coolers |
| Eaton Corporation plc | Full-line supplier | Hot and cold aisle containment sold with racks, UPS and liquid cooling |
| STULZ GmbH | Cooling equipment manufacturer | CyberRow in-row units for contained hot and cold aisles |
| Huawei Technologies Co., Ltd. | Full-line supplier | Prefabricated modular rows with integrated aisle containment and cooling |
| Leviton Manufacturing Co. (PRISM DCS) | Regional manufacturer | U.K.-made racks, cabinets, hot and cold aisle containment and caging |
| Modine Manufacturing Company (Airedale) | Cooling equipment manufacturer | In-row coolers and containment design support for enclosed pods |
| Conteg spol. s r.o. | Regional manufacturer | Czech-made racks, aisle containment and in-row cooling units |
| EDP Europe Ltd (Eziblank) | Specialist | Eziblank blanking panels, brush strips and gap systems for retrofits |
Air-side discipline stays essential in hybrid halls
Credence Research's view is that containment remains essential in European halls even as liquid cooling spreads, but its value is moving from panels to integrated row design. Hybrid suites still need tight control of residual air, and published PUE scores keep retrofit demand alive in older colocation halls. Suppliers that design enclosures together with liquid manifolds, fire systems and heat recovery will gain share. Buyers should specify containment early in each build and include maintenance, since gaps that open after tenant changes erode the efficiency gains that justified the spending.
Estimates rebuilt from capacity, rack and price data
The report uses 2025 as the base year and forecasts European containment spending for 2026 to 2035. Market values come from the Credence Research model, which multiplies new and refitted rack positions by installed costs, adds in-row pods, sealing parts and maintenance, and checks the result against capacity and project data. This edition replaces an earlier estimate with a 2024 base year. Segment and country splits are Credence Research estimates built from the same inputs. German efficiency targets follow the act in force, and a pending 2026 draft that would ease them is noted where relevant. Sources include EU and national regulators, statistics offices, industry associations, property adviser reports, list prices and company releases, and no interviews or surveys were conducted.
Hybrid halls and southern hubs carry growth to 2035
European containment spending should rise from USD 1.14 billion in 2026 to USD 2.77 billion by 2035, as colocation and cloud halls in Frankfurt, London and Paris keep adding suites and new campuses open in Spain, Italy and the Nordics. Hot aisle systems will remain the largest type, while enclosed in-row pods and hybrid designs gain as liquid and air cooling share rooms. Retrofits will matter more in Dublin and Amsterdam, where power limits slow new sites, and suppliers tied to hyperscale campus programs will see the largest orders. A fast move to fully liquid-cooled AI halls is the main risk.
How wide is the range of outcomes to 2035?
The outcome depends on how quickly planned capacity reaches construction and how much air-side content survives in liquid-cooled halls. Faster grid connections in Germany, Spain and Italy and an early start to AI Gigafactories would push growth toward the upside. A rapid move to fully liquid-cooled AI halls, or long power delays in Dublin, Amsterdam and Frankfurt, would hold spending near the downside case. Retrofit demand driven by efficiency rules limits how far growth can fall.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 7.8% | USD 2.25 billion | Grid delays persist and AI halls move to almost fully liquid cooling |
| Base | 10.32% | USD 2.77 billion | Planned FLAP-D and southern halls reach fit-out close to announced dates |
| Upside | 12.1% | USD 3.20 billion | Faster connections and AI Gigafactory awards bring several large campuses forward |
Frequently Asked Questions
How big is the Europe data center containment market?
What are data center containment solutions?
Which type of containment leads in Europe?
Which country leads European containment demand?
Which companies supply data center containment in Europe?
How do EU rules affect containment demand?
How much does containment cost in Europe?
Does liquid cooling remove the need for containment?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Containment Type
- 1.2.1 Hot Aisle Containment
- 1.2.2 Cold Aisle Containment
- 1.2.3 Rack-based Chimney Containment
- 1.2.4 In-row Cooling Containment
- 1.3 By Data Center Type
- 1.3.1 Colocation Data Center
- 1.3.2 Hyperscale Data Center
- 1.3.3 Enterprise Data Center
- 1.3.4 Cloud Data Center
- 1.3.5 Others
- 1.4 By Arrangement
- 1.4.1 Modular Containment
- 1.4.2 Rigid Containment
- 1.4.3 Hybrid Containment
- 1.4.4 Others
- 1.5 By Country
- 1.5.1 Germany
- 1.5.2 United Kingdom
- 1.5.3 France
- 1.5.4 Netherlands
- 1.5.5 Nordics
- 1.5.6 Ireland
- 1.5.7 Spain and Italy
- 1.5.8 Rest of Europe
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.04 billion → 2035: USD 2.77 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Data Center Containment Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Data Center Containment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Data Center Containment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Data Center Containment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Data Center Containment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Data Center Containment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Data Center Containment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Data Center Containment Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.04 billion → 2035: USD 2.77 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Data Center Containment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Containment Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hot Aisle Containment
- 12.3.7.2 Cold Aisle Containment
- 12.3.7.3 Rack-based Chimney Containment
- 12.3.7.4 In-row Cooling Containment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Data Center Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Colocation Data Center
- 12.4.7.2 Hyperscale Data Center
- 12.4.7.3 Enterprise Data Center
- 12.4.7.4 Cloud Data Center
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Arrangement - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Modular Containment
- 12.5.7.2 Rigid Containment
- 12.5.7.3 Hybrid Containment
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Germany
- 12.6.7.2 United Kingdom
- 12.6.7.3 France
- 12.6.7.4 Netherlands
- 12.6.7.5 Nordics
- 12.6.7.6 Ireland
- 12.6.7.7 Spain and Italy
- 12.6.7.8 Rest of Europe
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Data Center Containment Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Country-Level Shares, 2025
- 13.2 Country Market Size Comparison, 2025
- 13.3 Country Market Forecasts, 2025-2035
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Data Center Containment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Data Center Containment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Schneider Electric SE
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Vertiv Holdings Co
- 17.4 Rittal GmbH & Co. KG
- 17.5 Legrand SA (Minkels, USystems)
- 17.6 Eaton Corporation plc
- 17.7 STULZ GmbH
- 17.8 Huawei Technologies Co., Ltd.
- 17.9 Leviton Manufacturing Co. (PRISM DCS)
- 17.10 Modine Manufacturing Company (Airedale)
- 17.11 Conteg spol. s r.o.
- 17.12 EDP Europe Ltd (Eziblank)
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

