
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Grid Modernization Market Size 2024 | USD 11,227.24 million |
| Europe Grid Modernization Market , CAGR | 16.99% |
| Europe Grid Modernization Market Size 2032 | USD 39,393.23 million |
Market Overview
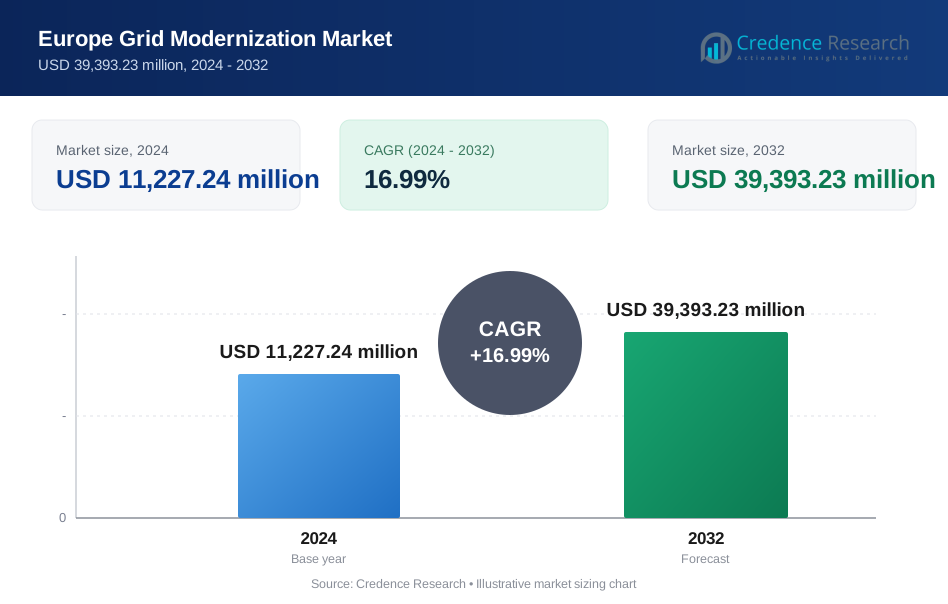
Europe Grid Modernization market size was valued at USD 11,227.24 million in 2024 and is anticipated to reach USD 39,393.23 million by 2032, at a CAGR of 16.99% during the forecast period (2024-2032).
The Europe Grid Modernization market is driven by increasing investments in smart grid infrastructure, rising integration of renewable energy sources, and supportive government policies promoting energy efficiency. The need to enhance grid reliability, reduce transmission losses, and improve demand response mechanisms further accelerates market growth. Technological advancements, including AI-driven grid management, IoT-enabled smart meters, and advanced energy storage solutions, are transforming the sector. Additionally, the push toward decarbonization and electrification of transportation fuels demand for modernized grids. Key trends include the adoption of digital substations, automation in grid operations, and cybersecurity advancements to safeguard critical energy infrastructure. Utilities are focusing on real-time monitoring and predictive maintenance to optimize grid performance. The shift toward decentralized power generation, including microgrids and distributed energy resources, is reshaping grid dynamics. As energy consumption patterns evolve, utilities and policymakers are prioritizing resilience, sustainability, and grid intelligence to meet future energy demands efficiently.
Europe's grid modernization is advancing rapidly, driven by strong governmental policies, increasing renewable energy adoption, and the need for enhanced grid resilience. Leading countries such as the UK, Germany, France, and Italy are heavily investing in smart grid technologies, energy storage solutions, and digital substations to optimize power distribution and manage fluctuating renewable energy sources. Northern and Eastern European nations, including Sweden, Denmark, Poland, and Austria, are also making strides in modernizing their grids with automation, AI-driven analytics, and cybersecurity enhancements. Several key players are at the forefront of this transformation, including ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric Europe, Alstom SA, Toshiba Europe, Landis+Gyr AG, Siemens Gamesa, and Eaton Europe. These companies are driving innovation in grid digitalization, energy management systems, and infrastructure upgrades, ensuring a more efficient, reliable, and sustainable electricity network across Europe.
Market Insights
- The Europe Grid Modernization market was valued at USD 11,227.24 million in 2024 and is projected to reach USD 39,393.23 million by 2032, growing at a CAGR of 16.99% from 2024 to 2032.
- Increasing demand for renewable energy integration and energy efficiency are key drivers of grid modernization in Europe.
- The adoption of smart grid technologies, energy storage solutions, and AI-driven grid management systems is driving significant market trends.
- Competitors in the market, such as ABB Ltd., Siemens AG, and Schneider Electric SE, are focusing on enhancing grid automation, digital substations, and cybersecurity solutions.
- High initial investment costs and the complexity of integrating new technologies into existing infrastructure are major market restraints.
- The UK, Germany, France, and Italy lead the market, with growing investments in smart grid technologies and renewable energy integration.
- Northern and Eastern Europe are also witnessing steady growth, with countries like Sweden, Poland, and Austria making significant advancements in grid modernization.
Market Drivers
Rising Investments in Smart Grid Infrastructure
The Europe Grid Modernization market is witnessing significant growth due to increasing investments in smart grid infrastructure. Governments and utility companies are allocating substantial funds to upgrade aging power grids with advanced technologies. For instance, the European Union's Green Deal and other regional policies encourage smart grid deployment, supporting a transition toward a low-carbon economy. Additionally, initiatives such as the European Energy Efficiency Directive promote the adoption of intelligent grid systems, further accelerating market expansion.
Increasing Demand for Grid Reliability and Resilience
Ensuring grid reliability and resilience against extreme weather events and cyber threats is driving modernization efforts across Europe. Climate change-induced challenges, including storms and heatwaves, pose risks to traditional power grids. As a result, utilities are investing in predictive maintenance, real-time monitoring, and self-healing grid technologies to enhance reliability. For instance, the European Commission has recognized the need for grid resilience, leading to investments in secure and resilient grid modernization solutions. Additionally, the rising threat of cyberattacks on energy infrastructure has prompted the deployment of robust cybersecurity measures. Governments are implementing stringent regulations to safeguard critical energy assets, driving investments in secure and resilient grid modernization solutions.
Technological Advancements in Grid Modernization
The adoption of cutting-edge technologies is revolutionizing grid modernization in Europe. The integration of IoT-enabled smart meters, AI-powered demand response systems, and blockchain-based energy trading platforms is transforming energy management. For example, the European Technology and Innovation Platform for Smart Grids for Energy Transition (ETIP SNET) has been actively involved in identifying unresolved research and innovation issues, which supports the development of these technologies. Digitalization and automation are optimizing grid operations, reducing costs, and improving efficiency. Moreover, advancements in distributed energy resources (DERs), such as microgrids and virtual power plants, are reshaping energy distribution models. These innovations enhance energy security, support decentralized power generation, and enable a more sustainable and intelligent grid ecosystem.
Integration of Renewable Energy Sources
The rapid integration of renewable energy sources, such as wind and solar power, is a key driver of grid modernization in Europe. Countries are focusing on reducing dependence on fossil fuels and meeting ambitious carbon neutrality goals. However, the intermittent nature of renewables necessitates advanced grid management solutions, such as AI-driven analytics and battery storage systems. Smart grids enable better forecasting, load balancing, and efficient distribution of renewable energy. The adoption of digital substations and automation technologies also enhances grid flexibility, ensuring seamless integration of renewable energy into the power system.
Market Trends
Adoption of Smart Grid Technologies
The increasing adoption of smart grid technologies is a key trend shaping Europe’s grid modernization market. Utilities are deploying IoT-enabled smart meters, digital substations, and AI-driven grid management systems to enhance operational efficiency. For instance, the European Union's Third European Energy Liberalization Package has set a goal to install "intelligent metering systems" in 80 percent of households by 2020, with some countries like Italy already achieving nearly 100 percent penetration. These technologies enable real-time monitoring, predictive maintenance, and automated fault detection, reducing downtime and optimizing energy distribution. Additionally, smart grids facilitate dynamic load balancing, ensuring efficient electricity flow and minimizing transmission losses. As regulatory bodies emphasize energy efficiency and grid optimization, the integration of digital technologies continues to accelerate across European power networks.
Expansion of Energy Storage Solutions
The expansion of energy storage solutions is transforming grid modernization efforts across Europe. With the rising share of intermittent renewable energy sources, advanced battery storage systems, pumped hydro storage, and hydrogen-based storage technologies are gaining traction. These solutions help stabilize the grid by storing excess renewable energy and releasing it during peak demand periods. Grid-scale energy storage enhances power reliability, mitigates fluctuations in renewable energy generation, and supports decentralized energy models. Investments in lithium-ion and solid-state battery technologies, coupled with government incentives, are further driving advancements in energy storage integration.
Growing Focus on Grid Decentralization
The shift toward grid decentralization is reshaping Europe’s electricity infrastructure. Distributed energy resources (DERs), including rooftop solar panels, wind farms, and microgrids, are gaining prominence, reducing reliance on centralized power generation. This transition enhances energy security, fosters local energy independence, and enables peer-to-peer energy trading through blockchain technology. Utilities are adopting virtual power plants (VPPs) to aggregate and optimize decentralized energy generation, ensuring efficient grid management. As more consumers generate and store their own electricity, the demand for flexible, decentralized grid solutions is expected to rise significantly.
Strengthening Cybersecurity in Energy Infrastructure
Cybersecurity has become a critical focus area in Europe’s grid modernization initiatives. As digitalization and automation increase, energy networks are becoming more vulnerable to cyber threats and data breaches. Governments and utility companies are investing in robust cybersecurity frameworks, incorporating AI-driven threat detection, blockchain-based security protocols, and advanced encryption methods. Regulatory agencies are enforcing stricter cybersecurity mandates to protect critical grid infrastructure from cyberattacks. Strengthening grid security ensures operational continuity, safeguards consumer data, and enhances resilience against emerging digital threats in the energy sector.
Market Challenges Analysis
High Implementation Costs and Infrastructure Upgrades
The high costs associated with grid modernization pose a significant challenge for utilities and governments across Europe. Upgrading aging power infrastructure with smart grid technologies, digital substations, and energy storage solutions requires substantial capital investment. For instance, the European Commission has estimated that about €584 billion of electricity infrastructure investments are needed between 2020 and 2030, particularly in the distribution grid, to reach the Fit for 55 and REPowerEU objectives for renewables and energy efficiency. Many regions face financial constraints, limiting their ability to deploy large-scale modernization initiatives. Additionally, integrating advanced technologies such as IoT-enabled meters, AI-driven analytics, and cybersecurity frameworks increases overall project expenditures. The need for extensive infrastructure overhauls, including replacing outdated transmission lines and substations, further adds to the financial burden. While government incentives and funding programs aim to support modernization efforts, securing long-term investments remains a challenge for several utilities.
Regulatory and Technological Integration Complexities
The complex regulatory landscape and technological integration challenges hinder the seamless adoption of grid modernization solutions in Europe. Energy policies and grid regulations vary across countries, making it difficult to establish a uniform framework for modernization efforts. Compliance with evolving cybersecurity standards, data protection laws, and energy efficiency mandates adds to the regulatory burden on utilities. Moreover, integrating decentralized energy sources, such as rooftop solar, wind farms, and energy storage systems, into existing grid networks requires sophisticated grid management solutions. The transition from traditional centralized power generation to a decentralized energy model demands significant advancements in grid flexibility and interoperability. Ensuring seamless communication between digital systems, utilities, and consumers presents additional technical challenges, requiring continuous innovation and collaboration among stakeholders.
Market Opportunities
Expansion of Renewable Energy Integration and Energy Storage Solutions
The growing focus on renewable energy adoption presents significant opportunities for grid modernization in Europe. With ambitious carbon neutrality goals, governments and utilities are accelerating the integration of wind, solar, and other renewable energy sources into the power grid. This transition drives demand for advanced grid management solutions, including AI-driven analytics, smart inverters, and real-time monitoring systems. Additionally, the expansion of energy storage solutions, such as lithium-ion batteries, pumped hydro storage, and emerging hydrogen-based technologies, offers new avenues for enhancing grid stability. Investments in large-scale energy storage infrastructure will enable better load balancing, reduce grid congestion, and support decentralized energy generation, creating long-term opportunities for modernization efforts.
Advancements in Smart Grid Technologies and Digitalization
The increasing adoption of smart grid technologies and digitalization presents lucrative opportunities for stakeholders in the Europe Grid Modernization market. Utilities are investing in IoT-enabled smart meters, AI-powered demand response systems, and blockchain-based energy trading platforms to optimize grid operations. The shift toward digital substations and automated grid control enhances efficiency, minimizes energy losses, and improves predictive maintenance capabilities. Additionally, the adoption of microgrids and virtual power plants (VPPs) is transforming energy distribution models, offering resilient and flexible solutions for power management. As policymakers and regulatory bodies emphasize energy efficiency, sustainability, and grid resilience, the demand for digital transformation solutions in the electricity sector is expected to grow, driving further opportunities in the market.
Market Segmentation Analysis:
By Component:
The Europe Grid Modernization market is segmented into hardware, software, and services, each playing a critical role in transforming power infrastructure. The hardware segment holds a significant share, driven by the increasing deployment of smart meters, sensors, advanced transmission lines, and digital substations. These components enhance grid reliability, enable real-time energy monitoring, and support seamless integration of renewable energy sources. The software segment is witnessing rapid growth due to the rising adoption of AI-driven grid management, predictive analytics, and demand response solutions. Utilities and grid operators are leveraging software-based automation to optimize energy distribution and reduce operational costs. The services segment, including consulting, maintenance, and grid modernization planning, is gaining traction as governments and private entities seek expert guidance to implement smart grid solutions efficiently. As the market evolves, the synergy between hardware, software, and service solutions is expected to accelerate grid digitalization, enhance energy efficiency, and strengthen Europe’s transition toward a more resilient and sustainable power infrastructure.
By Application:
The Europe Grid Modernization market is further segmented based on application into residential, commercial, and industrial sectors. The residential segment is expanding rapidly due to the increasing adoption of smart meters, home energy management systems, and decentralized renewable energy solutions, such as rooftop solar panels. Consumers are increasingly investing in energy-efficient solutions to reduce electricity costs and enhance energy independence. The commercial segment is driven by the need for smart grid solutions in office buildings, retail spaces, and public infrastructure to optimize energy consumption and improve demand response capabilities. Businesses are integrating advanced grid technologies to meet sustainability goals and reduce operational expenses. The industrial segment dominates the market, fueled by the high energy demand of manufacturing facilities, data centers, and large-scale production plants. Industries are adopting smart grid solutions to enhance power reliability, minimize downtime, and integrate renewable energy sources efficiently. As energy efficiency and sustainability become priorities, grid modernization across all applications will continue to accelerate in Europe.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Application:
- Residential
- Commercial
- Industrial
Based on End-User:
- Utilities
- Independent Power Producers (IPPs)
- Government and Municipalities
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
United Kingdom and Germany
The United Kingdom and Germany hold a significant share in the Europe Grid Modernization market, collectively accounting for approximately 40% of the total market. The UK is at the forefront of smart grid adoption, driven by strong government policies, increasing renewable energy integration, and investments in advanced grid infrastructure. Initiatives such as the Smart Systems and Flexibility Plan and regulatory support for demand response programs are accelerating modernization efforts. Additionally, the UK's commitment to achieving net-zero emissions by 2050 has led to large-scale deployment of energy storage systems, AI-driven grid management, and digital substations. Germany, a leader in renewable energy adoption, is heavily investing in grid upgrades to accommodate its ambitious Energiewende (energy transition) strategy. With wind and solar power playing a dominant role in the country’s energy mix, smart grid technologies, including predictive analytics and automation, are essential for grid stability. The ongoing expansion of high-voltage direct current (HVDC) transmission systems and digital grid solutions further strengthens Germany’s position in the market.
France
France is emerging as a key player in the Europe Grid Modernization market, accounting for around 15% of the regional share. The country is actively modernizing its power grid to support the increasing penetration of renewable energy, particularly wind and solar. The rollout of Enedis' Linky smart meter program has been instrumental in enhancing energy monitoring, improving demand response mechanisms, and reducing grid losses. France is also investing in advanced distribution automation, artificial intelligence for grid optimization, and enhanced cybersecurity measures to protect its energy infrastructure. Additionally, the French government's emphasis on nuclear power modernization, alongside the integration of decentralized energy systems, is driving the need for smart grid solutions. The rise of electric vehicle (EV) adoption is further influencing grid investments, as utilities expand charging infrastructure and implement vehicle-to-grid (V2G) solutions. These initiatives collectively contribute to France’s rapid grid transformation, ensuring greater reliability, efficiency, and sustainability in its power sector.
Spain and Italy
Spain and Italy collectively account for about 12% of the Europe Grid Modernization market, driven by their strong renewable energy commitments. Spain has significantly increased its investments in smart grid solutions to support its rapidly expanding wind and solar power capacity. Utilities are adopting digital substations, AI-powered energy forecasting, and grid automation to enhance efficiency and reliability. The Spanish government is also promoting energy storage deployment and microgrid development to ensure grid stability amid fluctuating renewable generation. Similarly, Italy is investing in advanced grid management systems to accommodate its growing solar energy sector. The country’s initiatives, such as the National Integrated Energy and Climate Plan, are driving smart grid deployment, demand-side response programs, and smart meter penetration. The adoption of blockchain technology for energy trading and decentralized grid management is further shaping the modernization landscape in both Spain and Italy. As these nations continue to advance their renewable energy goals, the demand for innovative grid solutions will continue to grow.
Northern and Eastern Europe
Countries such as Sweden, Denmark, Poland, and Austria are witnessing steady growth in grid modernization, collectively contributing around 10% of the regional market. Sweden and Denmark are leading in smart grid innovations, with high smart meter penetration rates and substantial investments in digital grid infrastructure. Both nations are focusing on offshore wind energy integration and automation technologies to improve grid resilience. Poland, a growing market for renewable energy, is modernizing its grid to accommodate increased wind and solar capacity while reducing coal dependency. The country is expanding energy storage systems and grid digitalization to improve reliability. Austria is adopting smart grid solutions to optimize energy distribution and manage the complexities of decentralized power generation. Additionally, Switzerland, Belgium, and the Netherlands are making significant strides in enhancing grid cybersecurity, energy trading platforms, and grid interconnectivity. As energy transition policies strengthen across these nations, grid modernization efforts will accelerate, ensuring a more resilient and efficient electricity network.
Key Player Analysis
- ABB Ltd.
- Siemens AG
- Schneider Electric SE
- Hitachi Energy
- General Electric Europe
- Alstom SA
- Toshiba Europe
- Landis+Gyr AG
- Siemens Gamesa
- Eaton Europe
Competitive Analysis
The Europe Grid Modernization market is highly competitive, with several global players leading the way in the development and deployment of advanced grid technologies. ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric Europe, Alstom SA, Toshiba Europe, Landis+Gyr AG, Siemens Gamesa, and Eaton Europe are among the key players driving innovation in the industry. These companies are focusing on smart grid solutions, automation, energy storage, and digital substations to meet the growing demand for efficient and resilient energy infrastructure. For instance, Siemens has acquired Trayer Engineering Corporation to broaden its grid modernization product portfolio, focusing on technologies that enhance grid resilience in the US. Leading players are focusing on providing smart grid solutions, including advanced automation, digital substations, and energy storage systems, to meet the rising demand for efficient energy infrastructure. These companies are also leveraging AI, machine learning, and real-time data analytics to optimize grid operations, reduce energy loss, and improve grid reliability. A key strategy for many companies is the integration of renewable energy sources, with a focus on ensuring that power grids can accommodate fluctuating energy inputs from wind and solar power. Additionally, there is a strong emphasis on cybersecurity solutions to protect grids from cyber threats, as more systems become digitalized. Automation and remote control of grid operations are becoming increasingly important, with digital solutions enabling better monitoring, predictive maintenance, and operational efficiency.
Collaborations, partnerships, and acquisitions are also common, as companies seek to expand their technological capabilities and broaden their market reach. The ongoing efforts to create more resilient, flexible, and sustainable grids are fueling continuous innovation and driving competition in the market. As the demand for modernization grows, competition in the European market will continue to intensify, with a focus on scalability, efficiency, and renewable integration.
Recent Developments
- In October 2024, Hitachi Energy introduced Grid-enSure in India to advance the country's transition to sustainable energy. The company also announced plans to invest around INR 2,000 crore over the next four to five years in capacity expansion and upgrades for various transformer factories.
- In August 2024, Hitachi Energy called for urgent action to expand global power grids, reduce connection bottlenecks, and accelerate the energy transition. They launched Grid-enSure™ at the CIGRE 2024 Paris Session, a portfolio of solutions to enhance grid flexibility, resilience, and stability.
- In May 2024, Siemens revealed the Gridscale X software, a "co-pilot" for flexible low voltage grid management, aiming to reduce outages by up to 30%.
Market Concentration & Characteristics
The Europe Grid Modernization market exhibits moderate to high concentration, with a few dominant players leading the development and deployment of advanced grid solutions. These companies possess strong technological capabilities and extensive portfolios that include smart grid infrastructure, energy storage systems, digital substations, and grid automation solutions. The market is characterized by a blend of established multinational corporations and specialized firms focusing on niche segments, such as renewable energy integration, grid cybersecurity, and AI-driven analytics. The competitive landscape is dynamic, with leading companies actively innovating and seeking strategic collaborations, mergers, and acquisitions to expand their market reach and technological capabilities. The market is also marked by increasing investments from both public and private sectors, driven by governmental policies, sustainability goals, and the growing demand for energy efficiency and renewable integration. Additionally, regional variations play a significant role in shaping the market, as each European country has its unique regulatory framework, energy demands, and infrastructure challenges, influencing grid modernization efforts. As digital transformation accelerates, there is a shift toward more decentralized energy systems, such as microgrids and virtual power plants (VPPs), further diversifying the market’s characteristics. The integration of AI, machine learning, and real-time data analytics is enhancing grid reliability and flexibility, offering significant growth opportunities in the market. The increasing push for renewable energy adoption and grid resilience is driving long-term changes in market concentration and dynamics.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Europe’s grid modernization market is expected to continue growing rapidly, driven by the increasing demand for renewable energy integration.
- Investment in smart grid technologies, including advanced metering infrastructure and digital substations, will see significant expansion.
- The adoption of AI, machine learning, and real-time data analytics will improve grid management and operational efficiency.
- Decentralized energy systems such as microgrids and virtual power plants will become more prevalent to support local energy generation and consumption.
- The focus on energy storage systems will grow as grids need to accommodate intermittent renewable energy sources like solar and wind.
- Cybersecurity will remain a top priority as grids become more digitalized and vulnerable to potential cyber threats.
- Integration of electric vehicles and charging infrastructure into the grid will increase, necessitating advancements in grid flexibility.
- Increased government support and regulatory frameworks will drive further investments in grid modernization.
- The shift towards achieving carbon-neutral and net-zero energy goals will propel the demand for more resilient and sustainable grids.
- Collaboration among industry players, utilities, and government bodies will be crucial for the successful implementation of grid modernization projects across Europe.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Investments in Smart Grid Infrastructure
European governments and utilities are allocating substantial funds to upgrade aging power grids with advanced technologies, supported by EU initiatives like the Green Deal and Energy Efficiency Directive, which accelerate smart grid deployment and modernization.
Integration of Renewable Energy Sources
The rapid adoption of wind and solar power across Europe requires advanced grid management and storage solutions to handle intermittent supply, driving demand for modernized, flexible, and intelligent grid systems.
Technological Advancements in Grid Modernization
The deployment of IoT-enabled smart meters, AI-driven analytics, and digital substations is transforming grid operations, enabling real-time monitoring, predictive maintenance, and improved energy efficiency.
Increasing Demand for Grid Reliability and Resilience
Climate change-induced weather events and rising cyber threats are pushing utilities to invest in resilient, self-healing grids and robust cybersecurity measures to ensure uninterrupted and secure power supply.
Supportive Government Policies and Decarbonization Goals
Ambitious carbon neutrality targets and regulatory frameworks across Europe are incentivizing utilities to modernize grids, integrate distributed energy resources, and support the electrification of transportation and other sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Grid Modernization market?
What factors are driving the growth of the Europe Grid Modernization market?
What are the key segments within the Europe Grid Modernization market?
What are some challenges faced by the Europe Grid Modernization market?
Who are the major players in the Europe Grid Modernization market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Utilities
- 1.2.2 Independent Power Producers (IPPs)
- 1.2.3 Government and Municipalities
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,227.24 million → 2032: USD 39,393.23 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Grid Modernization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Grid Modernization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Grid Modernization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Grid Modernization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Grid Modernization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Grid Modernization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Grid Modernization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Grid Modernization Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,227.24 million → 2032: USD 39,393.23 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Grid Modernization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Utilities
- 12.3.7.2 Independent Power Producers (IPPs)
- 12.3.7.3 Government and Municipalities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Grid Modernization End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Grid Modernization Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Grid Modernization Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Grid Modernization Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Schneider Electric SE
- 18.5 Hitachi Energy
- 18.6 General Electric Europe
- 18.7 Alstom SA
- 18.8 Toshiba Europe
- 18.9 Landis+Gyr AG
- 18.10 Siemens Gamesa
- 18.11 Eaton Europe
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

