
Market Overview:
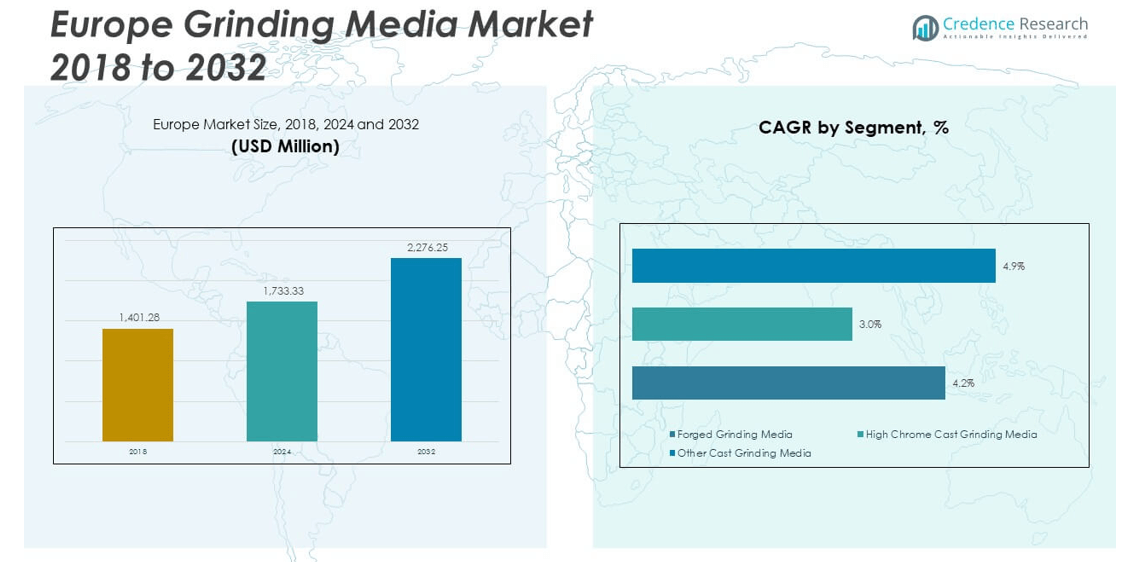
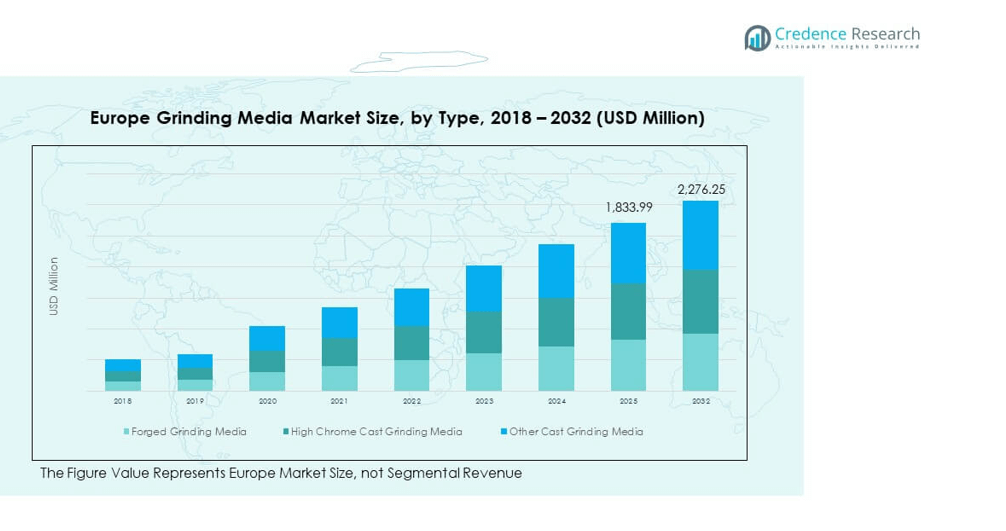
The Europe Grinding Media Market size was valued at USD 1,401.28 million in 2018 to USD 1,733.33 million in 2024 and is anticipated to reach USD 2,276.25 million by 2032, at a CAGR of 3.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Grinding Media Market Size 2024 | USD 1,733.33 million |
| Europe Grinding Media Market, CAGR | 3.13% |
| Europe Grinding Media Market Size 2032 | USD 2,276.25 million |
The Europe Grinding Media Market is driven by the rising demand from mining, cement, and power generation industries. Increasing infrastructure projects across Europe have boosted cement production, while mineral processing activities continue to expand. Technological advancements in grinding efficiency and wear-resistant materials are enhancing product adoption. Growing focus on operational efficiency and energy savings further supports the market. Strong demand for steel balls and ceramic media also contributes to its growth trajectory.
Regional growth is concentrated in Western Europe, where Germany, France, and the UK dominate due to large-scale mining and cement industries. Central and Eastern Europe are emerging as significant growth areas supported by industrial expansion and construction investments. The presence of established manufacturers strengthens Western Europe, while rising foreign investments in developing economies drive Eastern Europe. Southern Europe also shows potential, with demand linked to construction recovery. Together, these trends reflect diverse opportunities across the region.
Market Insights:
- The Europe Grinding Media Market size was valued at USD 1,401.28 million in 2018, reached USD 1,733.33 million in 2024, and is projected to reach USD 2,276.25 million by 2032, growing at a CAGR of 3.13%.
- Western Europe held the largest share at 41% in 2024, supported by advanced mining and cement industries. Germany, France, and the UK drive this dominance through industrial infrastructure and strong demand for forged grinding media.
- Central Europe accounted for 27% of the market in 2024, driven by industrial expansion and metallurgy projects, while Eastern Europe followed with 19%, supported by rising construction activities.
- Southern Europe emerged as the fastest-growing region with a 13% share in 2024, led by recovery in construction, cement demand, and increased foreign investments in infrastructure.
- By type, forged grinding media held around 57% share in 2024 due to its strength and durability, while high chrome cast grinding media accounted for 28%, with the remaining 15% covered by other cast grinding media.
Market Drivers:
Rising Demand from Mining and Cement Industries Strengthening the Growth of the Europe Grinding Media Market:
The Europe Grinding Media Market is strongly driven by the expansion of mining and cement industries. Increasing exploration and extraction activities create higher consumption of grinding media for ore processing. Cement manufacturing remains a key contributor due to the construction sector’s reliance on large-scale cement production. Demand growth is also supported by rapid infrastructure modernization in Western Europe. Manufacturers focus on higher efficiency products to reduce operational downtime in processing units. Advanced wear-resistant alloys and ceramics enhance durability, lowering replacement costs for operators. Regulatory support for energy-efficient processes promotes the adoption of advanced grinding media. The market is projected to strengthen further with continued industrial expansion across emerging European economies.
- For instance, Magotteaux, a global leader in grinding media, has more than 700,000 tons of annual grinding media production capacity. Their products serve mining, cement, power, and quarry sectors worldwide.
Technological Advancements in Manufacturing Processes Driving Higher Efficiency and Product Adoption:
Innovations in grinding ball casting and forging techniques significantly improve product performance. Manufacturers focus on producing uniform, high-density media to ensure consistent grinding output. Use of automated quality-control systems reduces defects and ensures longer product life. These advancements align with industry priorities of reducing energy usage and minimizing waste. Growth in research and development budgets by key producers supports material innovations. Ceramic-based grinding media gains popularity due to superior efficiency in specialized applications. It becomes critical for end users seeking higher output with lower resource consumption. Adoption of such improved materials strengthens customer confidence in long-term operational savings.
- For instance, Magotteaux emphasizes automated quality control and patented alloy developments focused on wear resistance, reducing replacement frequency and operational downtime.
Expansion of Energy Sector and Power Generation Boosting Market Growth Potential:
Power generation facilities, particularly coal and thermal plants, rely on grinding media for pulverizing operations. The steady growth in Europe’s energy demand increases consumption of grinding balls. Government-backed initiatives for energy diversification contribute to new power projects requiring grinding systems. Focus on replacing outdated energy plants with efficient technologies supports fresh demand. Grinding media becomes vital in reducing operational bottlenecks in coal-based energy facilities. Increased adoption of renewable energy does not fully reduce demand, as traditional plants continue operations. Emerging Eastern European countries invest in new energy infrastructure, creating additional demand. It continues to provide stable growth prospects for grinding media suppliers.
Rising Industrialization in Central and Eastern Europe Strengthening Long-Term Market Demand:
Central and Eastern European nations experience rapid industrial development, stimulating demand for grinding media. New factories and processing plants require grinding solutions for various raw materials. Rising foreign direct investment supports heavy industries including mining and metallurgy. Governments in these regions encourage infrastructure growth, driving construction-related cement consumption. Industrialization enhances the demand for robust grinding solutions capable of high-volume processing. Local production capacities expand to reduce reliance on imports, fostering regional competitiveness. It creates opportunities for grinding media suppliers to establish strong footholds. Rising demand from smaller, emerging economies in Europe supports long-term market stability.
Market Trends:
Adoption of Sustainable Materials in Grinding Media Manufacturing Supporting Environmental Compliance:
The Europe Grinding Media Market witnesses a growing trend toward sustainable production practices. Rising concerns over carbon emissions encourage manufacturers to use recycled steel and eco-friendly alloys. Adoption of advanced smelting techniques ensures reduced energy usage in production processes. Environmental certifications become critical for suppliers targeting large industrial buyers. Governments impose stricter environmental norms, compelling industries to use sustainable solutions. Companies market eco-friendly grinding media as a value-added advantage to attract global buyers. Demand for lower environmental footprint drives collaboration between steel producers and grinding media firms. It creates a competitive edge for companies investing in greener technologies.
- For instance, Strategic equity partnership with Grinding Media South Africa underscores technical and financial capacity enhancements aligned with sustainable practices.
Increasing Customization and Application-Specific Product Designs Driving Market Differentiation:
Industries across Europe demand grinding media tailored to unique operational needs. Customization includes optimizing size, hardness, and material composition for specific processes. Manufacturers introduce product lines catering to diverse requirements in mining, cement, and chemical industries. Tailored solutions improve grinding efficiency and extend operational lifespan of equipment. Higher emphasis on application-specific solutions fosters long-term supplier-customer relationships. Companies use data-driven insights to design grinding media with predictive wear performance. Demand for such specialized solutions grows in industries seeking reduced maintenance costs. It reinforces the market’s shift toward personalized and adaptive product strategies.
- For instance, Imerys offers customized mineral-based solutions and abrasive products for the mining and chemical industries. Drawing on the former expertise of S&B Industrial Minerals (acquired in 2015), Imerys works with customers to optimize factors like particle size and hardness for enhanced process efficiency.
Integration of Digital Monitoring Systems in Grinding Operations Enhancing Process Efficiency:
Automation trends extend into grinding operations, where digital monitoring systems are adopted. Sensors embedded in grinding equipment provide real-time data on wear and usage. Predictive maintenance becomes possible, reducing costly downtime for industrial facilities. The integration of digital systems aligns with Industry 4.0 transformation in Europe. Operators adopt smart solutions to track efficiency and optimize energy use. This trend creates higher demand for grinding media compatible with automated monitoring. Companies offering integrated solutions gain stronger competitiveness in the market. It highlights the importance of innovation beyond materials toward complete process optimization.
Growth in Export Potential for European Grinding Media Producers Strengthening Global Reach:
European manufacturers expand exports to regions with high mining and cement demand. Africa and the Middle East emerge as key destinations due to construction and resource projects. Strong reputation of European products for quality and durability enhances global competitiveness. Trade agreements and reduced tariffs further encourage cross-border market expansion. Companies invest in distribution networks to supply grinding media efficiently to global clients. Export-oriented strategies strengthen profitability despite fluctuating domestic demand. It positions European producers as leading suppliers in international markets. The trend highlights Europe’s role as a hub for advanced grinding media exports.
Market Challenges Analysis:
Rising Raw Material Costs and Price Volatility Creating Supply-Side Pressure on the Europe Grinding Media Market:
The Europe Grinding Media Market faces significant challenges due to fluctuating raw material costs. Steel prices directly affect the overall production expenses for manufacturers. Volatile global commodity prices disrupt planning and create cost uncertainties. Suppliers struggle to maintain profitability while ensuring competitive pricing. Companies face increasing difficulty in securing stable contracts for steel and alloys. Such volatility often translates into higher product prices for end users. Manufacturers attempt to counter these effects by adopting long-term supply agreements. However, persistent fluctuations remain a key barrier to market stability.
Strong Competitive Pressures and Increasing Substitution Threats Reducing Market Margins:
The competitive landscape of grinding media suppliers across Europe intensifies rapidly. Numerous regional and international players compete aggressively on price and innovation. Smaller producers face challenges in maintaining technology investments due to limited budgets. Substitution by advanced ceramic and composite media reduces demand for traditional steel balls. Clients increasingly seek low-cost imports, impacting European producers’ market share. Companies must innovate consistently to maintain relevance in this environment. Market concentration remains moderate, but pricing pressure limits profit expansion. It continues to challenge long-term sustainability for smaller or mid-sized manufacturers.
Market Opportunities:
Expansion of Smart Manufacturing Capabilities Creating Opportunities for Technologically Advanced Grinding Media:
The Europe Grinding Media Market benefits from the rise of smart manufacturing in industrial sectors. Digital technologies open pathways for integrating advanced grinding media with automated systems. Companies can differentiate products through compatibility with predictive maintenance tools. Smart factories adopt innovative materials to align with energy-efficient production goals. Suppliers focusing on high-tech grinding media gain preference in forward-looking industries. Increased automation in European plants creates consistent demand for technologically advanced solutions. This shift creates long-term opportunities for players investing in innovation. It supports stronger alignment with Europe’s broader industrial transformation.
Rising Demand for Renewable Energy Infrastructure Creating Fresh Market Opportunities Across Europe:
Europe’s shift toward renewable energy infrastructure creates indirect demand for grinding media. Construction of wind, solar, and related facilities stimulates cement and material processing. Grinding media supports these industries by enabling efficient raw material preparation. Governments push for large-scale renewable adoption, increasing construction material requirements. Companies supplying grinding media benefit from the associated demand surge. Suppliers aligning with renewable projects enhance their brand positioning in sustainable sectors. It creates significant opportunities in markets previously less dependent on grinding media. The trend ensures long-term stability through alignment with Europe’s clean energy transition.
Market Segmentation Analysis:
By Type
The Europe Grinding Media Market is categorized into forged grinding media, high chrome cast grinding media, and other cast grinding media. Forged grinding media dominates due to its superior strength and durability, making it highly suitable for mining and cement operations. High chrome cast grinding media is valued for its wear resistance and effectiveness in fine grinding applications, especially in industries seeking high efficiency. Other cast grinding media caters to smaller-scale or cost-sensitive industries where moderate durability is sufficient. It demonstrates demand diversity shaped by application intensity.
- For instance, High chrome cast grinding media, valued for wear resistance and fine grinding effectiveness, hold of the European market share, supporting high efficiency in demanding industrial processes. Other cast grinding media serve smaller-scale, cost-sensitive industries, illustrating a demand spectrum reflecting application intensity.
By Application
Segmentation by application includes power plants, cement, mining and metallurgy, and others. Mining and metallurgy lead the segment, driven by the need for efficient mineral processing across Europe. Cement remains a strong contributor, supported by infrastructure expansion and construction projects. Power plants, particularly coal-based, show consistent demand for grinding solutions to ensure reliable pulverization processes. Other applications such as chemicals and industrial processing provide incremental contributions. It underscores the critical role of grinding media across Europe’s core heavy industries.
- For instance, mining and metallurgy remain the leading segment, followed by cement-with power plants and other industrial applications providing steady incremental demand. This underscores grinding media’s critical role in Europe's core heavy industries and continuous industrial modernization.
By Sales Channel
The market is segmented into direct channel and distribution channel. Direct sales dominate, with large-scale buyers favoring direct sourcing to secure customized solutions and stable supply agreements. Distribution channels maintain relevance for smaller enterprises and regional industries that require flexibility and ease of access. It provides a balanced structure where both channels serve distinct market needs. This segmentation allows suppliers to maximize coverage while addressing the unique requirements of diverse customer groups across Europe.
Segmentation:
By Type
- Forged Grinding Media
- High Chrome Cast Grinding Media
- Other Cast Grinding Media
By Application
- Power Plant
- Cement
- Mining and Metallurgy
- Others
By Sales Channel
- Direct Channel
- Distribution Channel
By Region
- Europe (Aggregate)
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Regional Analysis:
Western Europe
Western Europe held the dominant position in the Europe Grinding Media Market with a 41% share in 2024. Countries such as Germany, France, and the UK drive this leadership through strong cement, mining, and metallurgy industries. The region benefits from well-established industrial infrastructure and high demand for forged grinding media. Energy-intensive sectors rely on durable and efficient products, strengthening market stability. Investments in construction and modernization projects further enhance consumption levels. It continues to serve as the primary hub for both production and demand in the region.
Central and Eastern Europe
Central Europe accounted for 27% of the Europe Grinding Media Market in 2024, supported by growing industrial bases and rising metallurgy applications. The Czech Republic, Poland, and Hungary show strong demand from both cement and mining sectors. Industrial expansion and foreign investments into these markets support future growth. Eastern Europe followed with a 19% share, driven by Russia and surrounding nations focusing on construction and mining projects. The demand pattern reflects increasing infrastructure development across emerging economies. It provides steady opportunities for both regional producers and international suppliers.
Southern Europe
Southern Europe represented 13% of the Europe Grinding Media Market in 2024, making it the smallest but fastest-growing sub-region. Countries such as Italy and Spain lead consumption, supported by recovery in construction and cement demand. Rising infrastructure development and government-backed projects strengthen the growth outlook. The region also benefits from imports due to limited local production capacity. Manufacturers target Southern Europe as a high-potential market for premium grinding media products. It reflects a dynamic growth pattern with strong potential for expansion in the coming years.
Key Player Analysis:
- Magotteaux Group
- Energosteel
- ABS Sfere
- EL Stomana
- Litzkuhn & Niederwipper GmbH
- SUPRASTEEL
- Fritsch GmbH
- HOSOKAWA ALPINE Aktiengesellschaft
- Maschinenfabrik Gustav Eirich GmbH & Co KG
- Ziegler Mineralstoffe (Alubit Grinding Media)
- Alpha Grinding Media
- Metinvest
- Others
Competitive Analysis:
The Europe Grinding Media Market is characterized by strong competition among regional and global players. Companies compete on product quality, cost efficiency, and technological innovation to strengthen their positions. Leading firms focus on durable forged and high chrome cast media to address diverse industrial applications. Strategic emphasis lies in partnerships with mining, cement, and power generation industries to secure long-term contracts. Innovation in wear-resistant materials and energy-efficient designs drives competitive differentiation. Smaller players operate regionally with flexible offerings but face pricing pressures from established suppliers. It reflects a moderately consolidated market with continuous innovation shaping rivalry intensity.
Recent Developments:
- In January 2025, Magotteaux expanded its production plant in Brazil, increasing capacity by 40,000 tons to a total of 110,000 tons per year of High Chromium grinding media, with a focus on sustainability and reducing CO2 emissions.
- In Energosteel, recent upgrades include the introduction of new automated equipment in its laboratory as of March 2025, enhancing quality and testing capabilities.
- Hosokawa Alpine Aktiengesellschaft is set to participate in POWTECH 2025 in September, showcasing its processing technologies, though no new product launch or acquisition was reported as of 2025.
- Steel Dynamics is acquiring the remaining 55% of New Process Steel in a deal announced in August 2025, expanding its value-added manufacturing exposure, which may impact grinding media supply chains indirectly.
Report Coverage:
The research report offers an in-depth analysis based on type, application, and sales channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for durable grinding media in cement and mining sectors will fuel adoption.
- Rising industrialization in Central and Eastern Europe will open new opportunities for suppliers.
- Sustainability initiatives will push producers toward eco-friendly materials and recycling practices.
- Technological innovation in wear-resistant alloys will enhance performance and efficiency.
- Expansion of power generation projects will sustain steady grinding media demand.
- Export potential to emerging global markets will strengthen Europe’s role as a supplier hub.
- Integration of smart monitoring systems will align grinding media with Industry 4.0 trends.
- Customization for application-specific needs will drive stronger supplier-customer relationships.
- Competitive pressure will intensify with increased presence of low-cost imports.
- Long-term growth will be shaped by infrastructure investments and energy transition projects.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Grinding Media Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Grinding Media Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Europe Grinding Media Market?
Who are the leading companies in the Europe Grinding Media Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Grinding Media Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Europe Grinding Media Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 1,401.28 million → 2032: USD 2,276.25 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Grinding Media Segmentation Snapshot
- 2.2.1 Market Split by Country – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Grinding Media Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Grinding Media Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Europe Grinding Media Drivers
- 3.3 Europe Grinding Media Restraints & Challenges
- 3.4 Europe Grinding Media Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Grinding Media Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Grinding Media Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Grinding Media category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Grinding Media Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Europe Grinding Media Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2018)
- 5.1.2 Regional Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2018)
- 5.1.4 Regional Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Europe Grinding Media. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Grinding Media Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Grinding Media Share Analysis – 2018
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Europe Grinding Media Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Grinding Media (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Europe Grinding Media
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Europe Grinding Media – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2032
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Europe Grinding Media – Priority Country 1
Chapter 10. Europe Grinding Media – Priority Country 2
Chapter 11. Europe Grinding Media – Priority Country 3
Chapter 12. Europe Grinding Media – Priority Country 4
Chapter 13. Europe Grinding Media Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
