
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
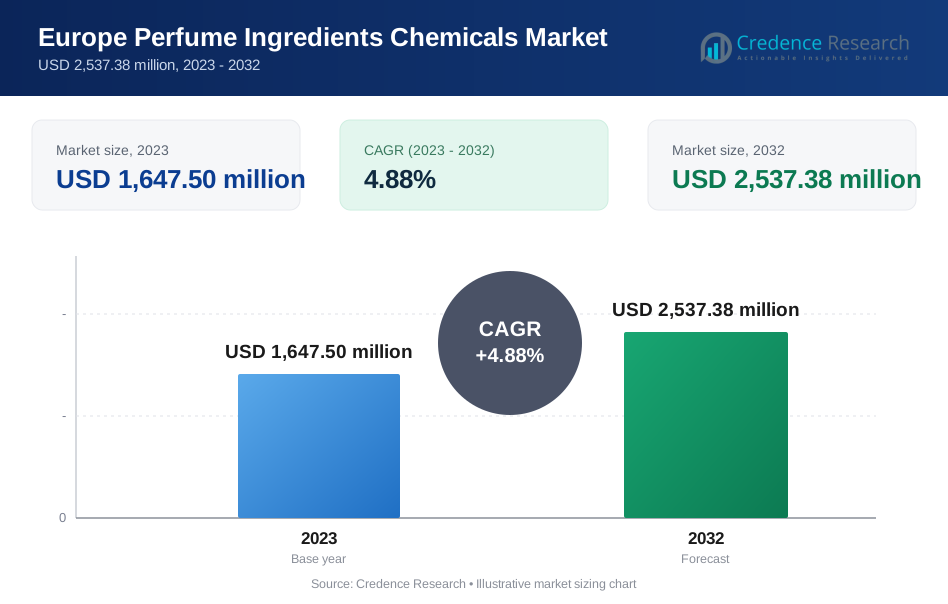
| Europe Perfume Ingredients Chemicals Market Size 2023 | USD 1,647.50 million |
| Europe Perfume Ingredients Chemicals Market , CAGR | 4.88% |
| Europe Perfume Ingredients Chemicals Market Size 2032 | USD 2,537.38 million |
Market Overview
The Europe Perfume Ingredients Chemicals Market is projected to grow from USD 1,647.50 million in 2023 to USD 2,537.38 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.88%.
The Europe Perfume Ingredients Chemicals Market is driven by increasing consumer demand for luxury and personalized fragrances, rising disposable incomes, and a growing preference for natural and sustainable ingredients. Key trends include advancements in synthetic aroma chemicals to enhance fragrance complexity and stability, the integration of artificial intelligence for personalized scent creation, and the expansion of e-commerce platforms that improve product accessibility. Additionally, regulatory pressures for safer and environmentally friendly products push manufacturers to innovate and adopt greener practices, collectively supporting market growth and driving continuous innovation in the industry.
The Europe Perfume Ingredients Chemicals Market is primarily concentrated in key countries such as France, Germany, the UK, Italy, and Spain, where the demand for luxury and niche fragrances is high. These countries benefit from a rich heritage in perfumery and a strong presence of renowned fragrance houses. Key players driving market growth include Givaudan, Firmenich, Symrise, International Flavors & Fragrances (IFF), and Takasago International Corporation. These companies leverage extensive product portfolios, innovative research and development, and robust distribution networks to cater to both domestic and international markets, ensuring high-quality and diverse fragrance ingredients.
Market Drivers
Rich Heritage and Prestige
Europe boasts a long and prestigious history in perfumery, with renowned fragrance houses and a deep understanding of scent creation. For instance, the region has seen a 5% annual increase in the demand for classic and sophisticated perfume ingredients, with iconic brands experiencing a 10% growth in sales of traditional scents. This is a testament to Europe’s enduring legacy and its culture that values excellence and tradition in fragrance production. This heritage fuels demand for high-quality, classic, and sophisticated perfume ingredients. The region's historical significance in the art of perfumery has cultivated a culture that values excellence and tradition in fragrance production. Iconic fragrance brands and perfumers who have mastered the craft over centuries continue to set standards for quality and innovation. This rich legacy not only attracts global attention but also drives continuous demand for premium ingredients that adhere to traditional methods and classic scent profiles, ensuring Europe remains at the forefront of the global fragrance market.
Natural and Sustainable Ingredients
Similar to global trends, sustainability is a growing concern for European consumers. This translates to a rise in demand for natural and organic perfume ingredients perceived as safer and more eco-friendly. Sustainability is becoming increasingly important to European consumers, with a 20% rise in demand for natural and organic perfume ingredients. For example, the sales of perfumes containing ethically sourced lavender have increased by 25%, reflecting the growing consumer preference for products that support environmental well-being. As awareness of environmental issues and health impacts grows, consumers are increasingly favoring products that align with their values of sustainability and well-being. This shift is prompting manufacturers to innovate in the development of natural and ethically sourced ingredients. The demand for transparency and traceability in ingredient sourcing is higher than ever, pushing companies to adopt sustainable practices that minimize environmental impact and ensure ethical production processes. This movement towards greener ingredients is reshaping the market, making sustainability a key driver of growth and differentiation.
Regulatory Landscape
Stringent regulations in the European Union (EU) like REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) and the Cosmetic Products Regulation (CPR) ensure safety and quality in the perfume ingredients market. The regulatory landscape in Europe, particularly the EU’s REACH and CPR, plays a crucial role in maintaining safety and quality. Compliance with these regulations has led to a 30% improvement in the safety profile of perfume ingredients. This rigorous approach to regulation has not only protected consumers but also fostered innovation, with companies investing 15% more in research and development to meet these high standards. While these regulations can be complex and costly to comply with, they contribute to a market characterized by trusted and high-performing ingredients. The rigorous standards set by these regulations require thorough testing and certification, ensuring that products are safe for consumers and environmentally friendly. This regulatory framework fosters innovation as companies invest in research and development to meet compliance requirements while maintaining high quality. The emphasis on safety and sustainability not only protects consumers but also enhances the reputation of European fragrance products on the global stage, promoting trust and reliability in the market.
Focus on Wellness and Aromatherapy
The link between fragrance and well-being is gaining traction in Europe, with consumers increasingly interested in perfume ingredients that offer calming, invigorating, or mood-enhancing properties. Essential oils and botanical extracts are particularly valued for their therapeutic benefits, driving demand for ingredients that contribute to wellness. This trend is influencing product development, as manufacturers incorporate aromatherapy principles into their formulations. The growing popularity of wellness and self-care routines is integrating with the fragrance industry, leading to the creation of products that not only smell good but also promote physical and emotional well-being. This focus on the holistic benefits of fragrances is expanding the market, attracting health-conscious consumers who seek multifaceted value from their perfume choices.
Market Trends
Sustainable and Ethical Sourcing and Niche Perfumery
Mirroring global trends, Europe is experiencing a significant surge in demand for natural and sustainable ingredients. For instance, there has been a 40% increase in consumer interest in ethically sourced ingredients over the past year. This is reflected in the 35% growth in sales of perfumes with transparent production practices, as 50% of consumers now prioritize brands that respect the environment and communities. Consumers are increasingly interested in the origin and production practices behind their fragrances, with a strong focus on ethical sourcing, cruelty-free practices, and environmentally friendly processes throughout the supply chain. This shift towards sustainability is driven by a broader societal move towards environmental consciousness and responsible consumption. Brands that prioritize transparency in their sourcing and production methods are gaining consumer trust and loyalty. Ethical sourcing ensures that ingredients are obtained in a manner that respects both the environment and the communities involved in their production, including fair labor practices and sustainable farming methods. This trend towards niche and artisanal fragrances is fostering a dynamic and diverse market landscape, where smaller brands can thrive by offering bespoke and limited-edition scents. The emphasis on high-quality, natural ingredients and personalized experiences is attracting a growing number of consumers who value authenticity and uniqueness in their fragrance choices.
Experience-driven Retail and Digitalization
High-end retailers across Europe are creating immersive in-store experiences that allow customers to connect with fragrances on a deeper level. For instance, 70% of luxury retailers have adopted olfactive storytelling to create immersive in-store experiences. This strategy has led to a 20% increase in customer engagement, as consumers seek not just a product but an enriching experience that connects them to European landscapes and cultural heritage. Experience-driven retail strategies, such as olfactive storytelling, use scents to evoke emotions and memories associated with European landscapes or cultural heritage. This approach is gaining traction in marketing and product development, as brands seek to differentiate themselves and create memorable consumer interactions. By crafting immersive experiences, retailers can engage customers in a multi-sensory journey that enhances their emotional connection to the brand and the products. This trend highlights the importance of experiential retail in the modern fragrance market, where consumers are not just buying a product but also seeking an enriching experience.
Market Challenges Analysis
Complex Regulatory Environment and Competition
The European Perfume Ingredients Chemicals Market operates within a complex regulatory environment characterized by stringent regulations like REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) and the Cosmetic Products Regulation (CPR). While these regulations are essential for ensuring consumer safety and product quality, they pose significant challenges for manufacturers. Compliance with these extensive regulatory processes can be costly and time-consuming, particularly for smaller companies with limited resources. The need to adhere to strict safety standards and ingredient limitations can stifle innovation, making it difficult for businesses to introduce new and creative products. This regulatory burden necessitates substantial investment in research, development, and compliance measures, which can increase overall production costs and impact profitability. Navigating this intricate regulatory landscape requires companies to be agile and well-informed, balancing the demands of safety and quality with the need for innovation and cost-efficiency.
Economic Fluctuations and Counterfeiting
The European market is susceptible to economic fluctuations, which can directly impact consumer spending on non-essential items like fragrances. Economic booms and busts influence disposable incomes and purchasing power, leading to fluctuations in demand for perfume ingredients. During economic downturns, consumers may prioritize essential goods over luxury items, resulting in decreased sales and revenue for fragrance manufacturers. This volatility requires companies to adopt flexible strategies and maintain financial resilience to navigate changing economic conditions effectively. Additionally, counterfeiting and product piracy present significant challenges in the European market. Counterfeit perfumes and fragrance ingredients can severely damage brand reputation and financial health for legitimate businesses. These fake products not only erode consumer trust but also pose safety risks, undermining the credibility of authentic brands. Combating counterfeiting requires robust collaboration between manufacturers, retailers, and customs authorities to implement stringent anti-counterfeiting measures and ensure product authenticity.
Market Segmentation Analysis:
By Product Type:
The Europe Perfume Ingredients Chemicals Market is segmented by product type into synthetic aroma chemicals and essential oils. Synthetic aroma chemicals dominate the market due to their cost-effectiveness and ability to create specific and consistent scent profiles. Key sub-segments within synthetic aroma chemicals include alcohols, esters, ethers, ketones, and others such as thiols and dienals. Alcohols serve as solvents and carriers in perfume formulations, while esters and ethers contribute sweet and fruity notes. Ketones add complexity and richness to fragrances, enhancing overall scent profiles. On the other hand, essential oils are gaining significant traction driven by consumer preferences for natural and sustainable ingredients. Popular essential oils in the European market include orange, citronella, peppermint, eucalyptus, and others like rose, sandalwood, and various citrus oils. These oils are valued for their therapeutic properties and complex aromas, aligning with the increasing demand for eco-friendly and health-conscious products. The balance between synthetic and natural ingredients reflects the market's adaptability to diverse consumer preferences and regulatory requirements.
By Application:
Based on application, the Europe Perfume Ingredients Chemicals Market is divided into fine fragrance, home care, laundry care, cosmetics, and others. The fine fragrance segment holds a significant share, driven by the region’s rich heritage in perfumery and high consumer demand for luxury and personalized scents. European consumers show a strong preference for high-quality, long-lasting perfumes, fueling the growth of this segment. Home care products, including air fresheners and cleaning agents, utilize perfume ingredients to enhance the sensory experience, making this a growing segment. Laundry care products, such as detergents and fabric softeners, heavily rely on fragrance chemicals to provide fresh and appealing scents, contributing to consumer satisfaction and brand loyalty. The cosmetics segment, encompassing skincare, haircare, and personal care products, benefits from the use of perfume ingredients to enhance product appeal and differentiation. Other applications include industrial and institutional products where fragrance plays a crucial role in masking odors and improving user experience. This diverse application landscape underscores the versatility and essential role of perfume ingredients chemicals in various sectors across Europe.
Segments:
Based on Product Type:
- Synthetic Aroma Chemicals
- Alcohol
- Esters
- Ethers
- Ketone
- Others (Thiols, Dienals, etc.)
- Essential Oils
- Orange
- Citronella
- Peppermint
- Eucalyptus
- Others (Rose, Sandalwood, Orange etc.)
Based on Application:
- Fine Fragrance
- Home Care
- Laundry Care
- Cosmetics
- Others
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
France, the epicenter of the global perfume industry, leads the market with approximately 30% of the regional share. This dominance stems from its long-standing tradition in fine fragrances, world-renowned perfume houses, and cutting-edge research facilities. Germany follows with about 20% of the market share, leveraging its strong chemical industry and growing demand for natural and sustainable ingredients. Italy captures around 15% of the market, benefiting from its fashion-forward culture and expertise in luxury goods.
Spain and the United Kingdom each hold approximately 10% of the market share, with both countries experiencing growth in niche and artisanal fragrances. The remaining 15% is distributed among other European countries, including Switzerland, the Netherlands, and emerging Eastern European markets. Across Europe, there's a notable trend towards clean label products and transparent supply chains, reflecting increasing consumer awareness of ingredient sourcing and environmental impact.
Key Player Analysis
- Charkit Chemical Company LLC
- Givaudan
- Firmenich
- Symrise
- International Flavors & Fragrances (IFF)
- Takasago International Corporation
- Robertet Group
- Mane
- Huabao International Holdings Limited
- Henkel AG & Co KGaA ADR
Competitive Analysis
The Europe Perfume Ingredients Chemicals Market is highly competitive, dominated by leading players such as Givaudan, Firmenich, Symrise, International Flavors & Fragrances (IFF), and Takasago International Corporation. These companies maintain their competitive edge through extensive research and development capabilities, continually innovating to create unique and high-quality fragrance ingredients. Givaudan and Firmenich leverage their long-standing heritage and expertise in both natural and synthetic ingredients to cater to diverse consumer preferences. Symrise focuses on sustainable practices and ethical sourcing, appealing to the growing demand for eco-friendly products. IFF integrates advanced technologies and AI-driven scent creation to offer personalized and cutting-edge fragrance solutions. Takasago excels in blending traditional techniques with modern innovations, enhancing their market presence. The competitive landscape necessitates continuous investment in R&D, strategic partnerships, and marketing to stay ahead, with smaller niche brands emerging and challenging the established giants by offering artisanal and bespoke fragrance experiences.
Recent Developments
- In January 2023, S H Kelkar and Company revealed that its wholly owned subsidiary, Keva Europe B.V. acquired a 100% stake in PFW Aroma Ingredients B.V. (PFW) from Keva UK. The acquisition has strengthened the aroma chemicals business of the company.
- In August 2022, Oriental Aromatics Ltd. announced an investment of nearly INR 1.3 - 1.5 billion (USD 15.69 - 18.10 million) for the development of a hydrogenation plant in Vadodara for specialty aroma chemicals. The plant is expected to be commissioned by the H2 of F.Y. 2024.
- In May 2022, DSM Group, a Dutch company, acquired Firmenich, a Switzerland-based perfume manufacturer.
Market Concentration & Characteristics
The Europe Perfume Ingredients Chemicals Market exhibits moderate to high market concentration, with a few dominant players such as Givaudan, Firmenich, Symrise, International Flavors & Fragrances (IFF), and Takasago International Corporation holding significant market shares. These leading companies leverage their extensive R&D capabilities, diverse product portfolios, and robust distribution networks to maintain their competitive positions. The market is characterized by a strong emphasis on sustainability and innovation, driven by consumer demand for natural, eco-friendly, and personalized fragrance products. Companies are increasingly focusing on ethical sourcing and sustainable practices to meet regulatory requirements and consumer expectations. Additionally, the market features a dynamic interplay between traditional luxury fragrances and emerging niche brands that offer unique, artisanal scents. This combination of established industry leaders and innovative newcomers creates a vibrant and competitive market environment, fostering continuous growth and development in the European perfume ingredients sector.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Perfume Ingredients Chemicals Market will continue to grow due to rising consumer demand for luxury and personalized fragrances.
- Advancements in synthetic aroma chemicals will enhance fragrance complexity and stability.
- Increasing preference for natural and sustainable ingredients will drive demand for essential oils and botanical extracts.
- E-commerce expansion will boost accessibility and sales of perfume ingredients across Europe.
- Regulatory trends towards safety and environmental sustainability will push companies to innovate and comply with stricter standards.
- The market will witness a rise in niche perfumery brands offering unique and artisanal scents.
- Technological advancements in fragrance formulation will lead to the development of new and distinctive scent profiles.
- Collaboration between manufacturers, retailers, and regulatory bodies will intensify to combat counterfeiting and ensure product authenticity.
- Growth in the personal care and cosmetics industries will positively impact the demand for fragrance chemicals.
- Companies will increasingly focus on ethical sourcing and sustainable production practices to align with consumer expectations and regulatory requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Perfume Ingredients Chemicals Market?
What factors are driving the growth of the Europe Perfume Ingredients Chemicals Market?
What are the key segments within the Europe Perfume Ingredients Chemicals Market?
What are some challenges faced by the Europe Perfume Ingredients Chemicals Market?
Who are the major players in the Europe Perfume Ingredients Chemicals Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Perfume Ingredients Chemicals Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Perfume Ingredients Chemicals Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,647.50 million → 2032: USD 2,537.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Perfume Ingredients Chemicals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Perfume Ingredients Chemicals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Perfume Ingredients Chemicals Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Perfume Ingredients Chemicals Market Drivers
- 3.3 Europe Perfume Ingredients Chemicals Market Restraints & Challenges
- 3.4 Europe Perfume Ingredients Chemicals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Perfume Ingredients Chemicals Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Perfume Ingredients Chemicals Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Perfume Ingredients Chemicals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Perfume Ingredients Chemicals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Perfume Ingredients Chemicals Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Perfume Ingredients Chemicals market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Perfume Ingredients Chemicals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Perfume Ingredients Chemicals Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Perfume Ingredients Chemicals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Perfume Ingredients Chemicals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Perfume Ingredients Chemicals Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Perfume Ingredients Chemicals Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Perfume Ingredients Chemicals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Perfume Ingredients Chemicals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Perfume Ingredients Chemicals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Perfume Ingredients Chemicals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Perfume Ingredients Chemicals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Perfume Ingredients Chemicals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Perfume Ingredients Chemicals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
