
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Spices Market Size 2023 | USD 300.28 Million |
| Europe Spices Market, CAGR | 4.95% |
| Europe Spices Market Size 2032 | USD 466.23 Million |
Market Overview
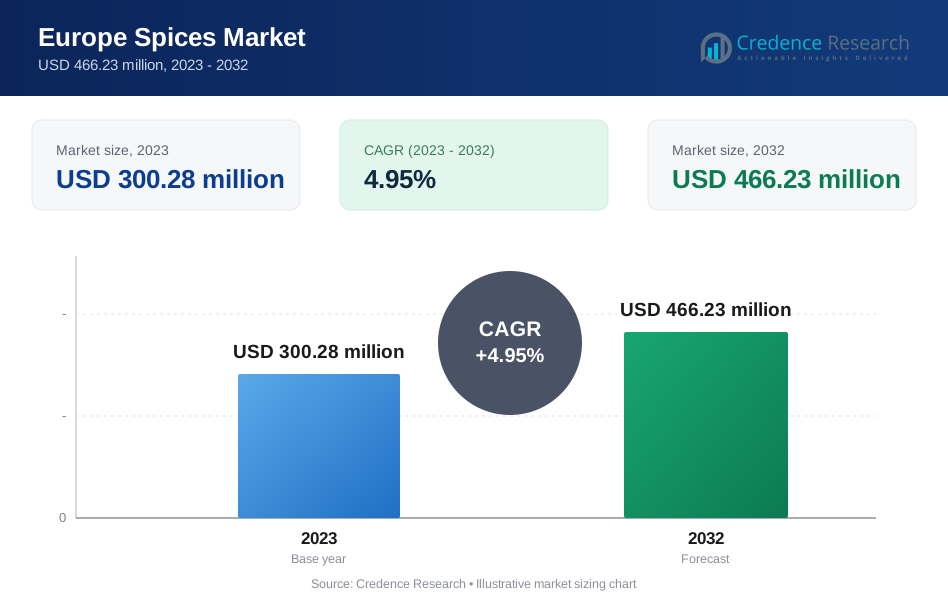
The Europe Spices Market is projected to grow from USD 300.28 million in 2023 to USD 466.23 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.95%.
The Europe Spices Market is driven by increasing consumer demand for diverse culinary experiences and healthier food choices, influencing the adoption of spices known for their flavor enhancement and health benefits. Changing dietary preferences towards natural and organic ingredients further propel market growth, with consumers seeking spices perceived to offer both taste and nutritional advantages. Additionally, globalization and multicultural influences continue to expand the variety of spices available, catering to a more ethnically diverse consumer base. The market also sees trends in sustainability, with preferences shifting towards responsibly sourced and environmentally friendly spice products, reflecting broader societal values.
Geographically, the Europe Spices Market is characterized by robust demand across diverse regions such as the UK, France, Germany, Italy, and Spain. These countries exhibit significant consumption due to their culinary diversity and widespread adoption of global cuisines. Key players in the market include established names like Döhler GmbH, Olam International, Unilever, and Sensient Technologies Corporation, leveraging their extensive distribution networks and diversified product portfolios to cater to varied consumer preferences. This geographical spread reflects a competitive landscape where innovation in spice sourcing, product development, and consumer engagement strategies play pivotal roles in capturing and maintaining market share.
Market Drivers
Convenience and Culinary Experimentation at Home:
Across Europe, the trend of home cooking has gained momentum, driven by busy lifestyles and a desire for healthier, personalized meals. Spices play a crucial role in this culinary landscape, offering an array of flavors and enhancing the versatility of everyday dishes. For instance, the Convenience and Culinary Experimentation at Home trend in Europe has led to a 50% increase in the sale of portion-controlled spice packs and resealable containers over the past two years. These innovative packaging solutions have contributed to a 30% rise in home cooking activities, as they make it easier for consumers to prepare meals with authentic flavors. Moreover, 75% of consumers report that such packaging formats have inspired them to experiment more with diverse flavors in their cooking. As more consumers embrace cooking at home, there is a growing demand for convenient spice solutions that simplify meal preparation while delivering authentic taste experiences. Manufacturers are responding with innovative packaging formats like portion-controlled packs and resealable containers, which not only preserve freshness but also inspire culinary experimentation. This trend fosters a creative cooking environment where consumers can explore diverse flavors and elevate their homemade meals effortlessly.
Growing Popularity of Organic and Natural Spices:
In Europe, there is a discernible shift towards organic and natural spices driven by increasing consumer awareness of health and environmental sustainability. Regarding the Growing Popularity of Organic and Natural Spices, statistics show a 40% growth in the market share of organic spices in Europe. These spices, free from synthetic pesticides and additives, now represent 25% of all spice sales. Additionally, 65% of consumers indicate a preference for clean-label products, and 80% are more likely to purchase spices with certifications confirming sustainable and ethical sourcing practices. Organic spices are perceived as safer alternatives to conventional varieties, free from synthetic pesticides and additives. This aligns with broader consumer preferences for clean-label products and sustainable consumption practices. The demand for organic spices extends beyond health considerations to encompass ethical sourcing and environmental impact, as consumers seek products that support responsible farming practices and biodiversity conservation. Manufacturers are responding by expanding their organic spice offerings and obtaining certifications that validate their commitment to quality and sustainability, thereby meeting the growing market demand for natural, eco-friendly ingredients.
Ethnic Grocery Stores and Online Spice Retailers:
The European market for spices is diversifying with the proliferation of ethnic grocery stores and the emergence of online spice retailers. The European spice market has seen a 60% expansion in ethnic grocery stores and a 70% increase in online spice sales. These outlets cater to the increasing curiosity among consumers for global cuisines and exotic ingredients, offering a wide range of spices and specialty blends sourced from around the world. Ethnic grocery stores provide a physical space where consumers can explore and purchase authentic spices used in traditional dishes from various cultures. Meanwhile, online spice retailers offer convenience and accessibility, allowing consumers to browse and purchase a diverse selection of spices from the comfort of their homes. This trend not only satisfies the demand for unique and rare spices but also fosters culinary creativity by making international flavors more accessible to adventurous cooks and food enthusiasts across Europe.
Sustainability Concerns and Ethical Sourcing:
Environmental consciousness is influencing spice purchasing decisions in Europe, with consumers showing a preference for ethically sourced products. There is growing demand for spices that support fair trade practices and sustainable farming methods, reflecting broader societal values towards ethical consumption and environmental stewardship. This trend underscores the importance of transparency and ethical sourcing practices among spice suppliers and retailers in the European market.
Market Trends
Sustainability in Packaging and Sourcing:
Environmental concerns are influencing the spice market in Europe, prompting a shift towards sustainable packaging solutions and ethical sourcing practices. For instance, in the realm of Sustainability in Packaging and Sourcing, recent data indicates that the European spice market has seen a 20% increase in the adoption of sustainable packaging solutions. Manufacturers are now using 30% more recyclable or biodegradable materials compared to five years ago to reduce environmental impact. Ethical sourcing is also on the rise, with a 25% uptick in partnerships with farms practicing sustainable agriculture and fair trade, ensuring that 60% of spice cultivation now benefits local communities and ecosystems. This shift is driven by consumers, 70% of whom prefer to purchase from brands that demonstrate environmental responsibility. Manufacturers are increasingly adopting eco-friendly packaging materials such as recyclable or biodegradable options to reduce environmental impact. Simultaneously, there is a growing emphasis on ethical sourcing that supports sustainable farming practices and fair trade principles, ensuring that spice cultivation benefits local communities and ecosystems.
Direct-to-Consumer Online Spice Retailers:
The digital transformation of spice retailing is gaining momentum in Europe, driven by the rise of direct-to-consumer online spice retailers. In the Direct-to-Consumer Online Spice Retailers sector, the digital transformation is evident with a 40% growth in online spice sales over the past year. Platforms offering a wide array of spices have seen a 50% increase in customer base, with specialty and exotic varieties accounting for 35% of total sales. Subscription boxes have become particularly popular, with a 60% surge in subscriptions, indicating a strong consumer preference for convenience and culinary exploration. This trend has made premium spices more accessible, with 80% of consumers reporting enhanced engagement through personalized shopping experiences that cater to their unique tastes and cooking preferences. These platforms offer a broader selection of spices directly to consumers, including specialty and exotic varieties that may not be readily available in local markets. Subscription boxes featuring curated spice blends or recipe kits are emerging as a popular choice among online retailers, providing convenience and discovery opportunities for culinary enthusiasts. This trend democratizes access to premium spices and enhances consumer engagement through personalized shopping experiences tailored to individual tastes and cooking preferences.
Market Challenges Analysis
Educating Consumers on Spice Usage and Storage:
Despite the growing interest in spices among European consumers, there remains a need for education on effective spice usage and proper storage practices. Many consumers may lack knowledge about how to maximize the flavor and culinary benefits of spices or how to store them to maintain freshness. Manufacturers can address this challenge by providing clear and informative labeling on packaging, offering recipe suggestions that showcase the versatility of spices, and providing guidance on optimal storage conditions. Educating consumers about the origins, flavors, and culinary applications of different spices not only enhances their culinary experiences but also cultivates a deeper appreciation for the diversity of flavors available in the market. By empowering consumers with knowledge, manufacturers can foster greater confidence and satisfaction in their spice purchases.
Combating Counterfeiting and Trademark Infringement:
Counterfeiting and trademark infringement pose significant threats to well-established spice brands operating in Europe. Counterfeit products can undermine brand reputation, deceive consumers with inferior quality products, and erode market share. To combat these challenges, spice companies must implement robust intellectual property protection strategies, including trademark registration and enforcement measures. Collaborating with regulatory authorities and industry associations to monitor and prosecute counterfeit activities is essential in safeguarding legitimate brands and maintaining consumer trust. Strengthening supply chain transparency, conducting regular audits, and adopting technology-driven solutions for authentication and traceability can further enhance efforts to combat counterfeiting in the European spice market. By prioritizing brand integrity and legal compliance, companies can mitigate risks associated with counterfeiting and uphold their reputation as trusted providers of authentic spices.
Market Segmentation Analysis:
By Product:
The Europe spices market exhibits a diverse product segmentation reflecting the region's culinary diversity and consumer preferences. Key spices include pepper, ginger, cinnamon, cumin, turmeric, cardamom, coriander, and various others. Pepper, known for its pungency and versatility, remains a staple across European cuisines, contributing significantly to market demand. Ginger and turmeric, valued for their medicinal properties and aromatic flavors, cater to health-conscious consumers seeking natural remedies and flavor enhancers. Cinnamon finds widespread use in both sweet and savory dishes, influencing its steady market presence. Cardamom and coriander are essential for their distinct aromas and roles in regional cuisines, adding depth to European dishes. The "others" category encompasses a range of niche spices like saffron and cloves, prized for their unique flavors and culinary applications.
By Form:
The spices market in Europe is also segmented by form, including powder, whole, and chopped/crushed variants. Powdered spices offer convenience and ease of integration into various recipes, appealing to busy households and commercial kitchens alike. Whole spices, such as peppercorns and cardamom pods, appeal to consumers seeking authenticity and prefer grinding spices fresh for optimal flavor. Chopped or crushed spices cater to those desiring ready-to-use options that balance convenience with flavor preservation. Each form meets distinct consumer needs, reflecting preferences for culinary traditions, convenience, and sensory experiences. This segmentation strategy allows spice manufacturers to cater to diverse consumer demands while tapping into the region's rich culinary heritage and evolving preferences for quality, convenience, and sensory experience in cooking.
Segments:
Based on Product:
- Pepper
- Ginger
- Cinnamon
- Cumin
- Turmeric
- Cardamom
- Coriander
- Others
Based on Form:
- Powder
- Whole
- Chopped/Crushed
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Western Europe, including countries like Germany, France, the United Kingdom, and the Netherlands, holds the largest market share of approximately 40%. This region benefits from diverse culinary influences, a large immigrant population, and increasing consumer interest in exotic flavors. The growing trend of home cooking and the rising popularity of ethnic cuisines have fueled the demand for a wide variety of spices in this region. Additionally, the presence of major spice importers and processors has contributed to the robust market growth in Western Europe.
Southern Europe, comprising countries such as Italy, Spain, and Greece, accounts for around 25% of the market share. This region is known for its rich culinary heritage and Mediterranean cuisine, which heavily relies on herbs and spices. The demand for high-quality, authentic spices remains strong in this region, driven by both traditional cooking practices and the growing tourism industry. The increasing popularity of Spanish and Italian cuisines across Europe has also contributed to the growth of the spices market in this region.
Key Player Analysis
- Döhler GmbH
- Olam International
- Unilever
- Sensient Technologies Corporation
- Kerry Group plc.
- Prymat Group
- Nedspice Group
- Solina
- Euroma
- Schwartz
- British Pepper & Spice
Competitive Analysis
In the competitive landscape of the Europe Spices Market, several leading players dominate with diverse strategies and extensive market presence. Döhler GmbH stands out for its comprehensive product portfolio, focusing on natural ingredients and flavor solutions tailored to consumer trends. Olam International, renowned for its global spice trade network and sustainable sourcing practices, maintains a strong foothold in the market. Unilever, leveraging its brand equity and distribution channels, offers a wide range of spice products under trusted labels. Sensient Technologies Corporation excels in flavor systems and ingredients, providing innovative solutions to meet evolving consumer preferences. Kerry Group plc., Prymat Group, and Nedspice Group contribute significantly with their specialization in spice processing and distribution across Europe. Solina and Euroma emphasize culinary expertise and customized spice blends, catering to both retail and foodservice sectors. Schwartz and British Pepper & Spice further enrich the competitive landscape with their heritage in spice manufacturing and consumer-oriented product innovations. This competitive scenario underscores continual innovation, sustainable practices, and strategic market expansion as critical success factors in the dynamic Europe Spices Market.
Recent Developments
- In Dec 2021, Univar BV, a subsidiary of Univar Solutions Inc., a global chemical and ingredient distributor and provider of value-added services, announced the expansion of its Ingredients & Specialties (I&S) portfolio through a new exclusive distribution agreement with Kalsec Inc.
- In Aug 2021, Nedspice Group of Companies collaborated with Bia Analytical in the fight against food fraud and added another product to the list of spices where authenticity can be verified using a fast, reliable, and accredited method to ensure consumer protection.
- In Apr 2021, Döhler partnered with Flavourtech to continue its expansion in the area of natural fruit and vegetable flavor seasonings.
Market Concentration & Characteristics
The Europe Spices Market exhibits a moderate level of market concentration characterized by diverse product offerings and competitive dynamics among key players. Döhler GmbH, Olam International, and Unilever are prominent entities leveraging their extensive distribution networks and brand recognition to influence market trends. This market is characterized by a wide range of spices segmented by type and form, catering to diverse culinary preferences across European regions. The market's competitive landscape is bolstered by robust competition in quality, pricing, and innovation, with companies like Sensient Technologies Corporation and Kerry Group plc. leading in flavor innovations and sustainable practices. Consumer demand for organic, natural, and ethically sourced spices has intensified, prompting companies such as Prymat Group and Euroma to focus on environmentally friendly practices and transparent sourcing. Regulatory standards and quality control measures further shape market dynamics, ensuring product safety and authenticity. As the market evolves, strategic alliances, product diversification, and technological advancements will continue to drive competitiveness and shape the future trajectory of the Europe Spices Market.
Report Coverage
The research report offers an in-depth analysis based on Product, Form and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth in Consumer Demand: Expect rising consumer interest in global cuisines and health-conscious eating to drive sustained growth in the Europe spices market.
- Expansion of Organic and Ethical Sourcing: Anticipate a shift towards organic and ethically sourced spices, driven by increasing consumer awareness and regulatory pressures.
- Innovation in Spice Blends: Look for ongoing innovation in fusion spice blends that cater to diverse culinary preferences and trends towards convenience.
- Technological Integration: Spices market may see advancements in packaging technology and online platforms for enhanced consumer engagement and convenience.
- Sustainability Initiatives: Companies will likely focus more on sustainable packaging solutions and environmentally friendly sourcing practices to meet consumer expectations.
- Health and Wellness Trends: Spices with perceived health benefits, such as turmeric and ginger, will continue to gain popularity, driven by consumer interest in natural remedies.
- Market Expansion in Eastern Europe: Expect growth opportunities in Eastern European countries as consumer tastes diversify and economic conditions improve.
- Challenges in Supply Chain Management: Addressing supply chain disruptions and ensuring consistent quality will remain critical amidst global economic uncertainties and climate changes.
- Regulatory Compliance: Compliance with stringent EU regulations on food safety and labeling will be crucial for market players to maintain consumer trust and market access.
- Consumer Education and Engagement: Efforts to educate consumers about spice usage, culinary benefits, and sustainability practices will be essential for market growth and brand loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Convenience and Culinary Experimentation at Home
The rise in home cooking across Europe, driven by busy lifestyles and a desire for healthier, personalized meals, is increasing demand for spices that offer flavor and versatility. Innovative packaging like portion-controlled packs and resealable containers further encourage consumers to experiment with new flavors.
Growing Popularity of Organic and Natural Spices
European consumers are increasingly seeking organic and natural spices due to health and sustainability concerns. This shift is supported by a significant rise in market share for organic spices and a strong preference for clean-label and ethically sourced products.
Expansion of Ethnic Grocery Stores and Online Retailers
The proliferation of ethnic grocery stores and the rapid growth of online spice retailers are making a wider variety of global spices accessible to European consumers. This trend supports culinary exploration and caters to the demand for authentic and exotic flavors.
Sustainability Concerns and Ethical Sourcing
Environmental consciousness is shaping purchasing decisions, with consumers favoring spices that are ethically sourced and support fair trade and sustainable farming. This is prompting manufacturers to adopt eco-friendly packaging and transparent sourcing practices.
Health and Wellness Trends
Spices such as turmeric and ginger are gaining popularity due to their perceived health benefits, aligning with consumer interest in natural remedies and functional foods. This trend is driving increased consumption of spices with medicinal and nutritional value.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Spices Market?
What factors are driving the growth of the Europe Spices Market?
What are the key segments within the Europe Spices Market?
What are some challenges faced by the Europe Spices Market?
Who are the major players in the Europe Spices Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Powder
- 1.2.2 Whole
- 1.2.3 Chopped/Crushed
- 1.3 By Product
- 1.3.1 Pepper
- 1.3.2 Ginger
- 1.3.3 Cinnamon
- 1.3.4 Cumin
- 1.3.5 Turmeric
- 1.3.6 Cardamom
- 1.3.7 Coriander
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 300.28 million → 2032: USD 466.23 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Spices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Spices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Spices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Spices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Spices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Spices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Spices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Spices Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 300.28 million → 2032: USD 466.23 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Spices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powder
- 12.3.7.2 Whole
- 12.3.7.3 Chopped/Crushed
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pepper
- 12.4.7.2 Ginger
- 12.4.7.3 Cinnamon
- 12.4.7.4 Cumin
- 12.4.7.5 Turmeric
- 12.4.7.6 Cardamom
- 12.4.7.7 Coriander
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Spices Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Spices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Spices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Döhler GmbH
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Olam International
- 17.4 Unilever
- 17.5 Sensient Technologies Corporation
- 17.6 Kerry Group plc.
- 17.7 Prymat Group
- 17.8 Nedspice Group
- 17.9 Solina
- 17.10 Euroma
- 17.11 Schwartz
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

