
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| European Electric Truck Market Size 2023 | USD 729.13 million |
| European Electric Truck Market, CAGR | 42.15% |
| European Electric Truck Market Size 2032 | USD 17,478.72 million |
Market Overview:
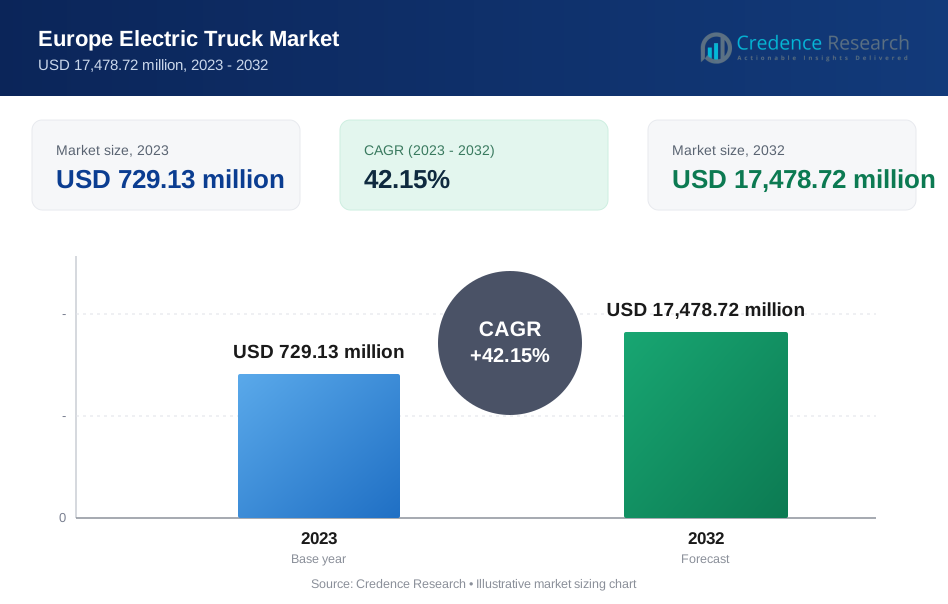
The Europe electric truck market is projected to grow from USD 729.13 million in 2023 to USD 17,478.72 million by 2032, at a compound annual growth rate (CAGR) of 42.15%.
This market is experiencing remarkable growth, driven by various factors. The surge in market size and the impressive growth rate showcase the potential and dynamism of this sector. The growth is fueled by advancements in technology, increasing environmental awareness, and supportive government policies, among other factors. This trajectory suggests a promising future for the Europe electric truck market. This surge can be primarily attributed to stringent emission regulations imposed by the European Union, prompting manufacturers to invest in cleaner transportation solutions like electric trucks. Moreover, government incentives such as subsidies and tax breaks are incentivizing fleet operators to adopt electric trucks, offsetting the initial higher purchase costs compared to diesel alternatives.
Technological advancements play a pivotal role in the rapid growth of the Europe electric truck market. Innovations in battery technology are extending the range and reducing charging times, addressing concerns regarding range anxiety and enhancing overall efficiency and performance. Furthermore, the growing environmental consciousness among businesses and consumers is driving the shift towards sustainable transportation solutions. Electric trucks offer a cleaner alternative to diesel counterparts, aligning with environmental goals and influencing purchasing decisions.
Looking ahead, several trends are poised to shape the future landscape of the Europe electric truck market. Diversification across light-duty, medium-duty, and heavy-duty segments will cater to a broader range of transportation needs. Focus on charging infrastructure development, battery technology innovations, and partnerships among stakeholders will further accelerate market growth. Despite the promising opportunities, challenges such as high upfront costs, limited charging infrastructure, and battery range limitations need to be addressed to unlock the full potential of the electric truck market in Europe.
Market Drivers:
Stringent Emission Regulations and Climate Change Concerns:
The European Union’s ambitious climate goals are driving the implementation of stricter emission standards for commercial vehicles, including heavy-duty trucks. For instance, in 2023, the EU adopted a set of Commission proposals to make the EU’s climate, energy, transport, and taxation policies fit for reducing net greenhouse gas emissions by at least 55% by 2030, compared to 1990 levels. This will enable the EU to become the first climate-neutral continent by 2050. Regulations like the Euro VII standards are pushing manufacturers towards cleaner alternatives such as electric trucks. The Euro 7 proposal focuses on improving control procedures for all vehicles, and aims to update and complete current emissions standards, covering dangerous pollutants such as nitrogen oxides (NOx).
Advancements in Battery Technology and Range Improvements:
Continuous advancements in battery technology are driving improvements in energy density and charging times, resulting in longer driving ranges for electric trucks. Manufacturers are also focusing on utilizing lighter materials in truck construction to offset the weight of battery packs, thereby enhancing payload capacity and overall efficiency. Additionally, the development of innovative battery swapping technologies holds promise for further reducing downtime and increasing operational efficiency for electric trucks, catering to the evolving needs of logistics operations.
Total Cost of Ownership (TCO) Advantages:
Despite higher upfront costs, electric trucks offer substantial savings in operating costs over their lifespan. Lower fuel costs, reduced maintenance requirements, and government incentives contribute to improving the total cost of ownership for electric trucks, making them financially attractive for fleet operators. Furthermore, reduced fuel price volatility and government grants for charging infrastructure installation further enhance the economic feasibility of electric trucks, aligning with the financial goals of logistics companies and fleet operators.
Government Incentives and Subsidies:
Governments across Europe are actively incentivizing the adoption of electric trucks through financial support, including subsidies and tax breaks. These incentives significantly mitigate the upfront costs associated with electric trucks, enhancing their competitiveness against traditional diesel counterparts. For instance, these automobiles will be subsidized by 20% of the purchase price, up to a maximum of £16,000 per vehicle. Moreover, substantial investments in expanding charging infrastructure are being made, addressing concerns related to range anxiety and ensuring the operational feasibility of electric trucks. By 2030, a total amount of up to €280bn will need to be invested in installing public and private charging points, upgrading the power grid, and building capacity for renewable energy production7. Tax breaks and exemptions offered by certain European countries further contribute to making electric trucks an economically viable option for logistics companiesparticulate matter (PM), carbon monoxide, and ammonia.
Market Trends:
Surge in Government Support and Regulations:
Stringent emission regulations and ambitious climate goals set by European governments are acting as a major catalyst for electric truck adoption. For instance, the European Union has implemented significant fiscal incentives such as purchase subsidies and vehicle purchase and registration tax rebates. These incentives have spurred the initial uptake of electric light-duty vehicles (LDVs) and underpinned the scale-up in EV manufacturing and battery industries. Additionally, regulations like upcoming CO2 reduction targets for trucks are pushing manufacturers to accelerate their development and production of electric models. The European Commission proposed new targets in 2023, which would decrease CO2 emissions per km from new heavy-duty vehicles (HDVs) by 90% by 2040, with intermediate targets for 2030 (45%) and 2035 (65%).
Technological Advancements and Cost Reductions:
Battery technology advancements are leading to longer ranges, faster charging times, and lower overall battery costs. For example, recent developments have led to batteries with higher energy density, enabling electric trucks to achieve longer ranges on a single charge. Fast-charging technology is another significant advancement, reducing downtime by enabling trucks to recharge quickly during breaks or layovers. This, coupled with improvements in electric motor efficiency and overall vehicle design, is making electric trucks a more attractive proposition for fleet operators. As production scales up, costs are expected to decrease further, creating a more competitive market. For instance, the cost of electric trucks in India ranges from Rs. 0.58 Lakh to Rs. 9.22 Lakh, and these prices are expected to decrease as production scales up and technology improves.
Expanding Focus on Urban Logistics and Short-Haul Applications:
Electric trucks are currently finding their sweet spot in urban and short-haul applications due to their lower range requirements and ability to operate quietly within city limits. This is particularly appealing for last-mile delivery fleets, waste collection services, and regional distribution networks. As battery ranges improve, electric trucks are expected to gradually penetrate longer-haul routes as well.
Growing Collaboration Between Manufacturers and Logistics Providers:
The European market is witnessing increased collaboration between electric truck manufacturers and logistics companies. These partnerships focus on developing customized electric truck solutions, ensuring reliable charging infrastructure at depots and along key routes, and exploring innovative operational models for integrating electric trucks seamlessly into existing fleets.
Market Restraints and Challenges:
Limited Charging Infrastructure and Range Anxiety:
Currently, the availability of charging infrastructure for electric trucks across Europe lags significantly behind that for passenger electric vehicles. This lack of readily available charging stations, especially along major transportation routes, creates "range anxiety" for potential buyers. Fears of running out of power before reaching a charging station can be a significant deterrent for long-haul trucking operations.
Higher Upfront Costs and Battery Investment:
Electric trucks carry a higher initial price tag compared to their diesel counterparts. While government incentives can help offset some of this cost difference, the upfront investment in battery technology remains a significant barrier for some businesses. Additionally, battery degradation over time necessitates replacements, adding to the overall operational cost considerations.
Slower Charging Times and Payload Limitations:
Compared to refueling a diesel truck, charging an electric truck can be a more time-consuming process. This can disrupt existing logistics schedules and potentially lead to inefficiencies, particularly for time-sensitive deliveries. Furthermore, the weight and size of batteries in current electric trucks can limit their cargo capacity compared to traditional diesel models, impacting overall payload capabilities.
Limited Production Capacity and Availability:
The electric truck market is still in its early stages of development, and production capacity for these vehicles is currently limited. This can lead to extended wait times for fleets looking to transition to electric powertrains. Additionally, the variety of electric truck models available is not yet as extensive as that of diesel trucks, potentially restricting options for businesses with specific needs.
Grid Capacity and Energy Mix Concerns:
Widespread adoption of electric trucks will place additional demands on the European electricity grid. Upgrading grid infrastructure to accommodate this increased demand will require significant investment. Furthermore, the reliance on fossil fuels in some European countries' energy mixes raises concerns about the overall environmental benefits of electric trucks if they are charged using a non-renewable power source.
Recent Developments:
- In June 2022, Swedish commercial vehicle maker Scania debuted its regional long-haul electric truck that would be available in Europe as both a rigid truck and a tractor-trailer. The truck would achieve full charge in less than 90 minutes, half the length of a driver's mandated 45-minute rest period for every 4.5 hours of driving in Europe at 375 kW. Both the Scania 45 R and S series feature a 410-kW powertrain.
- In June 2022, Plastic Omnium announced that it had agreed with ACTIA Group to acquire 100% of ACTIA Power Division for an enterprise value of EUR 52.5 million, with a closing scheduled in the third quarter of 2022. ACTIA Power, based in the United Kingdom, specializes in designing and manufacturing onboard batteries, power electronics, and electrification systems for electric vehicles in heavy mobility: trucks, buses, coaches, trains, and construction equipment.
- In June 2022, Mercedes Benz Trucks, a Daimler trucks subsidiary, announced its new eActros long-haul electric truck for long-distance transport at the IAA Transportation 2022 in Hanover. However, before its launch, the company revealed that the truck could achieve a 20% to 80% charge in 30 minutes.
- In May 2022, Mercedes-Benz Trucks announced that it is systematically pressing ahead with introducing additional battery-electric models for this and the future. For the important long-haul segment, the eActros LongHaul, with a range of around 500 kilometers on one battery charge, is scheduled to be ready for series production in 2024. Mercedes-Benz Trucks aims to increase the share of locally CO2-neutral new vehicles in Europe to more than 5 % by 2030.
- In April 2022, Volta Trucks unveiled the small 7.5 and 12 -ton iterations of the Volta Zero 16-ton. Both the new trucks would be visually similar to the 16-ton from the front, with the 12-ton having a long chassis design and an extra wheel to cater to the payload.
Segmentation Analysis:
By Propulsion Type
The electric truck market in Europe is primarily categorized into three propulsion types: Battery Electric Vehicles (BEV), Plug-In Hybrid Electric Vehicles (PHEV), and Fuel Cell Electric Vehicles (FCEV). As of 2023, BEVs dominate the market due to their zero-emission capabilities and lower operational costs. PHEVs are gaining traction as they offer flexibility for long-haul operations, while FCEVs are emerging as a viable option for heavy-duty applications, especially in regions with established hydrogen infrastructure.
By Truck Type
The market is also segmented by truck type, including light-duty trucks, medium-duty trucks, and heavy-duty trucks. Heavy-duty trucks account for the largest share of the market, driven by the need for sustainable solutions in freight transport. Medium-duty trucks are increasingly adopted for urban logistics, while light-duty trucks are popular among last-mile delivery services. The heavy-duty segment is expected to witness the highest growth rate as manufacturers innovate to meet stringent emission regulations.
By End User
End users of electric trucks include logistics, municipal services, and other applications. The logistics sector is the largest consumer, driven by the growing demand for sustainable supply chain solutions. Municipal services are also adopting electric trucks for waste collection and public transportation, aligning with environmental goals. Other applications, such as field services and distribution, are gradually integrating electric trucks to enhance operational efficiency and reduce carbon footprints. The Europe electric truck market is characterized by rapid growth across various segments, with BEVs leading the propulsion type category, heavy-duty trucks dominating the truck type segment, and logistics being the primary end user. As regulations tighten and technology advances, the market is expected to expand significantly in the coming years.
Segments:
By Propulsion Type
- BEV (Battery Electric Vehicle)
- PHEV (Plug-in Hybrid Electric Vehicle)
- FCEV (Fuel Cell Electric Vehicle)
By Truck Type
- Light Duty Trucks
- Medium Duty Trucks
- Heavy Duty Trucks
By End User
- Last-Mile Delivery
- Long Haul Transportation
- Refuse Services
- Field Services
- Distribution Services
By Range
- Up to 200 Miles
- Above 200 Miles
By Battery Capacity
- Less Than 50 kWh
- 50–250 kWh
- Above 250 kWh
By Country
- Germany
- United Kingdom
- Italy
- France
- Spain
- Belgium
- Russia
- The Netherlands
- Rest of Europe
Key player:
- AB Volvo
- Volta Trucks
- Daimler Trucks (Mercedes Benz Group AG )
- DAF Trucks NV (PACCAR Inc.)
- E-Trucks Europe BE
- Renault Trucks
- Tesla Motors Inc.
- Einride AB
- Tevva Motors Limited
- BYD Co. Ltd
- Scania AG
- MAN SE (Volkaswagen AG)
- IVECO SpA
- E-Force One AG
Regional Analysis:
Western Europe
Western Europe dominates the electric truck market, accounting for approximately 70% of the total European market share in 2023. The region benefits from well-established infrastructure, favourable government policies, and the presence of major manufacturers like Volvo Trucks, Daimler Trucks, and DAF Trucks. Countries such as Norway, Sweden, and the Netherlands lead in electric truck adoption, with Volvo Trucks capturing a significant market share of 42% in 2021.
Central and Eastern Europe
Central and Eastern Europe represent a smaller portion of the electric truck market, with a share of around 15% in 2023. However, the region is expected to witness steady growth as countries invest in infrastructure and adopt supportive policies to reduce emissions. Poland, Hungary, and the Czech Republic are emerging as key markets in this region.
United Kingdom
The United Kingdom accounts for approximately 10% of the Europe electric truck market. While the UK is one of the largest commercial vehicle markets in Western Europe, it lags behind other countries in terms of incentives and infrastructure development for electric trucks. The lack of a robust strategy and immediate investment in charging infrastructure may hinder the market's growth in the UK compared to other European nations.
Rest of Europe
The remaining European countries, including Southern Europe and the Baltics, collectively hold around 5% of the market share. These regions are expected to see gradual growth as they work towards aligning with the European Union's sustainability goals and investing in electric truck technologies. The increasing adoption of battery-electric and fuel cell electric trucks, coupled with supportive regulations and investments in charging infrastructure, will drive this growth across the region. Western Europe leads the Europe electric truck market, while Central and Eastern Europe, the United Kingdom, and the Rest of Europe present opportunities for growth as countries work towards reducing emissions and adopting sustainable transportation solutions.
Future Outlook:
- European governments are expected to continue implementing stringent emission regulations, promoting the transition to electric trucks and enhancing market growth.
- Increased incentives and subsidies for electric truck purchases will further stimulate adoption among fleet operators and logistics companies.
- Advancements in battery technology will provide longer ranges, shorter charging times, and higher payload capacities, making electric trucks more competitive against diesel models.
- Significant investments in charging infrastructure, including high-powered stations along major transport routes, will facilitate long-distance electric truck operations.
- Leading logistics companies are accelerating their electrification plans to meet sustainability goals and reduce operational costs, driving demand for electric trucks.
- As battery costs decrease and maintenance expenses for electric trucks remain lower, the overall TCO will increasingly favour electric models, influencing purchasing decisions.
- Manufacturers are expected to expand their electric truck portfolios, offering a wider range of models to cater to various applications and weight segments.
- The combination of electric trucks with autonomous driving technologies will enhance efficiency and safety, creating new market opportunities.
- Increased collaboration between truck manufacturers, energy companies, and logistics providers will accelerate the development and deployment of electric truck solutions.
- Growing environmental consciousness among businesses will make electric trucks more attractive for companies aiming to reduce their carbon footprints and promote sustainable practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the European electric truck market?
What are the key factors driving the growth of the European electric truck market?
How are technological advancements influencing the European electric truck market?
What future trends are expected in the European electric truck market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 729.13 million → 2032: USD 17,478.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Electric Truck Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Electric Truck Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Electric Truck Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Electric Truck Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Electric Truck Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Electric Truck Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Electric Truck Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Electric Truck Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 729.13 million → 2032: USD 17,478.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Electric Truck Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Electric Truck Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Electric Truck Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Electric Truck Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
