
Market Overview
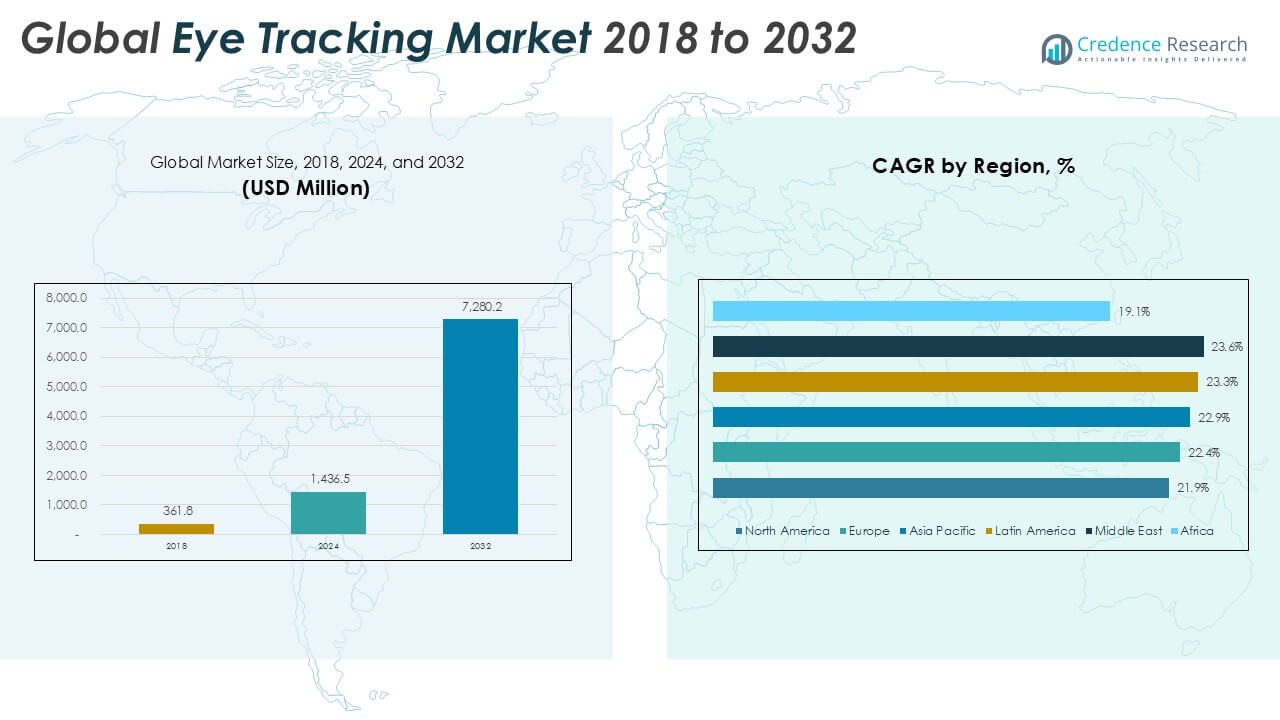
The Eye Tracking market size was valued at USD 361.8 million in 2018, increased to USD 1,436.5 million in 2024, and is anticipated to reach USD 7,280.2 million by 2032, at a CAGR of 22.58% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Eye Tracking Market Size 2024 | USD 1,436.5 Million |
| Eye Tracking Market, CAGR | 22.58% |
| Eye Tracking Market Size 2032 | USD 7,280.2 Million |
The Eye Tracking market is led by prominent players such as Tobii AB, Seeing Machines Ltd., EyeTech Digital Systems, EyeTracking, Inc., LC Technologies, Inc., and Gazepoint Research Inc. These companies are driving innovation through advanced eye-tracking hardware and AI-integrated software, focusing on applications across healthcare, automotive, and consumer electronics. Tobii AB maintains a strong leadership position through its diversified product offerings and global reach. Regionally, Asia Pacific dominates the market, accounting for 33.3% of the global share in 2024, fueled by rapid technological adoption in countries like China, Japan, and South Korea. Europe and North America follow, driven by strong research infrastructure and early adoption in accessibility and human-computer interaction solutions.
Market Insights
- The Eye Tracking market was valued at USD 361.8 million in 2018 and reached USD 1,436.5 million in 2024; it is projected to grow to USD 7,280.2 million by 2032, registering a CAGR of 22.58% during the forecast period.
- Growing demand for assistive technologies in healthcare, rising adoption in driver monitoring systems, and integration in AR/VR platforms are key factors driving market expansion.
- Emerging trends include the use of AI-powered gaze analysis tools, increasing deployment in gaming and advertising analytics, and a shift toward lightweight wearable eye-tracking devices.
- Asia Pacific led the global market with a 33.3% share in 2024, followed by Europe (26.0%) and North America (20.7%); hardware dominated the product segment due to high adoption of tracking glasses and screens.
- High device costs, complex calibration, and ethical concerns surrounding user data privacy remain key restraints to widespread market adoption.
Market Segmentation Analysis:
By Product:
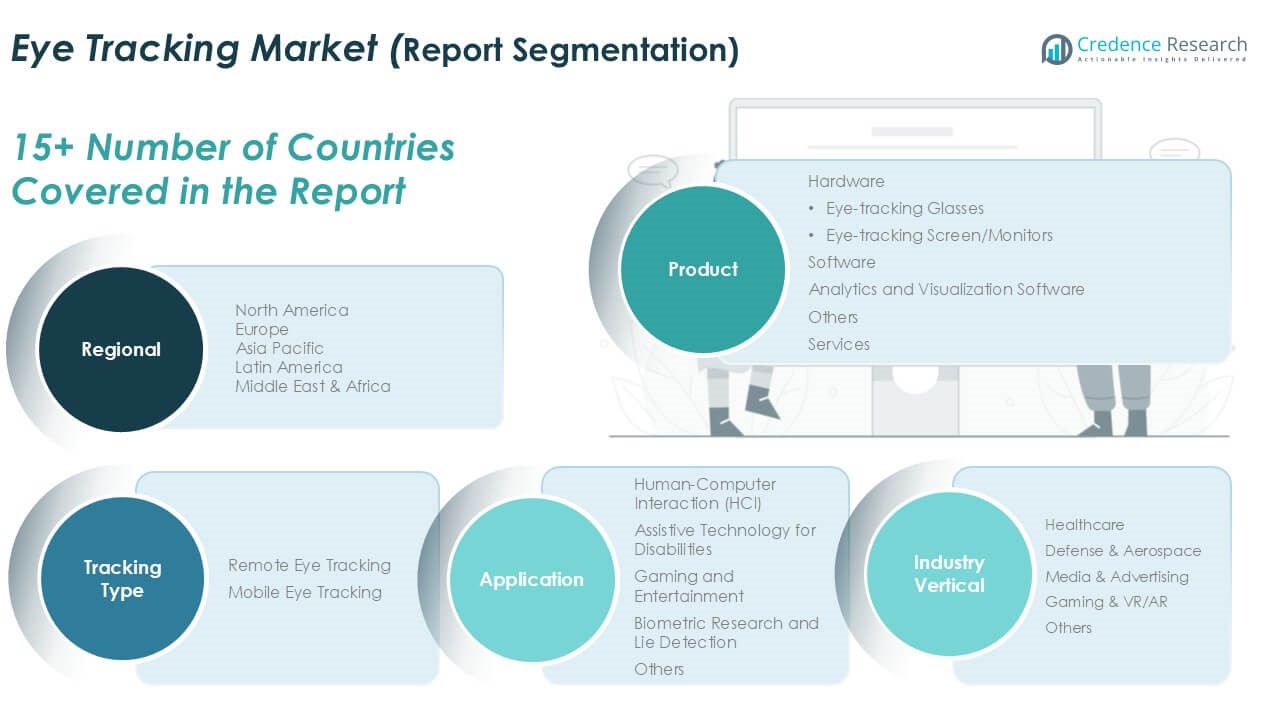
In the Eye Tracking market, the hardware segment held the dominant share in 2024, driven primarily by the growing adoption of eye-tracking glasses, which accounted for the largest sub-segment share. The increasing use of these devices in research, healthcare, and industrial applications has propelled their demand. Eye-tracking screens and monitors are also gaining traction in simulation and training environments. Meanwhile, software solutions, especially analytics and visualization tools, support researchers and developers in interpreting eye movement data effectively, though they hold a smaller share compared to hardware. The services segment continues to expand with growing demand for integration and maintenance support.
- For instance, Seeing Machines provides embedded service support across 2.3 million cars globally through its FOVIO driver monitoring platform.
By Tracking Type
Remote eye tracking emerged as the leading segment in 2024, capturing the majority share of the market. Its dominance stems from widespread use in usability testing, advertising research, and psychology studies, where non-intrusive tracking is crucial. These systems allow for precise eye movement analysis without requiring users to wear any device, making them ideal for large-scale lab and commercial environments. In contrast, mobile eye tracking-which includes wearable devices has seen rising adoption in real-world testing, especially in sports, retail analytics, and field research. However, remote systems remain preferred due to higher accuracy and user convenience.
- For instance, Pupil Labs’ Core eye tracker is a lightweight wearable that records gaze data at 200 Hz, supporting flexible deployments in uncontrolled environments.
By Application
Among application areas, human-computer interaction (HCI) represented the largest market share in 2024. This growth is largely attributed to rising investments in AI-driven interface development and accessible technology, especially for individuals with mobility or communication challenges. Eye tracking enhances control systems in both consumer electronics and professional systems, creating seamless user experiences. Gaming and entertainment also form a significant portion of the market, as developers integrate eye-tracking technology into immersive environments. Assistive technologies for disabilities are expanding steadily, driven by healthcare and rehabilitation use. Biometric research and lie detection remain niche but are gaining momentum in security and behavioral sciences.
Key Growth Drivers
Rising Integration in Healthcare and Assistive Technologies The increasing use of eye tracking in healthcare, particularly in neurological diagnostics and assistive communication tools for patients with motor disabilities, is a major growth driver. These systems enable non-verbal patients to interact with devices using eye movement, improving independence and care efficiency. Eye tracking is also aiding early detection of cognitive conditions such as Alzheimer’s and Parkinson’s. With growing investments in digital health and patient-centered technology, demand for precision eye-tracking hardware and software in medical settings is expected to expand significantly.
- For instance, SR Research’s EyeLink 1000 Plus system supports clinical studies with its high sampling rate of up to 2000 Hz, enabling the detection of subtle oculomotor irregularities in neurodegenerative disorders.
Expanding Applications in Human-Computer Interaction (HCI) The demand for intuitive user interfaces has accelerated eye tracking adoption in human-computer interaction. Eye-tracking systems enhance UX/UI responsiveness in sectors like automotive, consumer electronics, and industrial automation. In driver monitoring systems, eye tracking is increasingly deployed for fatigue detection and alertness assessment, supporting road safety. As organizations strive for hands-free, personalized digital experiences, the integration of eye tracking in AR/VR devices and smart systems continues to grow. These applications are fueling R&D and encouraging device manufacturers to integrate eye tracking across more platforms.
- For instance, Seeing Machines’ Guardian System has been deployed in over 42,000 vehicles for driver fatigue monitoring and has detected more than 16 million distraction events to date.
Growing Demand in Market Research and Advertising Analytics Eye tracking is becoming a vital tool in consumer behavior analysis, enabling brands to evaluate visual engagement with advertisements, packaging, and web content. By offering granular insight into gaze duration, fixation points, and visual attention, eye tracking helps optimize design and improve ROI on marketing campaigns. Companies are increasingly investing in this technology to refine strategies based on real user interaction data. As competition in digital advertising intensifies, eye tracking offers a scientific approach to understanding and predicting consumer attention patterns.
Key Trends & Opportunities
Adoption in Gaming and Augmented/Virtual Reality (AR/VR) The gaming and immersive technology sectors are witnessing rapid adoption of eye tracking to enhance realism and interactivity. In VR headsets, eye tracking supports foveated rendering, improving graphical performance and reducing processing load. It also enables gaze-based navigation and control, enriching gameplay and training simulations. Major players like Sony and Meta are incorporating eye tracking into next-gen devices, signaling vast opportunity. As AR/VR usage grows across education, design, and entertainment, eye tracking will serve as a foundational component for responsive user interfaces.
- For instance, HTC Vive Pro Eye, powered by Tobii, enables foveated rendering and supports gaze interaction latency of under 50 ms, improving immersion in VR environments. It also enables gaze-based navigation and control, enriching gameplay and training simulations.
Advancements in Artificial Intelligence and Eye-Tracking Software AI-powered eye-tracking software is enabling real-time data interpretation, behavioral predictions, and adaptive system responses. Machine learning algorithms are enhancing gaze mapping accuracy, pupil dilation analysis, and facial recognition integration. These improvements are expanding eye tracking's utility across security systems, accessibility tools, and psychological research. Additionally, cloud-based platforms are facilitating large-scale, remote eye tracking studies. The synergy between AI and eye tracking presents opportunities to develop smarter, more personalized digital systems across industries from automotive to e-learning.
- For instance, OpenFace 2.0, an open-source facial behavior analysis toolkit, processes synchronized eye movement and head pose data at 30 frames per second, supporting detailed behavioral modeling.
Emergence of Lightweight and Wearable Eye Tracking Devices Manufacturers are focusing on developing lightweight, ergonomic, and wireless eye tracking solutions for greater user comfort and mobility. Wearable eye trackers-especially glasses-are increasingly used in real-world environments such as retail spaces, sports training, and field research. This trend supports the demand for portable, accurate, and non-intrusive monitoring tools. With continuous innovation in miniaturized sensors and battery-efficient devices, wearables are opening new use cases previously limited to lab settings, offering vendors a broader commercial landscape.
Key Challenges
High Cost and Technical Complexity of Eye Tracking Systems Despite growing interest, the high upfront cost of eye tracking hardware and associated software remains a key barrier to adoption, particularly for small enterprises and academic institutions. Calibration requirements, environmental sensitivity, and the need for skilled professionals to analyze complex data further add to operational expenses. While prices are gradually declining with technological maturity, cost remains a limiting factor, especially in price-sensitive markets or in large-scale deployments where per-unit investment multiplies.
Privacy and Ethical Concerns Around Eye Data Eye tracking systems capture detailed information about users’ attention, intentions, and potentially emotional states. This raises serious concerns around data privacy, consent, and ethical use, especially in marketing, surveillance, and healthcare. Unauthorized data collection or misuse could lead to manipulation or profiling of individuals. Regulatory scrutiny is intensifying, and companies must ensure transparency, anonymization, and compliance with global data protection laws such as GDPR. These ethical and legal challenges may hinder broader implementation without robust safeguards.
Regional Analysis
North America In 2024, North America accounted for approximately 20.7% of the global eye tracking market, reaching a market value of USD 296.70 million, up from USD 77.11 million in 2018. The region is anticipated to grow to USD 1,440.02 million by 2032, registering a CAGR of 21.9%. Growth is driven by rising adoption of eye tracking in assistive technology, automotive driver monitoring systems, and advanced healthcare diagnostics. The U.S. leads the region due to high R&D activity and early integration in AR/VR and defense systems. North America remains a key innovation hub, contributing significantly to global technological advancements in eye tracking.
Europe Europe held a 26.0% market share in 2024 with a value of USD 372.67 million, rising from USD 94.48 million in 2018. By 2032, the market is projected to reach USD 1,872.47 million, reflecting a CAGR of 22.4%. The region benefits from strong academic research, industrial automation initiatives, and growing investments in accessibility and healthcare tech. Countries such as Germany, the UK, and France are leading adopters of eye tracking in usability research, neurological studies, and automotive systems. Regulatory support for data privacy and ethical tech deployment also fosters market growth, positioning Europe as a mature and steadily advancing region in this space.
Asia Pacific Asia Pacific emerged as the largest regional market in 2024, holding a dominant 33.3% share with a value of USD 478.39 million, up from USD 118.61 million in 2018. It is expected to surge to USD 2,475.27 million by 2032 at a CAGR of 22.9%. This growth is driven by rapid technological adoption in China, Japan, South Korea, and India, across sectors including consumer electronics, gaming, and education. Local tech firms and hardware manufacturers are increasingly integrating eye tracking in VR devices and mobile platforms. Government-backed digital learning programs and expanding clinical research also bolster regional demand.
Latin America Latin America accounted for 10.8% of the global eye tracking market in 2024, with a market size of USD 155.16 million, rising from USD 37.70 million in 2018. The market is forecast to reach USD 823.39 million by 2032, growing at a CAGR of 23.3%. Brazil and Mexico are leading the adoption curve due to their increasing investment in eye-tracking-enabled healthcare and marketing analytics. The rise of local research initiatives and digital advertising demand contributes to regional expansion. Despite infrastructural and funding limitations, the market shows strong potential with increasing integration in neuromarketing and usability testing applications.
Middle East The Middle East captured a 6.0% share of the global market in 2024, reaching USD 94.07 million from USD 22.47 million in 2018. It is projected to grow to USD 509.61 million by 2032, reflecting a robust CAGR of 23.6%-the highest among all regions. Growth is largely driven by smart healthcare programs, tech-enabled education, and adoption of AR/VR in Gulf countries. The UAE and Saudi Arabia are spearheading regional adoption through investments in AI, healthcare digitization, and surveillance systems. Though still emerging, the Middle East is showing rapid acceptance of advanced eye tracking technologies across sectors.
Africa Africa held a modest 2.8% market share in 2024 with a value of USD 39.50 million, up from USD 11.47 million in 2018. The market is projected to reach USD 159.44 million by 2032, growing at a CAGR of 19.1%, the slowest among all regions. Growth is primarily driven by pilot programs in healthcare and education across South Africa, Kenya, and Nigeria. While infrastructural and cost barriers remain, international collaborations and gradual integration of assistive technologies are helping build awareness and access. Africa remains a developing market with long-term potential, especially in medical and rehabilitation applications.
Market Segmentations:
By Product
- Hardware
- Eye-tracking Glasses
- Eye-tracking Screens/Monitors
- Software
- Analytics and Visualization Software
- Others
- Services
By Tracking Type
- Remote Eye Tracking
- Mobile Eye Tracking
By Application
- Human-Computer Interaction (HCI)
- Assistive Technology for Disabilities
- Gaming and Entertainment
- Biometric Research and Lie Detection
- Others
By Industry Vertical
- Healthcare
- Defense & Aerospace
- Media & Advertising
- Gaming & VR/AR
- Others
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The competitive landscape of the Eye Tracking market is characterized by a mix of established players and innovative startups, each contributing to technological advancements and expanding application areas. Leading companies such as Tobii AB, Seeing Machines Ltd., and EyeTech Digital Systems dominate the market with comprehensive product portfolios and strong R&D capabilities. These firms focus on strategic collaborations, product launches, and acquisitions to enhance their market presence and technological edge. For instance, Tobii AB has continued to lead in both hardware and software integration for consumer electronics and healthcare applications. Meanwhile, companies like Mirametrix Inc. and Gazepoint Research Inc. are gaining traction through cost-effective and portable solutions tailored to usability testing and academic research. Partnerships with AR/VR device manufacturers and automotive OEMs are becoming common strategies to embed eye-tracking capabilities in next-generation systems. The market remains highly innovation-driven, with competition centered on precision, latency, software compatibility, and multi-environment adaptability.
Key Player Analysis
- EyeTech Digital Systems, Inc.
- EyeTracking, Inc.
- LC Technologies, Inc.
- Mirametrix Inc.
- Tobii AB
- Sensomotoric Instruments GmbH
- Seeing Machines Ltd.
- Ergoneers GmbH
- Gazepoint Research Inc.
Recent Developments
- In June 2025, Ergoneers GmbH launched Prophea.X, a cutting-edge eye tracking and analysis platform that allows researchers to conduct multi-subject, portable eye tracking studies outside of traditional lab settings by integrating with neuro/physio sensors, providing automated AI-powered gaze analysis, scalable video observation, and compatibility with Tobii systems, effectively expanding research capabilities into real-world environments.
- In June 2024, Tobii introduced a software-only eye-tracking integration platform for webcams: Tobii Nexus. Its main advantage is easy-to-integrate devices and compatibility with applications such as education, ASD, ADHD, digital collaboration, and VR to better interact with diverse demographics.
- In May 2024, Apple unveiled Eye Tracking for iPad and iPhone, which enables individuals with physical disabilities to control devices with their eyes. The technology is powered by AI and offers on-device security, so there's no need for external hardware.
- In March 2024, Chinese smartphone goliath Honor Chinese smartphone goliath Honor launched an AI vision tracking option called 'Magic Capsule,' enabling customers to control their smartphones by glancing at the screen. The technology can differentiate between an intentional look and accidental one, enabling the phone to act without any requirement for touch.
- In February 2024, Lumen Research received a patent for its eye-tracing data collection platform, allowing it to attain points of interest on web pages through webcams on both desktop and mobile.
- In January 2024, Seeing Machines unveiled its Guardian Gen 3 at CES 2024, featuring advanced microsleep detection and eye-gaze tracking to prevent distracted driving. The new system meets the EU General Safety Regulation for Drowsiness Detection.
- In August 2022, EyeTech Digital Systems launched the EyeOn Open Eye-Tracking Platform with the OnBright suite, specifically designed for the AAC (augmentative and alternative communication) community. This platform is intended for end-users, medical application developers, and researchers, offering seamless integration and AI-powered adaptive calibration for customized user experiences.
Market Concentration & Characteristics
The Eye Tracking Market demonstrates a moderately concentrated structure, with a few key players such as Tobii AB, Seeing Machines Ltd., and EyeTech Digital Systems holding significant market shares due to their technological expertise and diversified product portfolios. It features strong entry barriers driven by high development costs, complex hardware-software integration, and proprietary technologies. The market benefits from sustained demand across healthcare, automotive, and consumer electronics sectors, encouraging investment in research and product innovation. It also shows high growth potential in emerging regions, particularly Asia Pacific, where demand for smart interfaces and wearable devices is increasing. Competitive dynamics focus on accuracy, latency, and adaptability to varied environments, which influence vendor differentiation. Intellectual property and strategic partnerships play a central role in maintaining competitive advantage.
Report Coverage
The research report offers an in-depth analysis based on Product, Tracking Type, Application, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue expanding rapidly due to growing demand in healthcare diagnostics and assistive communication technologies.
- Eye tracking will play a critical role in enhancing user interfaces in AR and VR systems across consumer and enterprise applications.
- Automotive manufacturers will increasingly adopt eye tracking for driver monitoring and in-cabin safety systems.
- Integration with AI and machine learning will improve real-time gaze analytics and predictive user behavior models.
- Advancements in miniaturization will lead to more lightweight and comfortable wearable eye tracking devices.
- Education and e-learning platforms will use eye tracking to assess student engagement and optimize content delivery.
- Marketing and advertising firms will expand use of eye tracking for consumer attention analysis and campaign optimization.
- Medical research institutions will deploy eye tracking in cognitive and neurological assessments with greater frequency.
- Demand will rise for cloud-based eye tracking software to support remote research and scalable analytics.
- Ethical standards and data privacy regulations will shape the development and deployment of eye tracking technologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration in Healthcare and Assistive Technologies
Eye tracking is increasingly used in neurological diagnostics and assistive communication tools for patients with motor disabilities, enabling non-verbal patients to interact with devices and aiding early detection of cognitive conditions. This drives demand for precision eye-tracking hardware and software in medical settings.
Expansion in Human-Computer Interaction (HCI)
Rising investments in AI-driven interfaces and accessible technology are accelerating adoption of eye tracking in consumer electronics, automotive, and industrial automation, enhancing user experience through intuitive, hands-free control systems.
Growth in Automotive Driver Monitoring Systems
Automotive manufacturers are integrating eye tracking for driver fatigue and distraction detection, supporting regulatory compliance and road safety initiatives. This is fueling adoption in both commercial and passenger vehicles.
Adoption in Gaming and AR/VR
Eye tracking is being embedded in gaming and immersive technology platforms to enable foveated rendering, gaze-based navigation, and enhanced interactivity, driving demand from both consumer and enterprise sectors.
Use in Market Research and Advertising Analytics
Brands and agencies are leveraging eye tracking to analyze consumer attention and engagement with advertisements, packaging, and digital content, providing actionable insights that optimize marketing strategies and improve ROI.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Eye Tracking Market?
What factors are driving the growth of the Eye Tracking Market?
What are the key segments within the Eye Tracking Market?
What are some challenges faced by the Eye Tracking Market?
Q: Who are the major players in the Eye Tracking Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Application
- 1.3.1 Human-Computer Interaction (HCI)
- 1.3.2 Assistive Technology for Disabilities
- 1.3.3 Gaming and Entertainment
- 1.3.4 Biometric Research and Lie Detection
- 1.3.5 Others
- 1.4 By Tracking Type
- 1.4.1 Remote Eye Tracking
- 1.4.2 Mobile Eye Tracking
- 1.5 By Industry Vertical
- 1.5.1 Healthcare
- 1.5.2 Defense & Aerospace
- 1.5.3 Media & Advertising
- 1.5.4 Gaming & VR/AR
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,436.5 million → 2032: USD 7,280.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Eye Tracking Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Eye Tracking Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Eye Tracking Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Eye Tracking Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Eye Tracking Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Eye Tracking Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Eye Tracking Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Eye Tracking Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,436.5 million → 2032: USD 7,280.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Eye Tracking Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Human-Computer Interaction (HCI)
- 12.4.7.2 Assistive Technology for Disabilities
- 12.4.7.3 Gaming and Entertainment
- 12.4.7.4 Biometric Research and Lie Detection
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Tracking Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Remote Eye Tracking
- 12.5.7.2 Mobile Eye Tracking
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Healthcare
- 12.6.7.2 Defense & Aerospace
- 12.6.7.3 Media & Advertising
- 12.6.7.4 Gaming & VR/AR
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Eye Tracking End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Eye Tracking Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Eye Tracking Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Eye Tracking Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tobii AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Seeing Machines Ltd.
- 18.4 EyeTech Digital Systems, Inc.
- 18.5 EyeTracking, Inc.
- 18.6 LC Technologies, Inc.
- 18.7 Gazepoint Research Inc.
- 18.8 Mirametrix Inc.
- 18.9 Sensomotoric Instruments GmbH
- 18.10 Ergoneers GmbH
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

