
Market Overview
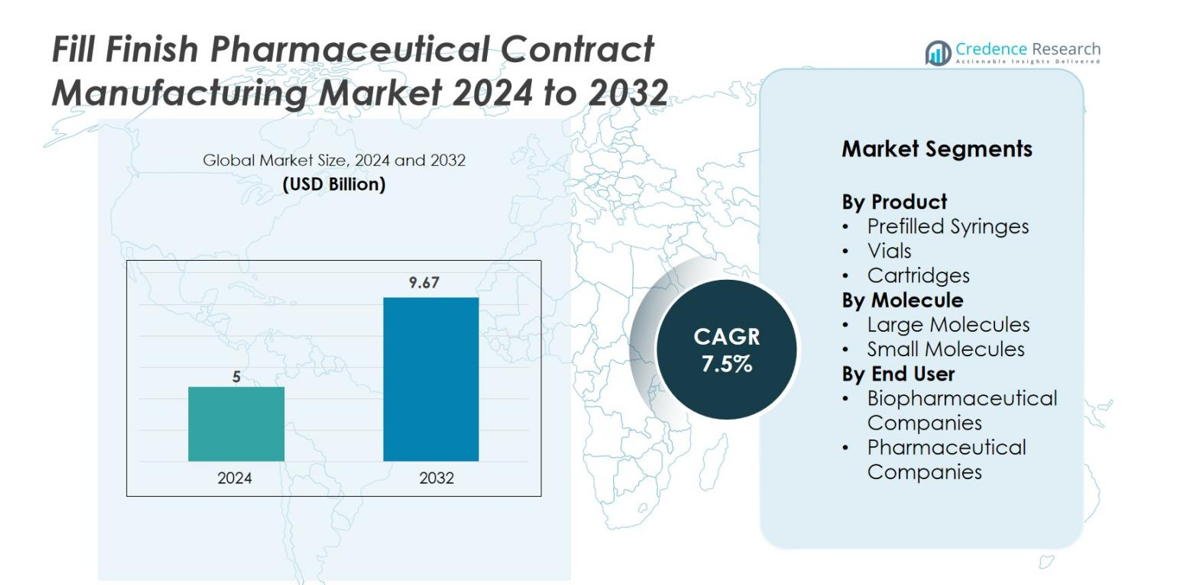
The Fill-Finish Pharmaceutical Contract Manufacturing market size was valued at USD 5 billion in 2024 and is anticipated to reach USD 9.67 billion by 2032, at a CAGR of 7.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fill Finish Pharmaceutical Contract Manufacturing Market Size 2024 | USD 5 billion |
| Fill Finish Pharmaceutical Contract Manufacturing Market, CAGR | 7.5% |
| Fill Finish Pharmaceutical Contract Manufacturing Market Size 2032 | USD 9.67 billion |
The Fill-Finish Pharmaceutical Contract Manufacturing market is driven by the strong presence of leading global CMOs that offer advanced sterile production capabilities and large-scale capacity. Key players include Thermo Fisher Scientific Inc., Catalent Inc., Baxter, Recipharm AB, Sartorius AG, Eurofins Scientific, Boehringer Ingelheim International GmbH, Symbiosis Pharmaceutical Services, MabPlex International, and Societal CDMO. These companies specialize in high-precision aseptic processing, automated fill-finish systems, and support for both biologics and small-molecule injectables. Regionally, North America leads the market with approximately 38–40% share, driven by its advanced biopharmaceutical ecosystem, followed by Europe with around 30–32% due to its strong regulatory environment and established contract manufacturing infrastructure.
Market Insights
- The fill-finish pharmaceutical contract manufacturing market was valued at USD 5 billion in 2024 and is projected to reach USD 9.67 billion by 2032, expanding at a CAGR of 7.5% during the forecast period.
- Market growth is driven by rising demand for biologics, injectable therapies, and sterile manufacturing outsourcing, as companies seek specialized capabilities, cost efficiency, and faster commercialization support.
- Key trends include increasing adoption of automation, isolator technology, flexible single-use systems, and growing preference for advanced packaging formats such as prefilled syringes and cartridges, with vials holding the largest product share at about 53%.
- Competition intensifies as major players-Thermo Fisher Scientific, Catalent, Recipharm, Baxter, and Eurofins Scientific-expand capacity, enhance aseptic capabilities, and pursue strategic partnerships to strengthen service portfolios.
- Regionally, North America leads with around 38–40% share, followed by Europe at 30–32%, while Asia-Pacific grows rapidly with 22–24%, supported by expanding biologics manufacturing and cost-effective contract services.
Market Segmentation Analysis
By Product
In the product segment of the fill-finish pharmaceutical contract manufacturing market, the vials sub-segment holds the dominant position with a share of 53.4% in 2024. This leadership is driven by the versatility and widespread adoption of vials for both large-molecule and small-molecule injectable formulations, particularly in biologics and vaccines. Contract manufacturers continue to expand high-capacity vial fill-finish lines, supported by stringent sterility requirements and growing demand for scalable packaging formats, which collectively reinforce the strong market position of vial-based fill-finish operations.
- For instance, Syntegon Technology GmbH has installed more than 1,500 vial-filling and closing machines globally to support large-scale production of critical injectable therapies.
By Molecule
Under the molecule classification, the large molecules sub-segment dominates with 67% market share in 2024. This prominence reflects the rapid expansion of biologics, monoclonal antibodies and other complex therapies that require advanced fill-finish capabilities. Growth is further supported by rising chronic disease prevalence, an increasing number of biologic approvals, and the shift toward outsourcing to specialized contract manufacturers. These providers offer sophisticated sterile processing, containment and quality assurance systems, enabling efficient production of large-molecule therapeutics and sustaining their dominant share.
- For instance, the CDMO Catalent, Inc. reported delivering over 70 billion doses across its biologics manufacturing and fill/finish services and managing ~1,400 active development programmes globally.
By End-User
Within the end-user category, biopharmaceutical companies represent the leading sub-segment, accounting for 55.3% of market revenue in 2024. Their dominance is driven by the extensive reliance on outsourced fill-finish services for biologics, cell-based therapies and personalized medicines. These companies increasingly partner with contract manufacturers to access flexible capacity, specialized sterile handling and regulatory-compliant environments. The need to accelerate time-to-market and reduce operational costs further strengthens the preference for outsourcing, ensuring that biopharmaceutical companies remain the primary users of fill-finish contract manufacturing services.
Key Growth Drivers
Rising Demand for Biologics and Injectable Therapies
The increasing adoption of biologics, monoclonal antibodies, and vaccines is significantly boosting demand for fill-finish contract manufacturing. Injectable therapies require strict sterility, precision filling, and advanced containment technologies, prompting companies to rely on specialized CMOs. Growth in chronic diseases and personalized medicine further drives the need for high-quality injectable production. As biologics pipelines expand, manufacturers seek external partners with sophisticated aseptic capabilities, solid quality systems, and scalable capacity, making biologics demand a major industry growth catalyst.
- For instance, Grand River Aseptic Manufacturing (GRAM) partnered with Johnson & Johnson to provide fill-finish services for their COVID-19 vaccine candidate, aiming to produce 100 million doses for the U.S. government.
Increased Outsourcing to Reduce Costs and Enhance Efficiency
Pharmaceutical and biopharmaceutical companies are rapidly outsourcing fill-finish operations to reduce capital expenditure and accelerate development timelines. Establishing aseptic facilities requires substantial investment in equipment, compliance, and skilled labor, making outsourcing an attractive alternative. CMOs provide flexible capacity, validated processes, and regulatory expertise, enabling faster scale-up and improved operational efficiency. Small biotech firms, in particular, rely heavily on CMOs due to limited in-house capabilities. This shift toward outsourcing continues to strengthen market expansion.
- For instance, Grand River Aseptic Manufacturing (GRAM) expanded its footprint by adding a 61,500 square-foot fill/finish facility in 2020 (tripling its production space to over 100,000 sq ft) to support client outsourcing of injectable drug manufacturing.
Technological Advancements and Capacity Expansion
Continuous advancements in automation, robotics, isolator systems, and digital process monitoring are enhancing precision and sterility in fill-finish manufacturing. CMOs are expanding production capacity, upgrading legacy lines, and adopting modern equipment to support growing demand for sterile injectable products. These improvements enable greater batch flexibility, accuracy, and quality assurance. As global demand for vaccines and biologics increases, investment in advanced technology and larger facilities supports higher throughput, making innovation and capacity growth major industry drivers.
Key Trends & Opportunities
Adoption of Flexible and Single-Use Technologies
The shift toward flexible and single-use technologies is transforming fill-finish operations by enabling faster changeovers, reduced cleaning requirements, and lower contamination risks. Single-use systems suit multi-product facilities managing diverse biologics and small-batch runs. Their use supports agility in clinical manufacturing and personalized medicine. CMOs adopting modular, flexible platforms can handle vials, syringes, and cartridges with ease, improving turnaround times and operational efficiency. This trend presents strong opportunities for providers offering adaptable, contamination-controlled fill-finish solutions.
- For instance, Merck Millipore’s Mobius® single-use final-fill assemblies demonstrated a reduction in campaign fill time from 36 hours to 12 hours, while achieving fill speeds of 10,000 units per hour in their single-use configuration
Expanding Demand for Advanced Packaging and Lyophilization
Demand for prefilled syringes, cartridges, and freeze-dried products is growing as biologics increasingly require enhanced stability and patient-friendly delivery formats. CMOs are expanding lyophilization capacity and investing in controlled nucleation and automated loading systems to improve quality and consistency. Advanced packaging formats support accurate dosing and safety, driving their adoption. As regulatory expectations evolve and drug pipelines diversify, opportunities rise for CMOs offering specialized packaging, serialization, and robust lyophilization services.
- For instance, Lyophilization Services of New England (LSNE), now part of PCI Pharma Services, operates 18 commercial-scale lyophilizers across its facilities and recently added a 30 m² large-scale lyophilizer, enabling significantly higher batch throughput for biologics and high-value injectables.
Key Challenges
High Capital Requirements and Technical Complexity
Fill-finish manufacturing requires significant investment in sterile equipment, isolators, cleanrooms, and automation systems. Maintaining aseptic compliance also demands ongoing validation, monitoring, and skilled staff, creating high operational costs. Biologics and complex injectables add further technical challenges, requiring advanced containment and strict environmental controls. Smaller CMOs often struggle to meet these demands, limiting industry participation. These high financial and technical barriers remain a major challenge for scaling and sustaining fill-finish capabilities.
Supply Chain Vulnerabilities and Capacity Limitations
Supply chain disruptions involving sterile components, single-use systems, and packaging materials pose ongoing challenges for fill-finish manufacturers. Limited availability of critical items can delay production and raise costs. Simultaneously, demand for injectable biologics often exceeds global fill-finish capacity, leading to long lead times and resource constraints. Smaller companies may struggle to secure manufacturing slots within high-demand CMOs. Managing capacity allocation and reducing dependency on fragile supply networks remain key industry obstacles.
Regional Analysis
North America
North America holds the largest share of the fill-finish pharmaceutical contract manufacturing market, accounting for 40% of global revenue. The region benefits from strong biologics pipelines, advanced manufacturing infrastructure, and the presence of leading CMOs with high-capacity sterile facilities. Increased outsourcing by major biopharmaceutical companies, combined with strict regulatory standards that encourage high-quality fill-finish processes, supports sustained growth. Rising demand for injectable therapies, continued investment in automation, and expansion of vaccine production capabilities further strengthen North America’s dominant regional position.
Europe
Europe represents 32% of the global fill-finish pharmaceutical contract manufacturing market, driven by its robust pharmaceutical base, strong regulatory framework, and extensive network of contract manufacturers. Countries such as Germany, Switzerland, and the UK are major hubs for sterile injectable production and biologics development. The region’s emphasis on high-quality aseptic standards and technological innovation supports continued growth. Increased demand for biologics, biosimilars, and advanced delivery formats also contributes to market expansion. Ongoing capacity upgrades and strategic partnerships with global drug developers reinforce Europe’s significant regional share.
Asia-Pacific
Asia-Pacific holds 24% of the market and is the fastest-growing region due to rising pharmaceutical production, expanding biologics manufacturing, and increasing outsourcing from Western companies seeking cost-effective solutions. China, India, South Korea, and Singapore are emerging hubs for sterile fill-finish services, supported by rapid facility modernization and government incentives. Growing demand for vaccines, biosimilars, and injectable generics drives capacity expansion. The region’s improving regulatory environment, skilled workforce, and competitive pricing continue to attract major global players, positioning Asia-Pacific as a rapidly expanding contributor to market growth.
Latin America
Latin America accounts for 5% of the global fill-finish pharmaceutical contract manufacturing market. While smaller in scale, the region is experiencing steady growth driven by expanding healthcare investments, rising demand for injectable drugs, and improved pharmaceutical manufacturing capabilities. Brazil and Mexico lead the market with growing contract manufacturing activities and increasing partnerships with global firms. Upgrades in sterile processing infrastructure and a shift toward outsourcing among local drug manufacturers support regional development. However, regulatory variations and limited high-end capabilities continue to moderate overall market expansion.
Middle East & Africa
The Middle East & Africa region holds 4% of the fill-finish pharmaceutical contract manufacturing market, with growth supported by strengthening healthcare systems and rising investment in local pharmaceutical production. Countries such as Saudi Arabia, the UAE, and South Africa are increasing focus on sterile manufacturing to reduce dependency on imports. Demand for vaccines and essential injectable therapies continues to rise, prompting gradual expansion of fill-finish capabilities. Despite ongoing improvements, market growth is moderated by limited technological infrastructure and reliance on external CMOs for complex biologics and specialty injectables.
Market Segmentations
By Product
- Prefilled Syringes
- Vials
- Cartridges
By Molecule
- Large Molecules
- Small Molecules
By End User
- Biopharmaceutical Companies
- Pharmaceutical Companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the fill-finish pharmaceutical contract manufacturing market is characterized by the presence of global CMOs with extensive sterile manufacturing capabilities and a growing number of regional specialists expanding their service portfolios. Leading companies such as Thermo Fisher Scientific Inc., Catalent Inc., Baxter, Recipharm AB, Sartorius AG, Eurofins Scientific, Boehringer Ingelheim International GmbH, Symbiosis Pharmaceutical Services, MabPlex International, and Societal CDMO play a prominent role in shaping market dynamics. These players compete through investments in high-throughput fill-finish lines, advanced isolator technology, and automation to ensure sterility and scalability for complex biologics and injectable therapies. Strategic collaborations, capacity expansions, and acquisitions are frequently employed to strengthen geographic presence and enhance technical capabilities. As demand for biologics, vaccines, and specialized delivery formats increases, competition intensifies around quality compliance, turnaround times, and the ability to support both clinical and commercial manufacturing needs.
Key Player Analysis
- Eurofins Scientific
- MabPlex International Co. Ltd.
- Baxter
- Symbiosis Pharmaceutical Services Ltd
- Sartorius AG
- Recipharm AB
- Catalent, Inc (acquired by Novo Holdings A/S)
- Boehringer Ingelheim International GmbH
- Societal CDMO (Recro Pharma, Inc)
- Thermo Fisher Scientific Inc.
Recent Developments
- In October 2025, Jubilant HollisterStier LLC (a subsidiary of Jubilant Pharmova Limited) launched its third sterile fill-&-finish line at its Spokane (Washington, US) facility, adding approximately 50% additional capacity and integrating advanced isolator technology for complex injectable products.
- In November 2024, Lonza announced the completion of its first GMP batch at the Portsmouth facility, advancing capacity for small- to mid-scale mammalian biologics and strengthening support for diverse molecule types.
- In May 2024, Eurofins CDMO Alphora Inc. announced a three-fold expansion of its Drug Product Analytical Services Laboratory in Mississauga, Canada, significantly enhancing its analytical and development capabilities.
Report Coverage
The research report offers an in-depth analysis based on Product, Molecule, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand as demand for biologics, vaccines, and injectable therapies rises globally.
- Outsourcing of sterile fill-finish operations will increase as pharmaceutical companies prioritize cost efficiency and faster time-to-market.
- Automation, robotics, and isolator-based technologies will become standard across advanced fill-finish facilities.
- Single-use and flexible manufacturing systems will gain wider adoption to support multi-product, small-batch, and personalized therapy production.
- Lyophilization capacity will expand to meet growing stability requirements for complex biologic formulations.
- Prefilled syringes and advanced delivery formats will see strong uptake, reshaping packaging preferences.
- Contract manufacturers will invest heavily in capacity expansion to address global shortages in sterile manufacturing.
- Regulatory expectations for sterility, traceability, and contamination control will continue to tighten.
- Strategic partnerships between biopharma companies and CMOs will grow to secure long-term production capacity.
- Asia-Pacific will emerge as a critical growth engine due to expanding biologics manufacturing and competitive service offerings.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Biologics and Injectable Therapies
The rapid growth of biologics, monoclonal antibodies, and vaccines is driving demand for advanced fill-finish contract manufacturing, as these products require stringent sterility and specialized handling that many pharmaceutical companies prefer to outsource.
Increased Outsourcing for Cost and Efficiency
Pharmaceutical and biopharmaceutical companies are increasingly outsourcing fill-finish operations to contract manufacturers to reduce capital investment, accelerate development timelines, and access specialized expertise, fueling market growth.
Technological Advancements in Fill-Finish Operations
Continuous innovation in automation, robotics, isolator technology, and single-use systems is enhancing precision, sterility, and scalability in fill-finish manufacturing, making contract services more attractive and efficient.
Rising Demand for Advanced Packaging and Lyophilization
The shift toward prefilled syringes, cartridges, and lyophilized products to improve drug stability and patient convenience is prompting CMOs to expand capabilities in advanced packaging and freeze-drying, supporting market expansion.
Capacity Expansion and Strategic Partnerships
Leading CMOs are investing in new facilities, expanding production lines, and forming strategic partnerships with biopharma companies to meet rising global demand and secure long-term manufacturing contracts, further propelling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Fill Finish Pharmaceutical Contract Manufacturing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fill Finish Pharmaceutical Contract Manufacturing Market projected to grow between 2025 and 2032?
Who are the major players in the global fill finish pharmaceutical contract manufacturing market?
What are the major market drivers of the fill finish pharmaceutical contract manufacturing industry?
What are the major market restraints of the fill finish pharmaceutical contract manufacturing industry?
What are the major market opportunities of the fill finish pharmaceutical contract manufacturing industry?
Who are the leading companies in the Fill Finish Pharmaceutical Contract Manufacturing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Vials
- 1.2.2 Prefilled Syringes
- 1.2.3 Cartridges
- 1.3 By End User
- 1.3.1 Biopharmaceutical Companies
- 1.3.2 Pharmaceutical Companies
- 1.4 By Molecule
- 1.4.1 Large Molecules
- 1.4.2 Small Molecules
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5 billion → 2032: USD 9.67 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fill Finish Pharmaceutical Contract Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fill Finish Pharmaceutical Contract Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fill Finish Pharmaceutical Contract Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fill Finish Pharmaceutical Contract Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fill Finish Pharmaceutical Contract Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fill Finish Pharmaceutical Contract Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fill Finish Pharmaceutical Contract Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fill Finish Pharmaceutical Contract Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5 billion → 2032: USD 9.67 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fill Finish Pharmaceutical Contract Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vials
- 12.3.7.2 Prefilled Syringes
- 12.3.7.3 Cartridges
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Biopharmaceutical Companies
- 12.4.7.2 Pharmaceutical Companies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Molecule - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Molecules
- 12.5.7.2 Small Molecules
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fill Finish Pharmaceutical Contract Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fill Finish Pharmaceutical Contract Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fill Finish Pharmaceutical Contract Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fill Finish Pharmaceutical Contract Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Catalent Inc.
- 18.4 Baxter
- 18.5 Recipharm AB
- 18.6 Sartorius AG
- 18.7 Eurofins Scientific
- 18.8 Boehringer Ingelheim International GmbH
- 18.9 Symbiosis Pharmaceutical Services
- 18.10 MabPlex International
- 18.11 Societal CDMO
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

