
Market Overview
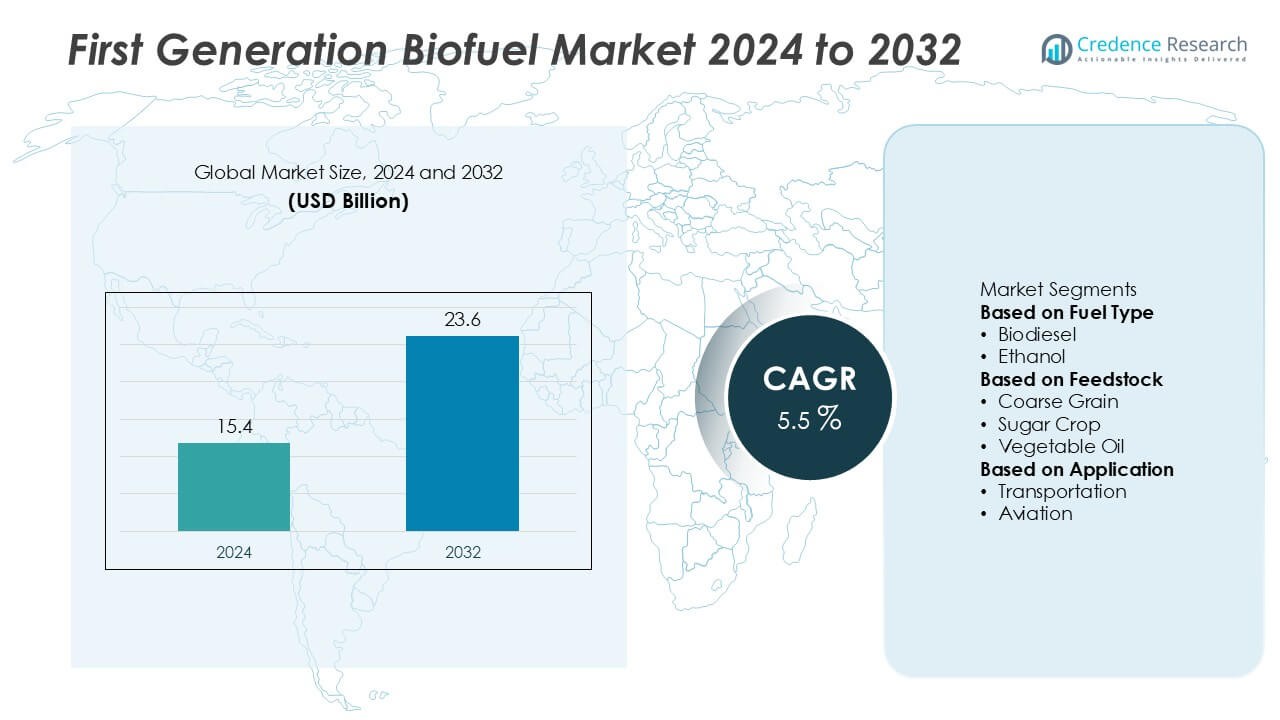
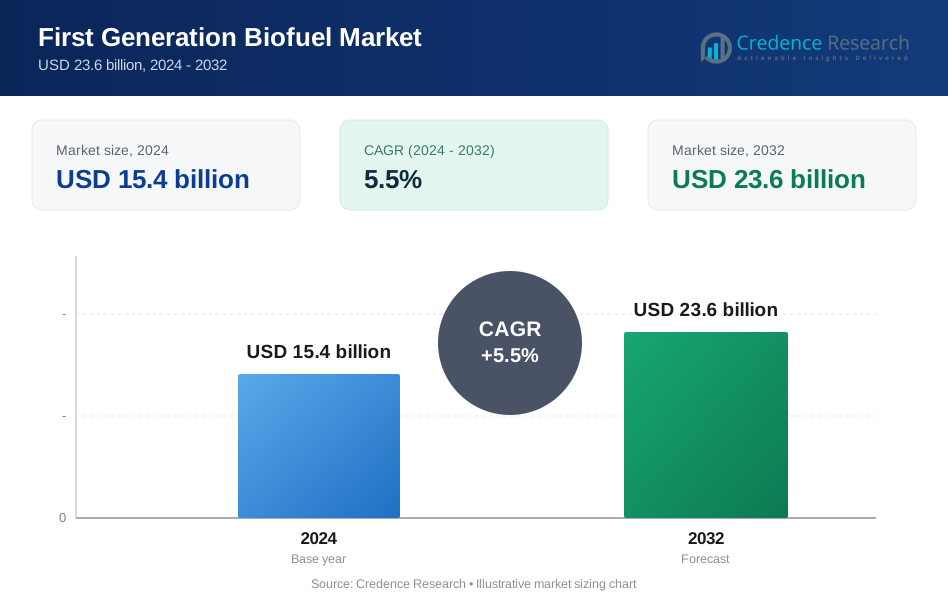
First Generation Biofuel Market size was valued at USD 15.4 billion in 2024 and is projected to reach USD 23.6 billion by 2032, growing at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| First Generation Biofuel Market Size 2024 | USD 15.4 Billion |
| First Generation Biofuel Market, CAGR | 5.5% |
| First Generation Biofuel Market Size 2032 | USD 23.6 Billion |
The First Generation Biofuel Market is driven by rising global energy demand, government blending mandates, and the push for reduced carbon emissions, supported by established feedstock supply chains such as corn, sugarcane, and vegetable oils.
The geographical landscape of the First Generation Biofuel Market reflects strong adoption across North America, Europe, Asia Pacific, Latin America, and parts of the Middle East and Africa, each influenced by policy frameworks, feedstock availability, and infrastructure development. North America demonstrates leadership through established ethanol and biodiesel production, supported by abundant corn and soybean supplies and stringent renewable fuel standards. Europe emphasizes biodiesel production using rapeseed oil, with regulatory support under the Renewable Energy Directive. Asia Pacific shows rapid growth, driven by expanding mandates in India, China, and Indonesia, supported by sugarcane and rice-based feedstocks. Latin America, led by Brazil, leverages its sugarcane industry and advanced flex-fuel vehicle adoption. Emerging regions in Africa and the Middle East explore early-stage programs but face challenges with supply consistency. Key players shaping the competitive dynamics include Chevron, DuPont, Green Plains, and Future Fuel, who combine technological innovation, policy alignment, and strong distribution networks to strengthen their positions globally.
Market Insights
- The First Generation Biofuel Market was valued at USD 15.4 billion in 2024 and is projected to reach USD 23.6 billion by 2032, growing at a CAGR of 5.5% during the forecast period.
- Growing energy demand, rising concerns about fossil fuel dependency, and supportive government mandates for blending biofuels with conventional fuels act as strong drivers for market expansion.
- Key trends include increasing adoption of ethanol and biodiesel in the transportation sector, integration into aviation and marine fuels, and expanding agricultural feedstock cultivation supported by advanced farming techniques.
- The competitive landscape features leading players such as Biogreen Synergy, Blue Son, Borregard, Caterpillar, Chevron, Coasan, DuPont, Future Fuel, Green Plains, and Montuk Renewables, who compete through research, technological improvements, and strategic partnerships.
- Market restraints include the food-versus-fuel debate, rising agricultural input costs, and competition from advanced biofuels derived from non-food feedstocks, which pose long-term sustainability concerns.
- Regional dynamics show North America leading with strong ethanol and biodiesel production, Europe focusing on rapeseed-based biodiesel, Asia Pacific experiencing rapid growth with mandates in India and China, Latin America led by Brazil’s sugarcane ethanol industry, and emerging interest from Africa and the Middle East.
- Overall, the market demonstrates steady growth opportunities supported by policy frameworks, technological innovation, and rising environmental awareness, while balancing challenges around feedstock dependency, cost efficiency, and evolving global energy transitions.
Market Drivers
Rising Global Energy Demand and Shift Toward Renewable Alternatives
The First Generation Biofuel Market benefits from the increasing global demand for sustainable energy sources. Growing concerns about depleting fossil fuels and volatile crude oil prices encourage industries and governments to seek renewable alternatives. Biofuels derived from food-based feedstocks such as sugarcane, corn, and vegetable oils serve as a practical option due to established supply chains and proven production technologies. It supports energy diversification and strengthens energy security in regions heavily dependent on oil imports. The drive toward lowering carbon emissions in transport and power generation further enhances its adoption. These factors collectively establish biofuels as a vital component in the global energy mix.
- For instance, DuPont commissioned a cellulosic ethanol facility in Nevada, Iowa, with a processing capacity of 30 million gallons per year, using corn stover as the primary feedstock. However, the plant was a financial failure and was shuttered by DowDuPont in 2017.
Supportive Government Policies and Subsidy Programs
Policy frameworks and subsidies play a central role in expanding the First Generation Biofuel Market. Many governments mandate blending biofuels with conventional fuels to reduce greenhouse gas emissions and promote cleaner energy. Tax incentives, financial support, and regulatory backing help producers maintain cost competitiveness. It enables smaller producers to enter the market while allowing larger players to scale operations effectively. Programs encouraging farmers to grow biofuel feedstocks stimulate agricultural demand and rural development. This regulatory push remains a critical growth driver for the industry.
- For instance, In Q3 2025, Green Plains continued advancing its Trailblazer carbon capture project, which is designed to sequester approximately 800,000 tons of biogenic CO₂ annually. This regulatory push, supported by U.S. programs like the 45Z Clean Fuel Production Credit, remains a critical growth driver for the industry.
Technological Advancements in Biofuel Production Processes
Continuous improvements in production efficiency drive the First Generation Biofuel Market forward. Upgrades in fermentation, refining, and conversion technologies help reduce costs and improve yield. It allows producers to compete with conventional fuels while meeting rising demand. Advancements also enhance the ability to integrate biofuel production with existing infrastructure, supporting quicker adoption in transport and energy sectors. The shift toward more energy-efficient processes also strengthens environmental benefits. These developments create a foundation for sustainable growth in the market.
Growing Awareness of Environmental and Economic Benefits
Public awareness of climate change and its economic impact influences the growth of the First Generation Biofuel Market. Consumers and industries increasingly favor cleaner alternatives that reduce carbon footprints. It supports the reduction of greenhouse gas emissions while stimulating domestic agriculture and rural economies. Using biofuels also helps nations reduce dependency on fossil fuel imports, lowering exposure to market volatility. Environmental groups and advocacy organizations further strengthen awareness and adoption rates. This growing recognition of economic and environmental advantages reinforces long-term market expansion.
Market Trends
Increasing Adoption of Biofuel Blending Mandates Across Key Regions
Governments in both developed and developing economies strengthen regulations that require blending biofuels with conventional fuels. The First Generation Biofuel Market gains traction as countries set ambitious blending targets to curb emissions and enhance fuel security. It enables a steady demand for ethanol and biodiesel in transportation sectors, particularly in road transport. Blending policies also create a structured demand that supports consistent revenue streams for producers. Emerging economies in Asia and Latin America expand adoption due to growing vehicle fleets. This trend ensures a stable long-term market outlook.
- For instance, in August 2025, Montauk Renewables and Emvolon launched a joint venture to convert biogas into green methanol, targeting 50,000 metric tonnes of output annually by 2030, with initial production capacity of 6,000 metric tonnes per year. Emerging economies in Asia and Latin America expand adoption due to growing vehicle fleets.
Expansion of Feedstock Cultivation and Supply Chain Networks
The expansion of agricultural activities for crops such as corn, sugarcane, and oilseeds supports the First Generation Biofuel Market. Producers invest in strengthening supply chain logistics to ensure consistent feedstock availability. It reduces production bottlenecks and stabilizes biofuel pricing in competitive energy markets. Farmers benefit from higher demand, creating new income streams while securing crop utilization. The integration of advanced farming techniques further improves crop yields, enhancing feedstock supply. This shift in agricultural dynamics directly supports biofuel production growth.
- For instance, DuPont partnered with New Tianlong Industry to license its cellulosic ethanol technology, contributing to the development of China's largest bioethanol facility based on corn stover. While such advancements aim to improve production and can support long-term biofuel market growth, the specific claim that this single development reduces production bottlenecks and stabilizes biofuel pricing in competitive energy markets is an overstatement.
Integration of Biofuels into Aviation and Marine Transportation Sectors
Broader integration of biofuels into aviation and shipping creates new opportunities for the First Generation Biofuel Market. Airlines explore bio-based fuel options to comply with international emission reduction frameworks. It positions biofuels as a practical near-term alternative to fossil fuels in heavy transport sectors. Shipping companies also test biofuel blends to meet stricter global emission regulations. Partnerships between fuel producers and transport operators accelerate commercial adoption. This trend reflects growing acceptance of biofuels beyond traditional road transport.
Investments in Research for Cost Efficiency and Yield Optimization
Research and development activities continue to reshape the First Generation Biofuel Market. Companies allocate significant resources to improving fermentation efficiency and reducing production costs. It enhances the competitiveness of biofuels against petroleum-based fuels. Pilot projects test new methods of maximizing output while minimizing waste. Governments and private investors support these innovations to secure long-term market viability. This sustained research focus ensures that first generation biofuels remain relevant in the evolving energy landscape.
Market Challenges Analysis
Food Versus Fuel Debate and Agricultural Resource Constraints
The First Generation Biofuel Market faces criticism due to its dependence on food-based feedstocks such as corn, sugarcane, and vegetable oils. Large-scale diversion of these crops toward fuel production raises concerns about food security and rising commodity prices. It places pressure on farmland, water resources, and fertilizer use, often leading to environmental degradation. Policymakers and advocacy groups highlight the ethical dilemma of prioritizing fuel over food in regions facing nutritional challenges. Rising agricultural input costs also create uncertainty for producers who rely heavily on stable supply chains. This conflict between energy needs and food availability remains a major challenge for sustained market growth.
High Production Costs and Competition from Advanced Biofuels
Another significant challenge for the First Generation Biofuel Market lies in cost competitiveness. Production expenses remain high due to feedstock prices, energy-intensive processes, and limited scalability. It struggles to compete with fossil fuels when crude oil prices remain low, reducing incentives for large-scale adoption. The emergence of second and third-generation biofuels also threatens its long-term relevance. Advanced biofuels derived from non-food sources offer better environmental performance and lower competition with agriculture. Investors and policymakers increasingly shift focus toward these alternatives, creating pressure on first generation biofuel producers to remain viable. This cost and technology challenge continues to shape the industry’s uncertain outlook.
Market Opportunities
Rising Demand in Emerging Economies and Expanding Transportation Needs
The First Generation Biofuel Market holds significant opportunities in emerging economies with rapidly growing transportation sectors. Expanding urbanization and rising vehicle ownership increase the demand for fuel alternatives that reduce reliance on imports. It positions biofuels as a practical solution to meet energy needs while supporting national sustainability goals. Governments in Asia, Africa, and Latin America implement blending targets and incentivize local production to reduce dependence on fossil fuels. This trend creates new growth corridors for producers willing to invest in regional supply chains. The ability to serve both energy security and environmental objectives strengthens its future market potential.
Strategic Collaborations and Investments in Infrastructure Development
Growing partnerships between governments, fuel producers, and agricultural stakeholders create fresh opportunities for the First Generation Biofuel Market. Infrastructure investments in blending facilities, storage, and distribution networks improve efficiency and accessibility. It enables smoother integration of biofuels into existing energy systems and expands availability across new markets. Collaborative projects with transport operators and refiners also accelerate commercial adoption on a larger scale. Financial institutions and investors see potential in supporting these initiatives, given the rising focus on renewable energy portfolios. These strategic efforts open pathways for expanding market reach and ensuring steady demand growth.
Market Segmentation Analysis:
By Fuel Type
The First Generation Biofuel Market is segmented into ethanol and biodiesel, both playing a central role in global energy diversification. Ethanol dominates the segment due to its widespread use in transportation, supported by strong government mandates for blending with gasoline. It benefits from established production processes using sugarcane and corn, making it cost-efficient in many regions. Biodiesel also holds a significant share, driven by demand in commercial vehicles and agricultural machinery. Its compatibility with existing diesel engines without major modifications makes it an attractive option for markets with high diesel consumption. Both fuel types continue to expand adoption as nations strengthen commitments to reduce greenhouse gas emissions.
- For instance, Green Plains operated its ethanol production facilities at 99% capacity utilization, optimizing fermentation efficiency through data-driven process improvements.
By Feedstock
Feedstock plays a critical role in shaping the dynamics of the First Generation Biofuel Market. Corn and sugarcane remain leading sources for ethanol production due to their high starch and sugar content. It allows efficient conversion into biofuels, particularly in countries like the United States and Brazil, where supply chains are well established. Vegetable oils and animal fats form the primary feedstocks for biodiesel production, widely used in Europe and Asia. Growing concerns about food security and environmental pressure create challenges for feedstock reliance, but steady demand continues to drive agricultural output. Expanding cultivation supported by technological advances in farming ensures feedstock supply remains stable for biofuel producers.
- For instance, In 2023, Chevron Renewable Energy Group produced 408 million gallons of biodiesel and renewable diesel combined, using over 15 types of feedstock including used cooking oil and animal fats.
By Application
Applications of first generation biofuels span transportation, power generation, and other industrial uses. The transportation sector holds the largest share in the First Generation Biofuel Market due to rising adoption of ethanol and biodiesel blends in road transport. It reduces dependency on fossil fuels while helping governments meet emission reduction targets. Power generation is an emerging application, where biofuels are used as a renewable alternative to coal and natural gas. Industrial uses, including heating and manufacturing processes, also contribute to demand in select regions. Expanding applications across multiple sectors reinforce the importance of first generation biofuels in the global renewable energy landscape.
Segments:
Based on Fuel Type
- Biodiesel
- Ethanol
Based on Feedstock
- Coarse Grain
- Sugar Crop
- Vegetable Oil
Based on Application
- Transportation
- Aviation
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share in the First Generation Biofuel Market, accounting for approximately 40% in 2024. The United States leads ethanol and biodiesel production, driven by the Renewable Fuel Standard (RFS) and state-level programs such as California’s Low Carbon Fuel Standard (LCFS). Established agricultural infrastructure ensures consistent corn and soybean feedstock supply, which sustains cost-competitiveness and reliable output. Canada strengthens regional growth with policy-driven biodiesel expansion and renewable fuel adoption. Strong investments in R&D improve conversion efficiency and maintain long-term viability. North America’s leadership remains critical to global biofuel supply dynamics.
Europe
Europe represents the second-largest share in the global First Generation Biofuel Market, accounting for nearly 28% in 2024. The EU’s Renewable Energy Directive (RED) and emission reduction mandates drive widespread adoption across countries such as Germany, France, and the UK. Germany dominates biodiesel production through rapeseed oil, while France strengthens ethanol supply using sugar beet. Matured infrastructure and robust regulatory frameworks support integration into transport and industrial uses. However, growing scrutiny over feedstock sustainability and indirect land-use changes may affect future investment. Europe’s policy-backed momentum secures its strong position in the global market.
Asia Pacific
Asia Pacific accounts for around 16% of the First Generation Biofuel Market in 2024 and demonstrates one of the fastest growth trajectories globally. Countries such as China, India, Japan, and South Korea expand their biofuel initiatives to enhance energy security and reduce emissions. The region leverages its abundant agricultural base, including sugarcane, rice, and corn, as key feedstocks. Government mandates like India’s E20 and Indonesia’s B35 strengthen demand, while infrastructure expansion ensures blending adoption. Public awareness and innovation further accelerate market penetration. Asia Pacific’s rapid growth positions it as a vital future contributor to global biofuel development.
Latin America & South America
Latin America, particularly South America, contributes about 11.7% of the First Generation Biofuel Market in 2025. Brazil dominates with sugarcane-based ethanol production, supported by flex-fuel vehicle technology and ambitious blending targets such as E30. Corn-based ethanol is increasingly incorporated, diversifying Brazil’s production portfolio. Other regional producers, including Colombia, Paraguay, and Argentina, expand output through national biofuel mandates. Strong domestic demand and export opportunities bolster South America’s role in the global supply chain. The region’s alignment with rural development and environmental goals ensures continued biofuel market relevance.
Middle East & Africa
The Middle East and Africa collectively account for a modest share, with the Middle East holding around 3.6% and Africa approximately 2.4% of the First Generation Biofuel Market in 2025. Adoption remains at an early stage but benefits from growing government interest. The Middle East explores feedstock development and policy frameworks to encourage investment, while Africa faces challenges such as limited logistics and inconsistent agricultural output. Countries like Uganda and South Africa struggle to implement blending mandates due to supply shortages. Despite these barriers, regulatory support and targeted investment could enable gradual regional participation in the global market.
Key Player Analysis
- DuPont
- Caterpillar
- Green Plains
- Coasan
- Borregard
- Montuk Renewables
- Chevron
- Future Fuel
- Blue Son
- Biogreen Synergy
Competitive Analysis
The competitive landscape of the First Generation Biofuel Market features leading players such as Biogreen Synergy, Blue Son, Borregard, Caterpillar, Chevron, Coasan, DuPont, Future Fuel, Green Plains, and Montuk Renewables. These companies compete on the basis of feedstock availability, production efficiency, distribution networks, and compliance with regulatory standards. They actively pursue strategic collaborations, joint ventures, and government partnerships to expand market reach and secure steady demand. Many invest in research and development to enhance fermentation technologies, optimize conversion rates, and reduce overall production costs, ensuring competitiveness against fossil fuels and advanced biofuels. Strong agricultural integration and established infrastructure give them an advantage in scaling output and meeting blending mandates across different regions. Several players also explore diversification into second-generation and advanced biofuels, strengthening long-term positioning while continuing to leverage first-generation capacity. Competitive intensity remains high, driven by fluctuating feedstock prices, policy shifts, and evolving consumer demand for sustainable energy solutions. This dynamic market environment encourages innovation, operational efficiency, and continuous adaptation to global energy transitions, positioning these companies as central contributors to the renewable energy landscape.
Recent Developments
- In August 2025, Montauk completed construction and commissioning of its second RNG (renewable natural gas) processing facility at its Apex site.
- In August 2025, Montauk Renewables joined with Emvolon to launch a joint venture converting biogas into green methanol. The venture aims to produce up to 50,000 metric tonnes annually by 2030, with initial capacity of around 6,000 metric tonnes per year at the first project site in Texas.
- In July 2025, Montuk Renewables initiated operations of a first-generation biofuel plant processing corn feedstock, reaching an initial output of 120 million liters of bioethanol annually.
- In February 2025, Future Fuel launched expanded production facilities for bioethanol derived from food-grade corn feedstock, achieving production capacity of 350 million gallons per year.
Report Coverage
The research report offers an in-depth analysis based on Fuel Type, Feedstock, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand under strong government mandates and blending targets across key regions.
- Producers will invest in improving conversion technologies to enhance efficiency and reduce costs.
- Ethanol will maintain dominance in transportation while biodiesel adoption grows in commercial vehicles and agriculture.
- Research will focus on optimizing feedstock use and minimizing environmental concerns linked to food-versus-fuel debates.
- Partnerships between fuel producers, farmers, and governments will strengthen supply chain stability.
- Expanding use of biofuels in aviation and marine transport will create new opportunities.
- Emerging economies will drive demand with rapid urbanization and growing energy needs.
- Competition from advanced biofuels will encourage innovation and diversification among first generation producers.
- Regional infrastructure development for blending, storage, and distribution will accelerate adoption.
- Environmental awareness and sustainability goals will sustain long-term relevance in the global energy mix.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for First Generation Biofuel, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the First Generation Biofuel market projected to grow between 2025 and 2032?
Which First Generation Biofuel market segment held the largest share in 2024?
What are the primary factors fueling the growth of the First Generation Biofuel market?
Who are the leading companies in the First Generation Biofuel market?
Which region commanded the largest share of the First Generation Biofuel market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 First Generation Biofuel Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global First Generation Biofuel Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 15.4 billion → 2032: USD 23.6 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 First Generation Biofuel Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. First Generation Biofuel Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 First Generation Biofuel Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 First Generation Biofuel Market Drivers
- 3.3 First Generation Biofuel Market Restraints & Challenges
- 3.4 First Generation Biofuel Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 First Generation Biofuel Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 First Generation Biofuel Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, First Generation Biofuel category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 First Generation Biofuel Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. First Generation Biofuel Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the First Generation Biofuel market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 First Generation Biofuel Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 First Generation Biofuel Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 First Generation Biofuel Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in First Generation Biofuel (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New First Generation Biofuel Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global First Generation Biofuel Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America First Generation Biofuel Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe First Generation Biofuel Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific First Generation Biofuel Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America First Generation Biofuel Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East First Generation Biofuel Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa First Generation Biofuel Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. First Generation Biofuel Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
