
Market Overview
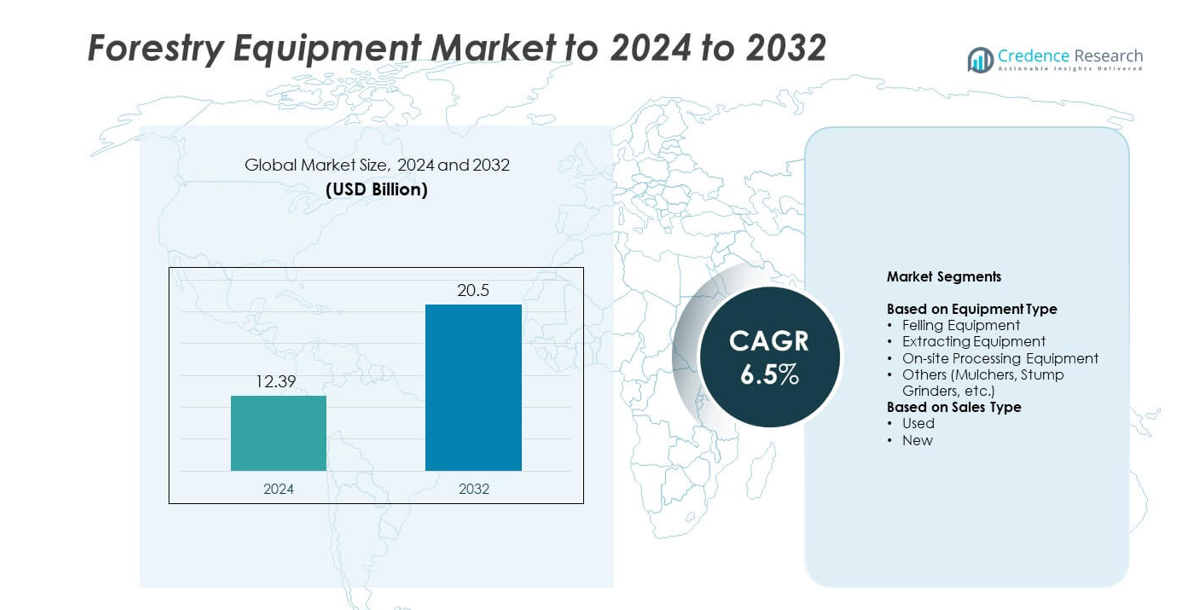
The Forestry Equipment Market size was valued at USD 12.39 Billion in 2024 and is anticipated to reach USD 20.5 Billion by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Forestry Equipment Market Size 2024 | USD 12.39 Billion |
| Forestry Equipment Market, CAGR | 6.5% |
| Forestry Equipment Market Size 2032 | USD 20.5 Billion |
The Forestry Equipment Market is dominated by leading manufacturers such as Deere & Company, Komatsu Ltd., STIHL Holding AG & Co. KG, Tigercat International Inc., and Ponsse Oyj. These companies focus on innovation, advanced telematics, and sustainable technologies to enhance performance and reduce environmental impact. Strategic partnerships and expanded distribution networks have strengthened their global presence. North America led the market in 2024 with a 36% share, driven by high mechanization and government-supported reforestation initiatives. Europe followed with a 29% share, supported by stringent environmental regulations and growing adoption of electric and hybrid forestry machinery.
Market Insights
- The Forestry Equipment Market was valued at USD 12.39 billion in 2024 and is projected to reach USD 20.5 billion by 2032, growing at a CAGR of 6.5%.
- Market growth is driven by rising mechanization, sustainable forestry practices, and increasing demand for efficient timber harvesting solutions across major regions.
- Key trends include the adoption of electric and hybrid machinery, telematics integration, and automation for improved productivity and reduced emissions.
- The market is highly competitive, with companies focusing on digital technologies, precision forestry tools, and strategic partnerships to expand their global reach.
- North America led with a 36% share in 2024, followed by Europe at 29% and Asia-Pacific at 24%, while the felling equipment segment dominated with a 38% share due to its efficiency in large-scale logging operations.
Market Segmentation Analysis:
By Equipment Type
Felling equipment dominated the forestry equipment market with around 38% share in 2024. Its leadership is driven by the high demand for mechanized tree-cutting and harvesting processes that enhance productivity and safety. The growing adoption of feller bunchers and harvesters, particularly in North America and Europe, supports efficient timber collection and minimizes manual labor. Increasing investments in advanced hydraulic and sensor-based felling systems also promote precision and fuel efficiency. Continuous upgrades in cutting mechanisms and operator comfort features are further strengthening the dominance of felling equipment across large-scale logging operations.
- For instance, Tigercat’s X870D feller buncher delivers 245 kW power with an 8.46 m cut radius and 3.28 m tail-swing radius, aiding high-productivity felling.
By Sales Type
New equipment accounted for the largest 67% share of the forestry equipment market in 2024. The segment’s dominance is attributed to the demand for technologically advanced, fuel-efficient, and low-emission machinery. Forestry companies prefer new machines with GPS-enabled tracking, telematics, and automation capabilities to improve operational accuracy and productivity. Stringent environmental regulations and sustainability mandates are encouraging replacement of older, less efficient equipment. Additionally, government-backed forestry modernization programs and financing support for new machinery purchases are fueling adoption among contractors and commercial logging operators.
- For instance, Komatsu’s 951 harvester provides 214 kW at 1,850 rpm, 222 kN tractive force, and weighs from 22,790 kg, reflecting modern performance targets.
Key Growth Drivers
Rising Mechanization in Forestry Operations
The forestry industry is rapidly shifting from manual labor to advanced mechanized solutions. Modern forestry equipment such as harvesters, skidders, and forwarders improves efficiency, reduces operational time, and ensures worker safety. This transition is driven by growing timber demand from construction, paper, and biomass sectors. Countries with expanding forestry industries are investing in automated and high-capacity machinery to optimize yields. The need for precision, productivity, and safety continues to push manufacturers toward developing next-generation mechanized equipment.
- For instance, Eco Log’s 688F eight-wheel harvester pairs a 286 hp Volvo Penta engine with a 270 kNm crane and 200 kN tractive force for steep-terrain logging.
Increasing Demand for Sustainable Forest Management
Sustainability initiatives are becoming a key factor in equipment purchases and forest operations. Forestry operators are adopting eco-friendly machines designed to reduce emissions and fuel use. Government programs promoting reforestation and sustainable logging practices are encouraging equipment modernization. Manufacturers are introducing low-impact machinery with hybrid power systems and improved hydraulic efficiency. This focus on sustainable forestry practices is directly supporting the adoption of new equipment and accelerating global market growth.
- For instance, Ponsse’s Model Series upgrade extended service intervals from 600/1,200 to 900/1,800 hours with Stage IV engines using SCR and cooled EGR to cut emissions.
Technological Advancements in Equipment Design
Integration of automation, telematics, and IoT-based monitoring is transforming forestry operations. Smart equipment now offers real-time data analytics for tracking productivity, equipment health, and terrain navigation. Advanced hydraulic systems and precision cutting tools enhance accuracy while minimizing wood waste. Manufacturers are prioritizing operator safety and ergonomics through sensor-based control systems and remote diagnostics. These technological innovations are improving overall efficiency and reducing downtime, making advanced forestry equipment more attractive to large-scale operators.
Key Trends & Opportunities
Adoption of Electric and Hybrid Equipment
The market is witnessing a gradual shift toward electric and hybrid-powered forestry machinery. These models offer lower emissions, reduced noise, and lower operating costs compared to traditional diesel equipment. Governments across Europe and North America are supporting electrification through subsidies and environmental regulations. Manufacturers are expanding research in battery technology to enhance power output and runtime. The growing emphasis on carbon neutrality presents strong opportunities for green and sustainable forestry equipment.
- For instance, Logset’s 12H GTE Hybrid delivers a peak output of up to 510 hp and 2,000 Nm torque from its combined diesel and electric system. The harvester uses a 175 kW electric motor to provide instantaneous boost power for peak load situations.
Expansion of Telematics and Data-Driven Operations
Telematics systems are becoming standard in modern forestry equipment, enabling fleet optimization and predictive maintenance. Real-time performance data allows operators to monitor productivity, fuel usage, and maintenance needs remotely. This data-driven approach helps reduce downtime and extends machine lifespan. Companies are also integrating AI and cloud-based platforms for enhanced equipment management. The growing digitalization of forestry operations is creating new revenue opportunities for software and analytics providers in the market.
- For instance, John Deere provides 5 years of JDLink connectivity on most new forestry models, and TimberMatic Maps records precise stem and log counts with GPS mapping.
Key Challenges
High Initial Investment and Maintenance Costs
The high cost of advanced forestry machinery remains a major challenge for small and medium operators. Equipment such as harvesters and skidders involve significant capital expenditure and ongoing maintenance expenses. Limited access to financing options in developing regions further restricts adoption. Additionally, the cost of skilled labor for machine operation and servicing increases total ownership costs. These economic barriers hinder large-scale modernization, particularly among independent contractors and small forestry firms.
Regulatory and Environmental Compliance Issues
Strict environmental and safety regulations often slow down equipment deployment and forest operations. Manufacturers must ensure compliance with emission standards, noise limits, and deforestation guidelines. These requirements raise production costs and limit the use of certain high-power engines. Regulatory differences across countries also create challenges for global manufacturers. Continuous adaptation to evolving sustainability laws and certification standards adds further complexity, impacting market expansion and profitability.
Regional Analysis
North America
North America held the largest 36% share of the forestry equipment market in 2024, driven by strong mechanization and sustainable forest management practices. The United States and Canada have advanced forestry industries supported by high adoption of harvesters, skidders, and loaders. Increasing demand for wood-based products and biomass energy continues to drive equipment sales. Government initiatives promoting reforestation and eco-friendly logging technologies also support market expansion. Major manufacturers in the region are investing in automation and telematics-based systems to improve operational safety, fuel efficiency, and productivity across large commercial forest areas.
Europe
Europe accounted for a 29% share of the forestry equipment market in 2024, supported by strict environmental regulations and sustainable forestry policies. Countries such as Finland, Sweden, and Germany are leading in advanced mechanized harvesting due to well-established timber industries. The demand for hybrid and electric forestry machinery is growing, aligning with the European Union’s emission-reduction goals. Investments in precision forestry technologies and digital management systems are improving efficiency and forest conservation. Increased public funding for reforestation and bioenergy initiatives further boosts regional market growth and modernization of forestry operations.
Asia-Pacific
Asia-Pacific captured a 24% share of the forestry equipment market in 2024, propelled by expanding forestry operations in China, Japan, and India. Rapid industrialization and rising demand for timber, pulp, and paper are key growth factors. Governments are encouraging modernization through subsidies for mechanized logging and reforestation projects. The adoption of advanced harvesting and processing machinery is increasing, particularly in large-scale forestry operations. Technological partnerships between regional and global manufacturers are enhancing local production capabilities, driving innovation and accessibility of advanced forestry equipment across emerging markets.
Latin America
Latin America represented a 7% share of the forestry equipment market in 2024, driven by expanding timber exports and reforestation programs in Brazil and Chile. The region’s vast forest reserves support strong logging and wood-processing industries. Government-backed initiatives promoting sustainable forest management are encouraging investment in efficient and low-emission machinery. However, limited infrastructure and fluctuating raw material prices pose challenges. International equipment manufacturers are strengthening regional distribution networks and offering financing options to increase accessibility of modern forestry machines among local operators and contractors.
Middle East & Africa
The Middle East & Africa accounted for a 4% share of the forestry equipment market in 2024, with growing demand from countries focused on afforestation and desert greening projects. Rising wood imports and investments in sustainable land management are driving regional interest in mechanized forestry tools. Africa, particularly South Africa and Kenya, is witnessing gradual modernization of forest operations. Challenges include limited capital access and technical expertise, but international collaborations are improving equipment availability. The region shows long-term potential due to increasing environmental restoration initiatives and expanding forestry infrastructure.
Market Segmentations:
By Equipment Type
- Felling Equipment
- Extracting Equipment
- On-site Processing Equipment
- Others (Mulchers, Stump Grinders, etc.)
By Sales Type
- Used
- New
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The forestry equipment market is characterized by strong competition among major players such as Deere & Company, Komatsu Ltd., STIHL Holding AG & Co. KG, Tigercat International Inc., and others. Companies are focusing on innovation, automation, and sustainability to strengthen their product portfolios and global presence. Advancements in telematics, GPS-based navigation, and fuel-efficient systems are driving differentiation among leading manufacturers. Strategic partnerships with forestry operators, dealers, and technology providers are expanding distribution and aftersales networks. Many producers are also investing in electric and hybrid machinery to comply with emission regulations and meet sustainability goals. Continuous R&D in precision cutting tools, hydraulic systems, and operator safety features is enhancing productivity and operational reliability. The competitive environment is expected to remain intense as manufacturers focus on digital integration, cost optimization, and localized production to cater to diverse regional markets and evolving forestry management needs.
Key Player Analysis
- Deere & Company (U.S.)
- Komatsu Ltd. (Japan)
- STIHL HOLDING AG & Co. KG (Germany)
- Tigercat International Inc. (Canada)
- Hitachi Construction Machinery Co. Ltd. (Japan)
- Ponsse Oyj (Finland)
- Vermeer Corporation (U.S.)
- Husqvarna Group (Sweden)
- MARUYAMA Mfg. Co., Inc. (Japan)
- C. Bamford Excavators Limited (U.K.)
- Logset Oy (Finland)
- Caterpillar Inc. (U.S.)
- Rottne Industri (Sweden)
- Yantai Lansu Co., Ltd. (China)
- Waratah (Canada)
- MOROOKA Co., Ltd. (Japan)
Recent Developments
- In 2025, John Deere Launched the new H-Series forestry machines, including the 1270H and 1470H Harvesters and 2010H and 2510H Forwarders.
- In 2025, Komatsu Ltd. Launched the new Komatsu 898 forwarder, a model adapted for plantation forestry with a 25-tonne load capacity.
- In 2024, Tigercat Introduced the LX877 feller buncher, designed for enhanced productivity in timber harvesting.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Sales Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The forestry equipment market will grow steadily, supported by rising mechanization in logging operations.
- Automation, telematics, and IoT integration will enhance equipment efficiency and reduce downtime.
- Electric and hybrid machinery adoption will expand due to stricter emission standards.
- Demand for sustainable and fuel-efficient equipment will strengthen under global reforestation programs.
- North America and Europe will maintain dominance due to advanced forestry practices and strong infrastructure.
- Asia-Pacific will witness rapid growth driven by industrial expansion and forest resource development.
- Manufacturers will focus on ergonomic designs and operator safety features to increase productivity.
- Data-driven forestry management systems will improve resource utilization and decision-making accuracy.
- Partnerships between equipment makers and government agencies will support modernization initiatives.
- Rising wood demand from construction and bioenergy sectors will continue to drive long-term market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Forestry Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Forestry Equipment Market projected to grow between 2025 and 2032?
Which Forestry Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Forestry Equipment Market?
Who are the leading companies in the Forestry Equipment Market?
Which region commanded the largest share of the Forestry Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.39 billion → 2032: USD 20.5 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Forestry Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Forestry Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Forestry Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Forestry Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Forestry Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Forestry Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Forestry Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Forestry Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.39 billion → 2032: USD 20.5 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Forestry Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Forestry Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Forestry Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Forestry Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

