
Labor costs and robots set professional fleet demand
The global floor cleaning and mopping machines market was valued at USD 6.39 billion in 2025 and is projected to increase from USD 6.71 billion in 2026 to USD 10.32 billion by 2035, registering a CAGR of 4.90% during 2026–2035. Demand comes from contract cleaners, retailers, warehouses, hospitals, airports, schools and food plants that replace manual mops and brooms with scrubber-dryers, sweepers, burnishers and autonomous units. North America held the largest regional share, 35.0% in 2025, because building service contractors there face high wages and buy through dense dealer and rental networks. Asia Pacific is the fastest-growing region at 5.9% a year, as Chinese robot makers scale output and regional malls and transport hubs mechanize floor care. The supply side shifted when the largest Western makers tied their robotic ranges to outside autonomy platforms and Chinese robot firms moved into Europe and North America. Buyers now compare machines on cost per square foot cleaned, runtime, water use and service coverage rather than on purchase price alone.
Contract cleaners and large sites buy most scrubbers and robots
The estimate counts powered machines that scrub, mop, sweep, vacuum or burnish hard floors and carpets in commercial, institutional and industrial buildings, including walk-behind and ride-on scrubber-dryers, robotic units, compact micro-scrubbers and burnishers. Contract cleaners, retailers, logistics operators and hospitals buy them outright, lease them through dealers or rent them on monthly service contracts.
Household vacuums, household wet-dry floor washers, cleaning chemicals, spare parts and service revenue sit outside the estimate, although parts and service carry a large share of supplier profit. Values are counted at manufacturer selling prices, so dealer margins and rental income are not added on top.
Floor Cleaning and Mopping Machines Market Insights
- The market is valued at USD 6.39 billion in 2025 and is projected to reach USD 10.32 billion by 2035, growing at a 4.90% CAGR as robots and compact scrubbers replace manual labor.
- North America led with 35.0% of 2025 value, while Asia Pacific grows fastest at 5.9% a year as Chinese robot output and regional transport hubs expand.
- Walk-Behind Scrubber-Dryers held 33.5% of 2025 value, because retail, school and office cleaners use them for daily aisle and corridor scrubbing.
- Tennant and Brain Corp agreed in April 2026 to extend their robotic exclusivity by three years and release 10 new robotic products within 24 months.
- Professional cleaning robot sales rose 34% to more than 25,000 units in 2024, according to the International Federation of Robotics.
Walk-behind scrubbers lead while robots grow fastest
Why do walk-behind scrubber-dryers lead while robots grow fastest?
Based on product type, the market is categorized into walk-behind scrubber-dryers, ride-on scrubber-dryers, robotic scrubbers and vacuums, sweepers and cordless electric brooms, commercial vacuum cleaners and others. Walk-Behind Scrubber-Dryers led with 33.5% of 2025 value because they fit store aisles, schools and offices at moderate prices, and a 2024 Tennant distributor price list carried a 20-inch T300 at about USD 6,400. Robotic Scrubbers and Vacuums grow fastest at 10.1% a year as large-area units reach logistics halls, and Kärcher rates its largest autonomous scrubber at up to 52,313 square feet an hour in open areas.
Why does scrubbing dominate while mopping grows fastest?
Based on method, the market is categorized into scrubbing, mopping, buffing and burnishing, spray cleaning and others, which cover sweeping, scarifying and steaming. Scrubbing led with 50.0% of 2025 value because scrubber-dryers wash and recover water in one pass, which most retail, warehouse and hospital cleaning schedules require. Mopping grows fastest at 6.6% a year as compact machines replace string mops in small rooms, and a university supply contract lists the Tennant CS5 micro-scrubber at USD 2,354.25 and the i-mop XL Plus at USD 5,832.36.
Why do commercial sites lead while logistics grows fastest?
Based on end user, the market is categorized into commercial sites, warehousing and logistics, industrial plants, healthcare, food and beverage and others, which cover education, transport hubs and government buildings. Commercial (Retail, Offices and Hospitality) sites led with 32.0% of 2025 value because contractors that clean stores, offices and hotels every night own large standardized fleets, and the BLS counted 831,700 janitors in services to buildings and dwellings in May 2023. Warehousing and Logistics grows fastest at 6.1% a year as robots move into distribution centers, and Pudu chose MODEX 2026 in Atlanta, a supply chain trade show, to debut its BG1 large scrubber-dryer robot series in April 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Walk-Behind Scrubber-Dryers | 33.5% | Robotic Scrubbers and Vacuums | 10.1% |
| By Method | Scrubbing | 50.0% | Mopping | 6.6% |
| By End User | Commercial (Retail, Offices and Hospitality) | 32.0% | Warehousing and Logistics | 6.1% |
Path width and autonomy set what buyers pay per machine
Prices rise with cleaning path, tank size, battery chemistry and autonomy, so a lithium-ion 20-inch walk-behind can cost three times a basic AGM unit of the same width. Dealers sell most machines on list prices with negotiated discounts, while public buyers use cooperative contracts tied to manufacturer price lists. Robots move the cost from purchase to subscription, and a large autonomous scrubber that lists near USD 96,000 also rents for about USD 2,700 a month. The figures below are single list or contract prices rather than market averages, because actual fleet prices vary with volume and service terms.
| Machine class | Typical price or fee | Basis |
|---|---|---|
| Upright micro-scrubber | USD 2,995 (Nilfisk Dryft) | Staples online list, 2026 |
| Walk-behind scrubber-dryer, 20-inch | USD 4,055 (Viper AS380, AGM) to USD 12,545 (Nilfisk SC550, lithium-ion) | Staples online list, 2026 |
| Ride-on scrubber-dryer, 32-inch | USD 26,245 (Tennant T7, lead-acid) | Cleaner Floors online list, 2026 |
| Compact multi-function robot | USD 22,000 (Pudu CC1) | RobotLAB online list, 2026 |
| Large robotic scrubber | USD 95,880 purchase or USD 2,669 a month (Gausium Scrubber 75) | RobotLAB online list, 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Wages, infection control and robot economics lift demand
Rising cleaner wages raise the payback on machines
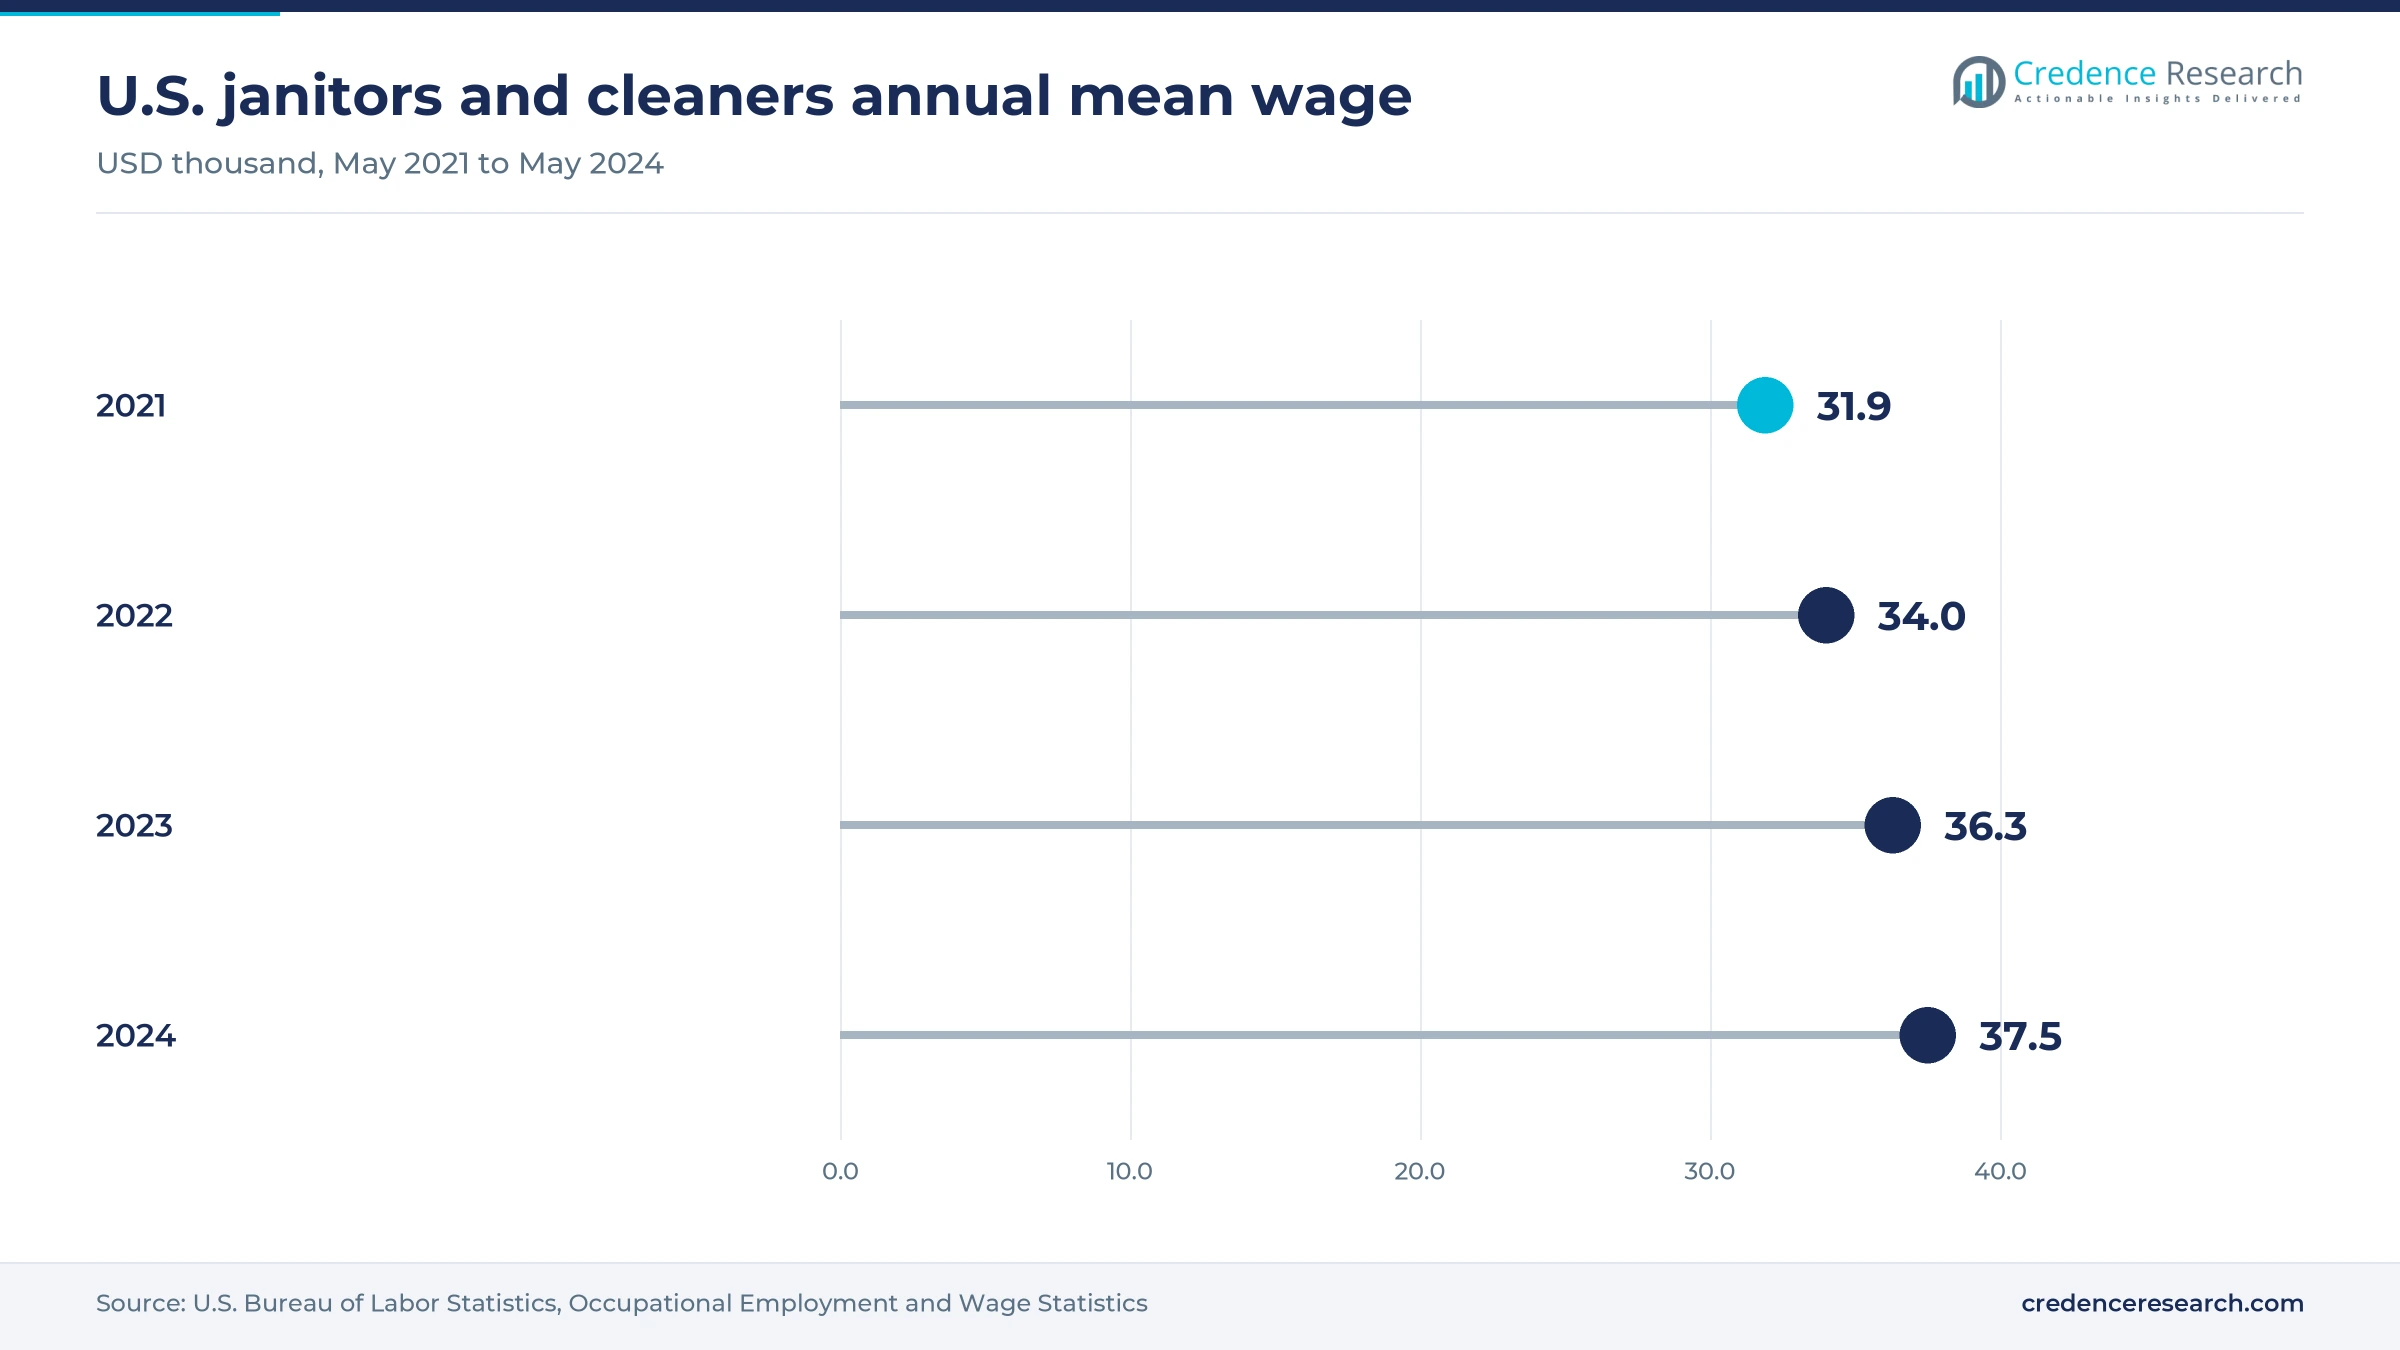
Labor makes up most of the cost of commercial floor care, so every wage increase shortens the payback on floor cleaning and mopping machines that cover more area per shift. U.S. janitors and cleaners earned an annual mean wage of USD 37,460 in May 2024, according to Bureau of Labor Statistics occupational data, up from USD 31,860 in the agency's May 2021 survey. The same survey counted 2,199,900 janitors and cleaners in May 2024, which shows how large the labor pool is that machines can make more productive. Building service contractors that sell facility management services bid on fixed prices per square foot, so a ride-on or robotic scrubber that covers more floor per shift protects their margin. Suppliers that can show cost per square foot cleaned gain the most from this pressure.
Infection control keeps hospital floor care mechanized
Hospitals buy floor cleaning and mopping machines such as scrubber-dryers and micro-scrubbers because recovering dirty water, rather than spreading it with a mop, reduces the residue that carries pathogens between rooms. The American Hospital Association counted 6,093 U.S. hospitals with 907,216 staffed beds in its 2026 Fast Facts edition, each with corridors and patient rooms cleaned every day. Hospital-onset C. difficile infections fell 11% in 2024 from 2023, according to the CDC national progress report released in July 2026, which keeps environmental cleaning under audit. Hako says its Scrubmaster B35 and B50, due from mid-2026, cut operating noise, a key criterion for daytime ward cleaning. Healthcare grows at about the market pace, but buyers favor suppliers with validated hygiene data.
Robot sales scale as unit economics improve
Autonomous scrubbers now pay back fast enough for multi-site retailers and airports to buy them in fleets rather than as pilots. Sales of professional cleaning robots rose 34% to more than 25,000 units in 2024, according to the International Federation of Robotics, ranking cleaning third among professional service robot uses. Brain Corp says more than 40,000 robots run on its autonomy software across six continents. Gausium targeted 20,000 unit sales for 2025, 40% to 50% more than in 2024, The Standard reported in May 2025. Robotic units grow at 10.1% a year, the fastest product rate, and buyers comparing robotic scrubbers increasingly weigh fleet software and service coverage alongside the machine.
Large logistics floors favor big autonomous units
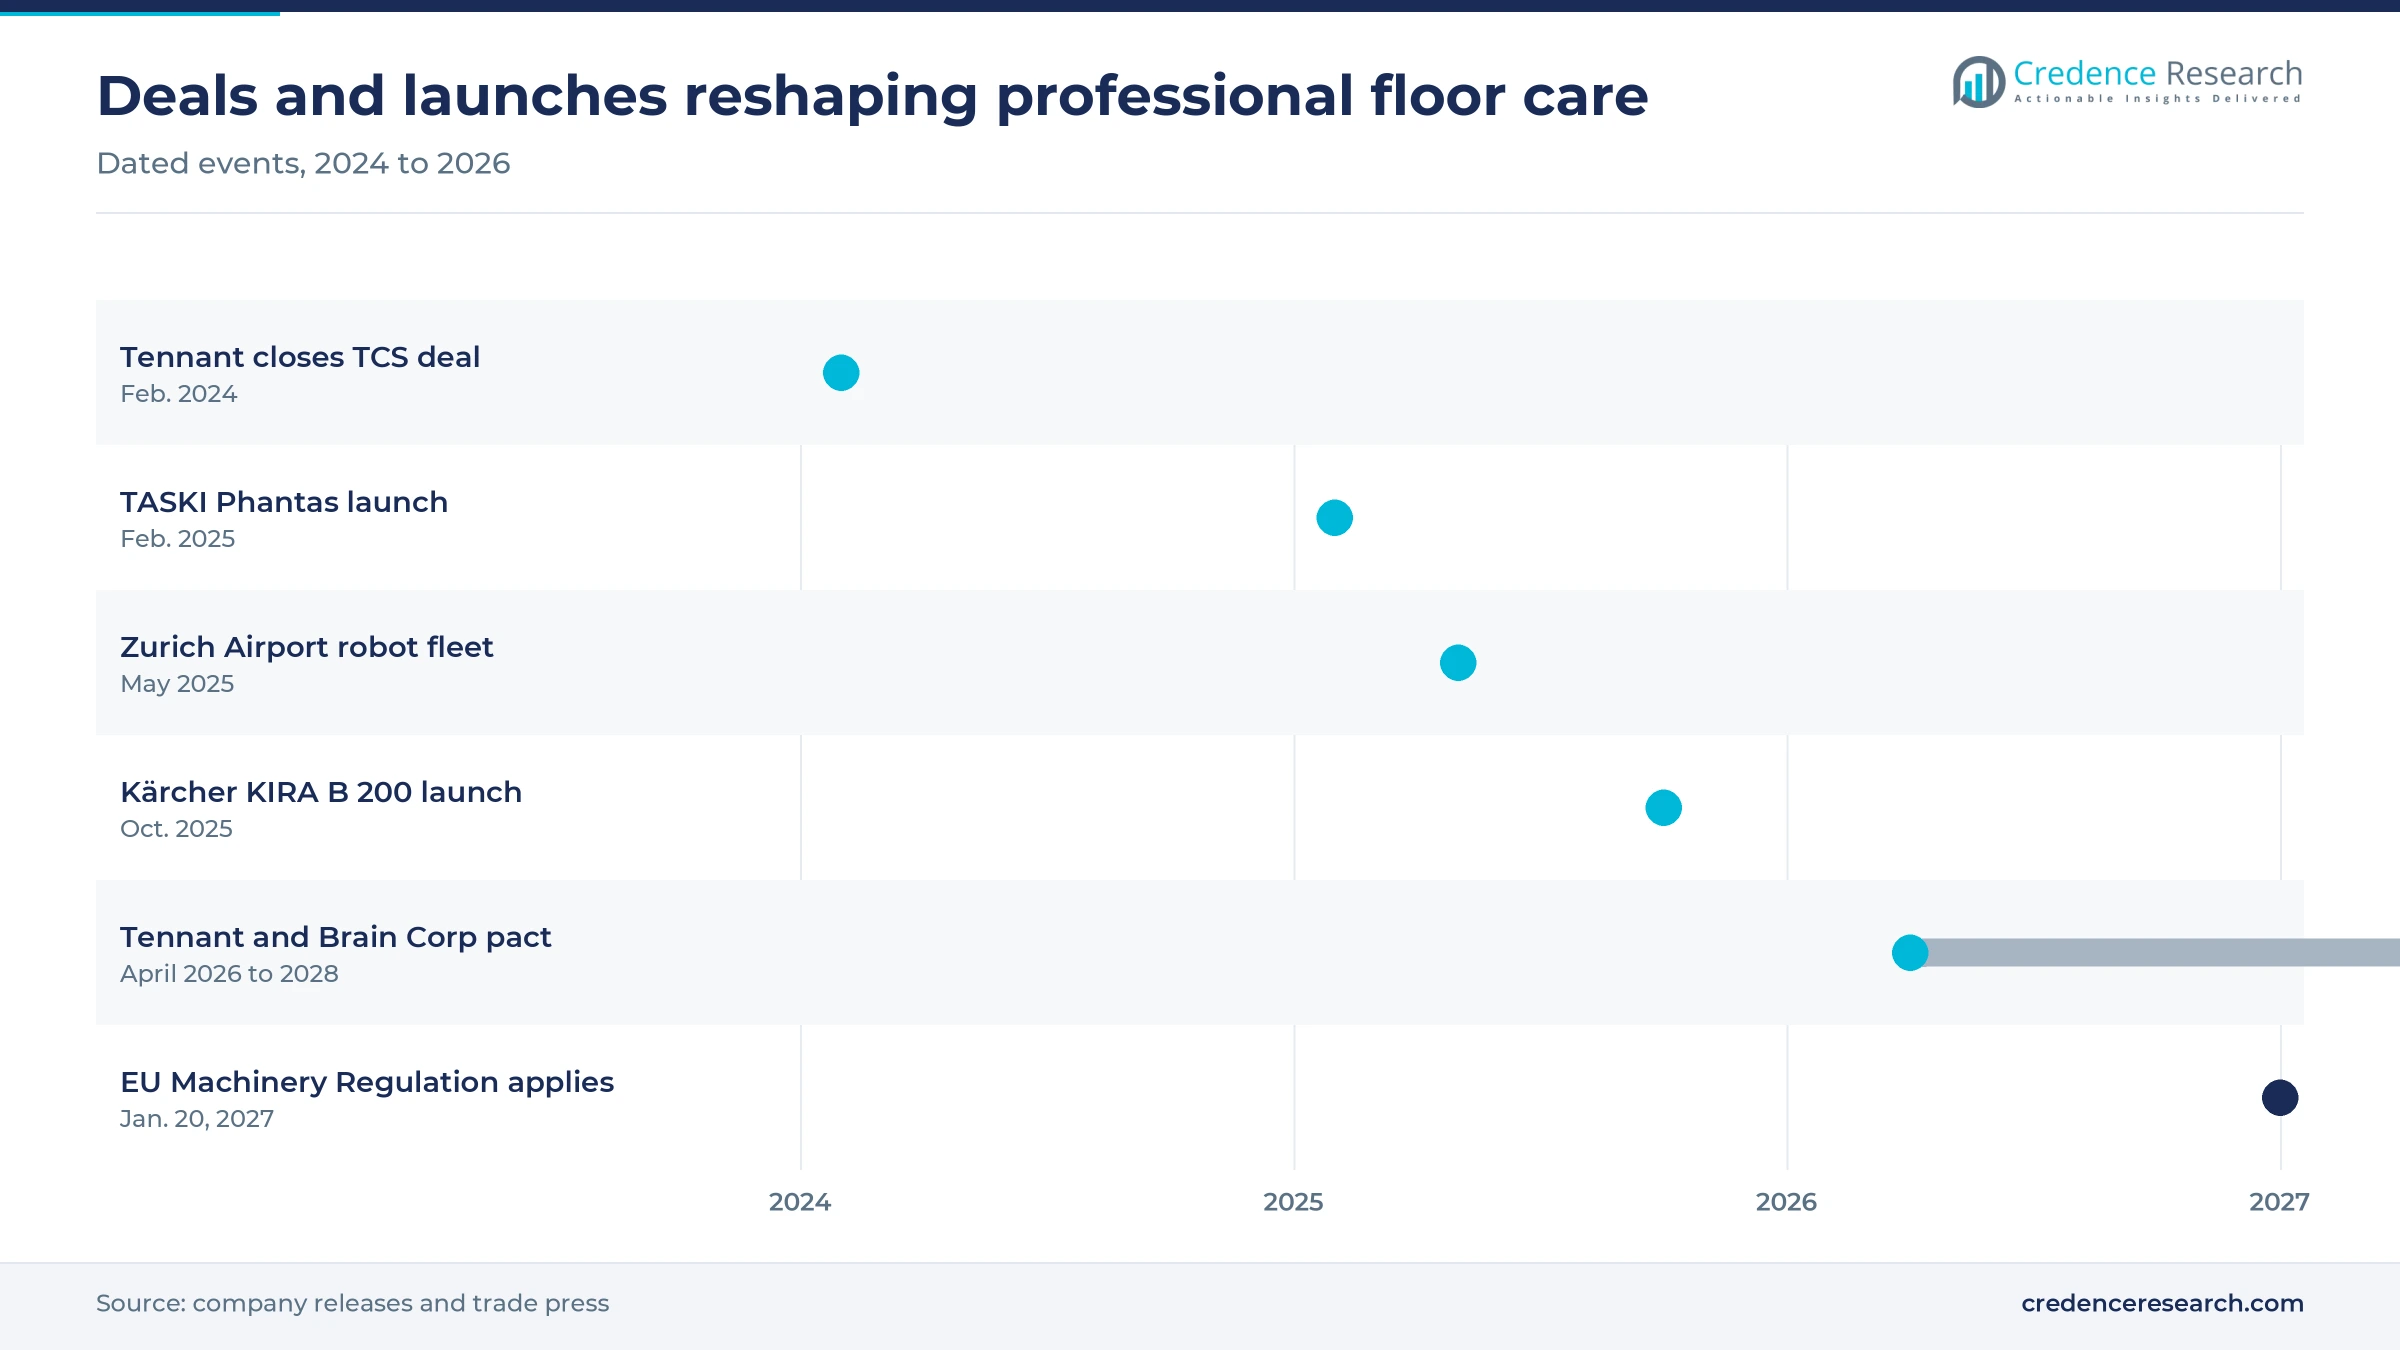
Distribution centers have the open floor area and night shifts that let large autonomous scrubbers run for hours without stopping. Kärcher launched the KIRA B 200 in October 2025 with 52-gallon fresh and dirty water tanks, a four-hour lithium-ion run time and an optional docking station that refills and empties the machine. The unit supports the VDA 5050 protocol, so it can share routes with automated guided vehicles already moving goods in the same hall. Pudu says its BG1 robots combine sweeping and scrubbing in one pass, which suits dusty warehouse floors. Warehousing and logistics grows at 6.1% a year, the fastest end-user rate, which favors suppliers that integrate with warehouse automation.
Autonomy pacts, micro-scrubbers and fleet rental
Machine makers are shifting to outside autonomy platforms
Western equipment makers are shifting toward licensed navigation software instead of building autonomy alone, which speeds robot launches but ties product plans to a software partner. Tennant and Brain Corp agreed in April 2026 to extend their exclusivity by three years and release 10 new robotic products within 24 months, according to a Tennant announcement. Under that split, Tennant handles design, sales and service while Brain Corp supplies the BrainOS platform. NEURA Robotics said in August 2026 that it was acquiring ADLATUS Robotics, an Ulm-based maker of cleaning and sweeping robots. Mid-size makers without such partnerships risk falling behind on navigation, safety certification and fleet reporting.
Micro-scrubbers and multi-function robots replace mops
Small spaces such as restrooms, clinics, kitchens and convenience stores are shifting from string mops toward compact scrubbers that apply and recover water. TASKI launched the Phantas in February 2025, a robot that works as either a scrubber-dryer or a vacuum and cleans up to 10,500 square feet per charge. Pudu lists its CC1 robot as a four-in-one machine that sweeps, scrubs, vacuums and mops at about 8,000 square feet an hour. Mopping grows at 6.6% a year, the fastest method rate, which opens room for suppliers of low-cost compact units sold through janitorial distributors.
Airports open a large fleet opportunity for robots
Airports offer one of the clearest openings for autonomous fleets, because terminals run around the clock with wide hard floors and strict appearance standards. Global airports handled a record 9.8 billion passengers in 2025, up 3.7% from 2024, Airports Council International reported in July 2026. Zurich Airport installed 20 TASKI Ecobot 50 and six Phantas robots under a May 2025 partnership, with an estimated return on investment of under two years. Kärcher U.K. says its newest large autonomous scrubber carries safety certification for public areas under a new industry standard. Suppliers that can connect robots to doors, elevators and airport management platforms are best placed to win these multi-unit tenders.
Rental and subscription fleets reach mid-size buyers
Monthly contracts turn a large capital purchase into an operating cost, which opens autonomous and ride-on machines to mid-size contractors that could not justify buying them. The fleet of professional service robots offered as a service grew 31% in 2024, the same federation data show, as more buyers rent rather than buy outright. The large Gausium robot in the pricing table rents for less than 3% of its purchase price each month, which lowers the entry barrier. Kärcher U.K. offers its large autonomous scrubber for purchase or through Kärcher Hire, and suppliers that build robotics as a service offers keep recurring revenue and a closer customer relationship.
Tariffs, deferred purchases and new EU safety rules
U.S. tariffs raise costs for imported machines
Tariffs on imported components and finished machines raised costs for suppliers serving U.S. buyers through 2025. Tennant said tariffs imposed in the second half of 2025 will keep pressing its gross margin in 2026, and Nilfisk said higher U.S. tariffs weighed on its 2025 margin. A Feb. 20, 2026, Supreme Court decision on emergency tariff powers left the final cost unclear, Tennant noted. European and Asian makers selling into U.S. dealer channels are most exposed, while local assembly reduces the risk.
Commercial buyers deferred fleet replacements in 2025
Commercial customers delayed machine replacements in 2025, which hit volume at the largest suppliers. Tennant reported an 8.7% volume decline for 2025, partly offset by 1.4% price, with the Americas the weakest region. Kärcher said the cleaning market declined in 2025 mainly because commercial customers held back on purchases. Nilfisk guided organic growth of minus 1% to plus 2% for 2026. Dealers carrying heavy ride-on inventory face the most pressure while replacement cycles stretch.
Chinese robot pricing squeezes Western margins
Chinese robot makers are pricing compact autonomous units well below Western large-area machines, which compresses margins in the segment growing fastest. The compact Pudu robot in the pricing table lists for under a quarter of the large Gausium unit, while Kärcher cited Chinese price pressure as a brake on its 2025 growth. Pudu says it has shipped more than 120,000 service robots to over 80 countries and regions. European mid-size makers without volume scale are most exposed, so they compete on service networks, local certification and integration rather than on price.
New EU safety rules add work for autonomous units
Robot suppliers selling in Europe must prepare for stricter conformity rules, which raises engineering and testing costs before launch. Regulation (EU) 2023/1230 on machinery applies from Jan. 20, 2027, replacing Directive 2006/42/EC and covering autonomous mobile machinery and AI-based safety functions, according to EU-OSHA. Small robot start-ups face the heaviest burden, because they lack in-house certification teams. Suppliers using certified autonomy platforms and sensors from larger partners can spread these costs across more units.
North America leads and Asia Pacific grows fastest
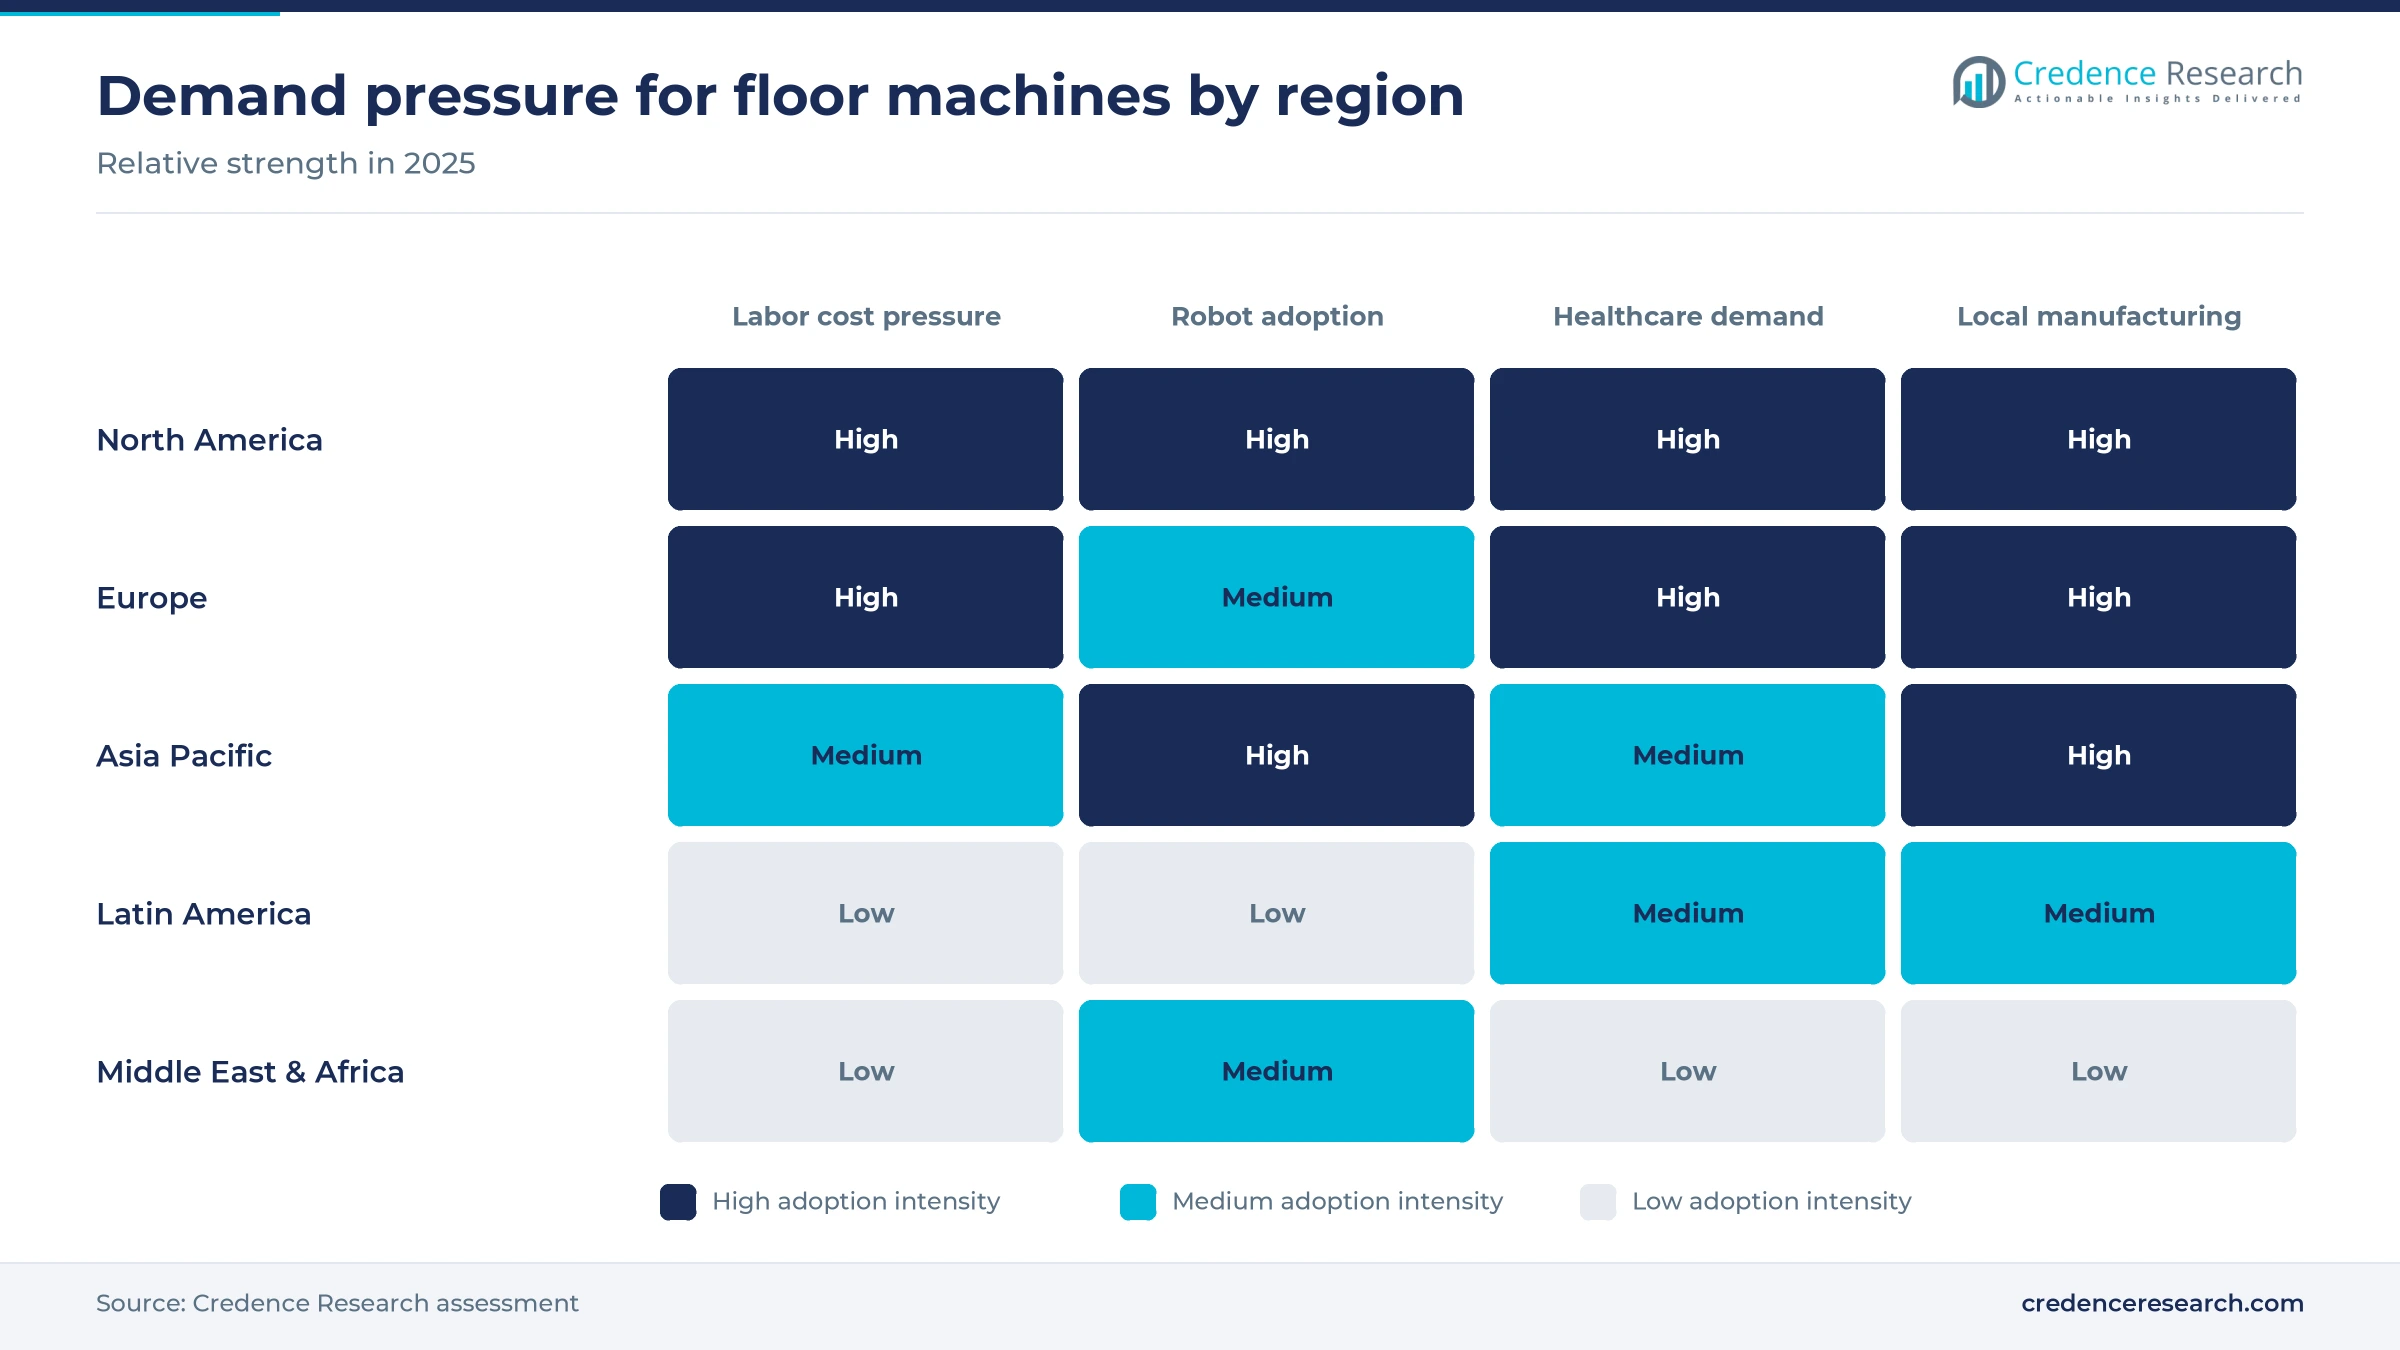
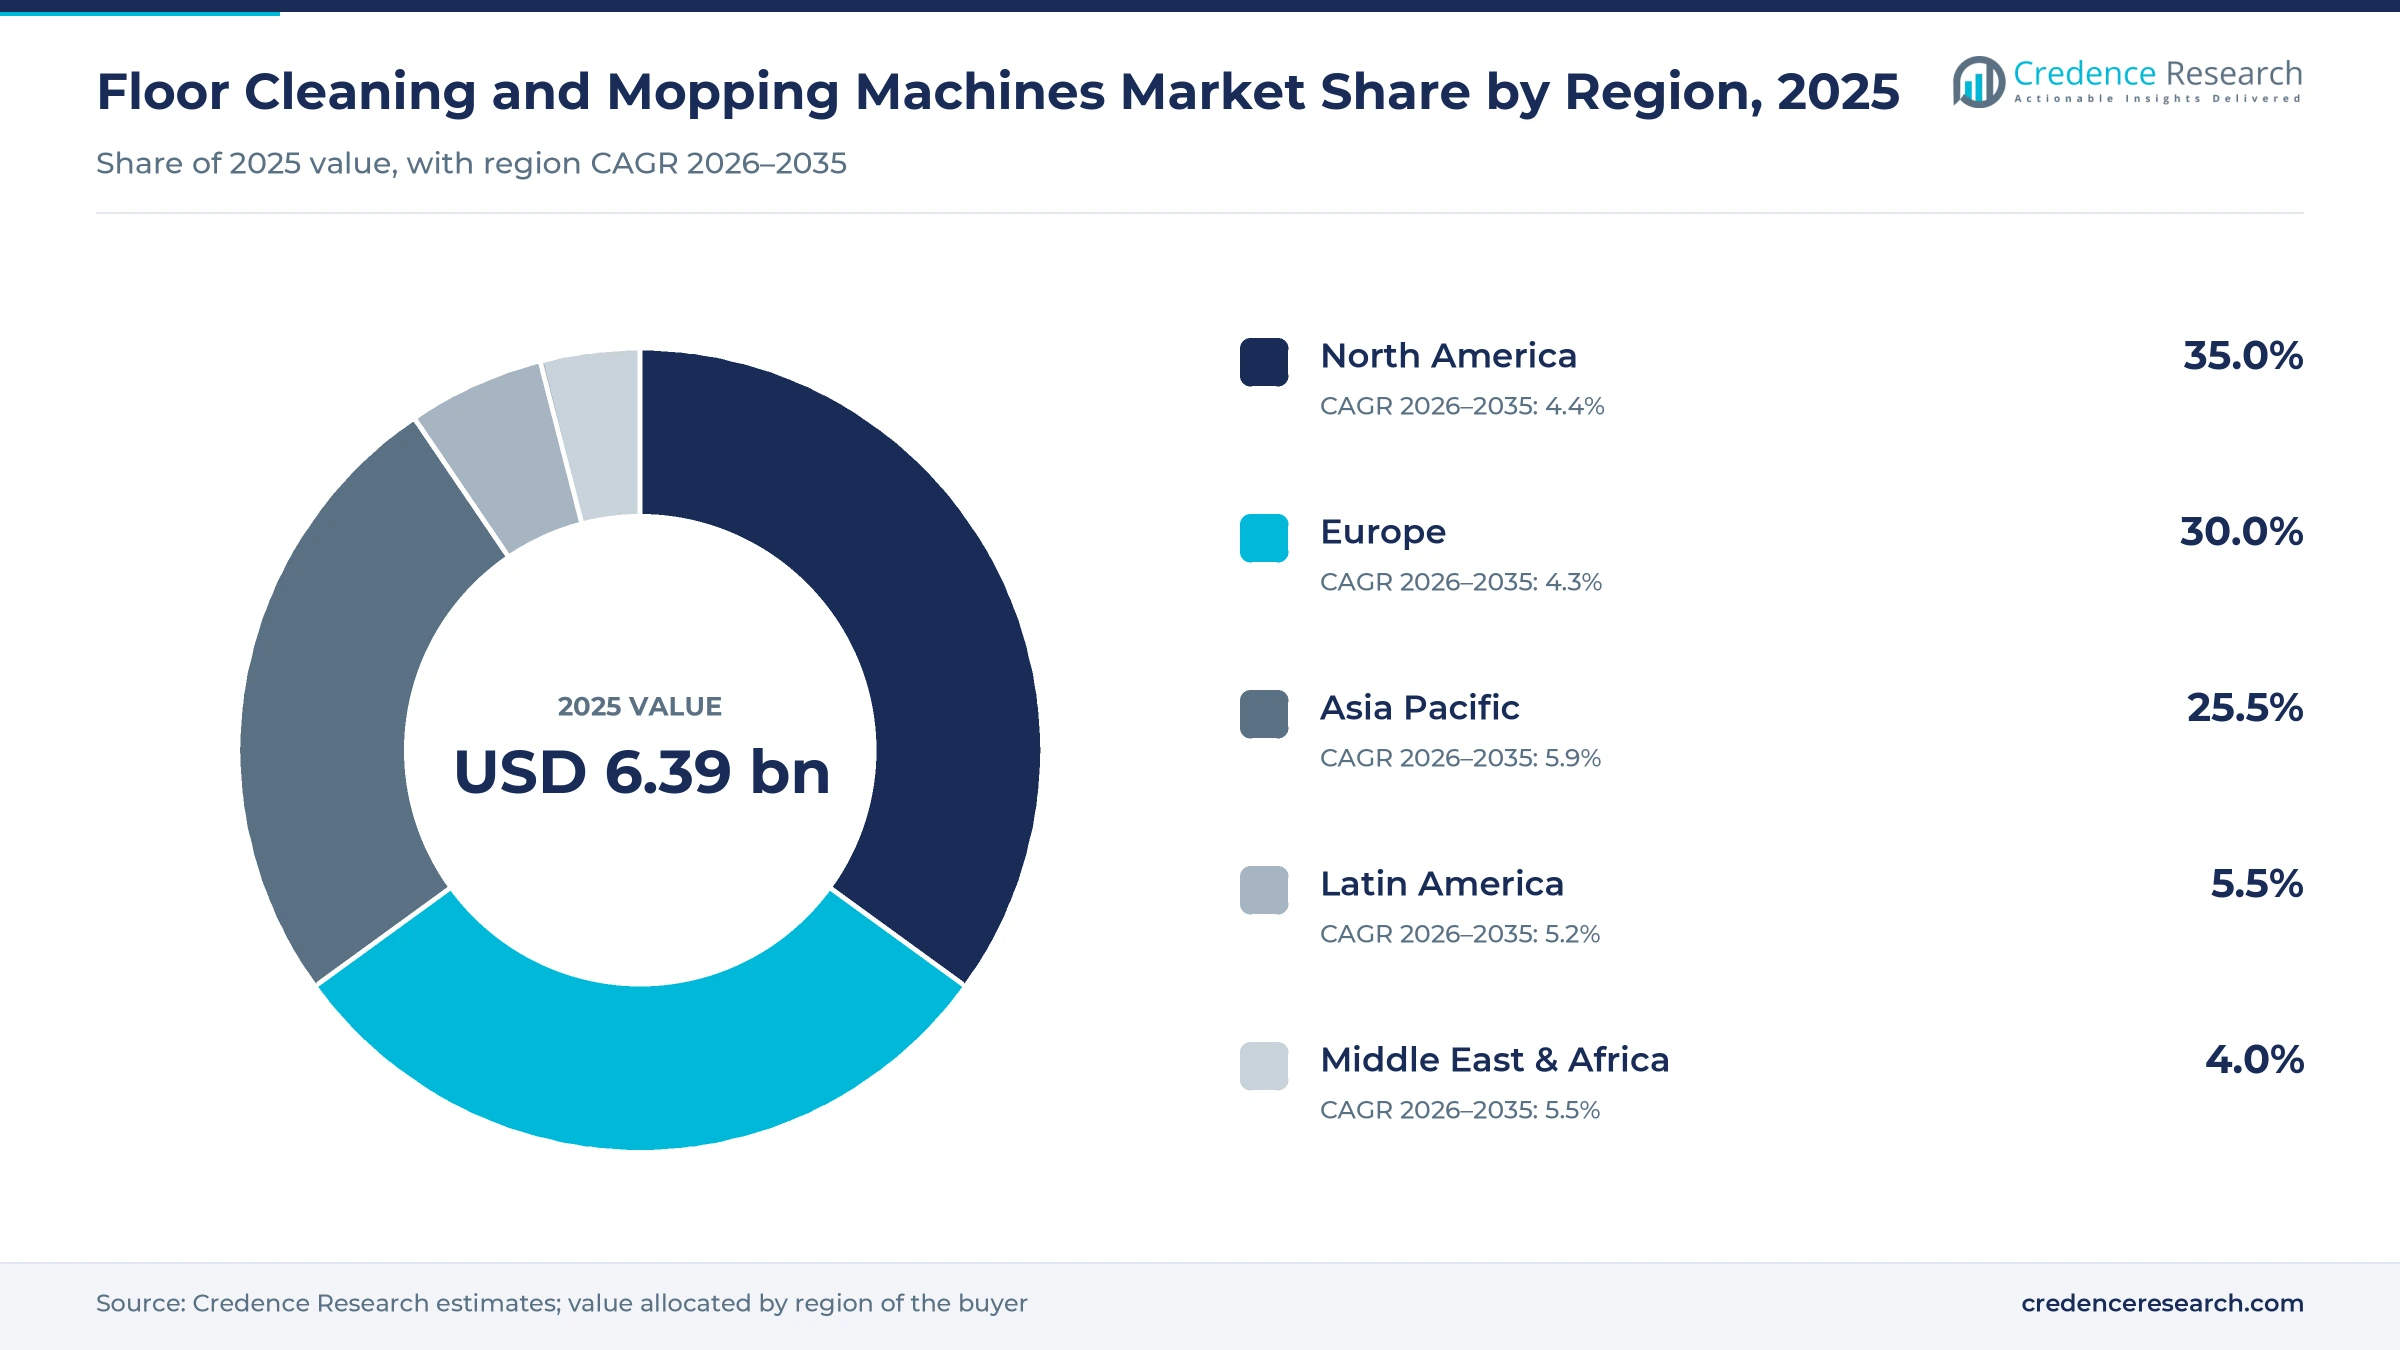
Regional demand for floor cleaning and mopping machines follows labor costs, the density of dealer and rental networks and the pace at which large sites adopt autonomous fleets. Shares and growth rates below are Credence Research estimates built from supplier footprints and public activity data.
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 2.24 | 35.0% | 4.4% |
| Europe | 1.92 | 30.0% | 4.3% |
| Asia Pacific | 1.63 | 25.5% | 5.9% |
| Latin America | 0.35 | 5.5% | 5.2% |
| Middle East & Africa | 0.26 | 4.0% | 5.5% |
North America leads on wages and contractor fleets
North America held 35.0% of 2025 value and grows at 4.4% a year, because high wages push contractors, retailers and schools to mechanize floor care. Tennant runs owned plants in Golden Valley, Minnesota and Holland, Michigan and a leased site in Louisville, Kentucky, which keeps lead times short for U.S. dealers. Its Americas organic sales fell 10.5% in 2025, which the company tied mainly to a new ERP system and a prior-year backlog release, so the dip reflects supplier disruption more than end demand. Tennant guided 3% to 6.5% organic growth for 2026 as operations normalize.
Europe combines Italian makers with direct distribution
Europe held 30.0% of 2025 value and grows at 4.3% a year, because contract cleaning is mature and buyers replace fleets on long cycles. Italy hosts a dense cluster of makers, including Fimap, Comac and Eureka, and Tennant owns plants in Venice, Cremona and Reggio Emilia for its IPC range. Nilfisk reported 2.3% organic growth in EMEA for 2025, with floor care driving growth. Tennant bought its largest Central and Eastern European distributor, TCS EMEA, in February 2024, gaining direct sales in Romania, Hungary, the Czech Republic and Slovakia.
Asia Pacific grows fastest on Chinese robot output
Asia Pacific held 25.5% of 2025 value and grows fastest at 5.9% a year, because local robot makers sell autonomous units at prices that let malls, airports and offices skip ride-on fleets, and Gausium targeted 40% to 50% higher unit sales in 2025. Tennant reported 11% organic growth in APAC in the fourth quarter of 2025, with equipment gains in Australia and China, and it operates a leased plant in Hefei. Kärcher added a production hall in Changshu, China, which positions it closer to regional buyers and to competing local makers.
Latin America relies on Brazilian production
Latin America held 5.5% of 2025 value and grows at 5.2% a year, because demand concentrates in Brazilian and Mexican retail, food processing and logistics sites. Tennant operates a leased plant in São Paulo and sells there under the Alfa brand, which gives it local cost and service advantages over importers. Public data on regional machine sales are thin, so this share carries a wider error range than the larger regions.
Middle East & Africa builds on hubs and new subsidiaries
Middle East & Africa held 4.0% of 2025 value and grows at 5.5% a year, because airports, malls and hotels in the Gulf buy large fleets while much of Africa still cleans manually. Kärcher opened a new subsidiary in Ivory Coast in 2025, and Tennant's 2024 distributor purchase, listed in the developments, extends its dealer reach into the region. No regional sales statistics were identified, so the estimate rests on supplier footprints and hub activity.
Robot launches and autonomy deals marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In February 2024, Tennant completed its acquisition of TCS EMEA, its largest distributor in Central and Eastern Europe, on Feb. 29. | Completed acquisition; it gives Tennant direct sales in four countries and a wider network into the Middle East and Africa. |
| In October 2025, Kärcher launched the KIRA B 200 autonomous scrubber-dryer for warehouses and other large floor areas. | Operational launch; Kärcher U.K. offers it for purchase or rental, with an optional docking station for unattended runs. |
| In November 2025, Nilfisk launched the VP25 robotic vacuum for offices, hotels and retail, built on its SC25 scrubber platform. | Commercial launch at ISSA 2025; available for purchase, extending Nilfisk robotics from scrubbing into carpet care. |
| In April 2026, Tennant and Brain Corp agreed to extend their robotic exclusivity by three years and release 10 new robotic products within 24 months. | Announced agreement; product releases are planned, and terms were not disclosed. |
| In August 2026, NEURA Robotics said it was acquiring all shares of ADLATUS Robotics, a German maker of cleaning and sweeping robots. | Announced acquisition; closing and terms were not disclosed at announcement. |
Lithium power, sensor navigation and docking stations
- Lithium-ion batteries replace lead-acid packs in walk-behind and robotic units, which removes watering, allows opportunity charging and lengthens runtime, although they raise the purchase price.
- LiDAR and camera navigation lets robots map sites, avoid people and repeat routes, and platforms such as BrainOS let machine makers license autonomy instead of building it.
- Docking stations refill clean water, drain dirty water and recharge robots, which turns a supervised machine into one that runs overnight without staff.
- Speed-dependent dosing adjusts water and detergent flow to travel speed, which cuts chemical use and keeps slip risk low on retail and hospital floors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Full-line makers defend dealers as robot firms scale
Competition turns on dealer coverage, service response and, increasingly, autonomy rather than on list price. Tennant, including the Nobles, IPC, Alfa and Gaomei brands, Nilfisk, including Viper and Clarke, and Kärcher cover every machine class. Hako, part of the Possehl Group, and Italian makers Fimap, Comac and Eureka compete on walk-behind and ride-on scrubbers and sweepers. Solenis took over Diversey in July 2023 and sells TASKI machines alongside cleaning chemicals, which lets it bundle equipment with consumables. Gausium and Pudu bring Chinese robot volume and lower prices, and they sell through integrators as well as directly. Brain Corp supplies autonomy software to several makers but sells no machines, so it is not profiled. Buyers of floor cleaning and mopping machines increasingly award multiyear fleet contracts that bundle machines, parts and service. The 10 companies profiled below cover full-line makers, Italian specialists, a chemicals-led supplier and robot makers.
How is the supply side organized and where do margins sit?
The supply side splits into three groups with different economics. Full-line makers such as Tennant, Nilfisk, Kärcher and Hako cover every machine class and rely on direct sales and dealers, and Tennant alone sells directly in 21 countries and through authorized distributors in more than 100. A cluster of Italian mid-size makers competes on walk-behind and ride-on value. Robot specialists such as Gausium and Pudu sell autonomous units directly and through integrators. Entry barriers sit in dealer coverage, service technicians and safety certification, and margins are highest on parts, consumables and service contracts rather than on the machines themselves.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Tennant Company | Full-line supplier | Sells scrubbers, sweepers and Brain Corp-powered robots under Tennant, Nobles and IPC |
| Nilfisk A/S | Full-line supplier | Sells scrubber-dryers, sweepers and SC25 and Liberty robots, plus Viper and Clarke |
| Alfred Kärcher SE & Co. KG | Full-line supplier | Sells scrubber-dryers, sweepers and KIRA autonomous scrubbers worldwide |
| Hako GmbH (Possehl Group) | Full-line supplier | Makes Scrubmaster scrubber-dryers and Sweepmaster sweepers in Germany |
| Solenis (Diversey, TASKI) | Chemicals-led supplier | Sells TASKI scrubbers and Ecobot and Phantas robots with cleaning chemicals |
| Fimap S.p.A. | Specialist | Italian maker of scrubber-dryers, sweepers and autonomous scrubber-dryers |
| Comac S.p.A. | Specialist | Italian maker of walk-behind and ride-on scrubber-dryers and sweepers |
| Eureka S.p.A. | Specialist | Italian maker of industrial sweepers and scrubber-dryers |
| Gausium | Robot specialist | Chinese maker of autonomous scrubbers and vacuums sold worldwide |
| Pudu Robotics | Robot specialist | Chinese maker of CC1 and BG1 cleaning robots for commercial sites |
Autonomy access will decide who keeps fleet accounts
Credence Research's view is that access to proven autonomy will decide which suppliers keep large fleet accounts over the next decade. Walk-behind and ride-on scrubbers still earn most of the value, but buyers now ask every bidder for a robotic option, fleet data and rental terms. Full-line makers hold dealer networks and service crews that robot start-ups lack, while Chinese robot makers hold price and volume. Contractors should test robots on cost per square foot before committing, and suppliers that combine service coverage with credible autonomy are best placed.
Earlier estimate rolled forward and tested on supply
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against a supply-side build of leading and regional makers' floor care activity and robot unit volumes. Regional and segment shares are Credence Research estimates based on supplier footprints, robot shipments, labor data and end-user activity. Sources include the U.S. Bureau of Labor Statistics, CDC, the American Hospital Association, the International Federation of Robotics, Airports Council International, EU-OSHA, company releases and filings, dealer list prices and trade press. No interviews or surveys were conducted for this update of the estimate.
Robots and compact scrubbers carry growth to 2035
Growth in floor cleaning and mopping machines to 2035 depends on how quickly large sites move from manual and ride-on cleaning to robot fleets, and on when commercial buyers return to normal replacement cycles. The base case assumes wages keep rising faster than machine prices, robots keep gaining share in logistics, airports and retail, and compact scrubbers keep replacing mops in small spaces. Chinese robot makers should keep gaining share in autonomous units, while Western full-line makers defend dealer and service income.
Labor costs and robot pricing set the range of outcomes
The spread of outcomes depends on how fast contractors and retailers move from pilots to robot fleets, and on whether commercial buyers resume normal replacement cycles after the 2025 slowdown. Persistent tariffs and weak commercial construction would stretch replacement cycles further. Falling robot prices, wider rental offers and continued wage growth form the main upside, especially in logistics and airports.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.5% | USD 9.14 billion | Tariffs persist and commercial buyers keep delaying ride-on and robot replacements |
| Base | 4.90% | USD 10.32 billion | Replacement cycles normalize and robots keep gaining share in large sites |
| Upside | 6.1% | USD 11.43 billion | Robot prices fall and rental fleets bring autonomy to mid-size contractors |
Frequently Asked Questions
How big is the floor cleaning and mopping machines market?
Which product type holds the largest share?
Which region leads the commercial floor cleaning machine market?
How do buyers evaluate the performance of modern floor scrubbers?
Are household hard floor cleaners included in the estimate?
Do floor machine makers supply private-label or OEM products?
How much does a robotic floor scrubber cost?
What restrains the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Walk-Behind Scrubber-Dryers
- 1.2.2 Ride-On Scrubber-Dryers
- 1.2.3 Robotic Scrubbers and Vacuums
- 1.2.4 Sweepers and Cordless Electric Brooms
- 1.2.5 Commercial Vacuum Cleaners
- 1.2.6 Others (Burnishers, Steam and Single-Disc Machines)
- 1.3 By Method
- 1.3.1 Scrubbing
- 1.3.2 Mopping
- 1.3.3 Buffing and Burnishing
- 1.3.4 Spray Cleaning
- 1.3.5 Others (Sweeping, Scarifying and Steaming)
- 1.4 By End User
- 1.4.1 Commercial (Retail, Offices and Hospitality)
- 1.4.2 Warehousing and Logistics
- 1.4.3 Industrial (Automotive, Chemical and Manufacturing)
- 1.4.4 Healthcare
- 1.4.5 Food and Beverage
- 1.4.6 Others (Education, Transport Hubs and Government)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6.39 billion → 2035: USD 10.32 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Floor Cleaning and Mopping Machines Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Floor Cleaning and Mopping Machines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Floor Cleaning and Mopping Machines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Floor Cleaning and Mopping Machines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Floor Cleaning and Mopping Machines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Floor Cleaning and Mopping Machines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Floor Cleaning and Mopping Machines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Floor Cleaning and Mopping Machines Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6.39 billion → 2035: USD 10.32 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Floor Cleaning and Mopping Machines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Walk-Behind Scrubber-Dryers
- 12.3.7.2 Ride-On Scrubber-Dryers
- 12.3.7.3 Robotic Scrubbers and Vacuums
- 12.3.7.4 Sweepers and Cordless Electric Brooms
- 12.3.7.5 Commercial Vacuum Cleaners
- 12.3.7.6 Others (Burnishers, Steam and Single-Disc Machines)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Method - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Scrubbing
- 12.4.7.2 Mopping
- 12.4.7.3 Buffing and Burnishing
- 12.4.7.4 Spray Cleaning
- 12.4.7.5 Others (Sweeping, Scarifying and Steaming)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial (Retail, Offices and Hospitality)
- 12.5.7.2 Warehousing and Logistics
- 12.5.7.3 Industrial (Automotive, Chemical and Manufacturing)
- 12.5.7.4 Healthcare
- 12.5.7.5 Food and Beverage
- 12.5.7.6 Others (Education, Transport Hubs and Government)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Floor Cleaning and Mopping Machines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Floor Cleaning and Mopping Machines Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Floor Cleaning and Mopping Machines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Floor Cleaning and Mopping Machines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tennant Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nilfisk A/S
- 18.4 Alfred Kärcher SE & Co. KG
- 18.5 Hako GmbH (Possehl Group)
- 18.6 Solenis (Diversey, TASKI)
- 18.7 Fimap S.p.A.
- 18.8 Comac S.p.A.
- 18.9 Eureka S.p.A.
- 18.10 Gausium
- 18.11 Pudu Robotics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

