
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| France Gastrointestinal Products Market Size 2023 | USD 511.44 Million |
| France Gastrointestinal Products Market, CAGR | 5.84% |
| France Gastrointestinal Products Market Size 2032 | USD 852.48 Million |
Market Overview
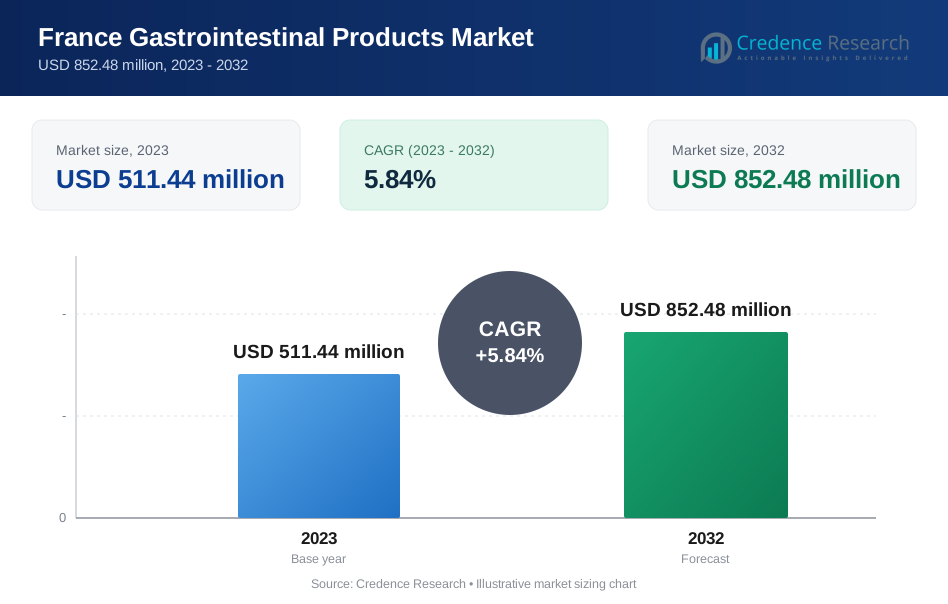
The France Gastrointestinal Products Market is projected to grow from USD 511.44 million in 2023 to USD 852.48 million by 2032, exhibiting a compound annual growth rate (CAGR) of 5.84% during the forecast period.
The France gastrointestinal products market is driven by the rising prevalence of gastrointestinal disorders, increasing awareness of digestive health, and growing demand for over-the-counter (OTC) medications. Lifestyle changes, such as unhealthy diets and sedentary habits, have significantly contributed to the surge in gastrointestinal issues, prompting greater adoption of treatment options. Additionally, advancements in pharmaceutical formulations and the introduction of innovative therapies are enhancing treatment outcomes, further fueling market growth. The aging population in France, which is more prone to digestive disorders, also plays a crucial role in driving demand. Key market trends include a shift toward natural and probiotic-based products, reflecting consumer preference for safer and holistic health solutions. The expansion of e-commerce platforms has improved product accessibility, boosting sales of gastrointestinal medications. Moreover, increasing investments in research and development are expected to bring advanced therapies to market, supporting long-term growth.
The geographical analysis of the France gastrointestinal products market highlights significant regional variations driven by healthcare infrastructure, demographic trends, and lifestyle factors. Northern France leads in product adoption due to its advanced medical facilities and robust pharmaceutical distribution network, while Southern France is witnessing increased demand due to rising awareness of digestive health and lifestyle-related disorders. Eastern and Western France also contribute substantially, with a growing focus on advanced treatments and preventive care solutions. Key players in the market, such as Guerbet, EchoSens, Medtronic, and Stryker, drive innovation through extensive research and development, introducing cutting-edge gastrointestinal devices and medications. Companies like Karl Storz, Hoya, and Smith & Nephew further strengthen the competitive landscape with diversified product portfolios and strategic collaborations. The combined efforts of these players ensure a steady influx of effective solutions to address a wide spectrum of gastrointestinal disorders, fostering growth across all regions in France.
Market Insights
- The France gastrointestinal products market was valued at USD 511.44 million in 2023 and is projected to reach USD 852.48 million by 2032, growing at a CAGR of 5.84%.
- Increasing prevalence of gastrointestinal disorders, such as IBS and GERD, is a major driver of market growth.
- Rising consumer awareness about digestive health and preventive care is leading to greater adoption of over-the-counter medications and natural products.
- The shift toward probiotic-based and natural gastrointestinal products reflects changing consumer preferences for holistic health solutions.
- High competition and market saturation are restraining growth, with established players dominating the market.
- Stringent regulatory frameworks in France create challenges for manufacturers in terms of compliance and product innovation.
- Regional markets like Northern and Southern France are witnessing strong growth due to improved healthcare access and increasing awareness of digestive health.
Market Drivers
Increasing Prevalence of Gastrointestinal Disorders
The growing incidence of gastrointestinal disorders such as irritable bowel syndrome (IBS), gastroesophageal reflux disease (GERD), and inflammatory bowel disease (IBD) is a key driver of the France gastrointestinal products market. Changing dietary habits, stress, and a rise in sedentary lifestyles have led to an increase in these conditions. This has created a significant demand for effective treatments, including antacids, laxatives, and proton pump inhibitors, to alleviate symptoms and improve quality of life. For instance, the Survey of Digestive Health Across Europe highlights that the prevalence of gastrointestinal disorders in France has been rising, driven by lifestyle changes and dietary habits. The healthcare system's focus on addressing these common disorders has further propelled the consumption of gastrointestinal products.
Rising Awareness of Digestive Health
Heightened awareness about digestive health and the importance of early diagnosis and treatment of gastrointestinal issues are driving market growth. Educational campaigns and initiatives by healthcare providers and pharmaceutical companies have played a pivotal role in informing the public about the symptoms and consequences of untreated digestive disorders. For instance, United European Gastroenterology (UEG) has been actively raising awareness about digestive health across Europe, including France, through various campaigns and initiatives. This has led to an increased willingness among consumers to seek medical advice and use over-the-counter (OTC) medications, further boosting the demand for gastrointestinal products in France.
Preference for Natural and Probiotic-Based Solutions
A significant trend influencing the market is the shift toward natural and probiotic-based gastrointestinal products. Consumers are increasingly opting for solutions that promote gut health without the side effects associated with conventional medications. Probiotic supplements and natural digestive aids have gained traction due to their perceived safety and holistic health benefits. This shift in consumer preferences has encouraged pharmaceutical companies to innovate and expand their product portfolios to include such alternatives, driving market growth.
Aging Population and Increased Healthcare Spending
France’s aging population, which is more susceptible to gastrointestinal issues, is another crucial driver for the market. Older adults often require ongoing treatment for chronic digestive conditions, leading to sustained demand for gastrointestinal medications. Coupled with increased healthcare spending and improved access to advanced treatments, this demographic trend ensures steady growth in the market. The focus on enhancing healthcare infrastructure and making treatments accessible to all segments of the population further strengthens the market’s outlook.
Market Trends
Emphasis on Research and Development (R&D)
Another key trend shaping the market is the increased focus on research and development activities to introduce advanced and effective gastrointestinal products. Pharmaceutical companies are investing heavily in creating innovative therapies to address unmet medical needs. This includes targeted treatments for chronic conditions like inflammatory bowel disease and GERD. For instance, the France Gastrointestinal Diseases Drug Development Market report highlights significant investments in R&D to develop targeted treatments for chronic conditions like inflammatory bowel disease and GERD. Such advancements are expected to enhance treatment outcomes and patient satisfaction, thereby strengthening the market’s long-term growth prospects.
Expansion of Over-the-Counter (OTC) Medications
The rise in the availability and adoption of over-the-counter gastrointestinal medications marks another significant trend. With growing awareness of digestive health and easier access to OTC products through pharmacies and online platforms, consumers are increasingly self-managing minor digestive issues. This trend has encouraged manufacturers to invest in marketing and distribution strategies to capitalize on this growing segment. The convenience and cost-effectiveness of OTC solutions have further fueled their acceptance among a broad consumer base.
Shift Towards Probiotic and Functional Products
One of the prominent trends in the France gastrointestinal products market is the increasing demand for probiotic and functional products. Consumers are becoming more conscious of the long-term impact of medications on gut health and are gravitating toward solutions that enhance the gut microbiome naturally. Probiotics, prebiotics, and functional foods that promote digestive health are gaining popularity as they offer preventive care and fewer side effects. This trend is driving innovation in the market, with companies introducing novel formulations to cater to this growing consumer preference.
Growing Influence of E-Commerce Platforms
The rapid growth of e-commerce has transformed the distribution landscape for gastrointestinal products in France. Online platforms offer a convenient way for consumers to access a wide range of products, including prescription and OTC medications. These platforms also provide detailed product information, enabling informed purchasing decisions. For instance, the rise of e-commerce has significantly improved product accessibility and increased competition among manufacturers to enhance their digital presence. The rise of e-commerce has not only improved product accessibility but also increased competition among manufacturers to enhance their digital presence and reach a wider audience, further boosting market growth.
Market Challenges Analysis
High Competition and Market Saturation
The France gastrointestinal products market faces significant challenges due to high competition and market saturation. With numerous pharmaceutical companies offering a wide range of products, the market has become increasingly crowded, making it difficult for new entrants to establish a foothold. Established players dominate the market with strong brand recognition and extensive distribution networks, leaving limited room for smaller firms or innovative products to gain traction. This intense competition also exerts downward pressure on pricing, reducing profit margins for manufacturers and creating a challenging environment for growth. For instance, a report by the French Competition Authority highlights the intense competition in the pharmaceutical sector, which has led to significant price sensitivity among consumers. Additionally, consumers often rely on trusted brands, making it harder for newer or less recognized products to achieve market penetration.
Stringent Regulatory Framework and Compliance Issues
Stringent regulatory requirements and compliance issues pose another significant hurdle for market participants. France’s healthcare and pharmaceutical sectors are governed by strict regulations to ensure patient safety and product efficacy. These regulations necessitate extensive testing, clinical trials, and approvals, which can delay the launch of new products and increase operational costs. For instance, the National Agency for the Safety of Medicines and Health Products (ANSM) requires comprehensive clinical trials and detailed safety evaluations for new drug approvals, which can extend the approval timeline significantly. Moreover, compliance with evolving guidelines and labeling standards adds complexity for manufacturers, particularly those looking to introduce innovative or natural gastrointestinal products. This regulatory burden can deter investments in research and development, hindering the pace of innovation in the market. Companies must navigate these challenges effectively to maintain competitiveness and sustain long-term growth.
Market Opportunities
Growing Demand for Personalized Medicine
The France gastrointestinal products market offers significant opportunities through the increasing adoption of personalized medicine. Advances in diagnostic technologies and a deeper understanding of individual patient profiles have enabled the development of tailored treatment solutions. Personalized therapies for gastrointestinal conditions, such as irritable bowel syndrome (IBS) and inflammatory bowel disease (IBD), can provide enhanced efficacy and reduced side effects, addressing unmet medical needs. This shift toward precision medicine is expected to attract investments in research and development, opening avenues for pharmaceutical companies to differentiate their offerings and capture market share. Additionally, integrating digital health tools, such as wearable devices and apps for monitoring digestive health, presents a unique opportunity to enhance patient engagement and treatment outcomes.
Expansion of Natural and Probiotic-Based Products
The growing consumer preference for natural and probiotic-based solutions presents another lucrative opportunity in the France gastrointestinal products market. Consumers are increasingly opting for safer, holistic approaches to managing digestive health, driving demand for probiotic supplements, functional foods, and plant-based formulations. This trend aligns with the broader shift toward preventive healthcare, offering companies a chance to innovate and expand their product portfolios to cater to this demand. Furthermore, the increasing popularity of e-commerce platforms provides an effective channel for reaching health-conscious consumers and promoting these products. Companies that can successfully combine innovation with accessibility are well-positioned to capitalize on this growing segment and strengthen their market presence.
Market Segmentation Analysis:
By Devices:
The France gastrointestinal products market is segmented by devices, including endoscopy devices, ablation devices, motility testing devices, biopsy devices, and stenting devices. Endoscopy devices dominate this segment, driven by their widespread use in diagnosing and managing gastrointestinal disorders, including cancers and inflammatory diseases. Technological advancements in imaging and minimally invasive techniques have significantly improved diagnostic accuracy and patient outcomes, boosting their adoption. Ablation devices and stenting devices are also gaining traction due to their effectiveness in managing complex gastrointestinal conditions such as cancers and strictures. Meanwhile, motility testing devices and biopsy devices play a critical role in diagnosing functional and structural abnormalities, further supporting the growth of this segment.
By Indications:
Based on indications, the market is categorized into gastrointestinal cancers, gastroesophageal reflux disease (GERD), irritable bowel syndrome (IBS), inflammatory bowel disease (IBD), and other diseases. Gastrointestinal cancers represent a significant share due to increasing incidence rates and the critical need for early diagnosis and treatment. GERD and IBS are also key segments, fueled by lifestyle changes, dietary habits, and stress-related conditions. The IBD segment is driven by growing awareness and advancements in targeted therapies. Other diseases, including peptic ulcers and motility disorders, contribute to market growth, reflecting the broad spectrum of gastrointestinal issues addressed by available products and therapies.
Segments:
Based on Devices:
- Endoscopy Devices
- Ablation Devices
- Motility Testing Devices
- Biopsy Devices
- Stenting Devices
Based on Indications:
- Gastrointestinal Cancers
- Gastroesophageal Reflux Disease
- Irritable Bowel Syndrome
- Inflammatory Bowel Disease
- Other Diseases
Based on End-User:
- Hospitals
- Ambulatory Surgical Centers & Independent Surgical Centers
- Clinics
- Other End Users
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds the largest market share in the gastrointestinal products market, accounting for approximately 35% in 2023. This dominance is attributed to the region's advanced healthcare infrastructure, widespread accessibility to medical facilities, and a high prevalence of gastrointestinal disorders. Urban centers like Paris and Lille house renowned medical institutions and research centers, driving innovation and adoption of advanced gastrointestinal therapies. The region also benefits from a well-established pharmaceutical distribution network, ensuring the timely availability of medications and devices. The growing aging population, which is more susceptible to digestive health issues, further fuels demand for gastrointestinal products in Northern France.
Southern France
Southern France holds a significant share of the market, contributing to about 25% of the overall revenue. This growth is driven by increasing awareness of digestive health and the rising prevalence of lifestyle-related gastrointestinal conditions such as GERD and IBS. Regions like Marseille and Nice have seen a surge in the adoption of natural and probiotic-based gastrointestinal products, reflecting consumer preference for holistic health solutions. The tourism-driven economy in Southern France has also led to better healthcare facilities and pharmacies catering to both residents and visitors, thereby supporting market growth. Additionally, government initiatives to improve healthcare access in rural areas of the south are expected to further expand the market.
Eastern France
Eastern France contributes approximately 20% to the gastrointestinal products market, driven by the expansion of advanced treatment options and diagnostic technologies. Cities like Strasbourg are emerging as hubs for medical innovation, particularly in minimally invasive procedures such as endoscopy and ablation therapies. The presence of research-oriented healthcare institutions and partnerships with global pharmaceutical companies have accelerated the development and availability of cutting-edge gastrointestinal products. Increasing healthcare spending and an aging population in this region are also key drivers, creating opportunities for growth in both urban and semi-urban areas of Eastern France.
Western France
Western France accounts for about 20% of the market share, supported by rising adoption of preventive care measures and a growing focus on natural and probiotic-based solutions. Key urban centers like Nantes and Rennes are experiencing increased consumer interest in over-the-counter medications and dietary supplements targeting digestive health. This trend is further amplified by the region's robust e-commerce channels, which provide convenient access to a wide range of gastrointestinal products. Efforts by healthcare providers to educate the population about early diagnosis and treatment of digestive disorders are also fostering market growth in Western France, with projections indicating steady expansion in the coming years.
Key Player Analysis
- Guerbet
- EchoSens
- Micro-Tech UK
- Ethicon Endo-Surgery
- Medtronic
- Stryker
- Smith & Nephew
- Karl Storz
- Hoya
- Company 10
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The competitive landscape of the France gastrointestinal products market is marked by the presence of several leading players, including Guerbet, EchoSens, Micro-Tech UK, Ethicon Endo-Surgery, Medtronic, Stryker, Smith & Nephew, Karl Storz, and Hoya. These companies are highly focused on product innovation, strategic partnerships, and expanding their portfolios to meet the rising demand for advanced gastrointestinal treatments. Companies in this market are constantly investing in research and development to introduce advanced gastrointestinal devices, such as endoscopy, biopsy, and ablation devices, which are crucial for diagnosing and treating gastrointestinal disorders. The rise in minimally invasive procedures has also spurred competition, as manufacturers develop solutions that improve treatment outcomes while minimizing recovery times for patients. Furthermore, with increasing consumer awareness about digestive health, companies are innovating in the areas of probiotics, functional foods, and over-the-counter medications, catering to a broader range of consumers looking for preventive care and natural health solutions. The market is characterized by the dominance of a few large players, but the entry of new firms focusing on specialized or niche products is intensifying competition. For instance, the French Competition Authority notes that the entry of new firms focusing on niche products is increasing competition in the market. Companies are also expanding their presence in various regions, particularly in Northern and Southern France, where demand for gastrointestinal products is growing due to improved healthcare infrastructure and rising awareness of digestive health. The competitive environment is further driven by evolving regulatory standards and the need for companies to meet stringent product quality and safety requirements.
Recent Developments
- In April 2023, Boston Scientific announced the launch of the EXALT Model B Single-use Bronchoscope, which expands its single-use endoscopy portfolio. This device is designed for diagnostic and therapeutic bronchoscopy procedures and offers high-resolution imaging and precise control.
- In March 2023, Polifarma Spa expanded its gastrointestinal portfolio through a long-term distribution agreement with Devintec Pharma Sagl, a Lugano-based company known for pioneering substance-based medical devices and the Gelsectan brand.
- In April 2023, Italian pharmaceutical innovator Azienda Farmaceutica Italiana partnered with TannerLAC, Inc. to distribute Hepilor, a medical device designed to protect the digestive system mucosa, throughout Latin America.
- In May 2022, Dr. Reddy’s Laboratories Ltd. announced a partnership with South Korea’s HK inno.N Corporation to supply and commercialize HK inno.N’s patented novel molecule, Tegoprazan, for treating gastrointestinal diseases in India and six key emerging markets.
- In March 2022, AbbVie Inc. received U.S. FDA approval for its novel drug, RINVOQ (upadacitinib), for the treatment of moderately to severely active ulcerative colitis.
Market Concentration & Characteristics
The market concentration of France gastrointestinal products is relatively high, with a few leading players commanding a significant share of the market. These players have established strong brand recognition, extensive distribution networks, and comprehensive product portfolios, allowing them to dominate the sector. However, the market is also characterized by a mix of large multinational corporations and smaller specialized firms, creating a competitive environment. The presence of both global giants and niche companies fosters innovation, as manufacturers strive to meet the diverse needs of patients and healthcare providers.
The characteristics of the French gastrointestinal products market reflect a growing demand for advanced diagnostic and therapeutic solutions, driven by an increasing prevalence of gastrointestinal disorders such as GERD, IBS, and IBD. The market is also witnessing a shift toward minimally invasive procedures, which has led to the development of innovative devices like endoscopes, biopsy tools, and ablation systems. In addition, the rising consumer preference for preventive healthcare and natural products, including probiotics and dietary supplements, is shaping market trends. Regulatory compliance and safety standards are also key characteristics of the market, as companies must navigate stringent requirements to ensure the safety and efficacy of their products. Overall, the French gastrointestinal products market is dynamic, with a balance of strong market leaders and emerging players contributing to its growth and innovation.
Report Coverage
The research report offers an in-depth analysis based on Devices, Indications, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The France gastrointestinal products market is expected to grow steadily due to increasing demand for advanced diagnostic and therapeutic solutions.
- Rising awareness about gastrointestinal health and the importance of early diagnosis will drive product adoption across regions.
- The shift towards minimally invasive procedures, including endoscopy and ablation treatments, will continue to shape the market.
- Probiotic-based products and natural supplements will see increased demand as consumers seek preventive and holistic health solutions.
- Aging population in France will contribute to the rising prevalence of gastrointestinal disorders, further boosting market growth.
- Technological advancements in diagnostic imaging, such as AI and robotics, will enhance the accuracy and efficiency of gastrointestinal treatments.
- Personalized medicine approaches, offering tailored treatments based on genetic profiles, will gain traction in the market.
- Strategic collaborations and acquisitions by leading companies will intensify competition and foster innovation in product development.
- Increased healthcare spending and improved access to treatment in rural areas will support market expansion in underserved regions.
- Stringent regulatory standards will continue to ensure the safety and quality of gastrointestinal products, driving consumer confidence and market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Gastrointestinal Products market?
What factors are driving the growth of the France Gastrointestinal Products market?
What are the key segments within the France Gastrointestinal Products market?
What are some challenges faced by the France Gastrointestinal Products market?
Who are the major players in the France Gastrointestinal Products market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Gastrointestinal Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Gastrointestinal Products Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 511.44 million → 2032: USD 852.48 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Gastrointestinal Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Gastrointestinal Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Gastrointestinal Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Gastrointestinal Products Market Drivers
- 3.3 France Gastrointestinal Products Market Restraints & Challenges
- 3.4 France Gastrointestinal Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Gastrointestinal Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Gastrointestinal Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Gastrointestinal Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Gastrointestinal Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Gastrointestinal Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Gastrointestinal Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Gastrointestinal Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Gastrointestinal Products Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Gastrointestinal Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Gastrointestinal Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Gastrointestinal Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Gastrointestinal Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Gastrointestinal Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Gastrointestinal Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Gastrointestinal Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Gastrointestinal Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Gastrointestinal Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Gastrointestinal Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Gastrointestinal Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
