
Market Overview
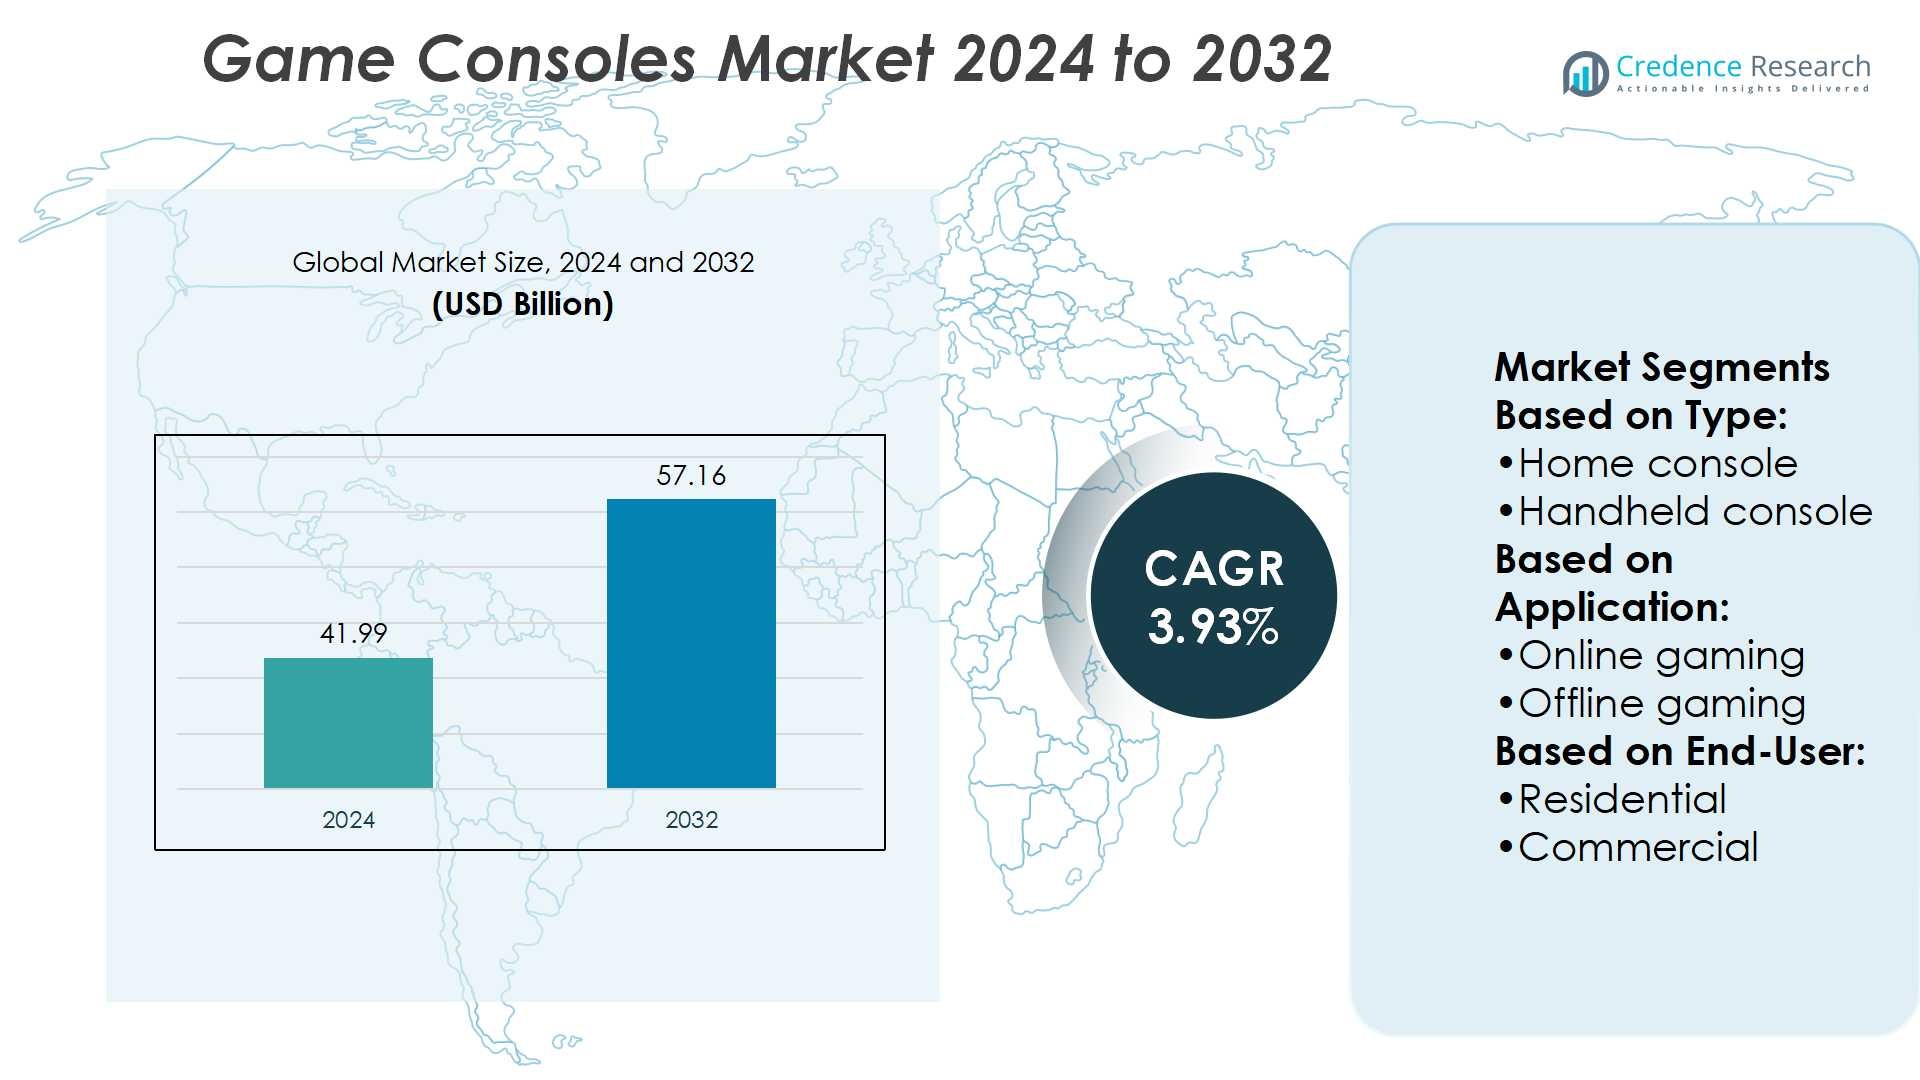
Game Consoles Market size was valued at USD 41.99 billion in 2024 and is anticipated to reach USD 57.16 billion by 2032, at a CAGR of 3.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Game Consoles Market Size 2024 | USD 41.99 Billion |
| Game Consoles Market, CAGR | 3.93% |
| Game Consoles Market Size 2032 | USD 57.16 Billion |
The Game Consoles Market grows through strong drivers and evolving trends that reshape global gaming. Rising demand for immersive experiences, high-performance hardware, and exclusive content strengthens adoption. Subscription models and digital ecosystems create recurring revenue streams while expanding player engagement. Esports popularity and online multiplayer services boost visibility and community-driven growth. Trends such as cloud gaming, cross-platform compatibility, and hybrid console demand reflect shifting consumer preferences. Integration of VR, AR, and AI enhances gaming realism and personalization. Sustainability and energy-efficient designs further influence development. The market continues to advance as companies invest in innovation, accessibility, and long-term user loyalty.
The Game Consoles Market shows strong geographical diversity, with Asia-Pacific leading through high adoption and esports growth, North America maintaining dominance with advanced infrastructure and premium console demand, and Europe recording steady expansion supported by established gaming communities. Latin America and the Middle East & Africa display emerging potential driven by rising internet access and younger populations. Key players shaping the market include Sony, Microsoft, Nintendo, Sega, Valve Corporation, ASUS, Razer, Logitech, Ayaneo, and SNK Corporation.
Market Insights
- The Game Consoles Market size was USD 41.99 billion in 2024 and will reach USD 57.16 billion by 2032, growing at a CAGR of 3.93%.
- Rising demand for immersive experiences, high-performance hardware, and exclusive content drives steady adoption.
- Cloud gaming, hybrid console demand, and cross-platform compatibility reflect major consumer-driven trends.
- Strong competition exists, with companies focusing on digital ecosystems, subscription services, and innovation to capture share.
- High development costs, semiconductor shortages, and pricing pressures act as restraints to wider growth.
- Asia-Pacific leads with esports-driven adoption, North America dominates with premium demand, and Europe records stable growth.
- Latin America and the Middle East & Africa present emerging opportunities supported by rising internet penetration and young populations.
Market Drivers
Growing Demand for Immersive Gaming Experiences Drives Hardware Advancements
The Game Consoles Market grows through rising consumer interest in immersive experiences. High-resolution graphics, faster frame rates, and real-time rendering drive demand for advanced consoles. Companies integrate powerful GPUs and CPUs to deliver seamless performance. Expanding libraries of visually rich titles reinforce this momentum. Competitive differentiation often relies on exclusive content and hardware superiority. It creates consistent pressure for innovation across the industry.
- For instance, Valve’s Steam Deck integrates a custom AMD APU featuring a quad-core/8-thread Zen 2 CPU clocked at 2.4–3.5 GHz and an RDNA 2 GPU delivering 1.6 TFLOPS of FP32 performance, enabling smooth AAA gaming experiences on a handheld device.
Expanding Online Gaming Ecosystems Enhance Market Growth
The integration of online services significantly strengthens the Game Consoles Market. Platforms offer multiplayer options, digital downloads, and subscription-based access to games. These services build recurring revenue streams for manufacturers and enhance user engagement. Cloud connectivity allows players to access titles across devices. Growing social interaction within gaming networks supports community-driven adoption. It reinforces customer loyalty and encourages longer console lifecycles.
- For instance, Sega’s original Phantasy Star Online on the Dreamcast launched with an initial deployment of 20 servers, scaled up to support 36,000 concurrent players at peak usage.
Rising Popularity of Esports and Competitive Gaming Creates New Opportunities
Esports expansion strongly influences the Game Consoles Market. Competitive gaming demands advanced hardware with minimal latency and high-speed processing. Leading brands sponsor tournaments and form partnerships with esports organizations. These initiatives increase brand visibility and drive console adoption among younger audiences. High-profile events showcase console capabilities to global audiences. It positions consoles as essential tools for aspiring professionals and dedicated fans.
Strong Influence of Technological Convergence and Cross-Platform Play
Technological convergence plays a central role in shaping the Game Consoles Market. Cross-platform compatibility enables users to engage with friends regardless of hardware choice. This flexibility supports broader adoption and reduces fragmentation in gaming communities. Integration of VR, AR, and AI elevates user experiences. Streaming services and backward compatibility further extend console value. It allows consumers to view consoles as multi-functional entertainment hubs.
Market Trends
Growing Adoption of Cloud Gaming and Digital Distribution Models
The Game Consoles Market reflects a steady transition toward cloud gaming and digital distribution. Consumers increasingly prefer downloading or streaming titles instead of purchasing physical discs. Subscription services provide access to large libraries at affordable costs. Major console makers invest heavily in cloud infrastructure to deliver seamless gameplay. Digital-first strategies also reduce reliance on retail channels. It reshapes how developers and publishers design and distribute content.
- For instance, ASUS provides server infrastructure for Boosteroid’s cloud gaming platform, which operates across 27 data center points of presence and supports over 6 million users in Europe, North and South America.
Expanding Role of Cross-Platform Compatibility and Shared Gaming Communities
Cross-platform play continues to shape the Game Consoles Market by unifying gaming experiences. Players demand the ability to interact with friends across devices without restrictions. Leading companies support this by forming partnerships with developers and online platforms. Cross-play reduces community fragmentation and increases engagement in multiplayer titles. Strong integration across ecosystems enhances customer loyalty. It establishes consoles as central gateways to broader gaming networks.
- For instance, Helldivers 2 published by Sony Interactive Entertainment achieved a peak concurrent player count of over 450,000 on Steam.The game surpassed 15 million units sold globally.
Increasing Integration of Virtual Reality, Augmented Reality, and AI Features
The Game Consoles Market experiences growth through rising integration of VR, AR, and AI. VR headsets provide immersive environments that redefine entertainment standards. AR capabilities add interactive layers to gameplay and encourage new applications. AI-driven personalization improves in-game experiences by adapting content to individual preferences. Hardware makers collaborate with technology providers to expand these advanced features. It creates differentiation in a competitive environment and strengthens consumer appeal.
Rising Influence of Esports and Streaming Culture on Console Adoption
Esports and live-streaming culture exert strong influence over the Game Consoles Market. Competitive gaming elevates hardware demand with emphasis on speed and reliability. Social platforms like Twitch and YouTube amplify visibility of console-based titles. Gamers showcase performance capabilities to large global audiences. The combination of esports and streaming fuels adoption among younger demographics. It positions consoles as cultural hubs where competition and entertainment converge.
Market Challenges Analysis
High Development Costs and Supply Chain Constraints Impact Market Stability
The Game Consoles Market faces challenges from high production costs and global supply chain issues. Advanced components such as GPUs, processors, and memory modules require significant investment. Semiconductor shortages disrupt manufacturing cycles and delay product launches. Rising raw material costs increase retail prices, reducing affordability in price-sensitive regions. Companies must balance innovation with profitability while managing volatile supply conditions. It creates uncertainty for both manufacturers and consumers who expect timely product availability.
Intense Competition and Shifts Toward Alternative Gaming Platforms
The Game Consoles Market also struggles with fierce competition and shifting consumer preferences. Mobile gaming, cloud-based platforms, and PC gaming attract a growing share of users. Strong demand for flexible and low-cost alternatives challenges traditional console sales. Competitive pressure forces companies to invest in exclusive titles and advanced features. Market saturation in developed economies further limits growth opportunities. It drives manufacturers to explore new services and subscription models to maintain relevance.
Market Opportunities
Expansion of Subscription Services and Cloud Gaming Platforms
The Game Consoles Market benefits from strong opportunities in subscription-based and cloud gaming models. Growing demand for affordable access to large content libraries supports this shift. Major brands invest in services that combine digital downloads with cloud access. These platforms extend console lifecycles while attracting diverse user groups. Emerging markets with rising internet penetration create new revenue streams. It allows console makers to strengthen recurring income and broaden their customer base.
Integration of Advanced Technologies and Emerging Regional Markets
The Game Consoles Market gains opportunities through adoption of VR, AR, and AI-driven experiences. Advanced features enhance gameplay and differentiate consoles from alternative platforms. Partnerships with developers expand innovation and generate exclusive content. Emerging markets in Asia-Pacific, Latin America, and Africa show rising demand for interactive entertainment. Growing disposable incomes and urbanization support adoption in these regions. It positions console makers to capture untapped audiences and accelerate long-term growth.
Market Segmentation Analysis:
By Type
The Game Consoles Market divides into home consoles, handheld consoles, and hybrid consoles. Home consoles dominate due to their powerful hardware, large storage, and immersive gaming experiences. These devices remain popular among core gamers who prioritize high-quality graphics and exclusive titles. Handheld consoles attract users seeking portability and accessibility, especially in regions with high mobile gaming adoption. Hybrid consoles combine the strengths of both, offering flexibility for users to switch between handheld and docked modes. It creates strong appeal for households that prefer versatile entertainment options, strengthening adoption across diverse demographics.
- For instance, The AYANEO 2 features an AMD Ryzen 7 6800U APU, 16 GB or 32 GB of LPDDR5-6400 memory, an RX 680M GPU delivering approximately 3.379 TFLOPS, powered by a 50.25 Whr battery in a 680 g chassis.
By Application
The Game Consoles Market segments by online and offline gaming applications. Online gaming records strong growth with increasing demand for multiplayer titles, esports, and streaming platforms. Players value access to live services, downloadable content, and subscription-based ecosystems. This segment benefits from cloud integration and rising social interaction in gaming networks. Offline gaming retains importance, appealing to users in areas with limited connectivity or those who prefer single-player experiences. It ensures consoles maintain relevance among traditional gamers while adapting to evolving digital trends.
- For instance, Microsoft’s Xbox Game Pass has grown to over 35 million subscribers with cloud gaming enabling access to hundreds of titles across Xbox, PC, and mobile devices.
By End User
The Game Consoles Market also classifies by residential and commercial users. Residential usage dominates, driven by rising consumer demand for interactive entertainment at home. Families and individual gamers invest in consoles that deliver immersive experiences and extensive content libraries. Commercial usage emerges in gaming cafés, esports arenas, and entertainment centers. These environments rely on consoles to attract competitive players and provide high-quality gaming setups. It highlights opportunities for manufacturers to target institutional buyers and expand market reach beyond households.
Segments:
Based on Type:
- Home console
- Handheld console
Based on Application:
- Online gaming
- Offline gaming
Based on End-User:
- Residential
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds nearly 24–25% of the Game Consoles Market in 2024. The region benefits from strong consumer spending, advanced broadband networks, and early adoption of next-generation consoles. Leading manufacturers focus on this region by releasing exclusive titles and promoting subscription services such as online passes and game libraries. Esports and streaming culture also strengthen demand, making consoles a household essential. Consumers in the United States and Canada prefer home consoles with powerful hardware and large storage, ensuring continued dominance of premium models. It highlights the region’s role as a major driver of revenue and innovation in the global landscape.
Europe
Europe accounts for around 20–25% of the Game Consoles Market. The region shows steady growth supported by established gaming communities and widespread broadband penetration. Countries like the United Kingdom, Germany, and France lead adoption due to strong demand for high-quality gaming systems. Governments support local developers through tax incentives, adding to content diversity. Esports tournaments and cross-platform play expand user engagement across the region. Players value a balance of online and offline gaming options, making Europe an attractive but competitive space for manufacturers. It secures Europe’s position as a stable and mature market with consistent demand.
Asia-Pacific
Asia-Pacific dominates the Game Consoles Market with nearly 46–47% share. Rising disposable incomes, rapid urbanization, and increasing internet access fuel adoption across key countries such as China, Japan, and South Korea. Esports popularity drives high sales of both home and handheld consoles, while hybrid models attract younger players. Companies form partnerships with local developers to create region-specific content that appeals to cultural preferences. Affordable broadband and mobile penetration support cloud gaming growth, expanding console utility. It positions Asia-Pacific as the largest and fastest-growing regional market with significant long-term potential.
Latin America
Latin America represents roughly 5–6% of the Game Consoles Market. Growth is supported by rising internet usage and increased demand for affordable entertainment. Brazil and Mexico lead in console adoption, driven by a growing youth population. However, high import tariffs and pricing challenges limit broader accessibility. Consumers often favor handheld and hybrid consoles due to cost efficiency and portability. Esports events and gaming cafés help expand awareness across urban areas. It reflects a promising yet cost-sensitive region with steady growth potential.
Middle East & Africa
The Middle East & Africa account for nearly 3–4% of the Game Consoles Market. Rising internet penetration, a growing young population, and expanding retail infrastructure support console sales. Countries like the UAE, Saudi Arabia, and South Africa drive demand through increasing interest in esports and online gaming. Pricing sensitivity and limited broadband coverage remain key challenges in rural areas. Manufacturers focus on localized pricing strategies and promotional campaigns to attract consumers. Handheld and hybrid consoles gain traction due to affordability and mobility. It shows that MEA is an emerging region with gradual but promising opportunities.
Key Player Analysis
- Valve Corporation
- Sega
- ASUS
- Sony
- Ayaneo
- Microsoft
- Razer
- Logitech
- Nintendo
- SNK Corporation
Competitive Analysis
The Game Consoles Market players including Sony, Microsoft, Nintendo, Sega, Valve Corporation, ASUS, Razer, Logitech, Ayaneo, and SNK Corporation. The Game Consoles Market remains highly competitive, driven by constant innovation, exclusive content, and ecosystem development. Companies focus on enhancing hardware performance, building strong digital service platforms, and expanding subscription-based models to attract and retain users. Hybrid and handheld devices gain traction as consumers demand flexibility and portability alongside traditional home consoles. Advancements in VR, AR, and cloud gaming create new opportunities for differentiation and customer engagement. Firms also prioritize cross-platform compatibility and community-driven features to strengthen loyalty. The competition highlights a clear emphasis on delivering immersive experiences while balancing affordability, accessibility, and long-term growth strategies.
Recent Developments
- In June 2025, Microsoft announced a strategic multi-year partnership with AMD to co-engineer custom silicon for its next-generation Xbox consoles. The new platform will support a broader ecosystem by offering an Xbox experience that is not locked to a single store or limited to one device.
- In June 2025, Microsoft and ASUS announced the launch of the ROG Xbox Ally and ROG Xbox Ally X, two new handheld gaming console developed in collaboration to bring the power of Xbox to portable devices. Designed to support Xbox Play Anywhere, Game Pass, Xbox Cloud Gaming (Beta), and Remote Play, these handhelds allows gamers to enjoy high-performance console experiences on the go.
- In June 2025, Nintendo launched the Nintendo Switch 2. The new console features enhanced hardware performance and a broader content library. The launch of Nintendo rolled out a firmware update, introducing system stability improvements and expanding the Nintendo Classics catalog with legacy GameCube titles.
- In May 2024, Gcore declared its strategic association with Xsolla, through which Gcore provides global solutions for edge AI cloud networking security to Xsolla as a video game commerce company.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand through stronger adoption of subscription-based gaming services.
- Cloud gaming will gain wider traction and extend console lifecycles.
- Hybrid and handheld consoles will record higher demand in emerging economies.
- Cross-platform compatibility will remain central to player engagement strategies.
- VR and AR integration will shape the next phase of immersive gaming.
- Esports and streaming platforms will drive visibility and hardware adoption.
- AI-driven personalization will improve gaming experiences and retention.
- Emerging regions will provide new growth opportunities with rising internet access.
- Digital distribution will reduce reliance on physical game sales.
- Sustainability and energy-efficient designs will influence console development.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Immersive Gaming Hardware
The push for high-resolution graphics, faster frame rates, and real-time rendering is driving demand for advanced consoles with powerful GPUs and CPUs, encouraging consumers to upgrade and attracting new users seeking premium gaming experiences.
Expansion of Online Gaming Ecosystems
The integration of multiplayer services, digital downloads, and subscription-based access to games is creating recurring revenue streams and increasing user engagement, making consoles more attractive as entertainment hubs.
Rising Popularity of Esports and Competitive Gaming
Esports growth is fueling demand for consoles with advanced hardware and low latency, while high-profile tournaments and partnerships with esports organizations are increasing brand visibility and adoption among younger audiences.
Growth of Cloud Gaming and Digital Distribution
The shift toward cloud gaming and digital-first strategies is reducing reliance on physical media, enabling access to large game libraries through subscriptions, and extending console lifecycles, especially in regions with strong broadband infrastructure.
Integration of VR, AR, and AI Technologies
The addition of virtual reality, augmented reality, and AI-driven personalization is enhancing gameplay experiences, differentiating consoles from alternative platforms, and appealing to tech-savvy consumers seeking next-generation entertainment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Game Consoles Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Game Consoles Market projected to grow between 2025 and 2032?
Which Game Consoles Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Game Consoles Market?
Who are the leading companies in the Game Consoles Market?
Which region commanded the largest share of the Game Consoles Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Home console
- 1.2.2 Handheld console
- 1.2.3 Hybrid console
- 1.3 By End-User
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.4 By Application
- 1.4.1 Online gaming
- 1.4.2 Offline gaming
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 41.99 billion → 2032: USD 57.16 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Game Consoles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Game Consoles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Game Consoles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Game Consoles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Game Consoles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Game Consoles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Game Consoles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Game Consoles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 41.99 billion → 2032: USD 57.16 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Game Consoles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Home console
- 12.3.7.2 Handheld console
- 12.3.7.3 Hybrid console
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Online gaming
- 12.5.7.2 Offline gaming
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Game Consoles End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Game Consoles Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Game Consoles Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Game Consoles Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sony
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft
- 18.4 Nintendo
- 18.5 Sega
- 18.6 Valve Corporation
- 18.7 ASUS
- 18.8 Razer
- 18.9 Logitech
- 18.10 Ayaneo
- 18.11 SNK Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

