
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| GCC Countries Medical Tourism Market Size 2024 | USD 367.41 Million |
| GCC Countries Medical Tourism Market, CAGR | 10.26% |
| GCC Countries Medical Tourism Market Size 2032 | USD 889.97 Million |
Market Overview:
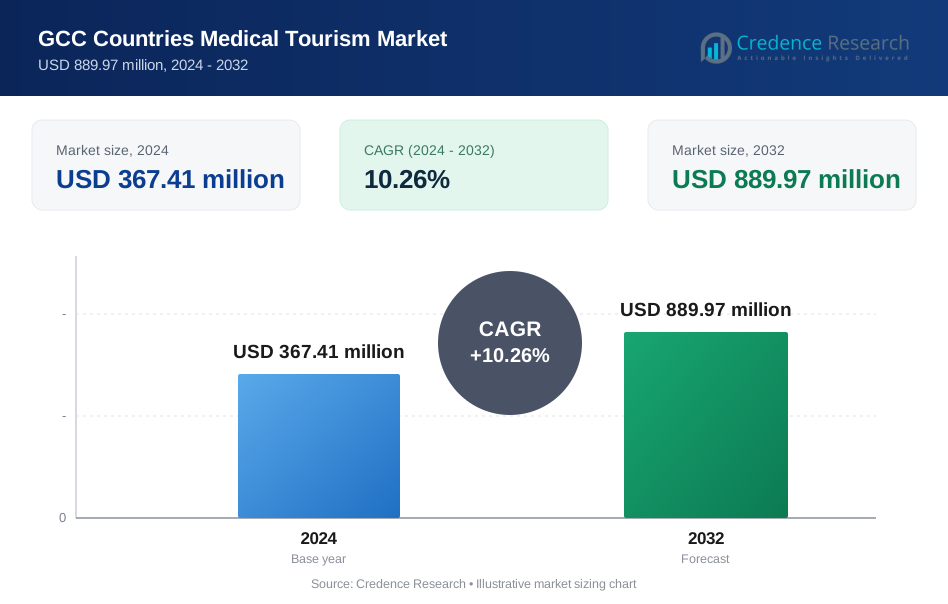
The GCC Countries Medical Tourism Market is projected to grow from USD 367.41 million in 2024 to an estimated USD 889.97 million by 2032, with a compound annual growth rate (CAGR) of 10.26% from 2024 to 2032.
The market growth is primarily fueled by state-of-the-art healthcare facilities, strategic government initiatives, and cost-effective treatments compared to Western countries. The region's world-class hospitals, accreditation by global medical bodies, and skilled healthcare professionals have positioned GCC countries as competitive players in medical tourism. Additionally, the expansion of wellness tourism, cosmetic surgery, and specialized treatments for chronic diseases contributes to the sector’s upward trajectory. Furthermore, favorable visa policies, medical tourism packages, and collaborations between healthcare providers and travel agencies enhance accessibility for international patients. The rise of AI-driven diagnostics, robotic surgeries, and telemedicine solutions further strengthens the GCC’s appeal as a medical tourism hub. Moreover, the growing preference for integrative and holistic treatments, including wellness retreats and alternative medicine, is broadening the scope of medical tourism services in the region.
The United Arab Emirates (UAE) and Saudi Arabia lead the market, with Dubai and Abu Dhabi emerging as key medical tourism hubs due to their internationally accredited hospitals and advanced healthcare infrastructure. Saudi Arabia, driven by Vision 2030, is investing heavily in medical cities and expanding healthcare facilities to attract international patients. Qatar, with its premium medical centers and government-backed health programs, is also gaining traction. Kuwait, Bahrain, and Oman are strengthening their healthcare sectors, primarily catering to regional patients seeking specialized treatments. Each country’s focus on medical tourism aligns with broader economic diversification strategies, positioning the GCC as a growing hub for high-quality, affordable healthcare services. Increasing participation in global medical tourism exhibitions and partnerships with international healthcare providers is further boosting the region’s visibility. Additionally, government-led marketing initiatives and the promotion of wellness-focused tourism infrastructure, such as luxury recovery resorts, are enhancing the GCC’s competitiveness in the global medical tourism industry.
Market Insights:
- The GCC medical tourism market is projected to grow from USD 367.41 million in 2024 to USD 889.97 million by 2032, with a CAGR of 10.26%.
- Investments in world-class hospitals, AI-driven diagnostics, and robotic surgeries enhance treatment quality and patient experience.
- Government initiatives such as Saudi Arabia’s Vision 2030 and UAE’s medical tourism portals streamline patient inflows and boost sector growth.
- High demand for cosmetic procedures, fertility treatments, cardiovascular care, and bariatric surgeries is driving market expansion.
- Competitive pricing compared to Western nations attracts patients from Europe, Asia, and Africa, supported by globally accredited hospitals.
- Inconsistent insurance policies, high treatment costs, and reliance on expatriate healthcare professionals present market constraints.
- Dubai, Abu Dhabi, Riyadh, and Jeddah serve as key hubs, with Qatar, Bahrain, Kuwait, and Oman strengthening their healthcare offerings.
Market Drivers:
Advanced Healthcare Infrastructure and Technological Innovations
The GCC countries have made significant investments in healthcare infrastructure, positioning themselves as leading destinations for medical tourism. World-class hospitals equipped with cutting-edge medical technology, robotic-assisted surgeries, and AI-driven diagnostics are enhancing the quality and efficiency of healthcare services. For instance, at American Hospital Dubai, robotic-assisted surgeries now account for up to 20% of all procedures, with over 2,000 robot-assisted surgeries conducted since 2020. The region’s adoption of telemedicine and digital health solutions further supports medical tourism by offering remote consultations and pre- and post-treatment care. These advancements ensure that patients receive specialized medical treatments comparable to those in Western countries at competitive costs.
Government Initiatives and Strategic Policies
Government-driven policies and initiatives play a crucial role in accelerating the growth of the medical tourism sector across the GCC. Countries such as the UAE and Saudi Arabia have introduced national strategies that focus on enhancing healthcare services and attracting international patients. Saudi Arabia’s Vision 2030 emphasizes medical city developments and specialized healthcare centers, while the UAE has launched dedicated medical tourism portals to streamline patient experiences. For instance, In June 2024, the Dubai Health Authority introduced 'Dubai in One Day', a novel medical tourism package enabling international visitors to schedule medical procedures swiftly while accessing comprehensive tourism amenities. Favorable visa regulations, including medical tourism visas and extended stays for post-surgical recovery, further facilitate patient inflow from international markets. These strategic efforts reinforce the region’s position as a premier medical tourism hub.
Cost-Effective and High-Quality Medical Services
Compared to Western countries, the GCC offers cost-effective yet high-quality healthcare services, making it an attractive option for medical tourists. Patients from Europe, Asia, and Africa seek medical treatments in the region due to competitive pricing without compromising on quality. Many hospitals in the GCC hold international accreditations, ensuring adherence to global medical standards. Additionally, the availability of highly skilled medical professionals, including internationally trained doctors and specialists, enhances the region’s credibility in offering advanced medical procedures such as organ transplants, oncology treatments, and cosmetic surgeries. For instance, Saudi Arabia has emerged as a leading center for organ transplants, performing a significant number of procedures annually. In 2023, the country successfully conducted 2,091 organ transplants, utilizing both living and deceased donors.
Rising Demand for Wellness and Specialized Treatments
The growing preference for wellness-focused medical tourism, including alternative medicine, rehabilitation, and holistic treatments, is driving market expansion. GCC countries are developing integrated wellness resorts that offer a combination of medical treatments and luxury recovery experiences. For instance, in December 2024, the UAE welcomed Tulåh, the world's first Integrated Clinical Wellness Resort, representing a $100 million investment in holistic health management. This innovative venture, spearheaded by KEF Holdings, blends modern medicine with traditional Indian healthcare and luxury hospitality to provide a comprehensive approach to well-being. Cosmetic and aesthetic procedures, fertility treatments, and bariatric surgeries are among the most sought-after medical services. Furthermore, partnerships between healthcare providers and luxury hospitality sectors are creating seamless healthcare tourism experiences, enhancing patient satisfaction and encouraging repeat visits. As the demand for personalized healthcare solutions rises, the GCC continues to diversify its medical tourism offerings to attract a wider patient base.
Market Trends:
Expansion of Specialized Medical Services
The GCC medical tourism market is witnessing a significant shift toward specialized medical services, catering to the increasing demand for complex treatments. Advanced procedures such as oncology treatments, orthopedic surgeries, and cardiovascular interventions are gaining prominence as healthcare providers invest in cutting-edge medical technologies. For instance, King Faisal Specialist Hospital & Research Centre (KFSHRC) exemplifies the GCC's shift towards specialized medical services. Their Oncology Centre offers advanced treatments like CAR T-cell therapy and cutting-edge radiation techniques to international patients. The growing focus on fertility treatments, in vitro fertilization (IVF), and genetic therapies is also attracting patients from Europe, Asia, and Africa. As a result, several hospitals across the UAE, Saudi Arabia, and Qatar are expanding their specialized departments to accommodate the rising influx of international patients seeking high-end medical care.
Integration of Artificial Intelligence and Robotics in Healthcare
The integration of artificial intelligence (AI) and robotic-assisted procedures is transforming the medical tourism landscape in the GCC. AI-driven diagnostics, predictive analytics, and personalized treatment plans are improving patient outcomes and enhancing efficiency. Robotic surgeries, particularly in fields such as urology, neurosurgery, and minimally invasive procedures, are increasingly being adopted by leading hospitals in Dubai, Riyadh, and Doha. For instance, KFSHRC Achieves Remarkable 98% Survival Rate in 400 Robotic Cardiac Surgeries. The automation of administrative processes, including AI-powered patient management systems, is also streamlining medical tourism by reducing wait times and improving coordination between international patients and healthcare providers.
Growth in Preventive and Wellness Tourism
A rising emphasis on preventive healthcare and wellness tourism is reshaping the GCC medical tourism sector. Luxury wellness resorts, integrative medicine centers, and holistic healing retreats are becoming key attractions for medical tourists seeking a combination of medical treatments and post-procedure rehabilitation. For instance, Rayya Wellness, established in 2020, has expanded to 15 locations across Dubai, focusing on integrated wellness retreats and personalized experiences. The demand for alternative medicine, including Ayurveda, traditional Chinese medicine, and regenerative therapies, is also growing among international patients. Wellness-focused infrastructure, such as specialized recovery centers and wellness resorts, is being developed in destinations like Dubai, Abu Dhabi, and Muscat, allowing patients to recover in a relaxing, high-end environment.
Strengthening of International Partnerships and Accreditations
GCC countries are actively pursuing international collaborations and hospital accreditations to enhance credibility and attract a larger patient base. Partnerships with globally recognized healthcare institutions are helping local providers adopt international best practices and offer advanced treatment options. For instance, KFSHRC has partnered with global institutions to ensure its healthcare professionals remain at the forefront of oncology research and treatment. Several leading hospitals in the UAE, Saudi Arabia, and Qatar have obtained Joint Commission International (JCI) accreditation, reinforcing their reputation as high-quality medical tourism destinations. Additionally, participation in global medical tourism exhibitions and strategic agreements with international insurance providers is expanding market reach, enabling more foreign patients to access healthcare services in the GCC.
Market Challenges Analysis:
Regulatory and Insurance Barriers
Despite significant advancements, regulatory challenges and inconsistent insurance policies pose obstacles to the growth of medical tourism in the GCC. Variations in healthcare regulations, licensing procedures, and medical malpractice laws across different countries create complexities for international patients seeking treatment. Additionally, many global insurance providers do not fully cover medical procedures performed in GCC nations, discouraging potential patients from choosing the region for healthcare services. Addressing these issues through harmonized regulations and international insurance collaborations is essential for sustained market growth.
High Treatment Costs Compared to Regional Competitors
Although GCC countries offer world-class medical facilities, the cost of certain treatments remains relatively high compared to emerging medical tourism destinations such as India, Thailand, and Turkey. While the GCC provides premium healthcare services, cost-sensitive medical tourists often opt for more affordable alternatives elsewhere. The absence of competitive pricing strategies, bundled medical tourism packages, and subsidized treatment options limits the market’s ability to attract a broader patient base, particularly from price-sensitive regions.
Workforce Shortages and Dependency on Expatriate Specialists
The shortage of highly specialized local healthcare professionals and the reliance on expatriate medical staff present challenges for long-term sustainability. Many GCC countries depend on internationally trained specialists, leading to concerns regarding workforce stability and retention. Additionally, fluctuations in expatriate labor policies and visa restrictions impact the availability of skilled medical professionals. Investing in local medical education, training programs, and retention strategies will be crucial for ensuring a stable and highly skilled healthcare workforce.
Perceived Quality and Brand Recognition Limitations
While the GCC has made progress in medical tourism, brand recognition and international patient trust remain areas for improvement. The region competes with well-established medical tourism hubs that have decades of experience in attracting foreign patients. Some potential medical tourists remain unfamiliar with GCC healthcare capabilities, creating the need for stronger global marketing efforts, patient testimonials, and international endorsements to enhance trust and credibility.
Market Opportunities:
The GCC medical tourism market presents significant opportunities driven by growing investments in specialized healthcare services, digital health innovations, and strategic government initiatives. The increasing demand for advanced treatments such as oncology, cardiology, and organ transplants positions the region as a competitive medical tourism destination. Additionally, the expansion of wellness tourism, cosmetic procedures, and fertility treatments offers a lucrative opportunity to attract high-net-worth individuals seeking premium healthcare services. The integration of telemedicine and AI-driven diagnostics further enhances patient convenience by enabling pre-treatment consultations and post-procedure follow-ups, making the medical tourism experience more seamless.
Furthermore, strong government support, strategic public-private partnerships, and international collaborations are expected to drive market expansion. The growing recognition of Dubai, Abu Dhabi, and Riyadh as leading medical tourism hubs enhances the region’s global competitiveness. Additionally, initiatives to streamline visa processes, improve patient facilitation services, and expand internationally accredited hospitals will attract a broader patient base. The development of luxury recovery centers, integrated wellness resorts, and specialized rehabilitation facilities presents a significant opportunity to position the GCC as a premium medical tourism destination. With continued investment in branding, global marketing strategies, and insurance collaborations, the GCC is well-positioned to capture a larger share of the global medical tourism market.
Market Segmentation Analysis:
The GCC medical tourism market is segmented based on treatment type, services, tour types, consumer orientation, and age group, each playing a critical role in shaping market dynamics.
By Treatment Type
The market is driven by a diverse range of treatments, with cosmetic and dental procedures leading due to high demand from international patients seeking aesthetic enhancements and restorative care. Cardiovascular and orthopedic treatments are gaining traction as the region advances in specialized surgeries and rehabilitation programs. The “others” category, which includes fertility treatments, oncology, and neurology, is witnessing strong growth as medical advancements improve treatment success rates.
By Services
The sector is divided into wellness and therapeutic services. Wellness services, including spa treatments, holistic therapies, and alternative medicine, are expanding as luxury wellness tourism grows. Therapeutic services, encompassing specialized medical treatments and post-operative care, remain the core driver of patient inflows.
By Tour Types
Medical tourists in the GCC opt for either independent traveler tours or group package tours. Independent travelers, often seeking personalized treatments, contribute to a significant portion of the market, while group package travelers prefer structured medical tourism packages offered by hospitals and tour operators.
By Consumer Orientation
Women represent a substantial share of the market, particularly in cosmetic and wellness treatments, while men primarily seek cardiovascular, orthopedic, and dental procedures. Children’s treatments, including pediatric surgeries and dental care, are also an important segment.
By Age Group
The 26-35 and 36-45 age groups dominate the market, particularly in cosmetic, dental, and wellness tourism. Patients aged 46-55 years often seek cardiovascular and orthopedic treatments, while younger individuals aged 15-25 years contribute to demand for aesthetic procedures and wellness services.
Segmentation:
By Treatment Type
- Dental Treatment
- Cosmetic Treatment
- Cardiovascular Treatment
- Orthopedic Treatment:
- Others
By Services
- Wellness Services
- Therapeutic Services
By Tour Types
- Independent Traveler Tour
- Group Package Traveler
By Consumer Orientation
- Men
- Women
- Children
By Age Group
- 15-25 Years
- 26-35 years
- 36-45 Years
- 46-55 Years
Regional Analysis:
United Arab Emirates (UAE)
The United Arab Emirates (UAE) leads the GCC medical tourism market, commanding approximately 40% of the total market share. This dominance is primarily attributed to the emirates of Dubai and Abu Dhabi, which have heavily invested in state-of-the-art healthcare infrastructure and attracted world-renowned medical professionals. In 2022, Dubai alone welcomed 674,000 medical tourists, with 39% originating from Asian countries, 22% from Europe, and 21% from Arab and GCC nations.
The UAE's healthcare system offers a diverse range of medical specialties, including cardiology, orthopedics, fertility treatments, and cosmetic surgery, making it a preferred destination for international patients seeking high-quality medical care.
Saudi Arabia
Saudi Arabia holds a significant portion of the GCC medical tourism market, with a market share of approximately 30%. The nation's ambitious Vision 2030 initiative emphasizes the expansion of healthcare services and the promotion of medical tourism as a key economic driver. Major cities like Riyadh and Jeddah are emerging as prominent medical hubs, offering specialized treatments in oncology, cardiology, and organ transplants. The government's substantial investments in medical cities, advanced healthcare technologies, and strategic partnerships with international medical institutions have bolstered Saudi Arabia's position as a competitive destination for medical tourists.
Qatar
Qatar accounts for approximately 15% of the GCC medical tourism market share. The country's capital, Doha, is at the forefront of this sector, boasting world-class healthcare facilities and a strong emphasis on medical research and advanced diagnostics. Qatar's healthcare system is renowned for its excellence in sports medicine, orthopedics, and cardiovascular care, attracting patients from across the globe. The nation's commitment to integrating AI-driven healthcare solutions and maintaining high standards of patient care continues to enhance its appeal to international medical tourists.
Kuwait, Bahrain, and Oman
Collectively, Kuwait, Bahrain, and Oman contribute the remaining 15% to the GCC medical tourism market. These countries are actively working to enhance their healthcare offerings to attract more regional and international patients. Kuwait is focusing on expanding services in advanced surgical procedures and fertility treatments, primarily drawing patients from neighboring countries. Bahrain is developing its medical wellness tourism by emphasizing integrative treatments, rehabilitation, and cosmetic procedures. Meanwhile, Oman leverages its natural landscapes to promote alternative medicine and holistic wellness retreats, appealing to patients seeking a combination of medical treatment and relaxation. Ongoing investments in healthcare infrastructure and international collaborations are expected to further elevate the medical tourism profiles of these nations within the GCC region.
Key Player Analysis:
- Fortis Healthcare
- Health capital (Wellness Zone WLL)
- Thumbay Medical Tourism
- Fakhri Travel & Tourism Centre
- American Hospital Dubai
- VAID Health Care Services (VHS)
- On-time Healthcare
- Shifa International Hospitals
- Zulekha Healthcare
- Exeter Bone & Joint
- Lyfboat Technologies Pvt. Ltd
- Medsurge India
- Al AfiyaMedi Tour
- Farhan Travel & Tourism
- AL Hakkim Medical Services
- Arabian Gulf Medical Tourism Agency
Competitive Analysis:
The GCC medical tourism market is highly competitive, with UAE and Saudi Arabia leading the sector due to their advanced healthcare infrastructure and internationally accredited hospitals. The UAE dominates the market with Dubai and Abu Dhabi emerging as global medical tourism hubs, offering specialized treatments in cosmetic surgery, orthopedics, and fertility services. Saudi Arabia, leveraging its Vision 2030 initiatives, is rapidly expanding its healthcare sector with world-class medical cities and specialized treatment centers. Qatar, holding a growing market share, is gaining recognition for its high-end healthcare services, sports medicine expertise, and AI-integrated medical solutions. For instance, under its Health Vision 2050 strategy, Oman is developing mega projects like the Sultan Qaboos Medical City to provide state-of-the-art facilities for complex treatments. Meanwhile, Kuwait, Bahrain, and Oman are strengthening their presence by focusing on regional patient inflows, wellness tourism, and specialized treatments. Competition within the GCC is intensifying as governments invest in medical tourism promotion, strategic partnerships, and technological advancements to enhance patient experience and attract a broader international clientele.
Recent Developments:
- In February 2025, the Medical Tourism Association (MTA) announced the launch of 'Better by MTA,' a transformative platform developed in partnership with Mastercard. This innovative solution aims to modernize the global healthcare experience by connecting medical travelers, insurers, qualified facilitators, and accredited healthcare providers. The platform will provide access to trusted providers, comprehensive education, financing options, and top-tier quality care, revolutionizing medical travel.
- In February 2025, Thumbay Healthcare hosted the 5th Annual Medical Tourism Conclave 2025 at Thumbay Medicity in Ajman, UAE. The event brought together global healthcare leaders to discuss advancements in medical tourism. As part of the conclave, Thumbay Healthcare announced the launch of new medical tourism courses in partnership with Gulf Medical University. They also signed a landmark agreement with Empire Aviation Group to enhance medical tourism services.
Market Concentration & Characteristics:
The GCC medical tourism market is moderately concentrated, with the UAE and Saudi Arabia collectively holding over 70% of the total market share. These countries dominate due to advanced healthcare infrastructure, internationally accredited hospitals, and strong government initiatives promoting medical tourism. Qatar, Kuwait, Bahrain, and Oman contribute to the remaining market share, focusing on niche healthcare services, wellness tourism, and regional patient inflows. The market is characterized by high-quality medical services, strategic government investments, and increasing adoption of advanced medical technologies such as AI-driven diagnostics and robotic-assisted surgeries. Luxury healthcare experiences, integration of telemedicine, and personalized treatment plans further differentiate the GCC as a premium medical tourism destination. Additionally, favorable visa policies, competitive pricing compared to Western markets, and strong public-private partnerships continue to attract international patients. As demand rises, the market is expected to see further expansion in specialized treatments and cross-border healthcare collaborations.
Report Coverage:
The research report offers an in-depth analysis based on By Treatment Type, By Services, By Tour Types, By Consumer Orientation and By Age Group. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued investments in healthcare infrastructure will enhance the region’s global competitiveness in medical tourism.
- Expansion of specialized treatments such as oncology, cardiology, and organ transplants will attract high-value medical tourists.
- Integration of AI, robotics, and telemedicine will improve diagnostic accuracy and streamline patient management.
- Government initiatives and policy reforms will simplify medical visa processes and enhance patient accessibility.
- Growth of wellness and preventive healthcare tourism will drive demand for luxury recovery centers and holistic treatment facilities.
- Increased international collaborations with top-tier medical institutions will strengthen the region’s reputation for high-quality healthcare.
- Competitive pricing strategies and bundled medical packages will attract cost-conscious patients from Europe, Africa, and Asia.
- Expansion of insurance partnerships will improve global patient coverage and financial accessibility for medical tourists.
- Strategic marketing and branding efforts will boost the GCC’s visibility in the global medical tourism industry.
- Sustained economic diversification efforts will position the GCC as a long-term leader in premium medical and wellness tourism.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advanced Healthcare Infrastructure and Technology
GCC countries have invested heavily in world-class hospitals, AI-driven diagnostics, and robotic-assisted surgeries, offering high-quality and efficient medical care that attracts international patients seeking advanced treatments.
Government Initiatives and Strategic Policies
National strategies such as Saudi Arabia’s Vision 2030 and the UAE’s dedicated medical tourism portals streamline patient inflows, simplify visa processes, and promote the region as a premier medical tourism hub.
Cost-Effective, High-Quality Medical Services
Compared to Western countries, the GCC offers competitively priced medical procedures without compromising on quality, supported by internationally accredited hospitals and highly skilled healthcare professionals.
Expansion of Wellness and Specialized Treatments
The growing demand for wellness tourism, cosmetic procedures, fertility treatments, and holistic health services is driving market growth, with the development of integrated wellness resorts and luxury recovery centers enhancing the region’s appeal.
International Partnerships and Accreditations
Collaborations with globally recognized healthcare institutions and the pursuit of international accreditations such as JCI increase the credibility of GCC providers, attracting a broader base of international medical tourists.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the GCC Countries Medical Tourism Market?
What factors are driving the growth of the GCC Countries Medical Tourism Market?
What are the key segments within the GCC Countries Medical Tourism Market?
What are some challenges faced by the GCC Countries Medical Tourism Market?
Who are the major players in the GCC Countries Medical Tourism Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Services
- 1.2.1 Wellness Services
- 1.2.2 Therapeutic Services
- 1.3 By Tour Types
- 1.3.1 Independent Traveler Tour
- 1.3.2 Group Package Traveler
- 1.4 By Treatment Type
- 1.4.1 Dental Treatment
- 1.4.2 Cosmetic Treatment
- 1.4.3 Cardiovascular Treatment
- 1.4.4 Orthopedic Treatment
- 1.4.5 Others
- 1.5 By Consumer Orientation
- 1.5.1 Men
- 1.5.2 Women
- 1.5.3 Children
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 367.41 million → 2032: USD 889.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 GCC Countries Medical Tourism Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 GCC Countries Medical Tourism Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 GCC Countries Medical Tourism Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 GCC Countries Medical Tourism Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 GCC Countries Medical Tourism Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 GCC Countries Medical Tourism Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 GCC Countries Medical Tourism Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 GCC Countries Medical Tourism Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 367.41 million → 2032: USD 889.97 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 GCC Countries Medical Tourism Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Services - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Wellness Services
- 12.3.6.2 Therapeutic Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Tour Types - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Independent Traveler Tour
- 12.4.6.2 Group Package Traveler
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Dental Treatment
- 12.5.6.2 Cosmetic Treatment
- 12.5.6.3 Cardiovascular Treatment
- 12.5.6.4 Orthopedic Treatment
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Consumer Orientation - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Men
- 12.6.6.2 Women
- 12.6.6.3 Children
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 GCC Countries Medical Tourism Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 GCC Countries Medical Tourism Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 GCC Countries Medical Tourism Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 American Hospital Dubai
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Thumbay Medical Tourism
- 17.4 Fortis Healthcare
- 17.5 Zulekha Healthcare
- 17.6 Shifa International Hospitals
- 17.7 Lyfboat Technologies Pvt. Ltd
- 17.8 Fakhri Travel & Tourism Centre
- 17.9 Health capital (Wellness Zone WLL)
- 17.10 VAID Health Care Services (VHS)
- 17.11 Exeter Bone & Joint
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

