
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Generalized Anxiety Disorder Treatment Market Size 2024 | USD 1825 million |
| Generalized Anxiety Disorder Treatment Market, CAGR | 9% |
| Generalized Anxiety Disorder Treatment Market Size 2032 | USD 3636.42 million |
Market Overview:
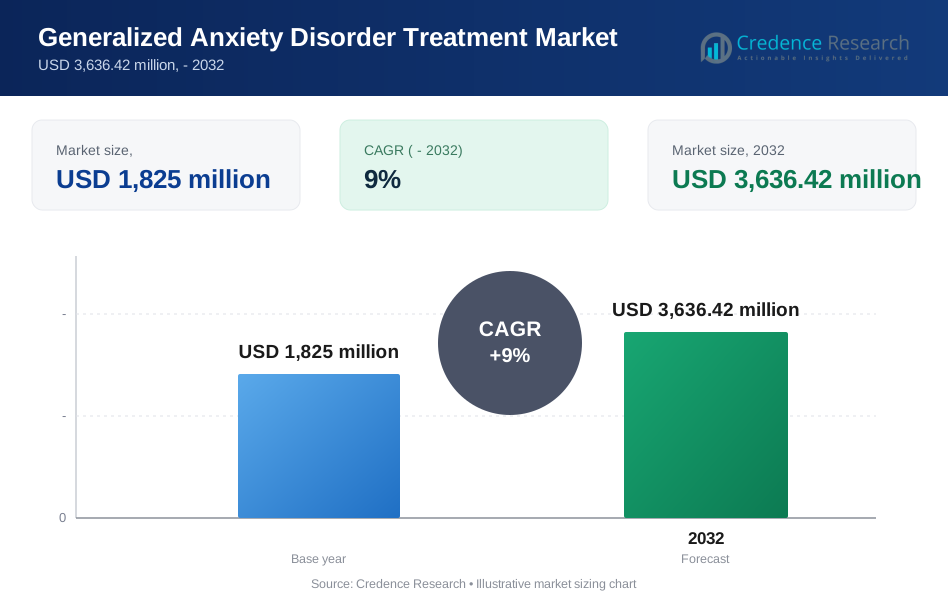
The Generalized Anxiety Disorder Treatment Market is projected to grow from USD 1825 million in 2024 to an estimated USD 3636.42 million by 2032, with a compound annual growth rate (CAGR) of 9% from 2024 to 2032.
The increasing prevalence of anxiety disorders, particularly GAD, is a primary driver of market growth. Factors such as rising stress levels, urbanization, and socioeconomic pressures contribute to the growing number of diagnosed cases. Additionally, the stigma surrounding mental health is gradually decreasing, encouraging more individuals to seek treatment. The market is also benefiting from advancements in pharmacological and non-pharmacological therapies. Medications such as selective serotonin reuptake inhibitors (SSRIs) and serotonin-norepinephrine reuptake inhibitors (SNRIs) remain first-line treatments, while newer therapies, including atypical antipsychotics and novel anxiolytics, are expanding the therapeutic landscape. Moreover, the integration of digital tools, such as telemedicine and mobile mental health apps, is improving access to care, particularly in underserved regions. Continued investment in research and development is further expected to drive innovation, with pharmaceutical companies focusing on improving the safety and efficacy profiles of existing treatments.
North America dominates the GAD treatment market, accounting for the largest share due to high mental health awareness, advanced healthcare infrastructure, and strong investment in therapeutic development. The United States leads the region, driven by an increasing number of GAD diagnoses and rising demand for effective treatment options. Europe follows closely, with significant contributions from countries like Germany, France, and the UK, where robust healthcare systems and growing mental health initiatives are supporting market growth. The Asia-Pacific region is witnessing rapid expansion, fueled by increasing awareness of mental health issues, rising disposable incomes, and improving healthcare access in countries such as China, India, and Japan. Meanwhile, Latin America and the Middle East & Africa are experiencing moderate growth as mental health awareness rises and governments work to improve healthcare infrastructure. These regional trends underscore the global demand for effective GAD treatments.
Market Insights:
- The GAD treatment market is projected to grow from USD 1,825 million in 2024 to USD 3,636.42 million by 2032, at a CAGR of 9%, driven by rising anxiety prevalence globally.
- Advancements in pharmacological therapies, including newer SSRIs, SNRIs, and atypical antipsychotics, are enhancing treatment outcomes and patient satisfaction.
- The adoption of digital tools like telemedicine and mental health apps is improving access to care, particularly in underserved areas.
- North America leads the market with 40% share, fueled by advanced healthcare infrastructure, mental health awareness, and robust pharmaceutical R&D.
- The Asia-Pacific region is the fastest-growing market due to increasing awareness, rising healthcare investments, and digital health adoption in countries like China and India.
- Investment in novel therapies, including psychedelics and personalized medicine, is opening new treatment pathways for resistant GAD cases.
- Public health initiatives and reduced stigma around mental health are encouraging more individuals to seek professional treatment, expanding the patient pool.
Market Drivers:
Increasing Prevalence of Generalized Anxiety Disorder and Mental Health Awareness
The rising prevalence of Generalized Anxiety Disorder (GAD) and a growing focus on mental health are driving the demand for effective treatments. Factors such as urbanization, socioeconomic stress, and the lingering effects of global crises have significantly increased anxiety levels across populations. For instance, according to recent studies, GAD affects approximately 4.05% of the global population, translating to around 301 million people. Public health campaigns and educational initiatives have been instrumental in reducing the stigma around mental health, encouraging patients to pursue treatment options. As more individuals recognize the importance of mental well-being, the demand for accessible and reliable GAD treatments continues to grow.
Advancements in Pharmacological Treatments
Pharmacological innovations play a critical role in the growth of the GAD treatment market. Selective serotonin reuptake inhibitors (SSRIs) and serotonin-norepinephrine reuptake inhibitors (SNRIs) remain the cornerstone of first-line therapies. However, advancements in atypical antipsychotics, benzodiazepines, and novel anxiolytics are enhancing therapeutic outcomes. Pharmaceutical companies are investing heavily in research to develop medications with improved efficacy and fewer side effects. Additionally, the emergence of personalized medicine is enabling tailored treatment approaches based on patient-specific factors such as genetics, improving treatment adherence and outcomes. This focus on innovation ensures the sustained growth of pharmacological options for GAD.
Integration of Digital Health Solutions
The integration of digital health technologies, including telemedicine and mobile mental health apps, has revolutionized GAD treatment. Telemedicine has expanded access to mental health professionals, allowing patients in underserved or remote areas to receive timely consultations and prescriptions. Mental health apps equipped with cognitive behavioral therapy (CBT) modules, mindfulness exercises, and real-time mood tracking are empowering individuals to manage their anxiety independently. These digital tools are not only supplementing traditional treatment approaches but also driving awareness and early intervention. As technology adoption increases, digital solutions are expected to play an increasingly central role in the GAD treatment ecosystem.
Rising Investment in Research and Development
Investment in research and development continues to drive innovation in GAD treatment. Pharmaceutical companies and academic institutions are focusing on identifying novel therapeutic targets and improving existing drug formulations. Clinical trials exploring the use of psychedelic compounds, such as psilocybin, for treatment-resistant anxiety disorders are gaining traction, highlighting the potential for groundbreaking advancements in the field. For instance, COMPASS Pathways is conducting phase IIb trials of psilocybin therapy for treatment-resistant depression and anxiety, showing promising preliminary results with a 25mg dose demonstrating a significant reduction in depressive symptoms after three weeks. Governments and private organizations are also funding mental health research to address the growing burden of anxiety disorders. These investments are expected to yield more effective and diverse treatment options, further propelling the GAD treatment market's growth.
Market Trends:
Growing Demand for Non-Pharmacological Therapies
A notable trend in the Generalized Anxiety Disorder (GAD) treatment market is the increasing demand for non-pharmacological therapies, driven by the growing preference for holistic and integrative approaches to mental health care. Cognitive Behavioral Therapy (CBT) remains a gold-standard psychotherapeutic intervention, with a proven track record of effectively managing GAD symptoms. For instance, a meta-analysis published in JAMA Psychiatry found that CBT significantly reduced anxiety symptoms in 60-80% of patients. In addition, mindfulness-based stress reduction (MBSR) and other behavioral therapies are gaining traction as complementary solutions, particularly for patients who experience side effects from medications or prefer drug-free options. The integration of these therapies into digital platforms, such as virtual CBT sessions, is further expanding their accessibility and appeal.
Emergence of Psychedelic-Assisted Treatments
The exploration of psychedelic-assisted treatments is a transformative trend in the GAD treatment landscape. Compounds such as psilocybin and MDMA are undergoing clinical trials for their potential to alleviate anxiety symptoms, particularly in treatment-resistant cases. Early-phase studies indicate that these substances may reset neural pathways, providing long-term relief from anxiety disorders after just a few guided therapy sessions. The ongoing research into psychedelics reflects a broader shift toward novel mechanisms of action and unconventional treatments in psychiatry, offering a glimpse into the future of GAD management.
Rising Role of Artificial Intelligence in Mental Health Care
Artificial intelligence (AI) is playing an increasingly important role in shaping the GAD treatment market. AI-driven tools are being utilized for early diagnosis, patient monitoring, and personalized treatment planning. Advanced algorithms can analyze patterns in patient data, such as responses to questionnaires and behavioral cues, to predict the likelihood of developing GAD and recommend appropriate interventions. For example, the AI platform "Woebot" uses natural language processing to deliver cognitive behavioral therapy techniques and has shown a 22% reduction in anxiety symptoms among users. Virtual mental health assistants powered by AI are also gaining popularity, offering real-time support and coping strategies to individuals. This trend highlights how technological advancements are improving efficiency and accessibility in mental health care.
Increasing Global Focus on Workplace Mental Health
The rising emphasis on workplace mental health is creating a significant opportunity for the GAD treatment market. Employers are increasingly recognizing the impact of anxiety disorders on productivity and are implementing mental health programs to support their workforce. Workplace wellness initiatives often include access to counseling, stress management workshops, and mental health apps, creating a wider pool of individuals seeking treatment for GAD. Governments and organizations are also introducing policies to address mental health in professional settings, further boosting demand for comprehensive anxiety management solutions. This trend underscores the growing societal acknowledgment of mental health as a critical component of overall well-being.
Market Challenges Analysis:
High Cost of Treatment
The high cost associated with Generalized Anxiety Disorder (GAD) treatment presents a significant market restraint. Medications, particularly branded therapies such as selective serotonin reuptake inhibitors (SSRIs) and serotonin-norepinephrine reuptake inhibitors (SNRIs), can be prohibitively expensive for many patients, especially in low- and middle-income regions. Psychotherapeutic interventions like Cognitive Behavioral Therapy (CBT) add to the financial burden, as these services often require multiple sessions and are not always covered comprehensively by insurance. This financial barrier limits access to effective treatment and reduces the overall adoption rate in cost-sensitive markets.
Stigma and Limited Awareness
Despite growing awareness about mental health, stigma remains a challenge, particularly in conservative or underserved regions. Many individuals are hesitant to seek treatment due to cultural taboos and misconceptions about mental illnesses. Additionally, a lack of awareness about the symptoms of GAD and the availability of effective treatments further exacerbates the issue. This delay in seeking professional help often leads to underdiagnosis and undertreatment, contributing to the growing disease burden. Addressing these societal barriers requires concerted efforts from healthcare providers, governments, and advocacy groups.
Side Effects and Treatment Resistance
The side effects associated with pharmacological treatments for GAD, such as weight gain, fatigue, and sexual dysfunction, often deter patients from adhering to prescribed regimens. Furthermore, some patients experience limited or no relief from standard medications, highlighting the challenge of treatment resistance. These issues underscore the need for more effective and tolerable therapies that can address the diverse needs of patients. The lack of universally effective treatments also complicates management strategies, posing a hurdle for healthcare providers.
Regulatory and Approval Challenges
Regulatory and approval hurdles present additional challenges for the GAD treatment market. Developing new medications requires extensive clinical trials and safety assessments, which are time-consuming and costly. Regulatory requirements vary across regions, adding complexity to the global commercialization of novel therapies. For emerging treatments, such as psychedelics and digital therapeutics, the lack of clear regulatory frameworks further delays market entry. Overcoming these barriers requires streamlined processes and collaborative efforts among stakeholders to ensure timely access to innovative treatments.
Market Opportunities:
The Generalized Anxiety Disorder (GAD) treatment market presents significant opportunities driven by the growing global focus on mental health and advancements in therapeutic approaches. The increasing prevalence of GAD, coupled with the gradual reduction in stigma surrounding mental health, is encouraging more individuals to seek treatment, expanding the patient pool. Innovations in pharmacological therapies, including next-generation SSRIs, SNRIs, and atypical anxiolytics, offer pharmaceutical companies the chance to address unmet needs with more effective and tolerable treatment options. Additionally, the rising interest in non-pharmacological interventions, such as mindfulness-based therapies and digital mental health tools, presents an opportunity for market diversification and growth.
Emerging markets, particularly in the Asia-Pacific, Latin America, and Middle East & Africa regions, offer lucrative opportunities due to increasing healthcare expenditure and improving access to mental health services. These regions are witnessing a surge in mental health awareness campaigns, government initiatives, and investments in healthcare infrastructure, paving the way for greater adoption of GAD treatments. The integration of telemedicine and mobile health platforms further enhances accessibility, particularly in underserved areas. Moreover, the development of personalized medicine and companion diagnostics tailored to individual patient needs represents a transformative opportunity to improve therapeutic outcomes and patient satisfaction. Collectively, these factors highlight a dynamic and evolving landscape, ripe for innovation and expansion in the GAD treatment market.
Market Segmentation Analysis:
The Generalized Anxiety Disorder (GAD) treatment market is segmented by drug class, therapies, distribution channel, and region, reflecting a diverse and evolving landscape.
By drug class, antidepressants such as SSRIs and SNRIs dominate the segment due to their efficacy as first-line treatments. Buspirone is gaining traction for its favorable side effect profile, while benzodiazepines remain widely used for short-term symptom relief despite concerns about dependency and withdrawal. These drug classes collectively address varying patient needs, contributing to market growth.
By therapies, Cognitive Behavioral Therapy (CBT) leads the segment as the gold-standard psychotherapeutic approach for managing GAD. Complementary therapies such as Interpersonal Therapy, Behavioral Therapy, and Mindfulness-Based Cognitive Therapy (MBCT) are gaining popularity for their holistic benefits. Increasing integration of these therapies with digital platforms, such as teletherapy and mental health apps, is further driving their adoption.
By distribution channel, hospital pharmacies hold a significant share due to the prevalence of prescribed medications. Retail pharmacies cater to outpatient and follow-up treatments, while online pharmacies are rapidly expanding, driven by convenience and growing telemedicine adoption.
Segmentation:
By Drug Class:
- Antidepressant
- Buspirone
- Benzodiazepines
By Therapies:
- Interpersonal Therapy
- Behavioural Therapy
- Cognitive Behaviour Therapy
- Mindfulness Based Cognitive Therapy
By Distribution Channel:
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Generalized Anxiety Disorder (GAD) treatment market exhibits regional variations in terms of adoption, awareness, and access to therapeutic options. The market is driven by differences in healthcare infrastructure, mental health awareness, and socioeconomic factors, with key regions including North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
North America holds the largest market share, accounting for approximately 40% of the global market in 2024. The region’s dominance is attributed to its advanced healthcare infrastructure, widespread awareness of mental health issues, and strong investment in pharmaceutical research and development. The United States drives this growth, supported by a high prevalence of GAD and a robust pipeline of innovative treatments. Favorable reimbursement policies and the presence of leading pharmaceutical companies further bolster North America’s position as the largest regional market.
Europe represents about 30% of the global market and is the second-largest contributor. Countries such as Germany, the UK, and France lead the region, benefiting from well-established healthcare systems and growing government initiatives to improve mental health services. The European Union’s focus on integrating mental health into public health policies and promoting workplace mental wellness has further driven market growth. Additionally, advancements in pharmacological therapies and access to psychotherapeutic services contribute to Europe’s strong market presence.
The Asia-Pacific region is the fastest-growing, accounting for approximately 20% of the market and projected to witness a compound annual growth rate (CAGR) exceeding 8% from 2024 to 2032. Rapid economic growth, increasing healthcare expenditure, and rising awareness of mental health conditions in countries like China, India, and Japan are fueling the region’s expansion. Improved access to healthcare services, coupled with the adoption of digital mental health platforms, has created significant opportunities for market players in the region.
Latin America holds a smaller market share of about 6%, with growth driven by improving healthcare systems in countries such as Brazil and Mexico. Increasing awareness campaigns and government initiatives aimed at addressing mental health challenges are contributing to steady progress, although barriers like affordability and limited access to specialized care remain challenges.
The Middle East & Africa accounts for approximately 4% of the global market, with gradual growth observed due to rising awareness of mental health issues and investments in healthcare infrastructure. Countries like South Africa and the UAE are at the forefront, with improving access to mental health services and efforts to integrate mental health into primary care.
Key Player Analysis:
- Abbott Laboratories
- Actavis
- Actavis Pharmaceutical Company
- Bionomics
- Bristol-Myers Squibb
- Eli Lilly and Company
- GlaxoSmithKline Pharmaceuticals Limited
- MindMed
- Pfizer, Inc.
- Takeda Pharmaceuticals
- VistaGen Therapeutics
Competitive Analysis:
The Generalized Anxiety Disorder (GAD) treatment market is characterized by intense competition among established pharmaceutical companies and emerging players developing innovative therapies. Leading companies such as Pfizer, Eli Lilly, GlaxoSmithKline, and Johnson & Johnson dominate the market with strong portfolios of first-line treatments like selective serotonin reuptake inhibitors (SSRIs) and serotonin-norepinephrine reuptake inhibitors (SNRIs). These companies leverage extensive research and development capabilities and global distribution networks to maintain their competitive edge. Emerging players are focusing on developing next-generation anxiolytics, atypical antipsychotics, and personalized therapeutic solutions to address unmet needs, such as treatment resistance and drug tolerability. Additionally, the growing integration of digital health solutions, including mobile apps and telemedicine platforms, has introduced new competitors in the mental health space. Strategic collaborations, acquisitions, and the expansion of product pipelines are key strategies shaping the competitive landscape. As demand for innovative and accessible solutions increases, the market continues to evolve with diverse opportunities for both established and new entrants.
Recent Developments:
- On December 5, 2024, the company was honored with the prestigious Innovation Passport designation from the UK's Medicines and Healthcare products Regulatory Agency (MHRA) for its MM120 Orally Disintegrating Tablet. This designation is expected to accelerate the product's path to market.
- In October 2024, AbbVie and Gedeon Richter announced a significant partnership to advance neuropsychiatric treatments. The collaboration includes a $25 million upfront payment to Richter and builds upon their successful efforts with VRAYLAR and ABBV-932 for the treatment of bipolar depression and GAD.
- In July 2024, MindMed secured a new patent for its MM120 Orally Disintegrating Tablet (ODT), extending protection until 2041. This innovative formulation utilizes Catalent's Zydis® ODT technology, which enhances absorption and bioavailability.
- In March 2024, the company reported groundbreaking clinical results, with its MM120 (lysergide d-tartrate) achieving a remarkable 48% remission rate from Generalized Anxiety Disorder (GAD) at 12 weeks after a single dose. These results earned the therapy FDA Breakthrough Therapy designation.
Market Concentration & Characteristics:
The Generalized Anxiety Disorder (GAD) treatment market demonstrates a moderately fragmented structure, with both global pharmaceutical giants and emerging players contributing to its growth. Leading companies, including Pfizer, Eli Lilly, GlaxoSmithKline, and Johnson & Johnson, hold a significant share due to their established product lines, extensive research and development capabilities, and strong global distribution networks. These key players dominate the market with first-line pharmacological therapies, such as SSRIs and SNRIs. Emerging companies are actively innovating in areas like atypical antipsychotics, novel anxiolytics, and digital mental health solutions, reflecting the dynamic and competitive nature of the market. High barriers to entry, such as rigorous regulatory requirements and the lengthy drug approval process, contribute to the concentration of major players. However, the growing demand for personalized therapies and digital solutions is creating opportunities for smaller companies to carve out niches. The market’s evolving landscape emphasizes innovation, accessibility, and patient-centered care.
Report Coverage:
The research report offers an in-depth analysis based on By Drug Class, By Therapies and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing prevalence of anxiety disorders globally will sustain demand for innovative treatment solutions.
- Advances in personalized medicine will drive the development of targeted therapies tailored to individual patient needs.
- Digital mental health tools, including telemedicine and mobile apps, will expand access to care, especially in underserved regions.
- Emergence of psychedelic-assisted therapies will introduce novel mechanisms for managing treatment-resistant GAD.
- Asia-Pacific will witness the fastest growth, supported by rising awareness and improving healthcare infrastructure.
- Enhanced integration of workplace mental health programs will boost the adoption of GAD treatments.
- Continued investment in research will foster the development of next-generation anxiolytics and non-pharmacological interventions.
- Increasing focus on addressing the side effects of current therapies will lead to improved patient adherence.
- Regulatory support for mental health initiatives will expedite the approval and commercialization of innovative treatments.
- Growing collaborations between pharmaceutical companies and digital health providers will shape the future of integrated care.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Generalized Anxiety Disorder and Mental Health Awareness
The global rise in GAD cases, driven by urbanization, socioeconomic stress, and reduced stigma, is expanding the patient pool and fueling demand for effective treatments as more individuals seek professional help.
Advancements in Pharmacological Treatments
Ongoing innovation in drug development, including next-generation SSRIs, SNRIs, and novel anxiolytics, is improving efficacy and tolerability, attracting both patients and providers to newer, more effective therapies.
Integration of Digital Health Solutions
Telemedicine and mental health apps are making GAD treatment more accessible, especially in underserved regions, by enabling remote consultations, digital CBT, and self-management tools, thus broadening market reach.
Rising Investment in Research and Development
Significant investments by pharmaceutical companies and academic institutions are accelerating the discovery of new therapeutic targets, including psychedelic-assisted therapies and personalized medicine, which are expected to address unmet needs and drive market growth.
Growing Demand for Non-Pharmacological Therapies
Increasing patient preference for holistic and integrative approaches, such as CBT and mindfulness-based therapies, is expanding the market beyond traditional medications and encouraging the adoption of digital and in-person psychotherapeutic interventions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected size of the GAD treatment market by 2032?
What is the estimated CAGR for the market from 2024 to 2032?
What are the primary drivers of market growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Therapies
- 1.2.1 Interpersonal Therapy
- 1.2.2 Behavioural Therapy
- 1.2.3 Cognitive Behaviour Therapy
- 1.2.4 Mindfulness Based Cognitive Therapy
- 1.3 By Drug Class
- 1.3.1 Antidepressant
- 1.3.2 Buspirone
- 1.3.3 Benzodiazepines
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,825 million → 2032: USD 3,636.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Generalized Anxiety Disorder Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Generalized Anxiety Disorder Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Generalized Anxiety Disorder Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Generalized Anxiety Disorder Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Generalized Anxiety Disorder Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Generalized Anxiety Disorder Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Generalized Anxiety Disorder Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Generalized Anxiety Disorder Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,825 million → 2032: USD 3,636.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Generalized Anxiety Disorder Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Therapies - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Interpersonal Therapy
- 12.3.7.2 Behavioural Therapy
- 12.3.7.3 Cognitive Behaviour Therapy
- 12.3.7.4 Mindfulness Based Cognitive Therapy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Antidepressant
- 12.4.7.2 Buspirone
- 12.4.7.3 Benzodiazepines
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Generalized Anxiety Disorder Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Generalized Anxiety Disorder Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Generalized Anxiety Disorder Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Eli Lilly and Company
- 17.4 GlaxoSmithKline Pharmaceuticals Limited
- 17.5 Abbott Laboratories
- 17.6 Takeda Pharmaceuticals
- 17.7 Bristol-Myers Squibb
- 17.8 MindMed
- 17.9 VistaGen Therapeutics
- 17.10 Actavis
- 17.11 Bionomics
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

