
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Generative Design Software Market Size 2024 | USD 398.32 million |
| Generative Design Software Market , CAGR | 10.69% |
| Generative Design Software Market Size 2032 | USD 949.89 million |
Market Overview
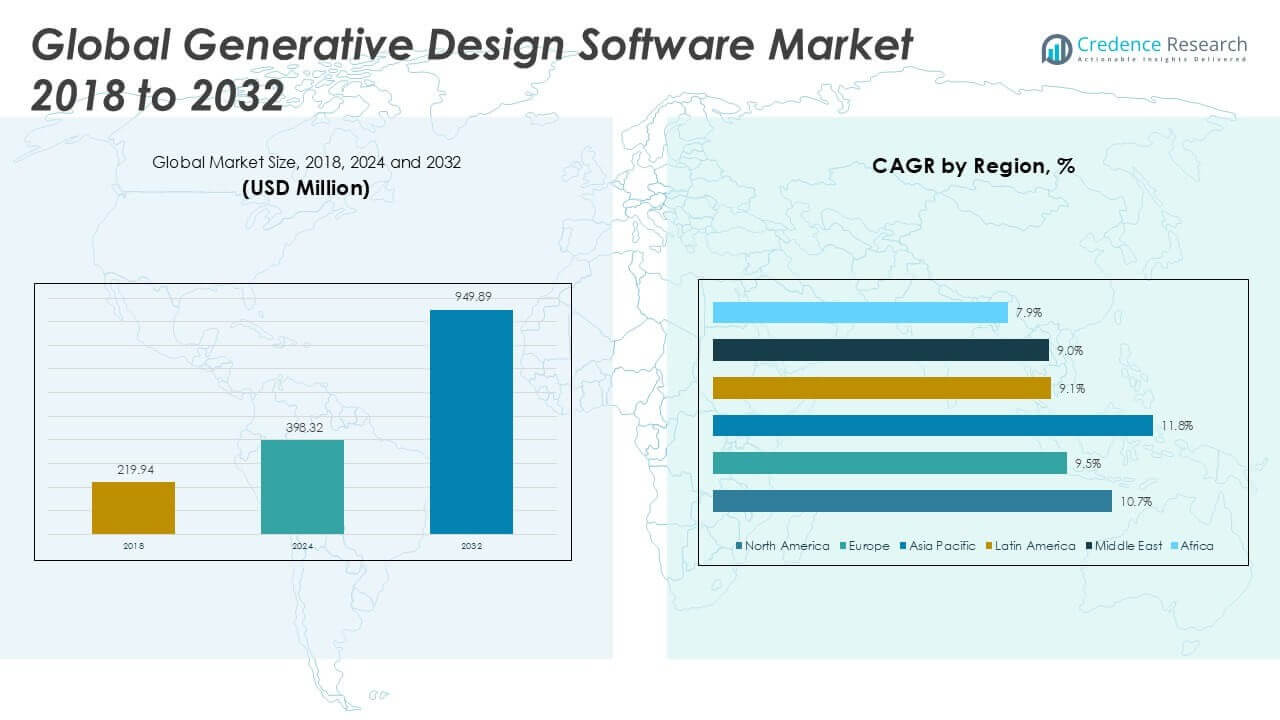
Generative Design Software Market size was valued at USD 219.94 million in 2018 to USD 398.32 million in 2024 and is anticipated to reach USD 949.89 million by 2032, at a CAGR of 10.69% during the forecast period.
The Generative Design Software market is propelled by the growing demand for innovative, efficient product development across industries such as automotive, aerospace, architecture, and manufacturing. Organizations are increasingly adopting generative design solutions to optimize material usage, reduce costs, and accelerate design cycles through AI-driven automation and simulation capabilities. The push for lightweight and sustainable products further fuels market growth, as generative design enables rapid prototyping and the creation of complex, performance-driven structures that traditional methods cannot achieve. Key trends include the integration of generative design with cloud-based platforms and advanced manufacturing technologies such as additive manufacturing and digital twins, supporting greater collaboration and scalability. The market is also witnessing increased investment in R&D and expanding adoption among small and medium-sized enterprises, as software providers offer more accessible, user-friendly interfaces. As industries focus on digital transformation and innovation, generative design software continues to gain traction as a critical enabler of next-generation engineering solutions.
The Generative Design Software Market demonstrates robust growth across major regions, including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in technological adoption, fueled by innovation in the United States and Canada, while Europe benefits from strong industrial bases in Germany, the United Kingdom, and France. Asia Pacific experiences rapid expansion due to significant investments in manufacturing and digital transformation across China, Japan, and India. Latin America, the Middle East, and Africa are witnessing steady adoption as awareness of advanced engineering tools increases. Key players shaping the competitive landscape include Autodesk, Inc., Siemens AG, and Dassault Systèmes, each offering comprehensive generative design solutions tailored to diverse industry needs. Altair Engineering, Inc. also stands out, leveraging deep expertise in simulation-driven design to deliver innovative products that address evolving customer requirements globally.
Market Insights
- The Generative Design Software Market was valued at USD 398.32 million in 2024 and is projected to reach USD 949.89 million by 2032, registering a CAGR of 10.69% during the forecast period.
- The market benefits from strong demand in automotive, aerospace, and architecture sectors, where companies seek to optimize product design, reduce costs, and accelerate development cycles through AI-driven automation.
- Major trends include the growing integration of generative design tools with cloud-based platforms and advanced manufacturing technologies such as additive manufacturing, enabling rapid prototyping and efficient production.
- Leading players such as Autodesk, Inc., Siemens AG, Dassault Systèmes, and Altair Engineering, Inc. compete by expanding their product portfolios, investing in R&D, and forming strategic partnerships to strengthen their market positions.
- The market faces restraints from high initial implementation costs, workforce skill gaps, and integration challenges with legacy IT infrastructure, which can slow widespread adoption, particularly among small and medium-sized enterprises.
- North America, Europe, and Asia Pacific remain the primary regions driving global market growth, with the United States, Germany, China, and Japan as key contributors due to their strong focus on innovation and advanced manufacturing.
- Continuous advancements in artificial intelligence, cloud accessibility, and simulation capabilities are expected to shape future market expansion, encouraging broader adoption across diverse industry verticals.
Market Drivers
Accelerating Demand for Advanced Product Optimization and Cost Reduction
Organizations across sectors such as automotive, aerospace, and construction are prioritizing efficiency and cost control. The Generative Design Software Market enables users to explore countless design iterations quickly, optimizing material usage and minimizing waste. This ability to automate complex calculations allows companies to develop high-performance products while reducing resource consumption. Cost savings and time efficiency are becoming critical competitive advantages, driving interest in digital solutions. Companies are replacing traditional, labor-intensive design processes with generative design tools to streamline workflows. The market gains momentum as businesses seek to lower expenses and enhance product quality through innovation.
- For instance, generative design software is increasingly being used to optimize material usage and minimize waste, reducing production costs.
Expanding Application Scope through AI and Simulation Integration
Artificial intelligence and simulation technologies are expanding the scope of generative design far beyond conventional CAD capabilities. The Generative Design Software Market benefits from integration with advanced simulation engines, allowing real-time analysis of stress, weight, and performance factors. It empowers engineers and designers to create structures and products that meet stringent technical requirements without extensive trial and error. These integrations facilitate design for manufacturability, accelerating the transition from concept to prototype. AI-driven features in generative design software support the exploration of unconventional solutions that were previously unattainable. Companies are leveraging these advancements to bring unique, optimized products to market more rapidly.
- For instance, AI-powered generative design solutions are enabling real-time analysis of stress, weight, and performance factors, improving design accuracy.
Rising Adoption Driven by Sustainability and Lightweighting Initiatives
Global focus on sustainability is a powerful market driver, with industries seeking ways to reduce their environmental impact. The Generative Design Software Market plays a pivotal role in enabling lightweight designs and sustainable material choices. It helps manufacturers meet regulatory requirements and consumer expectations for greener products. The software’s ability to generate intricate geometries supports both lightweighting and resource conservation initiatives. This trend aligns with the adoption of advanced manufacturing methods such as additive manufacturing, where material efficiency is paramount. Companies adopt generative design to remain compliant and relevant in evolving markets focused on sustainability.
Cloud Integration and Accessibility Promoting Wider Adoption
Cloud-based deployment models and intuitive user interfaces are making generative design accessible to a broader range of organizations, including small and medium-sized enterprises. The Generative Design Software Market is seeing increased demand as cloud integration simplifies collaboration and provides scalable computing power. It removes traditional barriers related to hardware costs and software complexity. Enhanced accessibility supports distributed teams and remote work environments, expanding the user base for generative design solutions. Vendors are focusing on user-friendly interfaces to lower training requirements and speed up onboarding. These developments enable more businesses to harness the benefits of generative design in their operations.
Market Trends
Growing Integration with Advanced Manufacturing Technologies
The convergence of generative design and advanced manufacturing methods continues to redefine engineering workflows. The Generative Design Software Market is witnessing stronger integration with additive manufacturing, enabling seamless transition from design to production. It supports the creation of complex, lightweight structures that were previously impractical with conventional manufacturing. Companies are leveraging this synergy to innovate faster and achieve greater design flexibility. The trend supports rapid prototyping and customization, offering competitive advantages in time-to-market and differentiation. Integration with advanced robotics and digital fabrication processes further expands possibilities for new product development.
- For instance, additive manufacturing is increasingly being integrated with generative design to create lightweight, complex structures.
Rising Adoption of Cloud-Based and Collaborative Platforms
The movement toward cloud-based platforms is transforming how organizations deploy and use generative design solutions. The Generative Design Software Market is responding with software-as-a-service (SaaS) models that facilitate real-time collaboration, data sharing, and scalability. It enables geographically distributed teams to work seamlessly on shared projects, improving efficiency and creativity. Cloud solutions reduce dependence on high-end local hardware, making powerful design tools accessible to a wider user base. Vendors are investing in security and interoperability to ensure smooth integration with existing digital ecosystems. This trend is fostering greater democratization and adoption of generative design across industries.
- For instance, vendors are investing in security and interoperability to ensure smooth integration with existing digital ecosystems.
Increasing Incorporation of Artificial Intelligence and Machine Learning
Artificial intelligence and machine learning are playing a pivotal role in elevating generative design capabilities. The Generative Design Software Market incorporates AI-driven algorithms to analyze constraints, generate optimized solutions, and learn from user feedback. It enables designers to explore thousands of options and receive intelligent recommendations that align with performance and cost criteria. AI integration enhances design creativity and efficiency, moving generative design beyond automation toward true co-creation between human and machine. Organizations benefit from accelerated innovation cycles and data-driven decision-making. This trend is shaping the next generation of engineering design processes.
Expanding Use Cases across Diverse Industry Verticals
Diverse sectors are recognizing the value of generative design beyond traditional engineering fields. The Generative Design Software Market is expanding into architecture, consumer goods, healthcare devices, and even fashion, supporting the development of highly customized, high-performance products. It addresses the growing demand for individualized solutions and complex geometries that conventional tools cannot deliver. Cross-industry adoption drives further software refinement and encourages new partnerships between technology providers and end-users. The trend signals a broadening impact of generative design on innovation strategies worldwide. Software developers are responding with vertical-specific features and support to meet evolving market needs.
Market Challenges Analysis
Complexity of Adoption and Skill Gaps in Workforce
The sophisticated nature of generative design tools creates barriers for many organizations. The Generative Design Software Market faces challenges as companies must invest in workforce training and adapt established design processes to fully utilize new software. It demands a high level of technical expertise, which can be difficult to develop quickly, especially for small and medium-sized enterprises. Resistance to change and a lack of familiarity with generative algorithms can slow down implementation. The steep learning curve may lead to underutilization of advanced features, limiting the return on investment. Companies must prioritize ongoing education and knowledge sharing to bridge these gaps.
- For instance, companies must invest in workforce training to bridge skill gaps and fully utilize generative design software.
Integration Issues and Data Security Concerns
Seamless integration with existing design and manufacturing systems remains a significant challenge for the Generative Design Software Market. Legacy infrastructure and proprietary software can limit interoperability, leading to inefficiencies and workflow disruptions. It may require costly customization or the development of new data exchange protocols to achieve optimal results. Data security and intellectual property protection are persistent concerns, particularly when deploying cloud-based generative design solutions. Organizations need robust cybersecurity measures to safeguard sensitive information and maintain compliance with regulations. Addressing these integration and security issues is vital for ensuring long-term adoption and market growth.
Market Opportunities
Expansion into New Industry Verticals and Customized Solutions
The Generative Design Software Market presents significant opportunities through its expansion into new industry verticals such as healthcare, consumer products, and architecture. Organizations in these fields seek solutions that can deliver highly customized, performance-driven products. It supports the creation of intricate geometries and design optimization, unlocking new value for sectors that traditionally relied on standard processes. Companies are looking for tailored software features that address specific regulatory and technical requirements unique to each industry. This market shift creates space for software providers to develop specialized modules and services. Expanding applications allow generative design vendors to reach new customer segments and diversify their revenue streams.
Advancement in AI Integration and Cloud-Based Deployment
The integration of artificial intelligence with generative design software opens up opportunities for greater automation and design intelligence. The Generative Design Software Market can leverage AI to offer real-time feedback, predictive analysis, and continuous improvement, transforming traditional design cycles. Cloud-based deployment further enhances accessibility, scalability, and collaboration for global teams, making advanced generative design tools available to organizations of all sizes. The move toward flexible, subscription-based models supports wider adoption across both large enterprises and small businesses. These advancements position the market to address rising demands for speed, innovation, and cost efficiency in product development. Vendors who prioritize AI and cloud integration can gain a competitive advantage and drive future market growth.
Market Segmentation Analysis:
By Deployment Model:
The Generative Design Software Market divides by deployment model into on-premises and cloud segments, reflecting the evolving needs of enterprises seeking flexibility, control, and scalability. On-premises deployment appeals to organizations requiring high levels of data security, compliance, and direct control over IT infrastructure. It remains a preferred option for large enterprises with dedicated resources and strict internal policies. However, the cloud segment is experiencing strong growth due to its cost-effectiveness, scalability, and accessibility. Cloud-based solutions facilitate seamless collaboration across distributed teams and support rapid deployment, enabling companies to respond quickly to market demands. Small and medium-sized enterprises, in particular, are embracing cloud deployment to minimize upfront investments and access advanced generative design capabilities without heavy infrastructure commitments.
By Component:
The Generative Design Software Market splits into software and services. Software forms the core of the market, driving adoption by offering intuitive design interfaces, AI-driven algorithms, and powerful simulation tools. It addresses the growing need for automation, efficiency, and design optimization across multiple industries. Services, including implementation, consulting, training, and support, complement the software segment by helping organizations maximize software utility and streamline integration into existing workflows. The demand for expert services is rising as companies look for tailored solutions and guidance to realize the full potential of generative design technology.
By Application:
The Generative Design Software Market covers product design and development, cost optimization, and other emerging use cases. Product design and development is the leading application, with businesses leveraging generative design to create innovative, high-performance products more efficiently. It enables engineers to explore numerous design alternatives, optimize material usage, and shorten development cycles. Cost optimization represents another significant application, with organizations utilizing generative design to reduce waste, manage resources, and improve overall cost efficiency. The "others" category encompasses a range of new and evolving applications, such as process optimization, rapid prototyping, and sustainability initiatives. These segments collectively underscore the versatility and transformative impact of generative design software across diverse industry verticals.
Segments:
Based on Deployment Model:
- On-premises
- Cloud
Based on Component:
- Software
- Services
Based on Application:
- Product Design and Development
- Cost Optimization
- Others
Based on End User Industry:
- Automotive
- Aerospace and Defense
- Healthcare and Medical
- Industrial Solutions
- Consumer Products
- Architecture and Construction
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Generative Design Software Market
North America Generative Design Software Market grew from USD 83.96 million in 2018 to USD 150.25 million in 2024 and is projected to reach USD 359.45 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.7%. North America is holding a 38% market share. The United States and Canada lead adoption, driven by strong investments in digital transformation and advanced manufacturing. Large enterprises across automotive, aerospace, and consumer goods industries use generative design to optimize innovation and productivity. The region’s focus on R&D and early adoption of cloud-based platforms supports market expansion. High technology awareness and a skilled workforce position North America at the forefront of generative design advancements. Key companies in the U.S. play a central role in global market leadership.
Europe Generative Design Software Market
Europe Generative Design Software Market grew from USD 45.79 million in 2018 to USD 78.85 million in 2024 and is estimated to reach USD 172.83 million by 2032, with a CAGR of 9.5%. Europe commands a 18% market share. Germany, the United Kingdom, and France anchor market activity, supported by a robust industrial base and regulatory push for digital innovation. European automotive and aerospace sectors leverage generative design for lightweighting and sustainability. Strategic collaborations between industry and research institutions accelerate adoption. The market benefits from funding initiatives and a growing emphasis on green engineering solutions. Key European software vendors and system integrators enhance regional competitiveness.
Asia Pacific Generative Design Software Market
Asia Pacific Generative Design Software Market grew from USD 67.11 million in 2018 to USD 127.97 million in 2024 and is forecast to reach USD 331.43 million by 2032, posting a CAGR of 11.8%. Asia Pacific accounts for 35% market share. China, Japan, and India drive growth through significant investments in smart manufacturing and infrastructure. Rapid industrialization and government support for advanced technologies encourage widespread use of generative design tools. Local and multinational companies in the region accelerate digital transformation to remain globally competitive. Cloud adoption and expanding R&D capacity further strengthen market prospects. Asia Pacific’s diverse manufacturing landscape creates opportunities for customization and industry-specific applications.
Latin America Generative Design Software Market
Latin America Generative Design Software Market grew from USD 10.89 million in 2018 to USD 19.48 million in 2024 and is set to reach USD 41.37 million by 2032, registering a CAGR of 9.1%. Latin America holds a 4% market share. Brazil and Mexico are at the forefront, with automotive and industrial sectors leading software uptake. Regional market growth is supported by increasing awareness of digital innovation and efficiency gains. Economic modernization initiatives encourage the adoption of advanced engineering tools. Collaboration between local industry players and global software vendors promotes technology transfer. Latin America’s potential for industrial diversification supports future market growth.
Middle East Generative Design Software Market
Middle East Generative Design Software Market grew from USD 8.30 million in 2018 to USD 14.07 million in 2024 and is expected to reach USD 29.76 million by 2032, at a CAGR of 9.0%. The Middle East commands a 3% market share. The United Arab Emirates and Saudi Arabia lead regional adoption, investing in smart infrastructure, aerospace, and construction. The region’s economic diversification strategies create a favorable environment for digital solutions. Major infrastructure projects and a focus on technology-driven growth support rising demand for generative design software. Market growth is underpinned by partnerships between international software firms and local organizations. Emphasis on sustainable urban development drives continued adoption.
Africa Generative Design Software Market
Africa Generative Design Software Market grew from USD 3.89 million in 2018 to USD 7.70 million in 2024 and is projected to reach USD 15.05 million by 2032, reflecting a CAGR of 7.9%. Africa represents a 2% market share. South Africa, Nigeria, and Egypt are key markets, benefiting from public and private investments in industrial modernization. The continent faces challenges in technology access and skills development but shows steady progress. Initiatives to enhance digital literacy and infrastructure are supporting gradual software adoption. The region’s industrial sectors leverage generative design for cost savings and efficiency improvement. Growth opportunities exist for market entrants focused on training and localized solutions.
Key Player Analysis
- Autodesk, Inc.
- Siemens AG
- PTC Inc.
- Dassault Systèmes
- Altair Engineering, Inc.
- ANSYS, Inc.
- Hexagon AB
- Bentley Systems, Inc.
- Evolver, Inc.
- Materialise NV
- Frustum Inc.
- Voxeljet AG
- Zebra Medical Vision
Competitive Analysis
The Generative Design Software Market features a dynamic competitive landscape shaped by prominent players including Autodesk, Inc., Siemens AG, Dassault Systèmes, Altair Engineering, Inc., ANSYS, Inc., and PTC Inc. These companies drive innovation by continuously expanding their generative design capabilities, leveraging artificial intelligence, and integrating advanced simulation and cloud-based solutions to enhance user experience. Market leaders prioritize the development of comprehensive, user-friendly software solutions that cater to a diverse range of industries, including automotive, aerospace, architecture, and consumer goods. Companies focus on expanding their portfolios through continuous product enhancements, ensuring compatibility with advanced manufacturing processes and digital ecosystems. Strategic partnerships, acquisitions, and collaborations with technology firms and research organizations support efforts to deliver more robust and integrated design platforms. Competitors also invest in customer support and training services to accelerate software adoption and maximize user value. The ability to provide industry-specific solutions, scalable cloud deployments, and seamless workflow integration has become a significant differentiator, with each company striving to strengthen its position in a market defined by rapid technological change and rising customer expectations.
Recent Developments
- In November 2023, Autodesk, Inc. launched Autodesk AI to remove non-productive work across the industries dealing with design. It provides generative and intelligent assistance capabilities and is available in the Design and Make Platform. Furthermore, it allows customers to discover freely while producing accurate, innovative, and precise results.
- In November 2023, Cognitive Design Systems (a manufacturer of 3D models) secured USD 2.2 million in funding. The funds accumulated will aid in the hi-tech development of CDS’s platform. Additionally, the company planned to expand its salesforce and geographic footprint in the U.S. and Europe.
- In October 2023, Altair launched Altair HyperWorks to enhance its design and simulation platform. It is a comprehensive, versatile, and open CAE platform that aids in transforming technology, offering an integrated solution to streamline workflow, enable innovation, and enhance user experiences.
- In April 2023, Cadence Design Systems, Inc. launched Cadence Allegro X AI. It is a system design AI technology offering revolutionary improvements in automation and performance. The product can be accessed through the Allegro X Design Platform and delivers an improved timeframe for PCB design.
- In February 2023, Hexagon AB launched a Design for Additive Manufacturing module with its Nexus Open Cloud platform. This enabled customers to utilize the Nexus browser interface to unite Simufact Additive process simulation software and Hexagon's MSC Apex Generative Design with AM Studio via the cloud.
Market Concentration & Characteristics
The Generative Design Software Market exhibits a moderately concentrated structure, with a few established technology firms holding significant influence due to their broad portfolios, advanced R&D capabilities, and global distribution networks. It features high entry barriers linked to technical complexity, the need for continuous innovation, and strong brand reputations among leading vendors. The market is characterized by rapid technological advancement, strong integration with cloud computing and AI, and an emphasis on user-centric design interfaces. Demand spans multiple industries, creating a diverse customer base that values scalable solutions and industry-specific functionalities. Product differentiation often centers on simulation accuracy, ease of use, interoperability with other digital tools, and ongoing support services. The market’s pace of change encourages companies to focus on agile development and collaborative partnerships to address evolving client needs, making it dynamic and innovation-driven.
Report Coverage
The research report offers an in-depth analysis based on Deployment Model, Component, Application, End User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The generative design software market is expected to grow rapidly with rising demand for automated and optimized design solutions.
- Integration with artificial intelligence and machine learning will enhance the ability to generate complex, efficient designs.
- Increasing adoption in industries like aerospace, automotive, and construction will drive market expansion.
- Cloud-based platforms are gaining popularity for offering better collaboration and computational power.
- Growing focus on sustainable and lightweight materials will boost the use of generative design tools.
- Software developers are enhancing compatibility with CAD and simulation tools to streamline workflows.
- Advancements in 3D printing technology will further accelerate the adoption of generative design solutions.
- Enterprises are investing in generative design to reduce development time and production costs.
- The demand for personalized and customized products is encouraging businesses to explore generative design.
- Strategic collaborations between software vendors and manufacturing firms are expected to drive innovation and adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Accelerating Demand for Advanced Product Optimization and Cost Reduction
Organizations in sectors such as automotive, aerospace, and construction are adopting generative design software to quickly explore design alternatives, optimize material usage, and minimize waste, resulting in significant cost savings and faster development cycles.
Expanding Application Scope through AI and Simulation Integration
The integration of artificial intelligence and advanced simulation engines enables real-time analysis of design constraints, allowing engineers to create high-performance, manufacturable products with fewer iterations and greater innovation.
Rising Adoption Driven by Sustainability and Lightweighting Initiatives
With increasing regulatory and consumer focus on sustainability, generative design software is being used to create lightweight structures and optimize resource use, helping manufacturers meet environmental goals and reduce their carbon footprint.
Cloud Integration and Accessibility Promoting Wider Adoption
Cloud-based deployment models and user-friendly interfaces are making generative design tools more accessible to small and medium-sized enterprises, enabling broader adoption by reducing hardware costs and supporting distributed, collaborative workflows.
Growing Integration with Advanced Manufacturing Technologies
The synergy between generative design and technologies like additive manufacturing and digital twins allows for rapid prototyping and the production of complex, customized components, driving innovation and expanding the range of feasible product designs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Generative Design Software Market?
What factors are driving the growth of the Generative Design Software Market?
What are some challenges faced by the Generative Design Software Market?
Who are the major players in the Generative Design Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Application
- 1.3.1 Product Design and Development
- 1.3.2 Cost Optimization
- 1.3.3 Others
- 1.4 By Deployment Model
- 1.4.1 On-premises
- 1.4.2 Cloud
- 1.5 By End User Industry
- 1.5.1 Automotive
- 1.5.2 Aerospace and Defense
- 1.5.3 Healthcare and Medical
- 1.5.4 Industrial Solutions
- 1.5.5 Consumer Products
- 1.5.6 Architecture and Construction
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 398.32 million → 2032: USD 949.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Generative Design Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Generative Design Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Generative Design Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Generative Design Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Generative Design Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Generative Design Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Generative Design Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Generative Design Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 398.32 million → 2032: USD 949.89 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Generative Design Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software
- 12.3.6.2 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Product Design and Development
- 12.4.6.2 Cost Optimization
- 12.4.6.3 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Model - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-premises
- 12.5.6.2 Cloud
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By End User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Automotive
- 12.6.6.2 Aerospace and Defense
- 12.6.6.3 Healthcare and Medical
- 12.6.6.4 Industrial Solutions
- 12.6.6.5 Consumer Products
- 12.6.6.6 Architecture and Construction
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Generative Design Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Generative Design Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Generative Design Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Generative Design Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Autodesk, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Dassault Systèmes
- 18.5 Altair Engineering, Inc.
- 18.6 PTC Inc.
- 18.7 ANSYS, Inc.
- 18.8 Hexagon AB
- 18.9 Bentley Systems, Inc.
- 18.10 Materialise NV
- 18.11 Frustum Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

