
Market Overview
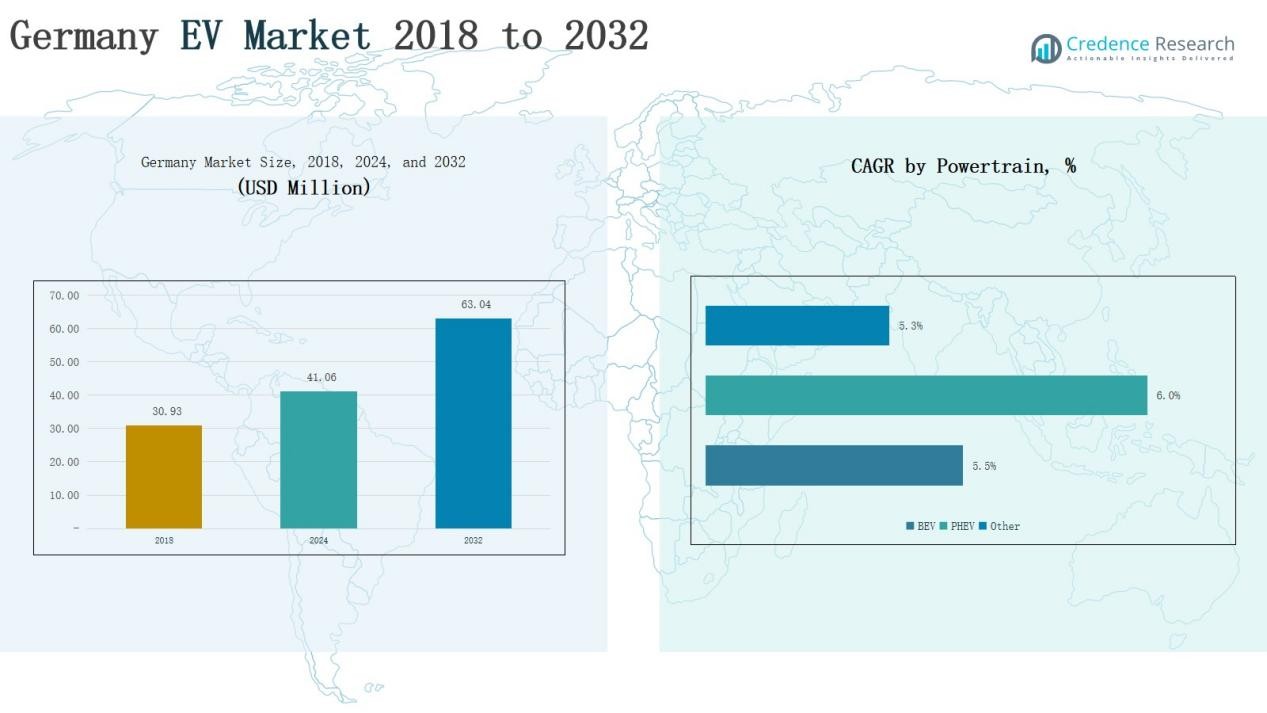
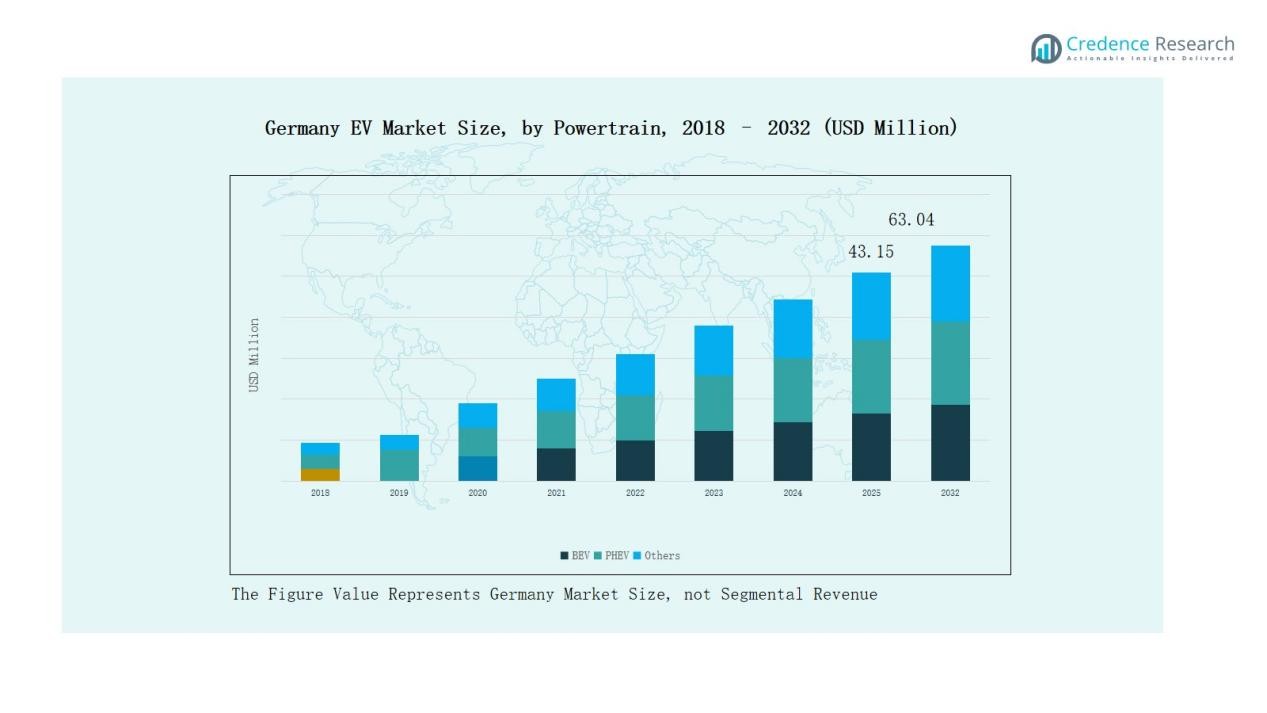
Germany Electric Vehicle (EV) Market size was valued at USD 30.93 million in 2018 to USD 41.06 million in 2024 and is anticipated to reach USD 63.04 million by 2032, at a CAGR of 5.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany EV Market Size 2024 | USD 41.06 Million |
| Germany EV Market, CAGR | 5.51% |
| Germany EV Market Size 2032 | USD 63.04 Million |
The Germany EV Market is highly competitive, driven by both domestic and international automakers. Volkswagen, BMW AG, Mercedes-Benz, and Audi leverage strong R&D capabilities and advanced production networks to secure leadership across BEV and PHEV segments. Tesla strengthens its premium positioning through advanced technology and a dedicated supercharger network, while Volvo, Renault S.A., Skoda, and Geely Holding expand accessibility with cost-efficient models tailored to diverse customer groups. Competitive strategies focus on charging partnerships, innovative battery technologies, and broad product portfolios. Regionally, Southern Germany led the market in 2024 with a 35% share, supported by major automaker headquarters, advanced infrastructure, and strong consumer purchasing power, making it the central hub for EV innovation and adoption.
Market Insights
- The Germany EV Market was USD 30.93 million in 2018, USD 41.06 million in 2024, and is projected to reach USD 63.04 million by 2032, growing at 5.51%.
- Battery Electric Vehicles led with 68% share in 2024, supported by incentives, emission regulations, and fast-charging expansion, while PHEVs held 27% and other powertrains 5%.
- Private buyers dominated with 72% share in 2024, driven by subsidies, tax benefits, and affordable BEV models, while corporate buyers held 28% supported by fleet electrification and leasing demand.
- Southern Germany led regionally with 35% share in 2024 due to automaker presence, strong infrastructure, and high consumer purchasing power, followed by Northern and Western regions at 25% each, and Eastern at 15%.
- Volkswagen, BMW AG, Mercedes-Benz, and Audi drive leadership in BEV and PHEV segments, while Tesla, Volvo, Renault, Skoda, and Geely expand affordability through broader product portfolios and strategic innovations.
Market Segment Insights
By Powertrain
Battery Electric Vehicles (BEVs) dominate the Germany EV Market, accounting for 68% share in 2024. Their leadership is driven by government incentives, stringent CO₂ emission targets, and the rapid expansion of charging infrastructure across urban and highway networks. Plug-in Hybrid Electric Vehicles (PHEVs) hold a 27% share, appealing to buyers who prioritize flexibility between electric driving and long-distance fuel reliability. Other powertrains, including fuel-cell EVs, represent the remaining 5% share, supported by early-stage investments and pilot projects in hydrogen mobility.
- For instance, PHEVs accounted for 10% of new registrations in Germany in April 2025 - 24,317 units - a jump of +60.7% year-on-year.
By End User
Private buyers lead the market with a 72% share in 2024, supported by strong subsidies, tax exemptions, and growing consumer preference for eco-friendly personal mobility. Affordable BEV models from domestic brands like Volkswagen and Renault further strengthen adoption in households. Corporate buyers hold a 28% share, with demand fueled by fleet electrification, sustainability commitments, and tax benefits for company-owned EVs. Logistics operators, mobility service providers, and employee leasing programs are expanding this segment steadily.
- For instance, Volkswagen introduced the ID. EVERY1, a compact battery electric vehicle priced around €20,000 ($21,000), aimed at offering affordable personal mobility with a range of over 155 miles.
Key Growth Drivers
Government Incentives and Regulatory Push
Government policies remain the backbone of EV adoption in Germany. Purchase subsidies, tax exemptions, and low-emission vehicle benefits significantly reduce the total cost of ownership. The German government also enforces strict CO₂ emission limits, compelling automakers to accelerate EV rollouts. Expansion of clean mobility zones in major cities further supports demand. These initiatives, combined with long-term commitments to phase out internal combustion engines, ensure steady growth momentum for the EV market.
- For instance, Volkswagen announced an €180 billion investment plan through 2027, with two-thirds allocated to electrification and digitalization, in line with the German government’s emission reduction targets.
Expansion of Charging Infrastructure
The rapid buildout of charging networks strongly boosts consumer confidence in EV adoption. Germany has invested in public fast-charging corridors across highways and dense urban regions, enabling long-distance travel convenience. Partnerships between energy providers, automakers, and government programs expand both public and private charging solutions. Home-charging subsidies encourage residential adoption, particularly in multi-family housing projects. By ensuring accessibility and reliability, charging infrastructure reduces range anxiety and promotes higher BEV penetration.
- For instance, in November 2023, Mercedes-Benz partnered with energy expert E.ON to develop and operate the Mercedes-Benz Charging Network in Europe, which is openly accessible to all vehicles. The partnership supports Mercedes-Benz's wider goal of having over 10,000 high-power charging points worldwide by the end of the decade.
Domestic Automotive Leadership and Innovation
Germany’s strong automotive industry provides a major advantage for EV growth. Leading brands such as Volkswagen, BMW, and Mercedes-Benz invest heavily in electrification, with extensive BEV and PHEV product portfolios. Advanced manufacturing facilities, R&D hubs, and dedicated EV production lines enhance supply capabilities. Continuous innovation in battery performance, connected vehicle features, and autonomous driving integration strengthens the value proposition. The presence of strong domestic players ensures competitiveness while meeting both local and global EV demand.
Key Trends & Opportunities
Rising Consumer Shift Toward BEVs
A clear transition is underway from PHEVs to BEVs, reflecting consumer preference for fully electric mobility. Falling battery prices and longer driving ranges make BEVs more appealing than ever. Domestic automakers are also scaling affordable entry-level EV models, broadening adoption among households. Government-supported leasing programs and attractive financing options further expand consumer accessibility. This trend positions BEVs to hold an increasing market share over the forecast period.
- For instance, BYD’s Dolphin hatchback offers 340 km WLTP range using a 44.9 kWh “blade” battery pack in its entry-level trim.
Integration of Smart and Connected Mobility
Opportunities are emerging from the integration of smart, connected features in EVs. Automakers in Germany are embedding advanced telematics, AI-driven energy optimization, and over-the-air software updates. These innovations improve performance, enhance user convenience, and unlock new revenue streams through subscription-based services. Coupled with the rise of vehicle-to-grid (V2G) solutions, connected EVs offer added value to consumers and grid operators alike. This trend drives technological leadership in Germany’s EV ecosystem.
- For instance, BMW announced that over 12 million vehicles are now connected to its My BMW app, enabling features like remote software upgrades and real-time vehicle data access.
Key Challenges
High Vehicle Costs and Affordability Gap
Despite subsidies, upfront EV prices remain higher compared to traditional vehicles. Battery costs, advanced technology integration, and supply chain complexities contribute to this premium. Many middle-income consumers delay EV purchases, limiting adoption beyond early adopters. While operational savings offset long-term expenses, affordability remains a major challenge. Achieving cost parity with internal combustion vehicles is crucial for wider market penetration.
Supply Chain Constraints and Battery Dependence
The EV industry faces supply chain risks, particularly for critical battery materials such as lithium, cobalt, and nickel. Global shortages and geopolitical dependencies create pricing volatility. Germany’s reliance on imports increases vulnerability, raising concerns over production scalability. Automakers are investing in local gigafactories and alternative chemistries, but short-term bottlenecks remain a barrier. Stable raw material access is essential to meet growing demand.
Uneven Charging Access Across Regions
Although infrastructure is expanding, disparities persist between urban and rural areas. Metropolitan regions enjoy dense charging availability, while remote areas lag behind, discouraging adoption outside cities. Limited high-speed charging capacity further slows BEV growth in long-distance travel use cases. Addressing these regional gaps requires coordinated government policies, public-private investment, and grid modernization. Ensuring equitable access to charging remains critical for nationwide adoption.
Regional Analysis
Northern Germany
Northern Germany holds 25% share of the Germany EV Market. The region benefits from strong wind energy generation, which supports sustainable EV charging. Hamburg and Bremen lead adoption with robust urban infrastructure and supportive municipal policies. Public transport electrification and large logistics hubs also strengthen demand. Manufacturers and suppliers collaborate with renewable projects to align EV use with clean energy. It remains a key growth area for sustainable urban mobility solutions.
Southern Germany
Southern Germany accounts for the largest share at 35%. The region is home to major automakers such as BMW, Audi, and Mercedes-Benz, which drive EV innovation and adoption. Dense urban centers like Munich and Stuttgart provide strong consumer demand supported by advanced charging networks. High purchasing power further fuels private EV ownership. Corporate fleets also expand steadily in industrial hubs. It plays a pivotal role in shaping product development and consumer adoption trends nationwide.
Eastern Germany
Eastern Germany represents 15% share of the market. The region has seen steady adoption due to government-backed investments in renewable energy and mobility infrastructure. Cities like Leipzig and Dresden act as focal points for EV pilot programs and charging rollouts. Lower population density slows adoption compared to western regions, but incentives are encouraging uptake. Emerging industrial sites contribute to growing fleet demand. It is gradually expanding its role within the national EV ecosystem.
Western Germany
Western Germany holds 25% share. Strong industrial bases and urban centers such as Cologne, Düsseldorf, and Frankfurt foster demand for EVs across both private and corporate segments. Extensive highway networks in the region make fast-charging infrastructure essential, which has been expanding rapidly. Consumers benefit from strong subsidy schemes and brand access through leading dealerships. Corporate electrification also gains traction in logistics and leasing services. It remains a balanced market with both consumer and industrial growth drivers.
Market Segmentations:
By Powertrain
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Other Powertrains
By End User
- Private Buyers
- Corporate Buyers
By Region
- Northern
- Southern
- Eastern
- Western
Competitive Landscape
The Germany EV Market is shaped by strong competition among domestic and international automakers. Leading companies such as Volkswagen, BMW, Mercedes-Benz, and Audi leverage advanced R&D capabilities, manufacturing strength, and established distribution networks to dominate both BEV and PHEV segments. Tesla holds a strong position in the premium EV category, supported by its dedicated supercharger network and technology-driven appeal. Volvo, Renault, Skoda, and Geely enhance accessibility by offering cost-effective models for mass-market adoption. Competitive strategies focus on expanding charging partnerships, improving battery efficiency, and launching models across various price points. Financial strength and innovation pipelines enable key players to maintain resilience against supply chain challenges and regulatory shifts. The market also witnesses growing fleet electrification demand from corporate buyers, encouraging automakers to develop tailored leasing and fleet solutions. Intense competition drives continuous innovation, ensuring rapid evolution of Germany’s EV ecosystem.
Key Players
Recent Developments
- In September 2025, BMW Group and E.ON introduced Germany’s first commercial Vehicle-to-Grid (V2G) solution, enabling bidirectional charging for BMW iX3 customers with a dedicated energy tariff.
- In September 2025, Volkswagen Group subsidiary Elli also launched a pilot project for bidirectional charging in private households, starting participant recruitment with an 11 kW charger solution.
- In February 2025, Tesla acquired parts of insolvent German parts maker Manz AG, including movable assets, property in Reutlingen, and more than 300 employees.
Report Coverage
The research report offers an in-depth analysis based on Powertrain, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Automakers will expand BEV portfolios across premium and mass-market segments.
- Charging infrastructure will grow rapidly, with more fast-charging corridors nationwide.
- Private buyers will continue leading adoption, supported by stronger subsidy schemes.
- Corporate fleet electrification will increase as businesses pursue sustainability goals.
- Domestic automakers will strengthen battery manufacturing and local gigafactory capacity.
- Connected and smart mobility features will become standard in most EV models.
- Partnerships between energy providers and automakers will accelerate grid integration.
- Hydrogen mobility pilots will gain traction in heavy-duty transport and logistics.
- Regional adoption gaps will narrow as rural charging investments expand.
- Competitive intensity will rise as foreign brands challenge domestic leaders with affordable models.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Incentives and Regulatory Push
Generous purchase subsidies, tax exemptions, and strict CO₂ emission regulations in Germany significantly lower the total cost of EV ownership and compel automakers to accelerate EV rollouts, driving market growth.
Expansion of Charging Infrastructure
Rapid investment in public and private charging networks, including fast-charging corridors and home-charging subsidies, reduces range anxiety and makes EV adoption more practical for both urban and rural consumers.
Domestic Automotive Leadership and Innovation
Germany’s leading automakers, such as Volkswagen, BMW, and Mercedes-Benz, are heavily investing in electrification, advanced battery technologies, and dedicated EV production lines, ensuring a robust supply of innovative EV models.
Rising Consumer Shift Toward BEVs
Falling battery costs, longer driving ranges, and the introduction of affordable BEV models are shifting consumer preference away from PHEVs toward fully electric vehicles, increasing BEV market share.
Corporate Fleet Electrification
Growing sustainability commitments and tax benefits are encouraging businesses to electrify their fleets, boosting demand for EVs in the corporate segment and supporting overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Germany EV Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Germany EV Market projected to grow between 2025 and 2032?
Which Germany EV Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Germany EV Market?
Who are the leading companies in the Germany EV Market?
Which region commanded the largest share of the Germany EV Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Private Buyers
- 1.2.2 Corporate Buyers
- 1.3 By Powertrain
- 1.3.1 Battery Electric Vehicles (BEV)
- 1.3.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 1.3.3 Other Powertrains
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 41.06 million → 2032: USD 63.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Electric Vehicle (EV) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Electric Vehicle (EV) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Germany Electric Vehicle (EV) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Germany Electric Vehicle (EV) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Electric Vehicle (EV) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Electric Vehicle (EV) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Electric Vehicle (EV) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Electric Vehicle (EV) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 41.06 million → 2032: USD 63.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Electric Vehicle (EV) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Private Buyers
- 12.3.7.2 Corporate Buyers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Powertrain - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Battery Electric Vehicles (BEV)
- 12.4.7.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 12.4.7.3 Other Powertrains
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Electric Vehicle (EV) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Electric Vehicle (EV) Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Electric Vehicle (EV) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Electric Vehicle (EV) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Volkswagen
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BMW AG
- 18.4 Mercedes-Benz
- 18.5 Tesla
- 18.6 Audi
- 18.7 Volvo
- 18.8 Skoda
- 18.9 Renault S.A.
- 18.10 Geely Holding
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

