
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Green Data Center Market Size 2024 | USD 2,880.94 million |
| Germany Green Data Center Market, CAGR | 19.55% |
| Germany Green Data Center Market Size 2032 | USD 12,022.28 million |
Market Overview
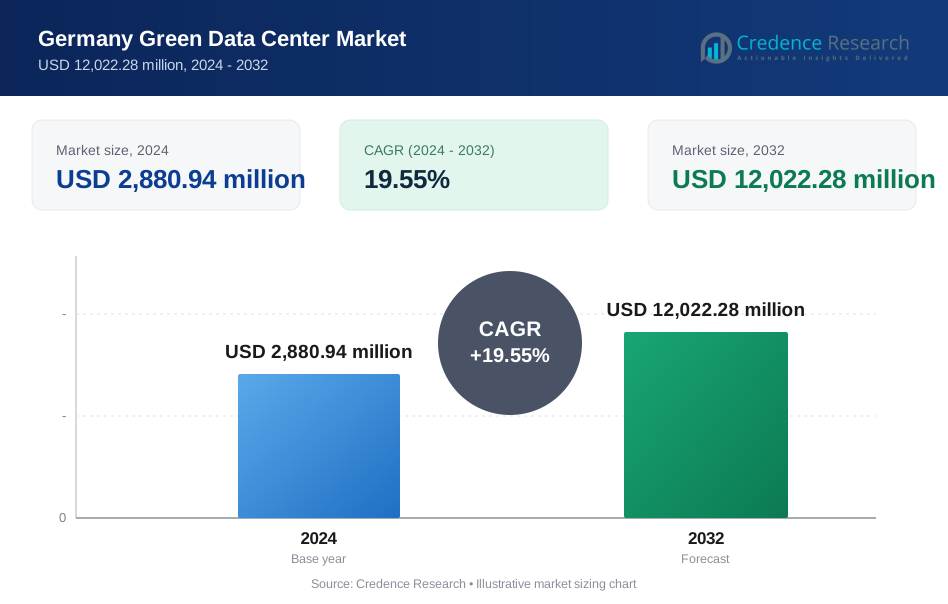
The Germany Green Data Center Market is projected to grow from USD 2,880.94 million in 2024 to an estimated USD 12,022.28 million by 2032, with a compound annual growth rate (CAGR) of 19.55% from 2025 to 2032. This substantial growth is driven by the increasing demand for energy-efficient and sustainable data infrastructure, aligning with Germany's commitment to environmental responsibility and digital transformation.
Key drivers of this growth include stringent environmental regulations, rising energy costs, and the need for scalable and efficient data storage solutions. Trends such as the adoption of artificial intelligence (AI), Internet of Things (IoT), and big data analytics are accelerating the demand for green data centers. Additionally, government initiatives promoting sustainable practices and investments in green technologies are fostering a favorable environment for market development.
Geographically, Frankfurt stands out as the primary hub for data centers in Germany, hosting a significant concentration of facilities due to its strategic location and robust infrastructure. Other cities like Berlin, Munich, and Hamburg are also witnessing growth in data center investments. Key players in the German green data center market include NTT DATA, Digital Realty, Equinix, and Rittal, among others. These companies are actively investing in sustainable technologies and expanding their presence to meet the growing demand for eco-friendly data storage solutions.
Market Insights
- The Germany Green Data Center Market is projected to grow from USD 2,880.94 million in 2024 to USD 12,022.28 million by 2032, with a CAGR of 19.55% from 2025 to 2032.
- The global Green Data Center Market is expected to grow from USD 59,645.02 million in 2024 to USD 239,470.06 million by 2032, at a CAGR of 18.98% from 2025 to 2032.
- Increasing demand for energy-efficient and sustainable data infrastructure, driven by Germany's focus on environmental responsibility and digital transformation.
- Rising energy costs and stringent environmental regulations are prompting data centers to adopt green technologies for better efficiency and sustainability.
- High initial capital investment required for the implementation of renewable energy solutions and energy-efficient infrastructure may limit market growth for smaller enterprises.
- Limited availability of green-certified real estate and infrastructure bottlenecks in some regions can delay the expansion of green data centers.
- Frankfurt leads the market due to its strategic location, robust infrastructure, and access to renewable energy, followed by other key cities like Berlin, Munich, and Hamburg.
- Leading companies such as NTT DATA, Digital Realty, Equinix, and Rittal are investing in sustainable technologies and expanding their presence to meet the growing demand for green data storage solutions.
Report Scope
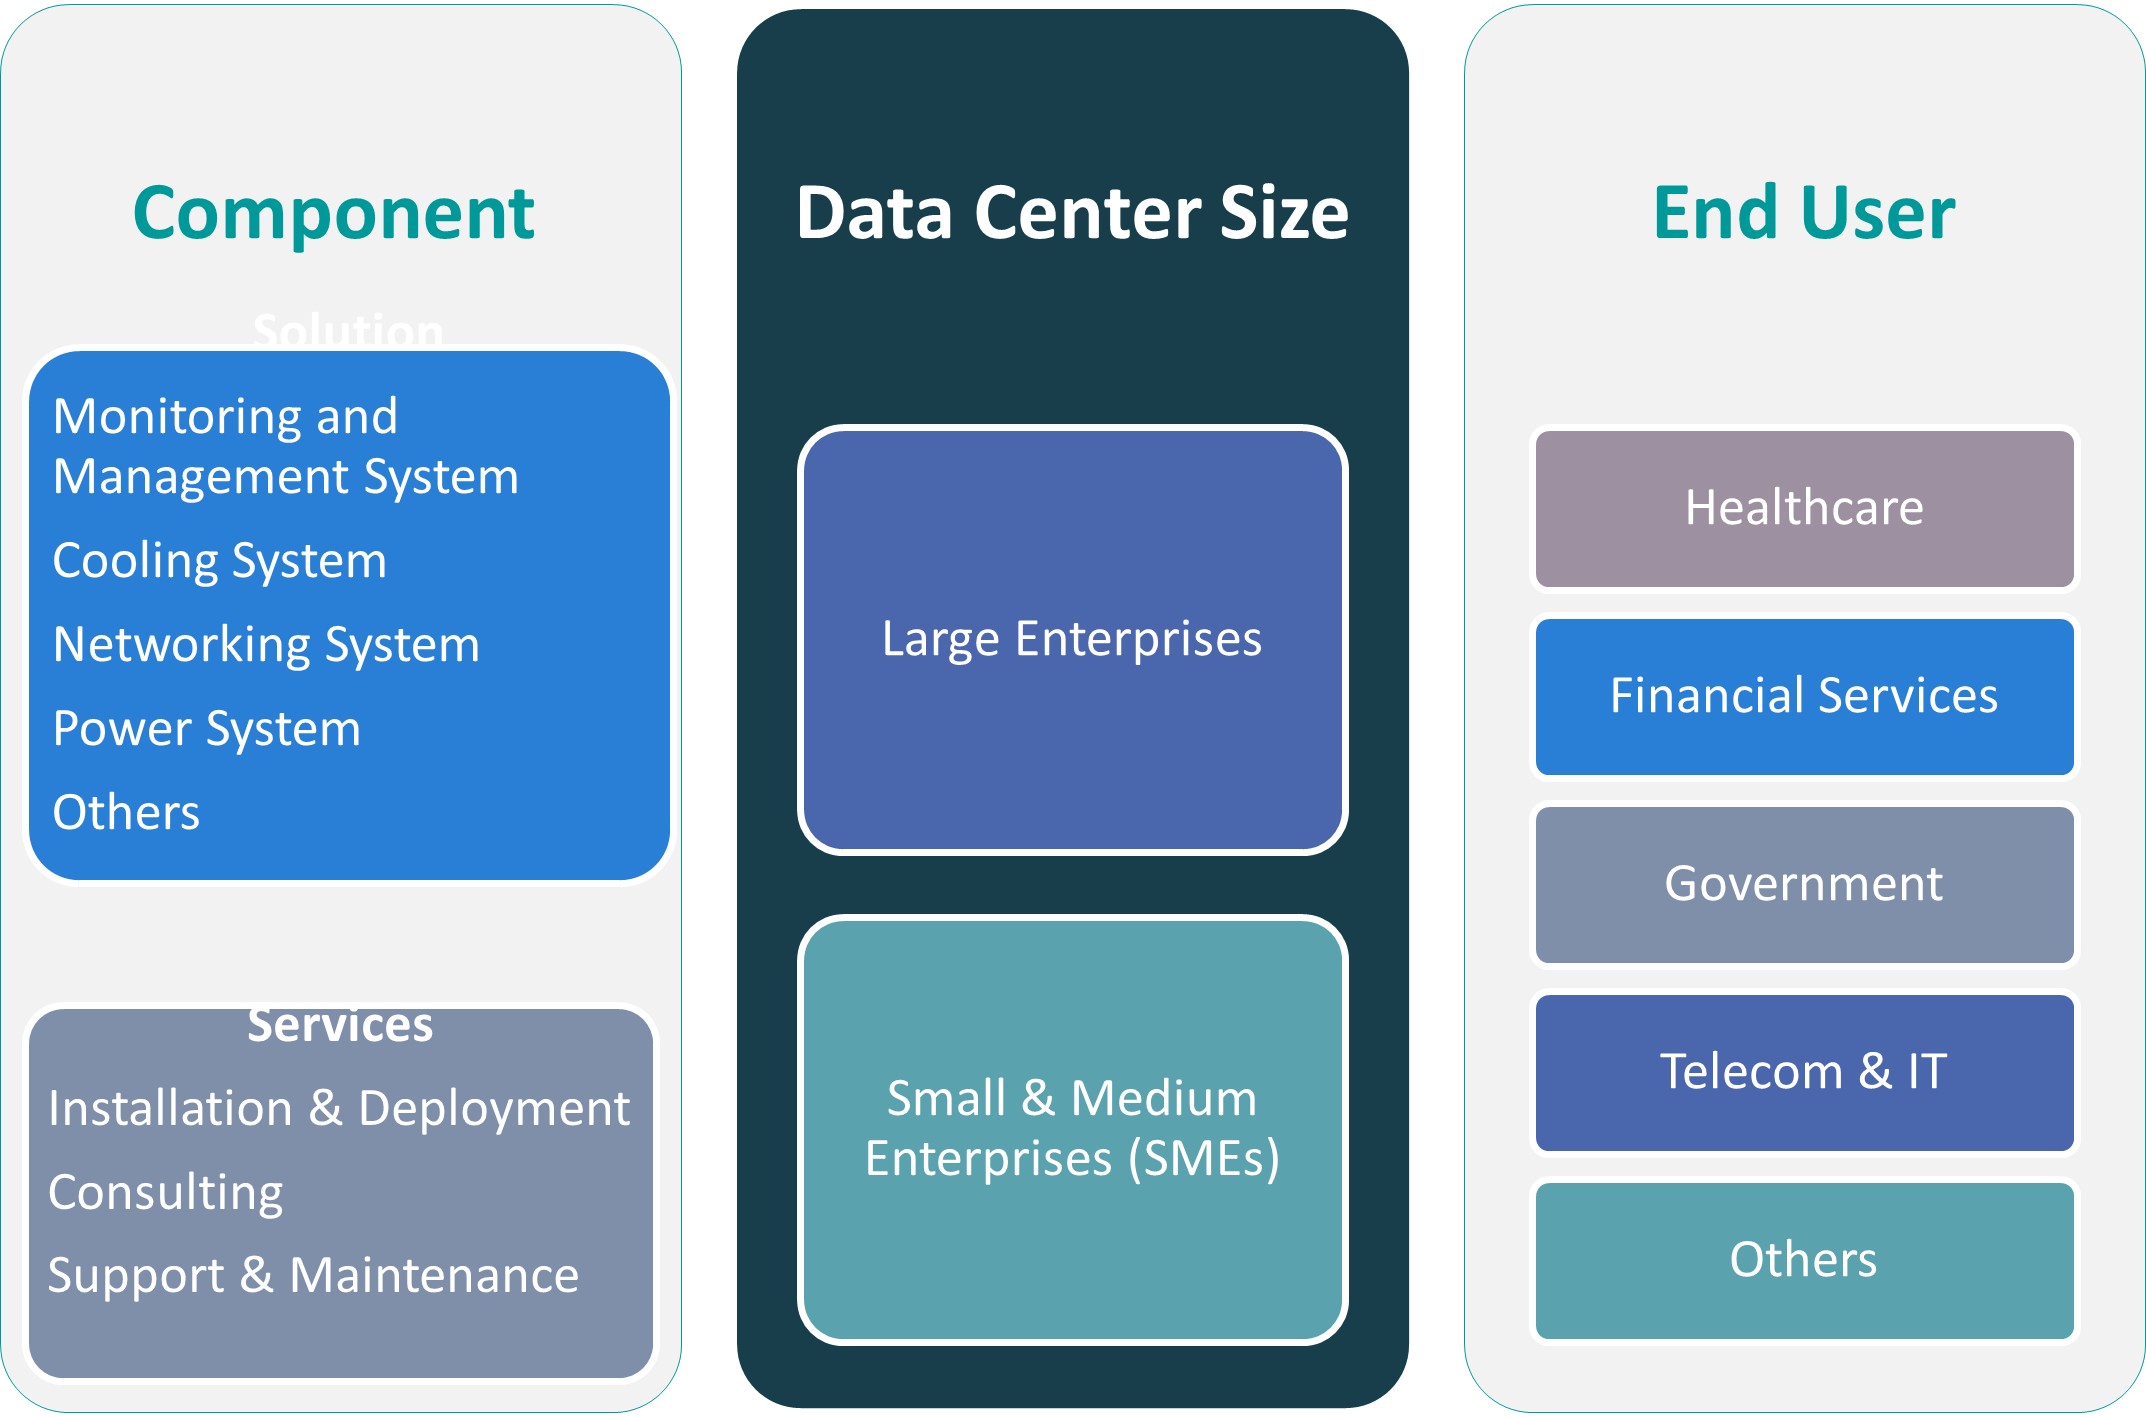
This report segments the Germany Green Data Center Market as follows:
Market Drivers
Corporate ESG Commitments and Green Branding Strategies
German enterprises are under growing pressure from stakeholders, investors, and consumers to meet Environmental, Social, and Governance (ESG) standards. As sustainability becomes a core business value, companies across sectors-from banking and automotive to manufacturing and telecommunications-are prioritizing green IT infrastructure to reflect their environmental responsibility. Hosting operations in green data centers enables companies to reduce Scope 2 emissions, align with ESG metrics, and enhance corporate reputation. Data center service providers are responding to this shift by marketing green credentials such as low Power Usage Effectiveness (PUE) ratios, zero-emission operations, and renewable energy integration. This eco-conscious branding not only attracts enterprise clients but also boosts investor confidence, especially as ESG-compliant investments gain traction in capital markets. Thus, the convergence of green branding and corporate sustainability strategies acts as a major catalyst for the German green data center market’s expansion.
Government Incentives and Infrastructure Modernization Initiatives
Germany’s government actively supports green transformation through financial incentives, public-private partnerships, and research grants. Incentive schemes, such as subsidies for renewable installations and tax benefits for energy-efficient upgrades, are making green data centers financially viable for both incumbents and new entrants. Additionally, Germany’s Digital Strategy 2025 and the Broadband Expansion Program emphasize the modernization of digital infrastructure with an environmental lens. These national initiatives encourage the deployment of smart grids, fiber optic networks, and intelligent building management systems-all of which complement the growth of green data centers. Local municipalities and technology parks are also facilitating access to green-certified real estate, clean energy grids, and waste heat reuse technologies. Collectively, these initiatives reduce capital expenditure burdens, improve ROI, and create a conducive environment for market development. As the government continues to integrate digital transformation with ecological goals, the green data center industry in Germany is poised for sustained and scalable growth.
Stringent Environmental Regulations and Sustainability Mandates
Germany has established itself as a global leader in environmental policy and climate action, and this commitment strongly influences the data center industry. The country’s regulations, such as the Renewable Energy Sources Act (EEG) and the Energy Efficiency Act, compel data center operators to reduce carbon footprints and energy consumption. Under these frameworks, companies are required to implement energy-saving practices and adopt green energy sources. Furthermore, the EU’s broader climate goals-such as the European Green Deal and Climate Neutral Data Centre Pact-reinforce the urgency for Germany-based data centers to align with carbon neutrality targets by 2030. For instance, the colocation data centers in the country are already utilizing renewable energy sources extensively, consuming approximately 16 billion kilowatt-hours of electricity annually. Compliance with these policies is no longer optional but essential for operational legitimacy, pushing operators to deploy renewable-powered infrastructure, liquid cooling systems, and advanced power management tools. As a result, the legislative environment not only supports but accelerates the growth of the green data center market in Germany, fostering long-term sustainability in digital infrastructure.
Surge in Data Consumption and the Rise of Emerging Technologies
The digital economy in Germany is expanding rapidly, driven by the proliferation of cloud computing, 5G rollout, and Industry 4.0 initiatives. This rise in data consumption is creating an urgent need for scalable and energy-efficient data center solutions. Technologies such as the Internet of Things (IoT), artificial intelligence (AI), and machine learning generate large volumes of data that require real-time processing and secure storage. Traditional data centers face limitations in terms of power consumption and heat generation when supporting such computationally intensive workloads. In contrast, green data centers, with their energy-efficient servers, modular designs, and sustainable cooling mechanisms, provide an optimal solution. For instance, the same report notes that waste heat recovery systems in colocation data centers in Germany are contributing to significant energy savings, with facilities designed to produce more than 8,000 megawatt-hours of reusable heat annually. Their ability to support high-performance computing (HPC) environments without compromising environmental goals positions them as the backbone of Germany’s future tech landscape. Moreover, the integration of edge computing and distributed networks further intensifies demand for decentralized yet sustainable infrastructure, enhancing the value proposition of green data centers.
Market Trends
Modular and Scalable Green Data Center Designs
Modular data center construction is gaining momentum in Germany as organizations seek scalable, energy-efficient, and cost-effective infrastructure solutions. This trend involves prefabricated, containerized, or pod-based data center components that can be deployed quickly and scaled incrementally based on demand. Modular designs offer distinct energy efficiency benefits as they enable precise power and cooling delivery based on real-time usage, minimizing waste. These systems also integrate seamlessly with renewable energy sources and energy storage units, supporting sustainability goals. The flexibility of modular data centers makes them ideal for edge computing applications, disaster recovery zones, and smart city environments-where compact, agile deployment is essential. Additionally, modular systems allow for more accurate capacity planning, quicker ROI, and lower upfront capital investment compared to traditional brick-and-mortar facilities. In Germany, companies are increasingly adopting this approach to meet the dual demands of digital transformation and carbon footprint reduction. Vendors such as Rittal, Siemens, and Schneider Electric are leading the charge with turnkey modular solutions tailored for the German market. These installations not only ensure compliance with environmental standards but also support emerging applications such as autonomous vehicles and IoT networks. The move toward modularity is a strategic response to evolving market needs, and it is expected to define the next generation of green data infrastructure in the country.
Circular Economy Integration and Waste Heat Reuse
The integration of circular economy principles, particularly waste heat reuse, is emerging as a forward-looking trend in the Germany Green Data Center Market. As data centers generate significant heat during operation, innovative facilities are beginning to capture and repurpose this thermal energy to supply district heating networks, local residential areas, or nearby industrial operations. This approach not only reduces waste but also improves the overall energy balance and sustainability profile of the data center. Several urban projects in Germany-especially in Frankfurt and Düsseldorf-are already pioneering this model, where data centers are connected to municipal heating systems, enabling two-way environmental and economic value creation. The concept is gaining regulatory and public support, as it aligns with national energy efficiency strategies and reduces the need for fossil-based heating. In addition to heat reuse, data center operators are adopting practices such as IT asset recycling, sustainable building materials, and eco-friendly refrigerants to minimize environmental impact throughout the facility’s lifecycle. This circular approach reflects a broader commitment to sustainability that extends beyond power usage alone. By embedding resource efficiency into every operational layer, German data centers are redefining industry standards and paving the way for more integrated, environmentally intelligent infrastructure ecosystems.
Transition to Renewable Energy-Powered Data Centers
A prominent trend shaping the Germany Green Data Center Market is the accelerated transition toward data centers powered entirely by renewable energy. Operators are increasingly investing in on-site solar and wind energy generation, as well as long-term Power Purchase Agreements (PPAs) with certified green energy providers. For instance, a data center in Frankfurt has installed photovoltaic systems capable of generating 3 megawatts of solar energy annually, reducing its reliance on grid electricity and cutting carbon emissions by approximately 50,000 metric tons per year. This shift is being driven not only by compliance with national and EU-level climate regulations but also by the growing demand from clients for carbon-neutral operations. These renewable-powered data centers not only contribute to Germany’s goal of becoming climate-neutral by 2045 but also enhance the sustainability credentials of their tenants. Operators who adopt this approach are gaining competitive advantages, securing sustainability-conscious clients, and achieving operational cost efficiencies through long-term energy savings.
Adoption of Advanced Cooling Technologies for Energy Efficiency
Another significant trend in the Germany Green Data Center Market is the widespread adoption of advanced cooling technologies aimed at reducing energy consumption and improving operational efficiency. For instance, a data center in Munich has implemented liquid cooling systems, achieving a Power Usage Effectiveness (PUE) ratio of 1.2 and reducing cooling energy consumption by 30% compared to traditional air-based systems. These innovative technologies minimize power usage and reduce reliance on energy-intensive air conditioning systems. In regions like Hamburg, where ambient temperatures permit, operators are leveraging free cooling systems that utilize outside air to maintain optimal temperatures within the facility. This trend aligns with the broader industry goal of achieving lower PUE ratios-ideally below 1.3. In addition to energy savings, advanced cooling technologies also support longer equipment lifespans and reduced maintenance needs, which translates to cost savings and operational resilience. As sustainability becomes a core operational metric, the adoption of cutting-edge cooling systems is emerging as a defining feature of modern, green-certified data centers across Germany.
Market Challenges
High Capital Expenditure and Technological Complexity
The Germany Green Data Center Market faces significant challenges, particularly the high initial capital investment required to build and operate sustainable facilities. Transitioning from traditional data center infrastructure to green alternatives involves the integration of advanced technologies such as renewable energy systems, energy-efficient HVAC units, liquid cooling solutions, and intelligent power management systems. For instance, these technologies, while beneficial in the long term, demand substantial upfront financial commitment. Smaller enterprises and new entrants often find it difficult to access the funding necessary to deploy such solutions at scale. Incorporating green design principles and meeting stringent environmental certifications, such as LEED or TUV Rheinland, adds to the complexity and cost of project execution. Achieving these certifications requires compliance with strict standards and audits, which can increase both administrative and financial burdens. There are also challenges associated with the integration of on-site renewable energy sources. These require land availability, favorable weather conditions, and compatibility with local energy grids. In regions where utility-scale renewable energy is not yet reliable or affordable, operators may face additional burdens securing sustainable power at competitive prices. These financial and technological constraints limit the pace of green data center adoption, particularly among mid-sized players, and could slow the market's overall expansion unless mitigated by stronger incentives or collaborative public-private funding models
Limited Availability of Green Real Estate and Infrastructure Bottlenecks
Another pressing challenge is the limited availability of green-certified real estate and supporting infrastructure, particularly in urban hubs like Frankfurt, Berlin, and Munich. As demand for data storage and processing power continues to surge, the competition for suitable land parcels equipped with access to renewable power sources and efficient cooling environments intensifies. Existing brownfield sites often require costly retrofitting to meet modern green standards, while new developments face zoning restrictions, environmental impact assessments, and lengthy permitting procedures. Furthermore, power grid limitations and lagging renewable energy infrastructure in certain regions create bottlenecks that impede new facility deployments. Even when suitable locations are identified, delays in grid upgrades or insufficient local energy capacity can stall construction timelines and inflate costs. The challenge is further compounded by a growing need for data centers to be situated closer to end users, driven by latency-sensitive applications like autonomous systems and edge computing. This geographic pressure narrows location choices and amplifies infrastructure strain. To overcome these hurdles, Germany must accelerate the expansion of green utility grids and foster regional infrastructure partnerships. Without addressing these spatial and infrastructural constraints, the country's green data center ambitions may be constrained despite strong market demand.
Market Opportunities
Expansion of Renewable Energy Integration
A significant opportunity in the Germany Green Data Center Market lies in the continued expansion of renewable energy integration. As Germany progresses toward its climate-neutral goals by 2045, there is an increasing demand for data centers to operate sustainably. This presents a key opportunity for operators to invest in renewable energy sources such as wind, solar, and hydropower, as well as innovative energy storage solutions. By incorporating on-site renewable energy generation or entering long-term Power Purchase Agreements (PPAs) with green energy providers, data center operators can not only meet regulatory requirements but also lower operational costs. This growing emphasis on renewable energy offers data center operators a competitive advantage while contributing to the country’s sustainability objectives. The government's strong support through subsidies and incentives for clean energy projects further boosts this opportunity.
Growth in Edge Computing and Modular Data Centers
With the rise of edge computing and the increasing demand for low-latency services, Germany presents a significant market opportunity for decentralized, modular green data centers. These facilities, which are smaller, more flexible, and energy-efficient, cater to localized needs and reduce the environmental impact associated with traditional centralized data centers. As edge computing becomes integral to industries such as automotive, healthcare, and telecommunications, demand for modular green data centers will grow. Operators who adopt modular designs equipped with energy-efficient cooling systems and renewable energy integration can address the needs of diverse industries while supporting sustainability goals. This trend presents an opportunity for green data center providers to expand into emerging markets across smaller cities and rural regions, thus broadening their footprint and meeting the demands of a digitally transforming economy.
Market Segmentation Analysis
By Component
The components segment of the Germany Green Data Center Market includes solutions and services integral to the design and operation of energy-efficient data centers. Solutions within this segment consist of monitoring and management systems, cooling systems, networking systems, power systems, and others. Monitoring and management systems are essential for overseeing the performance and energy consumption of green data centers, ensuring operational efficiency and compliance with environmental standards. Cooling systems, particularly liquid cooling and free-air cooling, are key to reducing the energy intensity of data centers, addressing the challenges of high-density server environments. Networking systems facilitate seamless data transfer while minimizing energy use, contributing to the overall sustainability of the infrastructure. Power systems, which often rely on renewable energy sources such as solar and wind, are critical to meeting the growing demand for sustainable power. The “Others” category includes additional systems and infrastructure that support green initiatives, such as waste heat recovery systems and smart grid technologies. The services aspect of the component segment includes installation & deployment, consulting, and support & maintenance. These services are essential for ensuring the effective implementation and continued operation of green technologies in data centers.
By Data Center Type
The market is also segmented by data center type, with two primary categories: large enterprises and small & medium enterprises (SMEs). Large enterprises typically require substantial data processing capabilities, necessitating large-scale green data centers that can support high performance while adhering to environmental standards. These enterprises often have the resources to invest in cutting-edge technologies such as renewable energy integration and advanced cooling systems. In contrast, SMEs are increasingly adopting green data center solutions as the demand for energy-efficient and cost-effective infrastructure grows. While SMEs may not have the same scale as large enterprises, they seek scalable, modular, and energy-efficient solutions to meet their digital transformation needs.
Segments
Based on Component
- Solution
- Monitoring and Management System
- Cooling System
- Networking System
- Power System
- Others
- Services
- Installation & Deployment
- Consulting
- Support & Maintenance
Based on Data Center Type
- Large Enterprises
- Small & Medium Enterprises (SMEs)
Based on End User
- Healthcare
- Financial Services
- Government
- Telecom & IT
- Other
Based on Region
- Frankfurt
- Berlin
- Munich
- Hamburg
- Other Regions
Regional Analysis
Frankfurt (35%)
Frankfurt is the dominant region in the German green data center market, holding the largest market share of approximately 35%. This city is a key data center hub, benefiting from its central location within Europe, well-established infrastructure, and access to renewable energy sources. Frankfurt is home to several major data center providers and telecom operators who are leading the transition to green data centers. The city's strategic location facilitates connections to other European markets, making it a preferred choice for data center operators seeking energy-efficient solutions. Additionally, Frankfurt's proximity to the European energy grid enables data center facilities to integrate renewable energy sources like wind and solar, further supporting the city’s growth as a green data center hub
Berlin (22%)
Berlin ranks second in terms of market share, accounting for around 22% of the market. The capital city is experiencing rapid growth in the green data center sector due to its strong focus on sustainability, digital innovation, and supportive local government policies. Berlin is home to a diverse range of companies, including startups and large enterprises, which are increasingly adopting green data center solutions to meet their digital transformation goals. The availability of renewable energy sources and a favorable business climate are key factors driving the expansion of green data centers in Berlin.
Key players
- Equinix
- Digital Realty
- OVHcloud
- VIRTUS
- Data4
Competitive Analysi
The Germany Green Data Center Market is highly competitive, with leading players such as Equinix, Digital Realty, OVHcloud, VIRTUS, and Data4 vying for market share. Equinix, a global leader in data center services, stands out with its extensive portfolio of sustainable, energy-efficient data centers and strong focus on renewable energy integration. Digital Realty, another key player, focuses on energy-efficient infrastructure, offering a robust product portfolio tailored to large enterprises and SMEs. OVHcloud, known for its environmentally conscious approach, delivers cost-effective solutions powered by renewable energy sources. VIRTUS offers scalable green data center solutions, while Data4 is expanding rapidly in Germany with a commitment to sustainability and energy efficiency. Each player is actively investing in renewable technologies, enhancing their competitive advantage, and responding to the growing demand for sustainable infrastructure in the region.
Recent Developments
- In December 2023, Vertiv acquired CoolTera Ltd., a provider of liquid cooling infrastructure solutions. This acquisition strengthens Vertiv's capabilities in high-density compute cooling, aligning with the industry's shift towards energy-efficient data center technologies.
- In July 2024, Huawei unveiled three green data center facility solutions at the Global Smart Data Center Summit. These include the AeroTurbo fans, IceCube polymer heat exchangers, and iCooling AI energy efficiency cooling solutions, designed to optimize cooling efficiency and reduce energy consumption.
- In May 2024, Microsoft launched its first hyperscale cloud data center region in Mexico, located in Querétaro. This facility aims to provide scalable, highly available, and resilient cloud services, supporting digital transformation and sustainable innovation in the region.
- In June 2024, HPE partnered with Danfoss to introduce the HPE IT Sustainability Services – Data Center Heat Recovery. This turnkey heat recovery module helps organizations manage and repurpose excess heat, contributing to more sustainable IT infrastructures.
- In November 2024, Google announced a partnership with SB Energy Global to supply 942 MW of renewable energy to power its data center operations in Texas. This initiative supports Google's commitment to operate on carbon-free energy and aligns with its sustainability goals.
- In January 2025, AWS announced plans to invest approximately $11 billion in Georgia to expand its infrastructure, supporting cloud computing and AI technologies. This investment is expected to create at least 550 new high-skilled jobs and enhance the state's digital innovation capabilities.
- In May 2024, IBM announced a partnership with Schneider Electric to develop and deploy energy-efficient data center solutions, focusing on reducing carbon emissions and improving operational efficiency.
Market Concentration and Characteristics
The Germany Green Data Center Market exhibits a moderate to high concentration, with a few key players dominating the landscape, including Equinix, Digital Realty, and OVHcloud. These players lead in terms of market share, driven by their extensive infrastructure, strong focus on sustainability, and investment in renewable energy sources. While the market is concentrated in major urban centers like Frankfurt, Berlin, and Munich, it is also witnessing increasing competition from smaller regional players and emerging technologies, such as modular data centers. The market is characterized by a strong emphasis on energy efficiency, low carbon footprints, and the integration of renewable power sources. Additionally, government policies promoting sustainability, coupled with the demand from enterprises for green certifications and lower operational costs, are fueling the growth of green data centers, contributing to the evolving dynamics of the market
Report Coverage
The research report offers an in-depth analysis based on Component, Data Center Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for green data centers in Germany will continue to rise, driven by the increasing need for sustainable IT infrastructure and digital transformation initiatives across industries.
- Germany will see more widespread adoption of renewable energy sources in data centers, with a stronger emphasis on solar, wind, and local energy generation solutions.
- Government policies and incentives promoting energy efficiency and sustainability will further accelerate the growth of green data centers in the region, aligning with Germany’s climate-neutral targets by 2045.
- Advanced cooling technologies, such as liquid cooling and free-air cooling, will become more prevalent, significantly reducing the energy consumption of data centers in Germany.
- The market will witness increased deployment of modular, scalable green data centers that offer flexibility and energy efficiency, catering to both small and large enterprises.
- With the rise of edge computing, more decentralized green data centers will emerge across smaller cities and rural areas in Germany, reducing latency and enhancing performance for local users.
- Data center operators will increasingly leverage sustainability as a key differentiator, adopting green certifications and transparent environmental practices to attract environmentally conscious clients.
- Stricter energy efficiency standards will be enforced, requiring data centers to adopt cutting-edge technologies and practices that minimize energy consumption while maximizing performance.
- There will be greater collaboration between data center operators and telecom providers to optimize the energy efficiency of networks, contributing to the broader adoption of green infrastructure.
- While major cities like Frankfurt and Berlin will remain dominant, there will be growing interest and investment in green data centers in secondary regions, helping to decentralize infrastructure and distribute energy load more effectively.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Germany Green Data Center Market in 2023 and 2032?
What are the key drivers of growth in the Germany Green Data Center Market?
Who are the key players in the Germany Green Data Center Market?
How are renewable energy and advanced cooling technologies influencing the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Green Data Center Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Germany Green Data Center Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,880.94 million → 2032: USD 12,022.28 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Green Data Center Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Green Data Center Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Green Data Center Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Germany Green Data Center Drivers
- 3.3 Germany Green Data Center Restraints & Challenges
- 3.4 Germany Green Data Center Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Green Data Center Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Green Data Center Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Green Data Center category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Green Data Center Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Germany Green Data Center Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Germany Green Data Center in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Green Data Center Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Germany Green Data Center Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Germany Green Data Center Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Green Data Center (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Germany Green Data Center
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Germany Green Data Center – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Germany Green Data Center – Priority Domestic Market 1
Chapter 10. Germany Green Data Center – Priority Domestic Market 2
Chapter 11. Germany Green Data Center – Priority Domestic Market 3
Chapter 12. Germany Green Data Center – Priority Domestic Market 4
Chapter 13. Germany Green Data Center Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
