
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
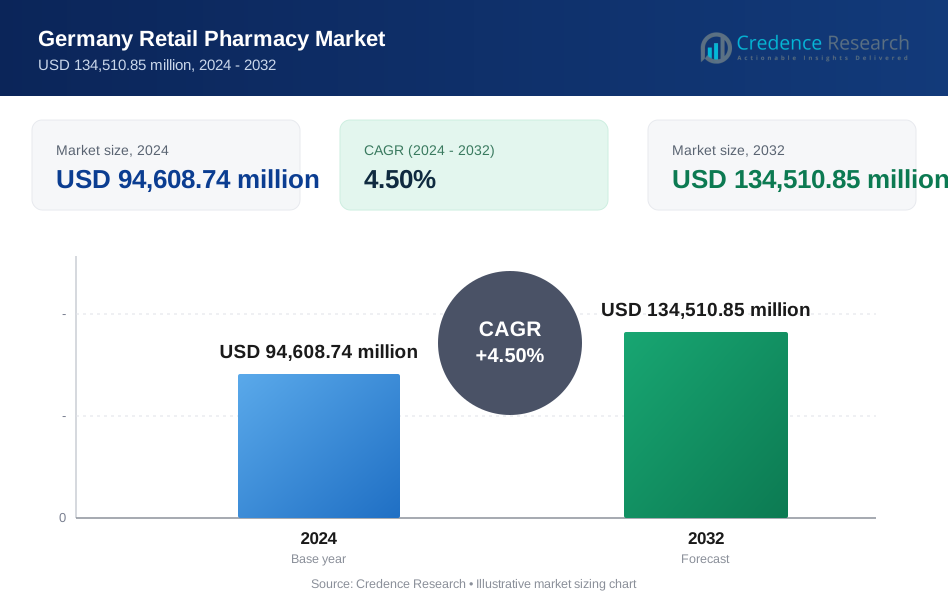
| Germany Retail Pharmacy Market Size 2024 | USD 94,608.74 million |
| Germany Retail Pharmacy Market, CAGR | 4.50% |
| Germany Retail Pharmacy Market Size 2032 | USD 134,510.85 million |
Market Overview
The Germany Retail Pharmacy Market is projected to grow from USD 94,608.74 million in 2024 to an estimated USD 134,510.85 million by 2032, with a compound annual growth rate (CAGR) of 4.50% from 2025 to 2032. This steady growth reflects the increasing demand for pharmaceutical products in the country, driven by factors such as an aging population and the rising incidence of chronic diseases.
Key drivers of the market include the growing prevalence of chronic conditions such as diabetes, hypertension, and respiratory diseases, which demand continuous medication and regular pharmacy visits. The shift toward self-medication and preventive healthcare is another prominent trend, with consumers increasingly seeking over-the-counter (OTC) products. Moreover, the rise of e-pharmacies and digital health services has transformed the traditional retail pharmacy model, making it more accessible and convenient for consumers.
Geographically, the retail pharmacy market in Germany is characterized by a strong presence of both local and international pharmacy chains. Major players include Walgreens Boots Alliance, Celesio, and DocMorris, who dominate the market with extensive networks of retail pharmacies and e-commerce platforms. These companies continue to expand their reach through mergers, acquisitions, and partnerships, ensuring their leadership in the evolving pharmacy landscape.
Market Insights
- The Germany Retail Pharmacy Market is projected to grow from USD 94,608.74 million in 2024 to USD 134,510.85 million by 2032, with a CAGR of 4.50% from 2025 to 2032, driven by increasing demand for pharmaceutical products.
- The Global Retail Pharmacy Market is expected to grow from USD 14,45,920.00 million in 2024 to USD 19,65,958.05 million by 2032, at a CAGR of 3.92% from 2025 to 2032.
- Growing prevalence of chronic diseases like diabetes and hypertension, the aging population, and rising demand for over-the-counter (OTC) products are significant factors driving the market growth.
- The integration of digital services, including e-pharmacies and online prescription services, has transformed the retail pharmacy landscape, making healthcare more accessible and convenient for consumers.
- An increasing shift towards self-medication and preventive healthcare is influencing consumer purchasing behavior, leading to higher demand for OTC drugs and health-related products.
- Regulatory challenges, such as strict pricing policies and compliance requirements for both physical and online pharmacies, can limit profit margins and slow market growth.
- Western Germany holds the largest market share, followed by Southern and Northern Germany, where urban areas drive demand for pharmaceuticals, and rural regions benefit from online and mail-order pharmacy services.
- Major players like Rossmann, Dm-drogerie, Müller, and DocMorris dominate the market, with increasing consolidation and the rise of digital pharmacy services contributing to a highly competitive environment.
Report Scope
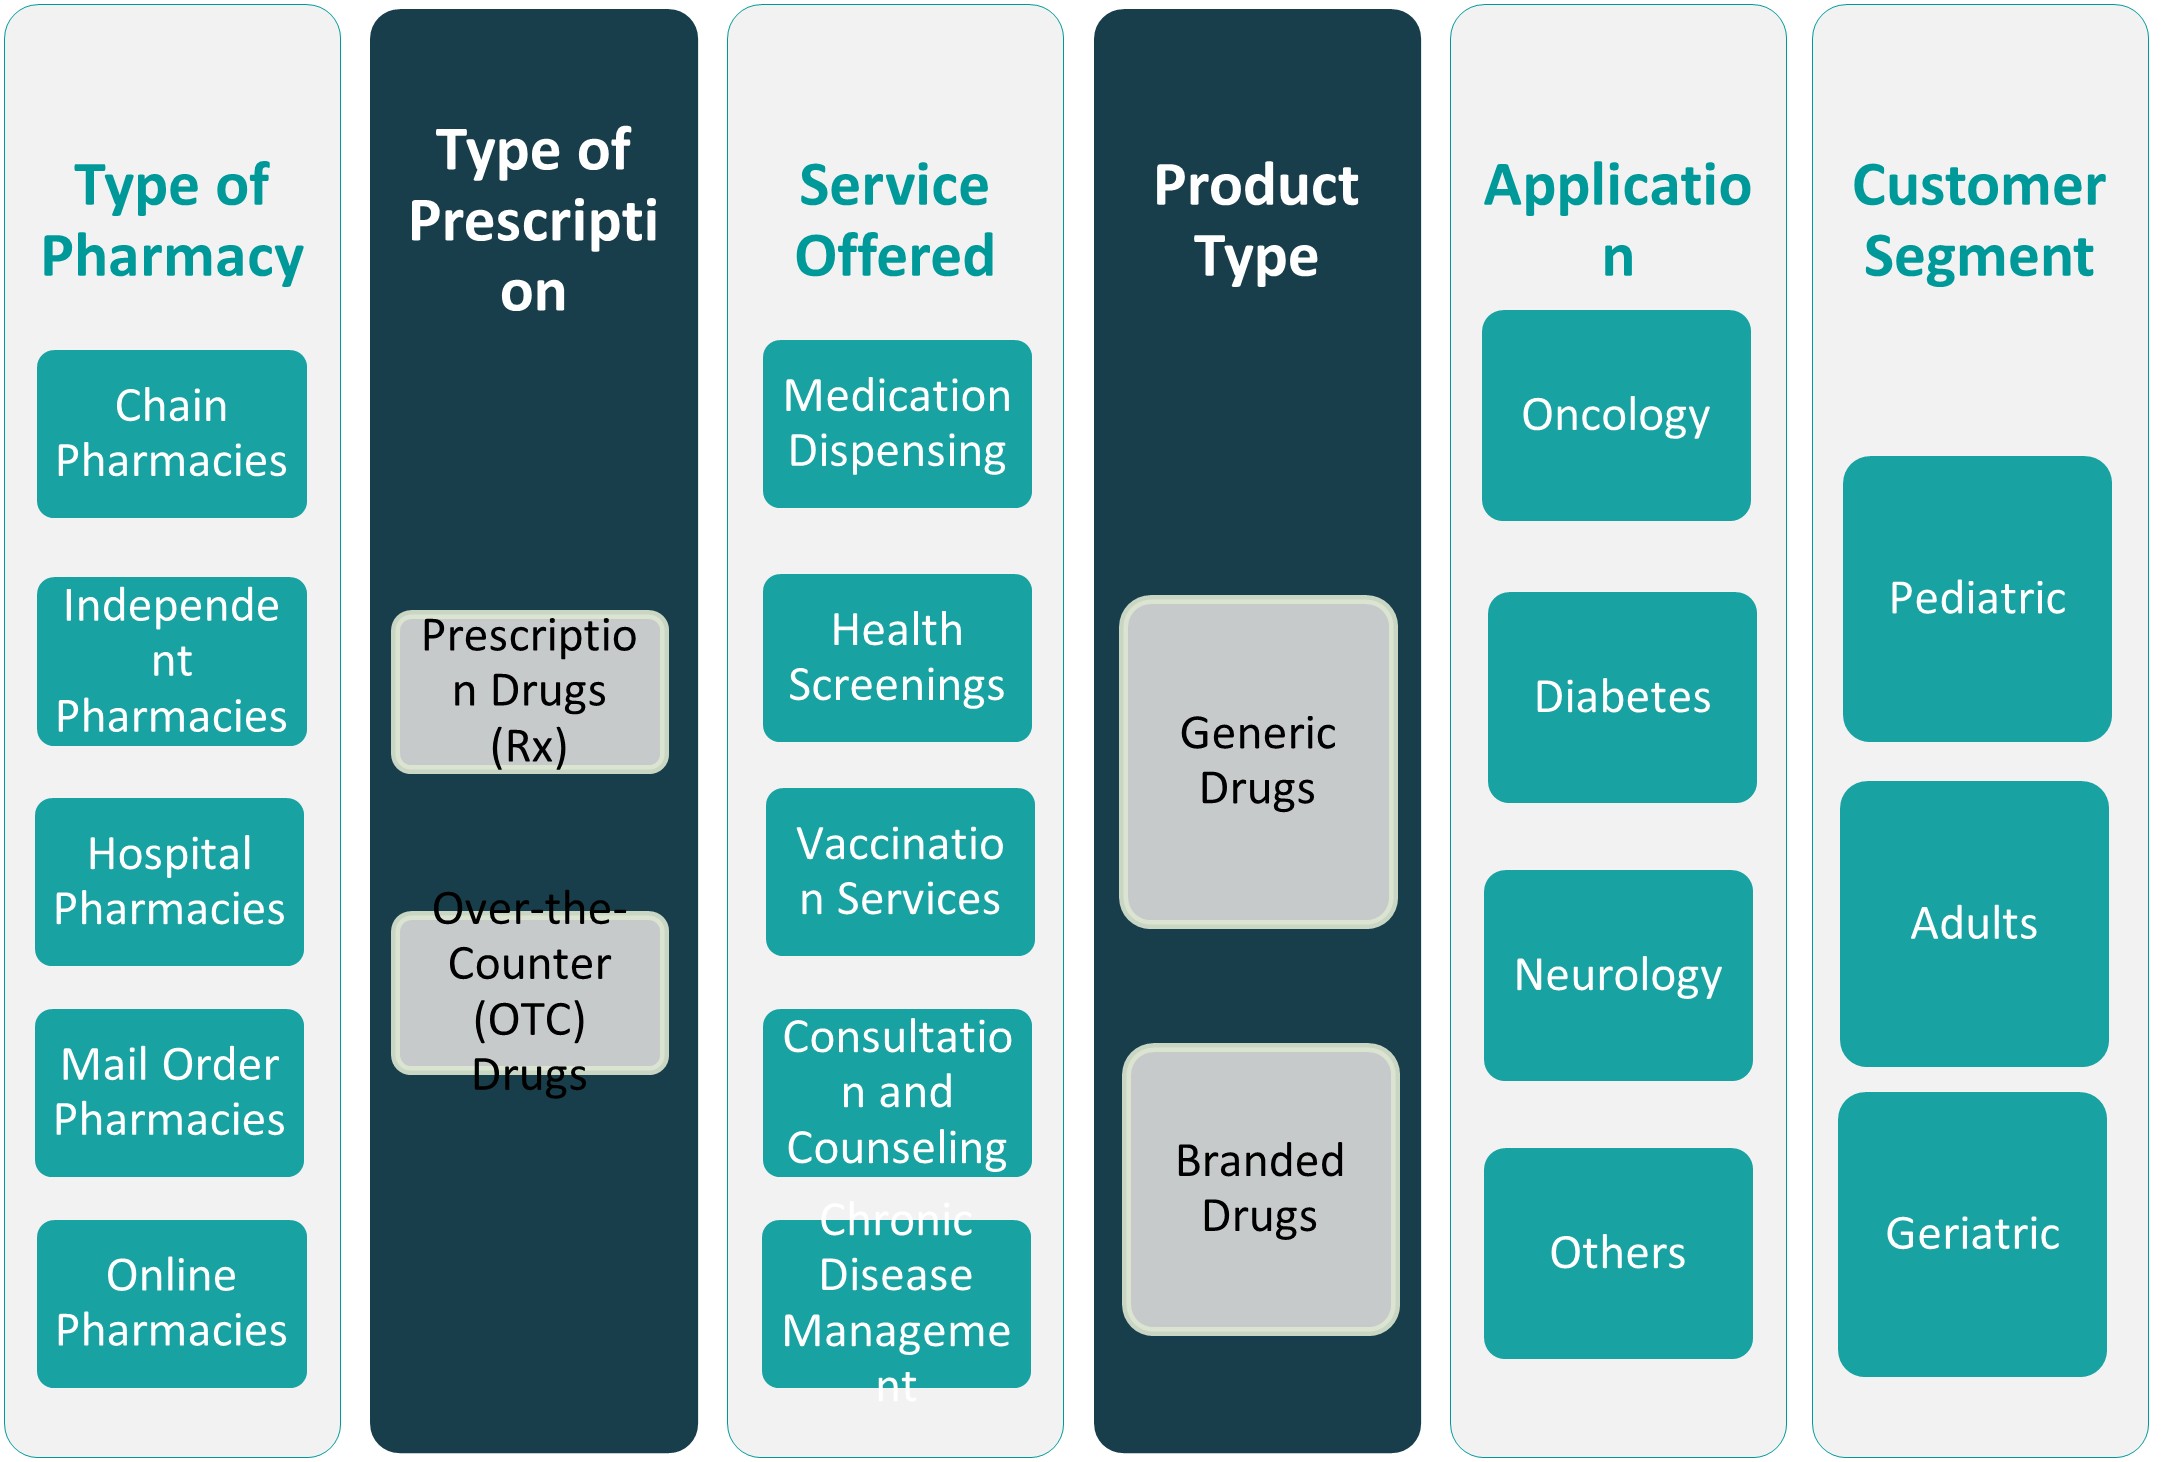
This report segments the Germany Retail Pharmacy Market as follows:
Market Drivers
Technological Advancements and Digitalization in Pharmacies
Germany’s retail pharmacies are accelerating digital transformation across front- and back-end operations, adopting online ordering, home delivery, telepharmacy and automated dispensing to meet changing consumer expectations and to offset pressures on physical stores; this shift is occurring within a network of roughly 17,571 community pharmacy locations reported at year-end 2023, which gives incumbents scale to roll out digital services nationally and to integrate electronic medication plans and pre-ordering tools without losing local presence, while a survey of German pharmacies found that 88.1 percent of respondents already offered five or more digital services such as website pre ordering, phone pre-orders and email contact evidence that digital is now mainstream rather than experimental in pharmacies and ABDA reports that about 150 active online pharmacies operate in Germany, signaling meaningful channel diversification that has expanded convenience for patients and created new revenue and adherence opportunities for operators as they combine automation with teleconsultations and logistics partnerships to deliver medications faster and reduce in-store congestion.
Self-medication and Preventive Healthcare Trends
German consumers’ increasing focus on self-care and prevention has driven pharmacies to expand OTC assortments, nutritional supplements and advisory services while leveraging their dense national footprint to provide accessible prevention interventions, a strategy supported by the structure of the market where roughly 21 pharmacies exist per 100,000 inhabitants and about 17,571 licensed outlets provide local reach and credibility for wellness offerings; ABDA data show the pharmacy network’s reach across urban and rural regions, enabling pharmacies to scale vaccination programs, screening initiatives and smoking cessation schemes that improve early detection and reduce downstream costs, and industry analyses note that many pharmacies now combine digital touchpoints with shelf assortments online OTC catalogs, mobile reminders and click and collect to capture a larger share of preventive spend as consumers prefer one-stop convenience and trusted counselling for minor ailments and supplements, turning pharmacies into frontline wellness centres that drive higher foot traffic and basket values and position them as cost effective alternatives to outpatient clinics for routine, preventive care.
Increasing Prevalence of Chronic Diseases
The growing chronic disease burden in Germany is a major demand driver for retail pharmacies, which serve as primary access points for long term medication, adherence support and home care supplies, a reality reflected in national and international health reporting that identifies Germany among OECD countries with high chronic disease prevalence and substantial diabetes burden official analyses project millions living with diabetes and related long term care needs while Germany’s extensive pharmacy network ensures ongoing points of contact for chronic patients who require repeat dispensing and management; for example, international and peer reviewed projections estimate several million people in Germany with diagnosed diabetes and rising numbers over coming decades, a patient base that generates recurring prescription volumes and drives pharmacy services such as medication reviews, dosage counselling and chronic care monitoring, enabling pharmacies to capture repeat revenues and deepen clinical relationships as they support disease management at home and help reduce hospital admissions through better adherence and early intervention, aligning community pharmacy roles with national goals for chronic care delivery and resource efficient outpatient management.
Aging Population and Geriatric Healthcare Needs
Germany’s demographic profile with the share of the population aged 65 and over reaching roughly 22 to 23 percent in recent reporting creates pronounced demand for pharmacy services tailored to older adults, including medication management, home delivery, assisted use packaging and specialised counseling for polypharmacy and comorbidity, and this demographic pressure amplifies the role of community pharmacies as accessible points of continuity for geriatric care; public statistics and demographic datasets confirm the rapid expansion of the 65+ cohort and the consequent rise in age related chronic conditions and long term care needs, so pharmacies are evolving their service models introducing medication reviews, home visit logistics and stronger ties with primary care and care managers to reduce medication errors and support safe therapy in the community, while their proximity to patients and frequent contact create opportunities to proactively manage adherence, prevent avoidable hospitalisations and provide value to payers and families who prioritize reliable, local support for older adults navigating complex treatment regimens.
Market Trends
Integration of Technology and Digital Health Services
Technology is transforming the retail pharmacy landscape in Germany, with digital health services becoming a key trend. Retail pharmacies are increasingly adopting technology to enhance customer experience and improve operational efficiency. Many pharmacies now offer telehealth services, allowing customers to consult pharmacists or healthcare providers virtually. This service has gained significant traction, especially during the pandemic, and is expected to continue growing as part of the broader trend toward digital healthcare.
Pharmacies are also incorporating mobile apps and digital platforms to help consumers track medication schedules, receive reminders, and access health information. Additionally, the use of automated dispensing systems, smart shelves, and self-service kiosks is improving pharmacy operations, reducing wait times, and increasing customer satisfaction. By integrating these technological advancements, pharmacies are positioning themselves as key players in the broader digital health ecosystem. This trend enhances accessibility to healthcare services and contributes to the ongoing shift from traditional in-person visits to more flexible, technology-driven pharmacy solutions.
Personalized Medicine and Health Consultations
Personalized medicine and tailored health consultations are gaining importance in the German retail pharmacy market. With advances in pharmacogenomics and a greater understanding of individual health needs, pharmacies are increasingly offering personalized services, such as customized medication regimens and health consultations. Consumers are seeking more personalized healthcare experiences, and pharmacies are stepping up to meet these demands by providing individualized advice on managing chronic conditions, preventing illnesses, and optimizing medication usage.
Pharmacists are playing an essential role in guiding patients through their medication therapies, ensuring that drugs are taken in the most effective manner. This trend is particularly relevant for individuals with complex health conditions who require more attention to detail regarding medication management. Additionally, many pharmacies are implementing data-driven solutions that enable them to offer personalized wellness recommendations and preventative care strategies based on customer health profiles. By offering personalized consultations and medication reviews, pharmacies are fostering stronger relationships with customers, enhancing satisfaction, and boosting sales in this segment. This trend aligns with the growing desire for holistic, patient-centered care.
Rise of E-Pharmacies and Online Sales
The increasing popularity of e-pharmacies is a prominent trend in the Germany retail pharmacy market. With consumers seeking convenience, online pharmacies offer a wide range of prescription and over-the-counter (OTC) products, delivered directly to their doorstep. This trend has been further accelerated by the COVID-19 pandemic, which highlighted the importance of online services in maintaining access to essential medications. For instance, during the pandemic, Germany witnessed a 25% increase in online pharmacy transactions, reflecting the growing consumer preference for digital healthcare solutions.
E-pharmacies not only offer convenience but also enable consumers to compare prices and access various health products more easily than traditional brick-and-mortar stores. As regulatory bodies like the Federal Institute for Drugs and Medical Devices (BfArM) streamline online pharmacy regulations, e-pharmacies are expanding their reach, contributing to the growing share of online pharmacy sales in Germany. Major players in the market are leading the way, offering innovative delivery solutions, personalized health advice, and discounts to attract consumers. The trend is expected to continue growing, supported by advancements in digital technologies and shifting consumer preferences toward contactless healthcare.
Increasing Focus on Health and Wellness Products
There is a noticeable shift towards health and wellness products in the German retail pharmacy market. Consumers are becoming more health-conscious and increasingly preferring preventive healthcare options, which is reflected in the growing demand for dietary supplements, vitamins, and natural health products. For example, nearly 70% of German consumers actively seek products that support immunity and stress management, showcasing the heightened awareness of maintaining a healthy lifestyle. This shift is also driven by a heightened awareness of maintaining a healthy lifestyle, which gained traction during the pandemic.
As a result, retail pharmacies are expanding their range of wellness products to meet consumer demand for products that support immunity, stress management, and overall well-being. Pharmacies are also focusing on offering organic, sustainable, and eco-friendly options, in response to rising consumer interest in sustainability. This growing trend is shaping pharmacy offerings, with a stronger emphasis on promoting health beyond traditional medications. Additionally, the integration of wellness advice and consultations into pharmacy services, such as personalized nutrition guidance and stress management tips, is further fueling this trend. Retail pharmacies that embrace this wellness-oriented approach are seeing increased consumer loyalty and improved sales growth in this segment.
Market Challenges
Stringent Regulatory Environment and Compliance Challenges
The retail pharmacy market in Germany faces significant challenges related to regulatory compliance, which can impact overall market dynamics. The pharmaceutical sector in Germany is tightly regulated by national authorities such as the Federal Institute for Drugs and Medical Devices (BfArM) and European Union directives. Retail pharmacies must adhere to stringent rules regarding the sale of prescription and over-the-counter (OTC) medications, pricing regulations, and the licensing of online pharmacies. For instance, the Arzneimittelpreisverordnung (AMPreisV) regulates the pricing of prescription drugs, capping profit margins for pharmacies to ensure affordability for consumers.
This regulation has led to operational complexities and high compliance costs for pharmacy businesses. One of the biggest challenges retailers face is navigating the pricing and reimbursement systems. For instance, the German Act on Digitalization in Healthcare (DVG) mandates the adoption of electronic prescriptions and digital platforms, requiring pharmacies to invest in new technologies and employee training. Online pharmacies, in particular, encounter additional hurdles such as cross-border regulatory compliance and adherence to both national and EU laws. These challenges necessitate significant investment in legal compliance and technology, which can burden smaller pharmacy businesses and hinder their growth.
Intense Competition and Margin Pressure
The retail pharmacy market in Germany is characterized by intense competition, which puts significant pressure on profit margins. There are numerous players in the market, ranging from large pharmacy chains like DocMorris and Celesio (operating under the McKesson brand) to independent pharmacies. This competition, coupled with the regulatory constraints on pricing, has led to a situation where pharmacies struggle to maintain profitability. With the rise of e-pharmacies and digital platforms, traditional brick-and-mortar pharmacies face the added challenge of competing with online retailers that often offer lower prices and the convenience of home delivery. The emergence of online pharmacies has intensified price competition, especially for OTC products, where price sensitivity among consumers is high.
Furthermore, the shift toward preventive care and self-medication has altered purchasing patterns, with consumers often opting for online options where they can compare prices easily. Pharmacies also face the pressure of offering value-added services such as personalized consultations, health screenings, and medication therapy management to differentiate themselves from their competitors. However, providing these services incurs additional operational costs that can erode profit margins. To remain competitive, pharmacies must continually invest in technology, customer service, and innovative business models, which can strain resources, especially for smaller or independent pharmacies. This competitive landscape and the constant need for differentiation are key challenges faced by the retail pharmacy market in Germany.
Market Opportunities
Expansion of Digital and Online Pharmacy Services
One of the most significant opportunities in the Germany retail pharmacy market lies in the expansion of digital and online pharmacy services. The growing shift towards e-pharmacies presents a lucrative avenue for retailers to capture a broader customer base, particularly among consumers who prefer the convenience of ordering medications and health products from home. The regulatory environment in Germany is gradually adapting to accommodate digital prescriptions, with the introduction of electronic prescriptions (e-prescriptions) paving the way for more seamless online transactions.
Pharmacies can capitalize on this by enhancing their digital platforms, offering home delivery services, and creating personalized health management tools through mobile apps. The rise in telemedicine and online consultations further supports this trend, as consumers increasingly seek virtual healthcare services. By adopting e-commerce solutions and expanding their digital presence, pharmacies can increase accessibility, reduce overhead costs, and tap into a growing segment of tech-savvy consumers looking for convenience and reliability in their healthcare services.
Growth in Preventive Healthcare and Wellness Products
Another promising opportunity for the Germany retail pharmacy market lies in the growing demand for preventive healthcare and wellness products. As consumers become more health-conscious and aware of the benefits of maintaining a healthy lifestyle, the market for vitamins, supplements, and natural health products is expanding. Retail pharmacies can leverage this trend by diversifying their product offerings to include a wide range of health and wellness products, particularly those focused on immunity, stress relief, and overall well-being. Additionally, pharmacies can provide value-added services such as personalized consultations, health screenings, and wellness advice, establishing themselves as key players in the broader health and wellness ecosystem. This focus on preventive care not only meets consumer demand but also enhances customer loyalty, creating a sustainable growth opportunity for pharmacies looking to differentiate themselves in a competitive market.
Market Segmentation Analysis
By Type of Pharmacy
The Germany retail pharmacy market is segmented by the type of pharmacy, which includes chain pharmacies, independent pharmacies, hospital pharmacies, mail-order pharmacies, and online pharmacies. Chain pharmacies are dominant in the market, with large players such as DocMorris and Celesio leading the way due to their extensive network and ability to offer competitive pricing. These pharmacies benefit from economies of scale and a wide reach across urban and rural areas. Independent pharmacies, on the other hand, provide a more personalized customer experience but face challenges due to competition from chain pharmacies and digital platforms.
Hospital pharmacies primarily cater to patients within medical institutions and are integral to the healthcare system. They often handle specialized medications and serve as a critical part of hospital services. Mail-order pharmacies are gaining traction, particularly with the growing demand for convenience and home delivery services, allowing consumers to order medications online. Online pharmacies have seen rapid growth, especially during the COVID-19 pandemic, as more consumers seek contactless healthcare options, making it a promising segment for future growth.
By Type of Prescription
The market is further segmented by the type of prescription, including prescription drugs (Rx) and over-the-counter (OTC) drugs. Prescription drugs account for a significant portion of retail pharmacy sales in Germany, driven by the increasing prevalence of chronic diseases such as diabetes, hypertension, and cardiovascular conditions. However, the OTC drugs segment has witnessed considerable growth, fueled by a rising trend in self-medication, with consumers opting for non-prescription products for minor ailments and preventive healthcare. Pharmacies are increasingly focusing on expanding their OTC product offerings, which range from pain relievers to dietary supplements, in response to consumer demand for convenience and cost-effective solutions.
Segments
Based on Type of Pharmacy
- Chain Pharmacies
- Independent Pharmacies
- Hospital Pharmacies
- Mail Order Pharmacies
- Online Pharmacies
Based on Type of prescription
- Prescription Drugs (Rx)
- Over-the-Counter (OTC) Drugs
Based on Service offered
- Medication Dispensing
- Health Screenings
- Vaccination Services
- Consultation and Counseling
- Chronic Disease Management
Based on Product Type
- Generic Drugs
- Branded Drugs
Based on Application
- Oncology
- Diabetes
- Neurology
- Others
Based on Customer
- Paediatric
- Adults
- Geriatric
Based on Region
- Western Germany
- Southern Germany
- Northern Germany
- Eastern Germany
Regional Analysis
Western Germany (40%)
Western Germany is one of the largest contributors to the retail pharmacy market, holding an estimated market share of around 40%. The region, which includes cities like Cologne, Düsseldorf, and Frankfurt, is a major hub for healthcare services, with a high concentration of both chain and independent pharmacies. Western Germany's well-developed infrastructure and high population density support a steady demand for prescription medications, over-the-counter products, and healthcare services. In this region, the growing trend of e-pharmacies is especially noticeable, as urban consumers seek the convenience of online ordering and home delivery. Additionally, the prevalence of chronic diseases in this region fuels demand for pharmacy services, especially for diabetes, hypertension, and heart disease management.
Southern Germany (30%)
Southern Germany, which includes the states of Bavaria and Baden-Württemberg, contributes approximately 30% to the retail pharmacy market. This region is known for its strong healthcare system and higher-than-average aging population, leading to a significant rise in demand for medications related to geriatric health. The demand for chronic disease management services, personalized health consultations, and specialized pharmaceutical products is increasing. Large cities like Munich and Stuttgart play a pivotal role in shaping the retail pharmacy landscape, with both independent pharmacies and e-pharmacies expanding their reach to cater to the region’s tech-savvy and health-conscious population.
Key players
- Rossmann
- Dm-drogerie
- Müller
- Schlecker
- DocMorris
- QVC
Competitive Analysis
The Germany retail pharmacy market is highly competitive, with several major players dominating the landscape. Rossmann and Dm-drogerie are two of the largest pharmacy chains, known for their extensive networks across the country. They offer a broad range of products, from medications to health and beauty items, and have integrated online platforms to cater to the growing demand for e-commerce. Müller and Schlecker, while smaller in comparison, maintain strong footholds with a loyal customer base due to their broad store presence and competitive pricing strategies. DocMorris, a prominent player in the online pharmacy segment, has capitalized on the growing trend of digital pharmacies and home delivery services, significantly expanding its market share in recent years. QVC offers a unique mix of retail products, including health-related items, and leverages its robust direct-to-consumer TV and online sales model. These companies are constantly innovating and adapting to changing consumer preferences, ensuring fierce competition in the market.
Recent Developments
- In December 2025, dm-drogerie markt launched its mail-order pharmacy dm-med in Germany, allowing customers to order non-prescription pharmacy-only medicines, pharmacy-exclusive supplements, vitamins, and dermocosmetics through dm’s online shop and app.
- In February 2026, Germany’s Wettbewerbszentrale filed a lawsuit against dm-drogerie markt over the dm-med online pharmacy model, arguing that the offering may blur the legal separation between drugstore retail and pharmacy-only medicines.
- In February 2026, DocMorris expanded its AI-first strategy by advancing its AI health companion with Infermedica, integrating symptom checks, telemedicine, pharmacy access, and other digital health services into a single app-based patient journey.
- In March 2026, Redcare Pharmacy, the parent of Shop Apotheke, nominated Anja Hendel, Max Müller, and Peter Schmid von Linstow to its Supervisory Board, positioning the company for stronger governance and strategic oversight in its online pharmacy business.
- In April 2026, Redcare Pharmacy became the first pharmacy to use a new TI access technology for Germany’s e-prescription infrastructure, aiming to speed up e-prescription processing and reduce waiting times for Shop Apotheke customers.
- In May 2026, Redcare Pharmacy simplified its group structure by merging Europa Apotheek Venlo B.V. into Shop-Apotheke B.V. and Europa Apotheek Service Venlo B.V. into Shop-Apotheke Service B.V., effective January 1, 2026, consolidating its German prescription-focused online pharmacy operations.
Market Concentration and Characteristics
The Germany retail pharmacy market exhibits moderate concentration, with several large players dominating the sector, alongside a significant number of smaller independent pharmacies. Major chains like Rossmann, Dm-drogerie, and Müller hold a considerable share of the market, leveraging their extensive store networks, competitive pricing strategies, and robust e-commerce platforms to reach a wide consumer base. In addition to these dominant players, DocMorris stands out in the online pharmacy segment, benefiting from the growing demand for digital pharmacy services and home delivery. Despite the strong presence of large chains, independent pharmacies continue to play a crucial role, particularly in rural areas, where they offer personalized services and cater to specific customer needs. The market is also characterized by increasing consolidation, with independent pharmacies often being acquired by larger chains or collaborating with digital platforms. As consumer preferences shift towards convenience and digital solutions, the market is gradually transitioning towards a more tech-driven and service-oriented landscape.
Report Coverage
The research report offers an in-depth analysis based on Type of Pharmacy, Type of prescription, Service offered, Product Type, Application, Customer and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for e-pharmacies will continue to rise as consumers increasingly prioritize convenience, with online platforms offering home delivery and digital prescriptions becoming more mainstream.
- Retail pharmacies will see continued growth in the health and wellness segment, as consumers focus on preventive care, vitamins, and dietary supplements to maintain overall well-being.
- Pharmacies will increasingly adopt digital health services such as telehealth consultations, medication management apps, and electronic prescriptions, enhancing customer convenience and care.
- With Germany’s aging population, there will be a sustained demand for pharmacy services tailored to older adults, such as chronic disease management, medication reviews, and personalized consultations.
- The shift towards online prescriptions will accelerate, driven by technological advancements and regulatory changes, allowing pharmacies to provide a seamless experience for consumers.
- Pharmacies will expand their offerings in preventive healthcare, including health screenings, vaccination services, and wellness advice, becoming key players in promoting early detection and health maintenance.
- Price competition will intensify, particularly between chain pharmacies and online platforms, as consumers continue to seek cost-effective solutions for their healthcare needs.
- Pharmacies will invest in automation and AI-driven solutions to streamline operations, improve service delivery, and reduce waiting times, enhancing customer satisfaction.
- Independent pharmacies will continue to thrive, particularly in rural areas, where they offer personalized service, health consultations, and build trust with local communities.
- The adoption of sustainable practices, such as eco-friendly packaging and energy-efficient operations, will grow as both consumers and pharmacies emphasize environmental responsibility in the healthcare industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Germany Retail Pharmacy Market in 2024 and 2032?
What is the compound annual growth rate (CAGR) of the Germany Retail Pharmacy Market?
What are the key drivers of the Germany Retail Pharmacy Market?
Who are the major players in the Germany Retail Pharmacy Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Retail Pharmacy Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Retail Pharmacy Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 94,608.74 million → 2032: USD 134,510.85 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Retail Pharmacy Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Retail Pharmacy Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Retail Pharmacy Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Retail Pharmacy Market Drivers
- 3.3 Germany Retail Pharmacy Market Restraints & Challenges
- 3.4 Germany Retail Pharmacy Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Retail Pharmacy Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Retail Pharmacy Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Retail Pharmacy category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Retail Pharmacy Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Retail Pharmacy Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Retail Pharmacy market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Retail Pharmacy Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Retail Pharmacy Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Retail Pharmacy Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Retail Pharmacy (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Retail Pharmacy Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Retail Pharmacy Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Retail Pharmacy Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Retail Pharmacy Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Retail Pharmacy Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Retail Pharmacy Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Retail Pharmacy Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Retail Pharmacy Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Retail Pharmacy Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
