
Market Overview
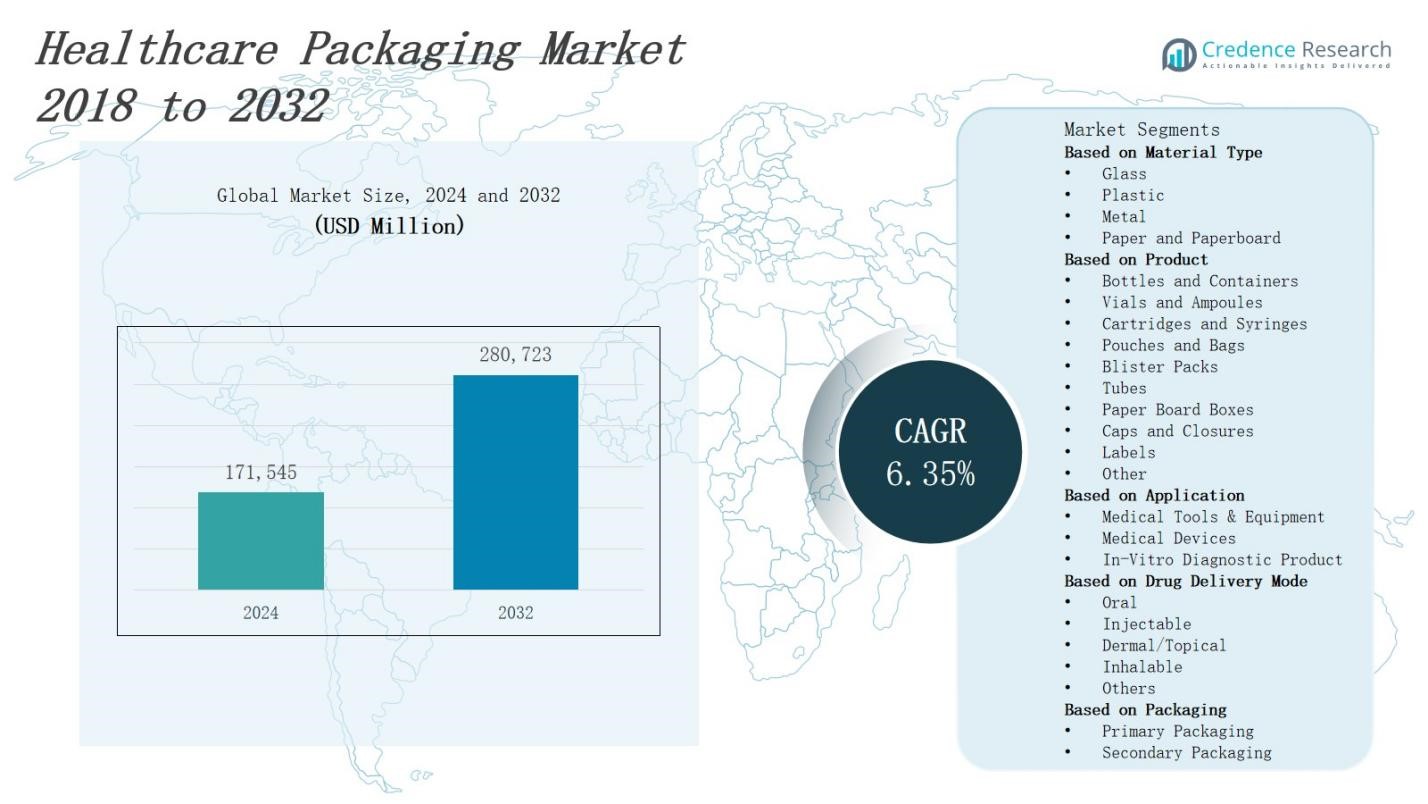
The healthcare packaging market is projected to grow from USD 171,545 million in 2024 to USD 280,723 million by 2032 at a compound annual growth rate of 6.35%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Healthcare Packaging Market Size 2024 | USD 171,545 Million |
| Healthcare Packaging Market, CAGR | 6.35% |
| Healthcare Packaging Market Size 2032 | USD 280,723 Million |
The healthcare packaging market benefits from strict regulatory requirements and growing demand for product safety. Manufacturers develop advanced sterilization‑compatible materials and tamper‑evident designs to meet FDA and EU standards. Rising patient awareness drives adoption of antimicrobial coatings and temperature‑monitoring labels. Sustainability initiatives prompt investment in recyclable and bio‑based substrates that reduce environmental impact. The expansion of pharmaceutical e‑commerce channels increases demand for durable, leak‑proof formats. Technological innovations such as serialization and RFID tracking enhance supply chain traceability. Automation and digital printing streamline production and support personalized labeling. Combined, these trends and drivers significantly propel market growth at a steady pace.
The healthcare packaging market spans North America, Europe, Asia Pacific, Latin America and Middle East & Africa, each region display dynamics. North America commands leadership with robust production and logistics. Europe emphasizes sustainability and regulatory compliance. Asia Pacific offers volume growth in China and India. Latin America benefits from growth in pharma sectors in Brazil and Mexico. Middle East & Africa posts demand in GCC and South Africa. Leading firms such as Amcor plc, Berry Global Inc., Huhtamäki Oyj, 3M Company and Sonoco Products Company shape competition through innovative solutions.
Market Insights
- The market will expand from USD 171,545 million in 2024 to USD 280,723 million by 2032 at a 6.35% CAGR.
- It faces stringent FDA, EMA and ISO standards that drive adoption of high‑barrier polymers, multilayer films and tamper‑evident closures.
- Serialization, RFID tracking and temperature‑sensitive labels enhance traceability and protect biologics across the supply chain.
- Recyclable plastics, bio‑based substrates and lightweight designs reduce environmental impact and support corporate sustainability goals.
- Digital printing and automated inspection accelerate SKU changeovers, ensure label accuracy and boost production throughput.
- Asia Pacific commands 37% market share, North America holds 28%, Europe 24%, Latin America 7% and Middle East & Africa 4%.
- Amcor plc, Berry Global Inc., Huhtamäki Oyj, 3M Company and Sonoco Products Company lead competition through innovation and green credentials.
Market Drivers
Stringent Standards Drive Material Development
The healthcare packaging market faces rigorous FDA, EMA and ISO requirements that mandate sterilization compatibility and barrier performance. It compels manufacturers to adopt high‑performance polymers and multilayer films. Producers test materials for extractables and leachables. They validate designs for medical devices and injectable drugs. Regulatory audits push innovation in tamper‑evident closures and peelable seals. Companies invest in quality systems to ensure compliance. This regulatory environment propels market expansion.
Patient Safety and Traceability Enhance Solutions
The healthcare packaging market emphasizes patient safety and supply chain transparency. It drives adoption of serialization and RFID tracking across primary and secondary packaging. Stakeholders require unique identification on vials and blister packs. Manufacturers integrate temperature‑sensitive labels to protect biologics. Companies implement anti‑counterfeit features to guard against diversion. It stimulates collaboration between packaging converters and biotech firms. This focus on traceability reinforces trust and propels market demand.
For instance, Schreiner MediPharm integrates RFID tags directly during manufacturing of pharmaceutical products, enabling hospitals to automate inventory management and monitor medication stock and expiration dates with 100% transparency.
Sustainability Initiatives Drive Material Selection
The healthcare packaging market adopts eco‑friendly substrates to meet environmental targets. It encourages use of recyclable plastics and bio‑based polymers. Manufacturers transition to lightweight designs that lower carbon footprint during transport. Companies develop compostable pouches for single‑use devices. Stakeholders partner with resin suppliers to secure certified sustainable materials. It reduces waste across clinical and retail channels. This shift toward green packaging enhances brand reputation and supports long‑term growth.
For instance, SÜDPACK Medica developed PharmaGuard®, a polypropylene (PP)-based recyclable blister packaging that aligns with sustainability standards, reduces eco-footprint, and can be processed on existing blister lines without compromising quality or product protection.
Digital Print and Automation Enhance Efficiency
The healthcare packaging market leverages digital print for customized labeling that meets patient‑specific needs. It integrates automated inspection systems to detect defects and ensure quality. Manufacturers deploy robotic assembly for consistent seal integrity on syringes and vials. Companies implement machine vision to verify label accuracy and lot codes. It streamlines changeover between SKUs and reduces downtime. Automation lowers labor costs and accelerates production throughput. This technological drive boosts market efficiency and competitiveness.
Market Trends
Smart Packaging Enhances Product Integrity
The healthcare packaging market leverages smart labels with embedded sensors that verify temperature and humidity. It supports real‑time quality checks for temperature‑sensitive therapeutics. Manufacturers equip vials and cartridges with NFC tags that grant instant authentication. Developers integrate QR codes to deliver patient guidance and dosage instructions. Converters install cloud platforms to monitor distribution data. Providers expand remote diagnostics by linking sensors to healthcare networks. This trend secures product integrity.
For instance, Pfizer incorporates NFC tags on packaging to authenticate products instantly and enhances patient engagement through digital interaction, securing supply chain integrity and reducing counterfeit risks.
Personalization and Patient‑Centric Designs Rise
The healthcare packaging market sees growth in patient‑centric formats that improve dosing accuracy and ease of use. It drives companies to offer personalized blister packs and pre‑filled syringes. Manufacturers tailor ergonomic shapes and color schemes to enhance patient adherence. Converters employ variable data printing to encode individual instructions. Providers test user feedback to optimize cap designs and clear instructions. This shift reduces medication errors and improves patient outcomes.
For instance, Dr Ferrer BioPharma introduced an award-winning nasal spray packaging that enhances patient comfort and compliance through user-friendly design features tested in patient feedback sessions.
Eco‑Conscious Materials Gain Momentum
The healthcare packaging market adopts recyclable polymers and bio‑based substrates to cut waste. It prompts partnerships with resin suppliers that hold sustainability certifications. Manufacturers replace single‑use plastics with compostable films for device packaging. Converters redesign cartons to use minimal materials without compromising protection. Providers implement return programs for reusable containers. This strategy supports corporate responsibility and aligns with global environmental targets. It reduces landfill impact and enhances brand credibility.
Digital Transformation Streamlines Production
The healthcare packaging market integrates robotics and AI‑driven inspection to boost output quality. It installs automated seal verification on pouch and bottle lines. Manufacturers use digital printing systems to apply dynamic labels and batch codes in real time. Converters adopt vision systems that validate every package before shipment. Providers monitor performance metrics through cloud dashboards. This digital makeover reduces manual errors and speeds delivery. It improves compliance with stringent labeling regulations.
Market Challenges Analysis
Complex Regulatory Landscape Strains Innovation
The healthcare packaging market faces a rigorous regulatory environment that demands thorough validation and documentation. It compels manufacturers to allocate resources for compliance audits and quality management systems. Regulators enforce strict criteria for material safety, sterilization compatibility and label accuracy. It extends development timelines and raises barriers for new product launches. Companies engage with notified bodies and certification agencies to secure approvals. It challenges smaller converters that lack comprehensive compliance frameworks. These requirements slow time to market and inflate R&D expenditures.
Rising Raw Material Costs and Supply Volatility
The healthcare packaging market grapples with volatile raw material prices that challenge packaging converters. Demand spikes for specialty polymers lead suppliers to raise resin costs. It affects profit margins for both primary and secondary packaging providers. Global supply chain disruptions hinder timely delivery of essential components. Companies face inventory shortages and scramble to qualify alternative sources. It forces stakeholders to adjust production schedules and negotiate longer lead times. These cost pressures reduce flexibility for innovation and strain operational budgets.
Market Opportunities
Growth in Biologics and Personalized Therapy Fuels Demand
The healthcare packaging market benefits from the rise of biologics and personalized therapies that require specialized containment and delivery formats. Increased use of single‑dose autoinjectors and prefilled syringes demands novel barrier films and advanced closure systems. It opens opportunities for converters to supply high‑barrier laminates and puncture‑resistant pouches. Manufacturers that offer compatibility with cold chain protocols gain competitive advantage in biologic drug distribution. Pharmaceutical companies seek packaging partners that can validate sterile barrier performance under strict protocols. This alignment of material science with therapy trends drives adoption of next‑generation packaging solutions. Stakeholders that invest in collaborative R&D projects capture a larger share of this high‑growth segment.
Expansion into Emerging Regions and Smart Technologies
The healthcare packaging market extends into emerging regions with expanding pharmaceutical sectors in Latin America and Asia‑Pacific. It presents converters with volume growth and the need for cost‑effective, scalable production lines. Digital print integration allows rapid label customization and local language compliance for diverse markets. Smart packaging technologies that incorporate RFID and NFC tags enable remote monitoring and patient engagement. Stakeholders that deploy automated production cells reduce lead times and improve quality metrics. This blend of regional expansion and digital adoption supports sustainable growth trajectories. Partners that align with these trends position themselves for long‑term success in global supply chains.
Market Segmentation Analysis:
By Material Type
The healthcare packaging market divides into glass, plastic, metal and paper & paperboard segments that address varied protection requirements. It assigns glass to injectables and diagnostics because of its chemical inertness and clarity. Plastic dominates disposables due to low cost and impact resistance. Metal supports advanced barrier properties for oxygen‑sensitive drugs. Paper & paperboard serves secondary packaging and cartons. This segmentation guides converters to select substrates that optimize safety, durability and regulatory compliance for each application.
For instance, Gerresheimer utilizes glass extensively for injectable pharmaceuticals due to its chemical inertness and clarity, ensuring drug stability and patient safety.
By Product
The healthcare packaging market organizes products into bottles & containers, vials & ampoules, cartridges & syringes, pouches & bags, blister packs, tubes, paperboard boxes, caps & closures, labels and other formats. It allocates vials & ampoules and cartridges & syringes for parenteral therapies. Bottles & containers and tubes suit oral and topical drugs. Pouches & bags and blister packs protect single‑dose units. Caps & closures and labels integrate tracking and tamper evidence. This structure helps manufacturers tailor designs to meet dosing accuracy, handling and supply‑chain traceability requirements.
For instance, Uhlmann’s LiPro system efficiently packages vials, ampoules, and cartridges with integrated Track & Trace software to ensure patient safety and clear product traceability.
By Application
The healthcare packaging market applies to medical tools & equipment, medical devices and in‑vitro diagnostic products. It serves medical tools & equipment with rigid trays and pouches that ensure sterility during storage and transport. Medical devices require customized packaging that preserves calibration and functionality. In‑vitro diagnostic products demand barrier films and compartmented formats to prevent cross‑contamination. This categorization enables stakeholders to address unique performance specifications, validate packaging protocols and maintain compliance across diverse healthcare segments.
Segments:
Based on Material Type
- Glass
- Plastic
- Metal
- Paper and Paperboard
Based on Product
- Bottles and Containers
- Vials and Ampoules
- Cartridges and Syringes
- Pouches and Bags
- Blister Packs
- Tubes
- Paper Board Boxes
- Caps and Closures
- Labels
- Other
Based on Application
- Medical Tools & Equipment
- Medical Devices
- In-Vitro Diagnostic Product
Based on Drug Delivery Mode
- Oral
- Injectable
- Dermal/Topical
- Inhalable
- Others
Based on Packaging
- Primary Packaging
- Secondary Packaging
Based on Packaging Format
- Flexible Packaging
-
- Bags & Pouches
- Envelopes
- Tubes
- Sachets
- Rigid Packaging
-
- Trays
- Boxes & Folding Cartons
- Clamshells
- Blisters
- Bottles & Jars
- Containers
- Aerosol Cans
- Ampoules & Vials
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The healthcare packaging market holds a 28 percent share in North America. It benefits from robust pharmaceutical production and stringent FDA regulations. Manufacturers deploy high‑barrier polymers and multilayer films for sterile injectables. Converters integrate serialization systems to prevent counterfeiting. Companies invest in digital printing for rapid label customization. This region supports advanced automation and quality management systems. Stakeholders drive innovation through strategic technical collaborations and infrastructure investments globally across sectors.
Europe
The healthcare packaging market commands a 24 percent share in Europe. It relies on stringent EU directives and comprehensive sustainability mandates. Manufacturers adopt recyclable polymers and lightweight laminate designs. Converters integrate advanced barrier films for diagnostic kits and medical devices. Companies employ automated inspection systems to verify seal integrity. Stakeholders invest in digital printing for rapid SKU changeovers. Regulatory frameworks and green policies drive improvement and competitive differentiation across markets.
Asia Pacific
The healthcare packaging market secures a 37 percent share in Asia Pacific. It leverages cost-efficient manufacturing hubs in China and India. Manufacturers produce high-volume syringe and vial packaging to meet growing demand. Converters expand cold chain capabilities for sensitive biologics and vaccines. Companies customize labels for local language requirements and regulatory compliance. Stakeholders adopt scalable automation to enhance throughput. This focus drives sustainable growth and competitive advantage across emerging economies.
Latin America & Middle East & Africa
The healthcare packaging market holds 7 percent in Latin America and 4 percent in Middle East & Africa. It serves growing pharmaceutical sectors in Brazil, Mexico, Gulf states and South Africa. Manufacturers produce cost‑efficient blister packs and sachets for generics. Converters adapt materials to withstand tropical and arid climates. Companies integrate multilingual labels, tamper‑evident seals. Stakeholders establish regional facilities to improve distribution speed. This focus offers growth through collaborations.
Key Player Analysis
- Berry Global Inc.
- Dunmore Corporation
- Toray Plastics, Inc.
- CCL Industries Inc.
- Sonoco Products Company
- Winpak Ltd.
- 3M Company
- Constantia Flexibles Group GmbH
- Sealed Air Corporation
- Huhtamäki Oyj
- Gerresheimer AG.
- Amcor plc
- DS Smith Plc
Competitive Analysis
Leading packaging converters and material suppliers such as Amcor plc, Berry Global Inc., and Huhtamäki Oyj compete on quality, innovation and sustainability. The healthcare packaging market demands high barrier performance for sterile drugs and sensitive biologics. It pushes firms to develop multilayer films, advanced polymers and peelable seals that meet stringent FDA and EMA requirements. Companies such as Sealed Air Corporation and Constantia Flexibles Group secure contracts by offering tamper‑evident closures and digital printing capabilities that enable rapid SKU customization. Firms like 3M Company differentiate offerings through antimicrobial coatings and surface modifications. Smaller specialists such as Winpak Ltd. and Toray Plastics, Inc. target niche applications with bespoke pouches and cold‑chain liners. Industry leaders invest in automation and serialization technology to accelerate throughput and enhance traceability. Strategic partnerships between converters and pharmaceutical brands streamline supply chains and reduce lead times. Competitive pressure drives consolidation through mergers and acquisitions, while joint R&D projects accelerate material innovation and reduce overall packaging costs.
Recent Developments
- In December 2024, Japan-based TOPPAN Holdings acquired the thermoformed and flexibles packaging business of Sonoco Products, a deal valued at $1.8 billion, highlighting consolidation in the packaging sector.
- On July 21, 2025, Ampersand Capital Partners completed the acquisition of CurTec Group B.V., a specialist in high‑performance plastic packaging for pharmaceutical and specialty chemicals
- On July 25, 2025, Nelipak® Corporation broke ground on a new ISO 13485‑certified healthcare packaging facility in Grecia, Alajuela, Costa Rica.
- On July 24, 2025, DuPont launched Tyvek® with Renewable Attribution, an extension of its sustainable healthcare packaging portfolio designed to lower carbon footprint.
Market Concentration & Characteristics
The healthcare packaging market exhibits moderate-to-high concentration, with top ten players controlling the majority of global revenue. Major firms such as Amcor plc, Berry Global Inc., Huhtamäki Oyj and 3M Company secure contracts with leading pharmaceutical manufacturers through proven compliance and advanced material portfolios. It features high entry barriers due to strict regulatory approval processes, capital-intensive production lines and certified quality management systems. Market participants compete on innovation in barrier technologies, tamper‑evident solutions and sustainability credentials. Niche specialists provide tailored offerings for regional biosimilar and vaccine packaging segments. It involves strategic partnerships between converters, resin suppliers and pharmaceutical brands to accelerate product development. Regional fragmentation persists in emerging markets, where local converters adapt materials for climate resilience and cost optimization. Volume production centers in Asia Pacific supply cost‑effective solutions, while North America and Europe drive high‑margin custom formats. It demands continuous investment in automation and traceability systems to comply with evolving pharmaceutical distribution models.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Product, Application, Drug Delivery Mode, Packaging, Packaging Format and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will adopt smart labels with real‑time monitoring to ensure product integrity.
- Companies will expand cold‑chain packaging solutions to support growing biologics and vaccines.
- Converters will integrate digital printing for on‑demand, patient‑specific labeling.
- Suppliers will develop bio‑based and recyclable materials to meet environmental mandates.
- Firms will deploy robotics and AI‑driven inspection to enhance production accuracy.
- Stakeholders will collaborate on serialization networks to combat counterfeiting globally.
- Providers will customize ergonomic packaging to improve patient adherence and dosing.
- Regions will localize manufacturing to reduce lead times and supply‑chain risk.
- Partners will invest in modular production lines to accommodate rapid SKU changes.
- Brands will leverage data analytics to optimize packaging design and reduce waste.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Standards
Strict FDA, EMA, and ISO requirements mandate advanced barrier materials, sterilization compatibility, and tamper-evident features, compelling manufacturers to innovate and invest in high-performance packaging solutions.
Patient Safety and Supply Chain Traceability
The need for serialization, RFID tracking, and temperature-sensitive labels to ensure product authenticity and protect biologics drives adoption of smart packaging technologies and enhances market demand.
Sustainability Initiatives
Growing environmental concerns and corporate sustainability goals are pushing manufacturers to develop recyclable plastics, bio-based substrates, and lightweight packaging, supporting long-term market growth.
Growth in Biologics and Personalized Therapies
The rise of biologics and personalized medicines requires specialized packaging formats such as prefilled syringes and cold-chain compatible solutions, expanding opportunities for innovative packaging providers.
Digital Printing and Automation
The integration of digital printing and automated inspection systems enables rapid SKU changeovers, personalized labeling, and improved production efficiency, making packaging more responsive to evolving healthcare needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the healthcare packaging market?
What factors are driving the growth of the healthcare packaging market?
What are the key segments within the healthcare packaging market?
What are some challenges faced by the healthcare packaging market?
Who are the major players in the healthcare packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Bottles and Containers
- 1.2.2 Vials and Ampoules
- 1.2.3 Cartridges and Syringes
- 1.2.4 Pouches and Bags
- 1.2.5 Blister Packs
- 1.2.6 Tubes
- 1.3 By Application
- 1.3.1 Medical Tools & Equipment
- 1.3.2 Medical Devices
- 1.3.3 In-Vitro Diagnostic Product
- 1.4 By Material Type
- 1.4.1 Glass
- 1.4.2 Plastic
- 1.4.3 Metal
- 1.4.4 Paper and Paperboard
- 1.5 By Packaging Format
- 1.5.1 Flexible Packaging
- 1.5.2 Rigid Packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 192.84 billion → 2032: USD 353.04 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Healthcare Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Healthcare Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Healthcare Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Healthcare Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Healthcare Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Healthcare Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Healthcare Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Healthcare Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 192.84 billion → 2032: USD 353.04 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Healthcare Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bottles and Containers
- 12.3.7.2 Vials and Ampoules
- 12.3.7.3 Cartridges and Syringes
- 12.3.7.4 Pouches and Bags
- 12.3.7.5 Blister Packs
- 12.3.7.6 Tubes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Medical Tools & Equipment
- 12.4.7.2 Medical Devices
- 12.4.7.3 In-Vitro Diagnostic Product
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Glass
- 12.5.7.2 Plastic
- 12.5.7.3 Metal
- 12.5.7.4 Paper and Paperboard
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Packaging Format - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Flexible Packaging
- 12.6.7.2 Rigid Packaging
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Healthcare Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Healthcare Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Healthcare Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Healthcare Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Berry Global Inc.
- 18.4 Huhtamäki Oyj
- 18.5 3M Company
- 18.6 Sonoco Products Company
- 18.7 Sealed Air Corporation
- 18.8 Gerresheimer AG
- 18.9 Constantia Flexibles Group GmbH
- 18.10 Winpak Ltd.
- 18.11 CCL Industries Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

