
Market Overview
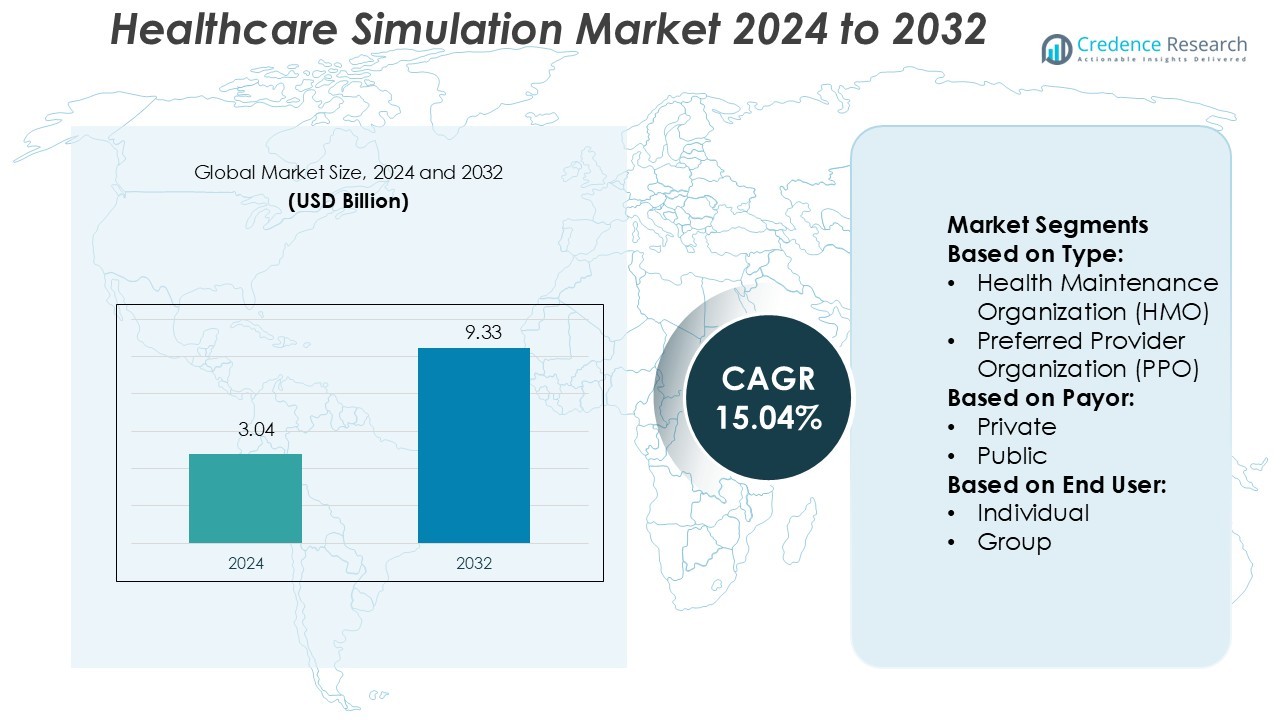
Healthcare Simulation Market size was valued USD 3.04 billion in 2024 and is anticipated to reach USD 9.33 billion by 2032, at a CAGR of 15.04% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Healthcare Simulation Market Size 2024 | USD 3.04 Billion |
| Healthcare Simulation Market, CAGR | 15.04% |
| Healthcare Simulation Market Size 2032 | USD 9.33 Billion |
The healthcare simulation market is driven by key players including Intelligent Ultrasound, Gaumard Scientific, Kyoto Kagaku Co., Ltd, Surgical Science Sweden AB, Simulaids, Operative Experience, Inc., Limbs & Things Ltd, Mentice, 3D Systems, Inc., and Simulab Corporation. These companies focus on advanced simulation technologies such as AI-enabled platforms, VR-based training tools, and high-fidelity manikins to enhance clinical skill development. Strategic partnerships with academic institutions and healthcare providers strengthen their global presence. North America leads the healthcare simulation market with a 39.4% share, supported by strong healthcare infrastructure, early technology adoption, and regulatory initiatives promoting patient safety and training standardization.
Market Insights
- The Healthcare Simulation Market was valued at USD 3.04 billion in 2024 and is projected to reach USD 9.33 billion by 2032, growing at a CAGR of 15.04%.
- Market growth is supported by increasing investments in AI-enabled simulation platforms, VR training tools, and high-fidelity manikins that enhance medical skill development.
- Key players focus on product innovation, strategic partnerships, and academic collaborations to strengthen their competitive position and global reach.
- High initial investment costs and limited skilled personnel act as major restraints, particularly in developing regions.
- North America leads with a 39.4% market share, followed by Europe with 27.8% and Asia Pacific with 23.6%. The hospital and academic segment accounts for the largest share, driven by regulatory support and training standardization.
Market Segmentation Analysis:
By Type
The Health Maintenance Organization (HMO) segment holds the largest market share in the healthcare simulation market. HMO models offer lower premiums and coordinated care through primary care providers, increasing patient enrollment. Strong cost-control mechanisms and preventive care programs enhance their appeal. Growth is supported by rising awareness of managed healthcare plans and improved reimbursement structures. Many healthcare institutions adopt HMO models to streamline service delivery and reduce administrative costs, driving their dominance over PPO and EPO models.
- For instance, Intelligent Ultrasound had deployed over 1,700 high-fidelity ultrasound simulator systems to more than 800 medical institutions in an expanded number of countries.
By Payor
The private payor segment dominates the healthcare simulation market, supported by growing employer-sponsored health plans and personalized insurance options. Private insurers provide flexible coverage, faster claim processing, and value-added services, attracting more consumers. Increasing competition among private insurers leads to innovative plan offerings and improved customer engagement. This growth is further driven by digital health adoption and the expansion of virtual care services, which align well with private sector efficiency models and cost-sharing programs.
- For instance, Gaumard Scientific’s HAL® S5301 patient simulator includes a wireless, tetherless design that enables fully operational use during transport and supports Bluetooth, RF, and wired connectivity modes.
By End User and Mode
The individual segment leads the healthcare simulation market due to rising consumer demand for flexible and affordable coverage. Growing awareness of personalized health plans and digital enrollment platforms supports this trend. In terms of mode, the online segment holds the dominant share, driven by telehealth expansion and digital access to insurance services. Online platforms offer convenience, real-time plan comparison, and faster onboarding. Increased smartphone penetration and growing preference for virtual healthcare solutions further strengthen this segment’s growth.
Key Growth Drivers
Rising Demand for Advanced Medical Training
Healthcare professionals increasingly rely on realistic training tools to enhance patient safety. High-fidelity simulation systems allow learners to practice critical procedures in controlled environments. Academic institutions and hospitals are integrating simulation labs into their training programs to reduce medical errors. Government and private funding for medical education further support this adoption. The growing focus on competency-based learning continues to push healthcare organizations to invest in simulation platforms, driving strong market expansion.
- For instance, Hamamatsu Photonics offers a variety of light sources for biomedical and industrial applications, which includes both lamps and lasers LC8 is a UV spot light source that uses a mercury-xenon lamp and is suitable for tasks like UV curing or microscope illumination.
Growing Focus on Patient Safety and Risk Reduction
Healthcare systems are adopting simulation technology to minimize adverse events and improve clinical outcomes. Simulation enables repeated practice of complex procedures without putting real patients at risk. Hospitals use scenario-based training to strengthen teamwork and response time in emergencies. Regulatory bodies also promote structured simulation-based assessments as part of quality standards. This focus on safer care delivery boosts investment in simulation tools, accelerating market growth.
- For instance, ROHM Semiconductor develops red laser diodes, such as the RLD63NPCx series, which operate at a typical wavelength of 635 nm. These high-precision laser diodes are suitable for applications such as optical disk pickups and sensors.
Technological Advancements in Simulation Platforms
Continuous innovation enhances the realism and performance of simulation technologies. Artificial intelligence, virtual reality, and augmented reality are improving the accuracy and adaptability of training systems. Integration with electronic health records allows more personalized learning experiences. Portable and cloud-based solutions also enable remote training and scalability for institutions. These innovations are making simulation more accessible and effective, driving strong adoption across medical education and healthcare organizations.
Key Trends & Opportunities
Expansion of Virtual and Remote Simulation
The market is witnessing a rapid shift toward web-based and VR-driven training solutions. These tools allow learners to access simulation modules without physical lab constraints. Hospitals and universities use remote platforms for continuous education and emergency response training. The flexibility of these solutions is opening opportunities in developing regions and rural areas with limited infrastructure.
- For instance, Nichia's NDB7K75 laser diode is a high-power blue laser diode with a dominant wavelength of 450 nm, delivering 3.5 W output power for applications such as high-intensity lighting and industrial processing.
Integration of AI and Analytics in Training Programs
AI-powered simulation platforms offer real-time performance tracking and personalized feedback. These capabilities help trainers identify skill gaps and improve learning outcomes. Analytics also support evidence-based training design and accreditation compliance. This trend is creating opportunities for software providers and driving the adoption of advanced simulation technologies in healthcare institutions.
- For instance, IPG Photonics offers high-power single-mode fiber lasers in its YLR-SM series. These lasers can provide up to 3 kW of continuous-wave output, typically with a wavelength of ~1,070 nm.
Rising Investments in Specialized Simulation Centers
Healthcare systems are increasing investments in dedicated simulation centers to support advanced learning. These centers enable multi-disciplinary training, emergency response preparation, and complex surgical procedure practice. Industry partnerships and academic collaborations are also expanding, creating new revenue streams and growth opportunities for simulation solution providers.
Key Challenges
High Initial Investment and Maintenance Costs
Advanced simulation systems require significant capital for installation, equipment, and ongoing updates. Many healthcare institutions face budget constraints, particularly in developing regions. Maintenance, software upgrades, and faculty training add to the operational costs. This financial barrier limits access to advanced simulation tools and slows adoption among smaller facilities.
Limited Trained Personnel and Technical Expertise
Effective simulation training depends on skilled instructors and technicians. Many institutions lack trained personnel to manage complex systems and run simulation scenarios effectively. This shortage impacts the quality and consistency of training programs. Without sufficient investment in workforce development, the expansion of healthcare simulation remains constrained.
Regional Analysis
North America
North America leads the healthcare simulation market with a 39.4% share in 2024. The region benefits from advanced healthcare infrastructure, strong regulatory support, and widespread use of simulation-based medical training. The U.S. dominates due to early technology adoption in academic and clinical settings. Federal funding and accreditation requirements further encourage simulation integration in medical education. High investments in AI-powered simulators and virtual reality platforms enhance training efficiency. Leading universities and hospitals continue to expand their simulation centers, solidifying North America’s position as the largest regional market.
Europe
Europe holds a 27.8% share of the healthcare simulation market in 2024. The region’s growth is supported by robust government initiatives to standardize medical training and improve patient safety. Countries such as Germany, the U.K., and France lead adoption through strong academic and clinical collaborations. The European healthcare system emphasizes quality assurance and continuous professional education. Advanced simulation labs and increased funding for healthcare digitalization further strengthen market expansion. Growing partnerships between technology providers and medical institutions position Europe as a key innovation hub in simulation technologies.
Asia Pacific
Asia Pacific accounts for a 23.6% share of the healthcare simulation market in 2024. Rapid healthcare infrastructure development, growing medical education demand, and rising investments in digital training tools drive regional growth. China, Japan, and India are leading adopters, supported by government health programs and expanding medical universities. Affordable VR-based and cloud-enabled simulators increase accessibility in training environments. The region is also witnessing a surge in private investments and international collaborations. Strong economic growth and digital transformation initiatives position Asia Pacific as the fastest-growing regional market.
Latin America
Latin America represents a 5.2% share of the healthcare simulation market in 2024. Brazil and Mexico lead adoption, supported by healthcare modernization programs and rising demand for skilled medical professionals. The region focuses on improving patient safety and emergency response capabilities. Simulation centers in teaching hospitals and universities are expanding with support from government and private funding. Partnerships with international training organizations help build capacity and technical expertise. Although investment levels are lower than in developed markets, growing awareness of simulation benefits supports steady regional growth.
Middle East & Africa
The Middle East & Africa account for a 4% share of the healthcare simulation market in 2024. Market growth is driven by government-led healthcare transformation programs and increasing adoption of digital training technologies. The UAE and Saudi Arabia are leading the region with investments in advanced simulation centers for medical education. Partnerships with global simulation companies support rapid skill development in critical care and emergency medicine. Limited infrastructure in parts of Africa presents challenges, but rising healthcare spending and workforce training needs offer promising growth potential.
Market Segmentations:
By Type:
- Health Maintenance Organization (HMO)
- Preferred Provider Organization (PPO)
By Payor:
- Private
- Public
By End User:
- Individual
- Group
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The healthcare simulation market is shaped by key players such as Intelligent Ultrasound, Gaumard Scientific, Kyoto Kagaku Co., Ltd, Surgical Science Sweden AB, Simulaids, Operative Experience, Inc., Limbs & Things Ltd, Mentice, 3D Systems, Inc., and Simulab Corporation. The healthcare simulation market is becoming increasingly competitive, driven by strong investments in advanced training technologies. Companies are focusing on AI-enabled platforms, virtual reality, and high-fidelity manikins to enhance the realism of medical training. Partnerships with universities, hospitals, and training centers are expanding global reach and improving product adoption. Many firms are prioritizing scalable and cloud-based solutions to support remote and hybrid learning environments. Continuous innovation, regulatory compliance, and training standardization are key factors shaping the market. Strategic mergers, acquisitions, and new product launches are strengthening market positions and supporting long-term growth opportunities.
Key Player Analysis
- Intelligent Ultrasound
- Gaumard Scientific
- Kyoto Kagaku Co., Ltd
- Surgical Science Sweden AB
- Simulaids
- Operative Experience, Inc.
- Limbs & Things Ltd
- Mentice
- 3D Systems, Inc.
- Simulab Corporation
Recent Developments
- In May 2025, Goodwin University revealed plans for a nursing simulation center. This facility will include high-fidelity mannequins and specialized medical environments, offering students extensive, hands-on training experiences to prepare them for real-world clinical situations.
- In January 2024, Laerdal Medical announced a global distribution partnership with SIMCharacters, an Austrian company specializing in neonatal simulation technology. The partnership aims to revolutionize medical training and enhance healthcare simulation.
- In January 2024, CAE Inc.collaborated with SimHawk. This collaboration aims to combine SimHawk's didactic and motion-based learning with CAE Healthcare's manikin-based simulation, ultimately offering a more comprehensive and effective training experience.
- In June 2023, Wolters Kluwer Health announced collaborating with Laerdal Medical and the National League for Nursing (NLN) to launch vrClinicals for Nursing. This VR-based learning solution is designed to address the gaps in nursing education and prepare students for the real-world pressures of nursing practice.
Report Coverage
The research report offers an in-depth analysis based on Type, Payor, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see wider adoption of AI-powered simulation platforms in training programs.
- Virtual reality and augmented reality tools will enhance immersive medical education.
- Cloud-based simulation solutions will support remote and hybrid learning models.
- Government funding and regulatory support will strengthen training infrastructure.
- Integration with electronic health records will improve personalized learning experiences.
- Demand for specialized simulation centers will grow across academic institutions.
- Strategic collaborations will expand simulation access in emerging economies.
- Advancements in sensor technologies will increase training accuracy and realism.
- Mobile and portable simulation devices will enable flexible learning environments.
- Continuous innovation will drive broader acceptance in both clinical and academic settings.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Healthcare Simulation Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Healthcare Simulation Market projected to grow between 2025 and 2032?
Which Healthcare Simulation Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Healthcare Simulation Market?
Who are the leading companies in the Healthcare Simulation Market?
Which region commanded the largest share of the Healthcare Simulation Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.04 billion → 2032: USD 9.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Healthcare Simulation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Healthcare Simulation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Healthcare Simulation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Healthcare Simulation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Healthcare Simulation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Healthcare Simulation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Healthcare Simulation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Healthcare Simulation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.04 billion → 2032: USD 9.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Healthcare Simulation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Healthcare Simulation Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Healthcare Simulation Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Healthcare Simulation Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

