
Market Overview
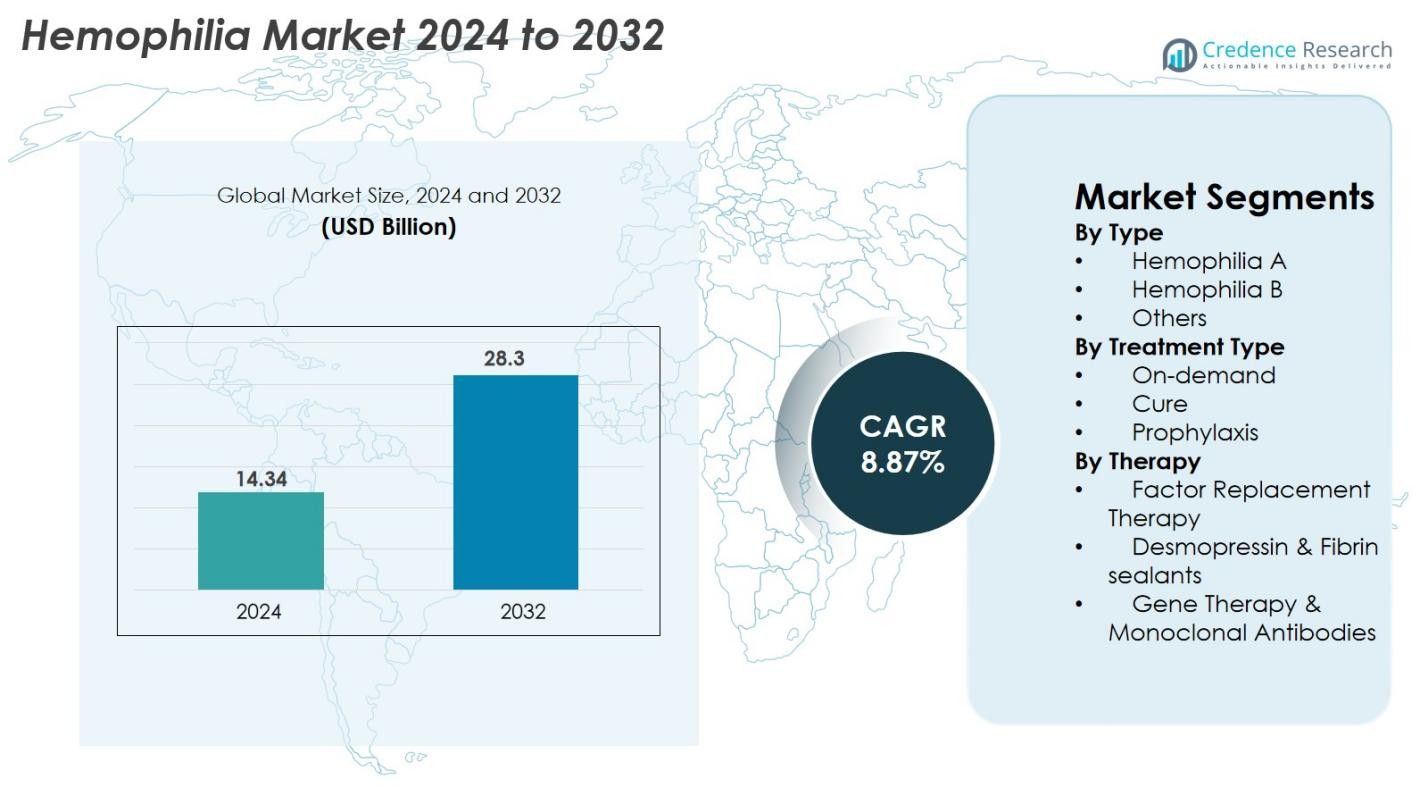
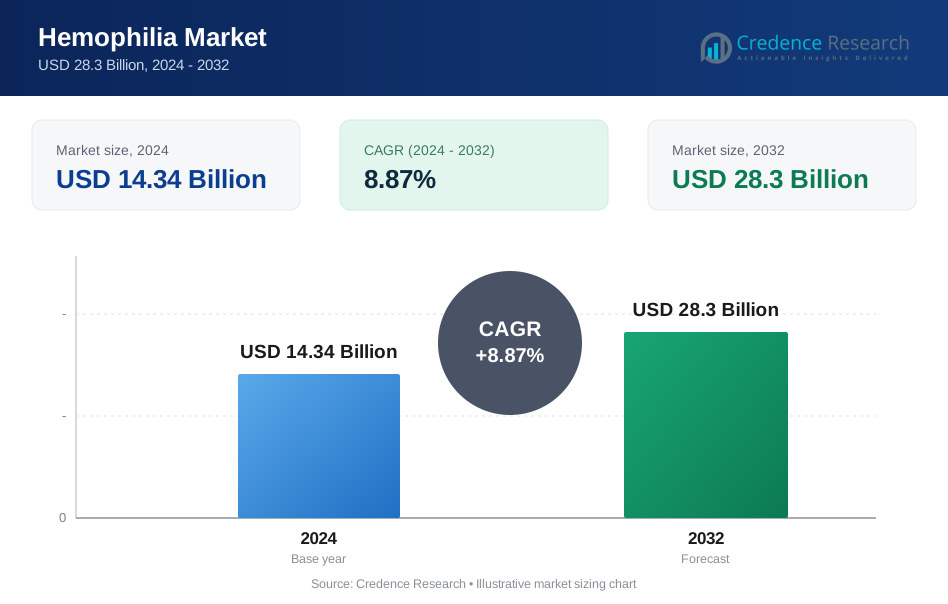
Hemophilia Market size was valued at USD 14.34 Billion in 2024 and is anticipated to reach USD 28.3 Billion by 2032, at a CAGR of 8.87% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hemophilia Market Size 2024 | USD 14.34 Billion |
| Hemophilia Market, CAGR | 8.87% |
| Hemophilia Market Size 2032 | USD 28.3 Billion |
Hemophilia Market features strong participation from global biopharmaceutical leaders, including Takeda Pharmaceutical Company Limited, CSL Behring, Pfizer Inc., Bayer AG, BioMarin, Spark Therapeutics Inc., Sanofi, F. Hoffmann-La Roche Ltd., Novo Nordisk A/S, and Octapharma AG, all driving innovation across factor replacement therapies, extended half-life products, monoclonal antibodies, and gene therapies. These companies continuously expand R&D pipelines and strategic partnerships to strengthen product portfolios and global reach. Regionally, North America leads the market with a 38% share in 2024, supported by advanced healthcare infrastructure and high adoption of next-generation therapies, while Europe and Asia-Pacific follow as major contributors to overall market growth.
Market Insights
- The Hemophilia Market was valued at USD 14.34 Billion in 2024 and is projected to reach USD 28.3 Billion by 2032, expanding at a CAGR of 8.87%.
- Rising adoption of prophylaxis therapy, which holds the dominant 62% segment share, and increasing availability of recombinant and long-acting biologics are driving market expansion globally.
- Key trends include rapid advancement in gene therapy and monoclonal antibodies, along with growing use of digital health tools and personalized dosing supported by pharmacokinetic profiling.
- Major players such as Takeda, CSL Behring, Pfizer, Bayer, BioMarin, Sanofi, Roche, Spark Therapeutics, Novo Nordisk, and Octapharma are strengthening competitiveness through innovation, strategic collaborations, and global access programs.
- Regionally, North America leads with a 38% share, followed by Europe at 30% and Asia-Pacific at 22%, while Latin America and the Middle East & Africa hold the remaining share, supported by improving diagnosis and treatment programs.
Market Segmentation Analysis
By Type
The Hemophilia market by type is dominated by Hemophilia A, accounting for 78% of the market share in 2024, driven by its significantly higher prevalence compared to Hemophilia B and other rare clotting disorders. The strong diagnostic presence, established treatment protocols, and larger patient pool support this dominance. Hemophilia B holds a moderate share due to fewer global cases, while the “Others” segment remains limited but benefits from advancements in molecular diagnostics. Rising awareness programs, improved newborn screening, and expanded access to replacement factors continue to propel growth across all type-based segments.
- For instance, Roche's Hemlibra (emicizumab) had already been used to treat over 20,000 people globally across clinical and real-world programs by early 2023, demonstrating its extensive adoption in Hemophilia A management.
By Treatment Type
The treatment type segmentation highlights Prophylaxis as the leading sub-segment, capturing 62% of the market share in 2024, supported by its proven ability to prevent bleeding episodes and reduce long-term joint damage. Its adoption is rising globally as clinical guidelines increasingly recommend prophylactic regimens over episodic (on-demand) treatment. On-demand therapy still holds relevance in developing markets where cost barriers persist. “Cure”-oriented approaches, including emerging gene therapy pathways, remain small but fast-growing, primarily driven by ongoing clinical advancements and rising acceptance of potentially one-time curative treatments.
- For instance, Roche’s Hemlibra prophylaxis showed an annualized bleed rate (ABR) of 1.5 in the HAVEN 3 trial, compared to 38.2 with no prophylaxis, demonstrating a significant reduction in bleeding episodes.
By Therapy
Within therapy segmentation, Factor Replacement Therapy remains the dominant segment, contributing 71% of the market share in 2024, attributed to its long-standing clinical use, availability of recombinant factors, and strong physician preference. Its growth is sustained by the shift toward extended half-life products that reduce infusion frequency. Desmopressin and fibrin sealants serve as supportive options for mild cases, contributing modestly to overall revenue. Meanwhile, Gene Therapy and Monoclonal Antibodies represent the fastest-expanding sub-segments, driven by innovations targeting sustained factor expression, reduced treatment burden, and long-term disease modification.
Key Growth Drivers
Rising Adoption of Prophylactic Treatment Regimens
The global Hemophilia market continues to expand due to the increasing shift from on-demand treatment to full prophylactic care. Prophylaxis significantly reduces bleeding frequency, improves joint health, and enhances overall quality of life, prompting widespread recommendation by international clinical guidelines. Countries with advanced healthcare systems, such as the U.S., Germany, and Japan, report high prophylaxis adoption rates, while emerging economies are gradually transitioning due to improving reimbursement structures. Pediatric populations particularly benefit from early prophylaxis initiation, reducing long-term disease complications. Extended half-life (EHL) factors further strengthen this driver by lowering infusion burden, improving adherence, and supporting consistent bleed prevention.
- For instance, Roche’s Hemlibra prophylaxis reduced treated bleeds to an annualized bleed rate (ABR) of 1.5 in the HAVEN 3 study, compared to 38.2 without prophylaxis, demonstrating substantial clinical benefit
Advancements in Gene Therapy and Long-Acting Biologics
Gene therapy is emerging as one of the most transformative drivers, offering the possibility of a functional cure through durable factor expression. Biotech innovators and major pharmaceutical companies continue to accelerate clinical trial progress, regulatory filings, and market launch strategies. Approvals for long-acting biologics and monoclonal antibodies are reshaping treatment by allowing low-frequency dosing and reducing lifelong infusion dependency. These technologies significantly enhance patient convenience and long-term outcomes. Growing investment, promising safety profiles, and patient willingness to opt for curative approaches further boost market expansion, positioning gene therapy as a major growth catalyst.
- For instance, CSL Behring and uniQure’s Hemgenix demonstrated a mean Factor IX activity of 36 IU/dL at 18 months in Phase 3 HOPE-B results, confirming sustained expression after a single infusion.
Increasing Global Diagnosis Rates and Access to Treatment
Rising diagnosis rates, expanding newborn screening programs, and increasing awareness are significantly improving patient identification across developed and emerging economies. Global initiatives by organizations such as the World Federation of Hemophilia are helping bridge treatment gaps, especially in countries where underdiagnosis was previously widespread. Improved access to recombinant and plasma-derived products, along with strengthened healthcare infrastructure in India, Brazil, China, and Africa, is driving broader treatment adoption. Digital health platforms, home-infusion services, and telemedicine are further enhancing accessibility, reducing follow-up gaps, and supporting better adherence. As diagnostic capabilities continue to expand globally, the market benefits from steady growth in the treated patient population.
Key Trends & Opportunities
Expansion of Gene Therapy Commercialization and Market Uptake
A major trend shaping the Hemophilia market is the transition of gene therapies from clinical research to commercial rollout. As more products receive regulatory approvals, companies are scaling manufacturing capacity, enhancing distribution frameworks, and developing outcome-based pricing models that support reimbursement. Real-world evidence is strengthening payer and provider confidence, demonstrating sustained factor expression and reduced bleed rates. Increasing collaborations among biotech firms, CDMOs, and government agencies are improving accessibility and accelerating adoption. Over the next decade, broader eligibility criteria, stronger safety data, and improved affordability will create substantial opportunities within this rapidly evolving treatment landscape.
- For instance, Hemlibra demonstrated strong efficacy with minimal dosing frequency options, and achieved a median annualized bleed rate (ABR) of 0.0 in its once-every-4-weeks dosing pivotal trial (HAVEN 4).
Rising Use of Digital Health Platforms and Personalized Treatment Approaches
Digital health adoption is accelerating, driven by AI-powered monitoring tools, mobile apps, and wearable devices that track bleeding episodes, factor usage, and treatment adherence. Personalized therapy guided by pharmacokinetic (PK) profiling allows clinicians to optimize dosing schedules and minimize factor wastage. These tools enhance patient engagement, improve disease management, and support remote clinical interventions, especially for pediatric and underserved populations. Pharmaceutical companies are increasingly integrating digital services with their biologic and gene therapy products to support education, monitoring, and treatment optimization. As digital ecosystems strengthen, they unlock new opportunities for precision care and differentiated product positioning.
- For instance, BioMarin collects long-term data on FVIII expression patterns and patient outcomes for Roctavian-treated patients through required post-market surveillance, long-term follow-up studies, and national hemophilia registries
Key Challenges
High Treatment Costs and Limited Reimbursement in Emerging Markets
The high cost of Hemophilia therapies-including recombinant factors, extended half-life products, and gene therapies-remains a major barrier, particularly in developing regions. Many healthcare systems lack the financial capacity to support continuous prophylactic treatment or advanced biologics, forcing patients to rely on inconsistent access to plasma-derived factors. Limited insurance coverage and slow reimbursement approvals further widen global treatment disparities. Although international aid programs provide support, they are insufficient to meet long-term demand. Payers also hesitate to reimburse costly gene therapies due to long-term cost-effectiveness uncertainty, posing a significant challenge to widespread global access and adoption.
Safety Concerns, Inhibitor Development, and Long-Term Uncertainty
Despite technological advances, inhibitor development remains a significant clinical challenge, reducing treatment efficacy and increasing complexity. Emerging therapies such as gene therapy and monoclonal antibodies still face concerns related to long-term safety, immune reactions, liver function impacts, and variability in factor expression. Regulatory agencies maintain strict approval pathways, often prolonging commercialization timelines. The need for extensive post-marketing surveillance and long-term monitoring adds additional burden. These challenges highlight the importance of robust clinical validation and careful patient selection, making safety-related concerns one of the most substantial obstacles to broader adoption of next-generation Hemophilia treatments.
Regional Analysis
North America
North America dominates the Hemophilia market, accounting for 38% of the global share in 2024, supported by advanced healthcare infrastructure, strong reimbursement systems, and widespread adoption of prophylaxis and extended half-life factor therapies. The U.S. leads regional growth due to high awareness, improved diagnostic coverage, and rapid uptake of gene therapies and monoclonal antibodies. Strategic collaborations between biopharma companies, extensive clinical research activity, and a strong pipeline of innovative treatments further reinforce the region’s leadership. Rising treatment accessibility through home-infusion programs and digital monitoring tools continues to strengthen North America’s market position through 2032.
Europe
Europe represents the second-largest Hemophilia market, holding 30% of global share in 2024, driven by strong national healthcare systems, structured hemophilia registries, and early adoption of recombinant factor products. Countries such as Germany, the U.K., Italy, and France maintain high treatment penetration due to comprehensive reimbursement frameworks and government-supported patient programs. Increased focus on prophylaxis, expanding home-care infusion support, and rising acceptance of gene therapy options continue to accelerate market growth. Regulatory bodies encourage innovation through accelerated pathways, supporting a steady introduction of long-acting biologics. Europe’s emphasis on patient safety and standardized care further strengthens its market relevance.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing regional market, accounting for 22% of global share in 2024, supported by expanding healthcare spending, improving diagnosis rates, and rising awareness in countries such as China, Japan, India, and South Korea. Government initiatives to strengthen rare disease management and increased availability of plasma-derived and recombinant factors are reshaping treatment accessibility. Japan and Australia lead adoption of advanced biologics, while China and India drive volume growth due to large patient populations. Investment in genetic testing, improved hemophilia centers, and growing interest in digital health platforms position Asia-Pacific for strong long-term expansion.
Latin America
Latin America holds 6% of the global Hemophilia market share in 2024, with growth supported by improving access to diagnostic services and expanding national hemophilia programs in Brazil, Mexico, Argentina, and Chile. Brazil leads the region due to government-funded treatment initiatives and rising availability of recombinant and extended half-life factors. Despite progress, treatment disparities persist due to uneven reimbursement and high therapy costs. International aid programs and partnerships with global organizations continue to support product availability. Gradual improvements in healthcare infrastructure and increased clinician training are expected to enhance treatment uptake across the region over the coming years.
Middle East & Africa
The Middle East & Africa region accounts for 4% of the global market share in 2024, characterized by rising awareness, expanding diagnostic capabilities, and government-led rare disease initiatives. Gulf countries such as Saudi Arabia, the UAE, and Qatar lead adoption of modern therapies due to strong healthcare investments, while African nations rely heavily on international aid and plasma-derived products. Limited infrastructure, high therapy costs, and inconsistent supply chains remain major barriers to widespread adoption. However, growing partnerships with global health organizations and ongoing improvements in specialty care centers are gradually strengthening the region’s future market potential.
Market Segmentations
By Type
- Hemophilia A
- Hemophilia B
- Others
By Treatment Type
- On-demand
- Cure
- Prophylaxis
By Therapy
- Factor Replacement Therapy
- Desmopressin & Fibrin sealants
- Gene Therapy & Monoclonal Antibodies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Hemophilia market features a strong and evolving competitive landscape shaped by global biopharmaceutical leaders and emerging innovators developing advanced therapies. Major companies such as Takeda Pharmaceutical Company Limited, CSL Behring, Pfizer Inc., Bayer AG, BioMarin, Spark Therapeutics Inc., Sanofi, F. Hoffmann-La Roche Ltd., Novo Nordisk A/S, and Octapharma AG play a central role through extensive product portfolios spanning recombinant factors, extended half-life therapies, and novel monoclonal antibodies. The landscape is further reshaped by rapid advancements in gene therapy, where BioMarin, Spark Therapeutics, and Pfizer lead clinical and commercial activities. Strategic partnerships, R&D investments, and regulatory approvals are accelerating innovation, while companies expand global footprints through manufacturing scale-up and access programs. Intensifying competition around long-acting biologics, digital support platforms, and precision-based dosing solutions continues to drive differentiation, positioning key players to strengthen market presence through 2032.
Key Player Analysis
- Bayer AG
- Spark Therapeutics, Inc.
- Octapharma AG
- Novo Nordisk A/S
- BioMarin
- Pfizer, Inc.
- Sanofi
- Takeda Pharmaceutical Company Limited
- CSL Behring
- F. Hoffmann-La Roche Ltd.
Recent Developments
- In June 2025, Novo Nordisk expanded its partnership with the Novo Nordisk Haemophilia Foundation to scale projects aimed at improving care for people living with bleeding disorders, aiming to quadruple annual beneficiaries by 2030.
- In March 2025, Sanofi announced that the U.S. Food and Drug Administration (FDA) approved its therapy Fitusiran (brand name “Qfitlia”) for people aged 12 and older with haemophilia A or B, with or without inhibitors.
- In February 2025, Pfizer announced it would end global development of its gene therapy Fidanacogene elaparvovec (brand name “Beqvez”) for haemophilia B.
Report Coverage
The research report offers an in-depth analysis based on Type, Treatment Type, Therapy and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience strong growth as gene therapy becomes more widely adopted across severe Hemophilia A and B cases.
- Long-acting biologics and monoclonal antibodies will gain larger patient acceptance due to reduced dosing frequency and improved convenience.
- Prophylaxis therapy usage will expand further as global guidelines increasingly recommend preventive treatment over on-demand options.
- Digital health tools and remote monitoring platforms will enhance treatment adherence and personalized care.
- Emerging markets will witness increased diagnosis rates and access to recombinant therapies through government and NGO initiatives.
- Biosimilar factor products will slowly enter selected regions, improving affordability and expanding patient reach.
- Healthcare systems will adopt value-based pricing models to support reimbursement of high-cost gene therapies.
- Innovation in PK-based dosing and individualized therapy will reshape clinical decision-making and optimize factor utilization.
- Strategic collaborations between biotech firms and pharmaceutical companies will accelerate R&D advancements.
- Global manufacturing capacity for recombinant factors and novel biologics will expand to meet rising demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Prophylactic Treatment Regimens
The shift from on-demand to prophylactic care is reducing bleeding episodes and long-term complications, leading to improved patient outcomes and increased market demand, especially in countries with advanced healthcare systems.
Advancements in Gene Therapy and Long-Acting Biologics
Innovations in gene therapy and extended half-life biologics are transforming the treatment landscape by offering the potential for functional cures and reducing the frequency of infusions, which enhances patient convenience and drives market expansion.
Increasing Global Diagnosis Rates and Access to Treatment
Expanded newborn screening, rising awareness, and improved healthcare infrastructure are enabling earlier and more accurate diagnosis, increasing the number of treated patients and supporting market growth in both developed and emerging regions.
Expansion of Digital Health and Personalized Dosing
The adoption of digital health tools, remote monitoring, and pharmacokinetic-guided personalized dosing is improving treatment adherence and optimizing therapy, which supports better clinical outcomes and drives further market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hemophilia Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hemophilia Market projected to grow between 2025 and 2032?
Which Hemophilia Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hemophilia Market?
Who are the leading companies in the Hemophilia Market?
Which region commanded the largest share of the Hemophilia Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Hemophilia A
- 1.2.2 Hemophilia B
- 1.2.3 Others
- 1.3 By Therapy
- 1.3.1 Factor Replacement Therapy
- 1.3.2 Desmopressin & Fibrin sealants
- 1.3.3 Gene Therapy & Monoclonal Antibodies
- 1.4 By Treatment Type
- 1.4.1 On-demand
- 1.4.2 Cure
- 1.4.3 Prophylaxis
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14.34 Billion → 2032: USD 28.3 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hemophilia Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hemophilia Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hemophilia Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hemophilia Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hemophilia Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hemophilia Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hemophilia Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hemophilia Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14.34 Billion → 2032: USD 28.3 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hemophilia Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hemophilia A
- 12.3.7.2 Hemophilia B
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Therapy - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Factor Replacement Therapy
- 12.4.7.2 Desmopressin & Fibrin sealants
- 12.4.7.3 Gene Therapy & Monoclonal Antibodies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-demand
- 12.5.7.2 Cure
- 12.5.7.3 Prophylaxis
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hemophilia Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hemophilia Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hemophilia Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Takeda Pharmaceutical Company Limited
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 CSL Behring
- 17.4 Pfizer Inc.
- 17.5 Bayer AG
- 17.6 BioMarin
- 17.7 Spark Therapeutics Inc.
- 17.8 Sanofi
- 17.9 F. Hoffmann-La Roche Ltd.
- 17.10 Novo Nordisk A/S
- 17.11 Octapharma AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

