
Market Overview:
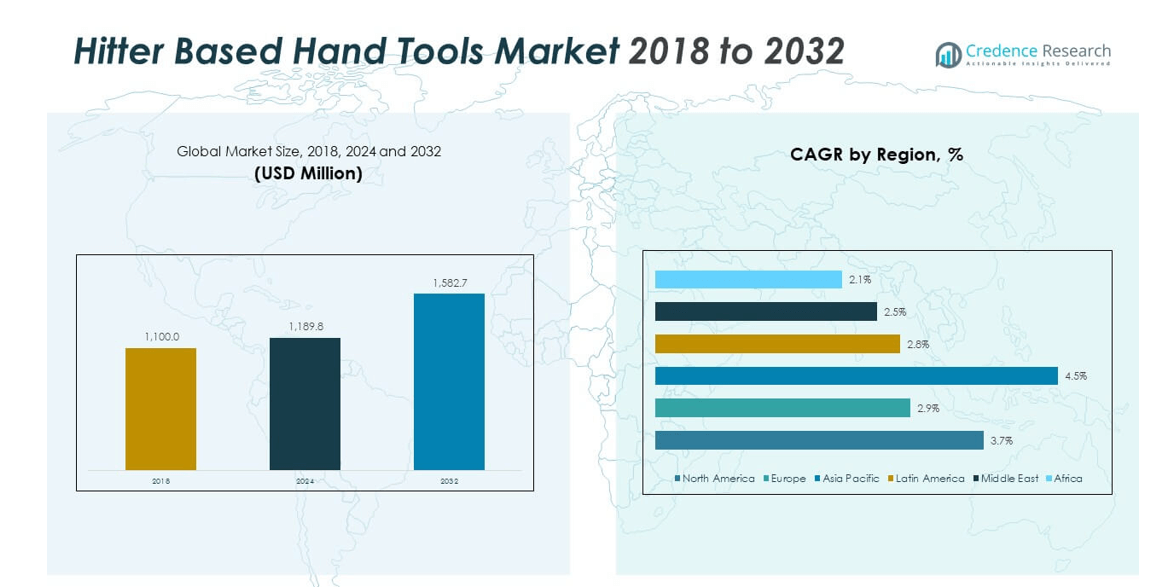
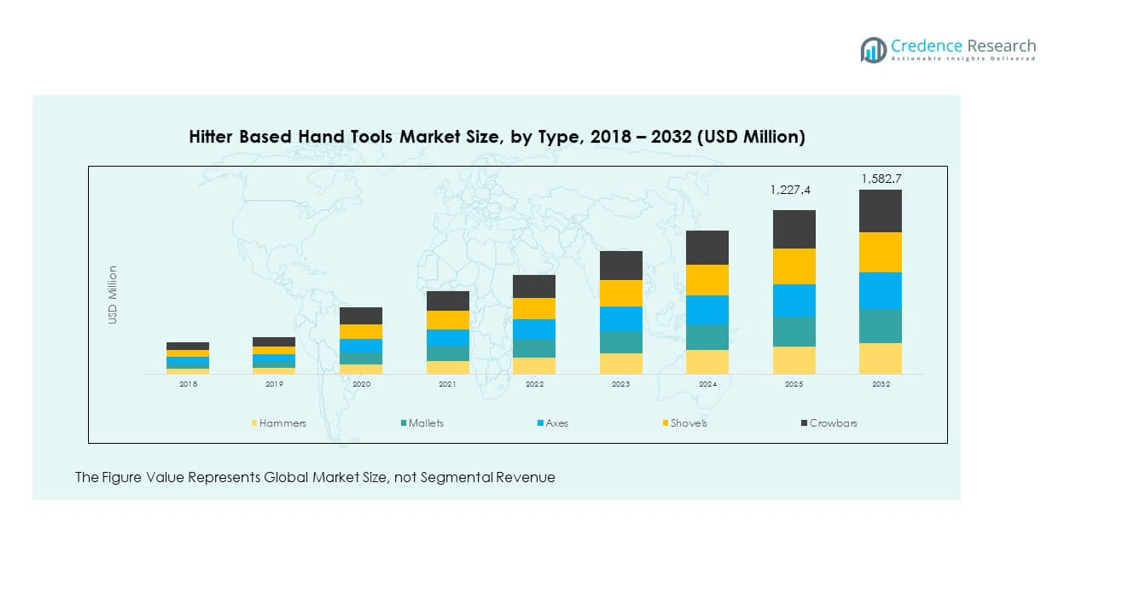
The Hitter Based Hand Tools Market size was valued at USD 1,100.0 million in 2018 to USD 1,189.8 million in 2024 and is anticipated to reach USD 1,582.7 million by 2032, at a CAGR of 3.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hitter Based Hand Tools Market Size 2024 | USD 1,189.8 million |
| Hitter Based Hand Tools Market, CAGR | 3.7% |
| Hitter Based Hand Tools Market Size 2032 | USD 1,582.7 million |
Market growth is driven by rising construction activities, industrial expansion, and home improvement trends. Increasing DIY culture, coupled with strong demand from automotive repair and maintenance, is also fueling adoption. Manufacturers are introducing ergonomic designs and durable materials to enhance user efficiency and safety, which further supports market penetration. Government initiatives promoting infrastructure development, particularly in developing economies, add momentum to demand for hitter-based hand tools across professional and residential applications.
Regionally, North America and Europe dominate the market due to established industrial bases and advanced construction practices. Asia-Pacific is emerging as a high-growth region, supported by rapid urbanization, growing infrastructure projects, and expanding manufacturing hubs in countries like China and India. Latin America and the Middle East are gradually gaining traction, driven by rising residential construction and infrastructure modernization efforts.
Market Insights:
- The Hitter Based Hand Tools Market was valued at USD 1,100.0 million in 2018, reached USD 1,189.8 million in 2024, and is projected to attain USD 1,582.7 million by 2032, growing at a CAGR of 3.7%.
- Asia Pacific accounted for 37.9% of the market in 2024, North America held 26.4%, and Europe captured 22.4%, supported by strong construction activity, industrial applications, and established consumer demand.
- Asia Pacific is the fastest-growing region with 37.9% share, driven by rapid urbanization, infrastructure development, and expanding manufacturing hubs across China, India, and Southeast Asia.
- From the type segmentation, hammers represented the largest portion with roughly 32% of the market share in 2024, supported by wide usage in construction, woodworking, and household applications.
- Shovels accounted for around 25% of the type-based share in 2024, reflecting steady demand in agriculture, forestry, and infrastructure projects worldwide.
Market Drivers:
Expanding construction and infrastructure projects creating sustained demand for durable hand tools
The global rise in construction activity continues to shape the demand for durable hand tools. Governments are prioritizing urban development, road expansion, and housing projects. Contractors and builders require reliable hitter-based tools to perform critical onsite tasks. The Hitter Based Hand Tools Market benefits from consistent procurement across residential and commercial sites. It is seeing steady support from industrial repair and renovation work. Infrastructure programs in developing nations amplify this momentum. Demand aligns with increasing emphasis on safety and durability in professional-grade equipment. Strong infrastructure funding ensures long-term opportunities for hand tool manufacturers.
Rising consumer preference for do-it-yourself projects strengthening household demand channels
DIY adoption has surged across many regions, especially in urban households. Consumers are engaging in personal renovation projects, boosting demand for affordable hand tools. The Hitter Based Hand Tools Market experiences higher volumes of retail sales through home improvement outlets. It is supported by rising interest in self-maintenance and furniture repair. Toolkits with compact yet reliable hitter-based products see fast adoption. Manufacturers target this base with product bundles and ergonomic designs. Online platforms expand availability and convenience for DIY-focused buyers. Growing lifestyle preference for self-reliance continues to reinforce the household demand channel.
- For example, Bosch’s IXO cordless screwdriver is recognized as one of the world’s most popular power tools, with more than 18–20 million units sold globally according to Bosch’s official communications. The IXO series is widely credited for its compact, ergonomic, and user-friendly design that reshaped DIY tool adoption.
Expanding automotive and manufacturing repair activity supporting professional use cases
Industrial repair activities remain a strong growth pillar for tool manufacturers. Automotive service centers rely heavily on hitter-based tools for frequent maintenance jobs. The Hitter Based Hand Tools Market gains traction from increased vehicle ownership and fleet services. It is boosted further by manufacturing plants requiring hand tools for assembly and repair work. Service professionals prioritize tools offering durability and precision. Consistent replacement cycles strengthen recurring sales volumes. Manufacturers focus on designing versatile tools for varied industrial use. This sector ensures reliable revenues in both advanced and emerging economies.
- For example, Snap-on tools are extensively used across industrial and automotive sectors and are certified to ISO 6789 standards for torque measurement on key tools. Official Snap-on product literature highlights this compliance, confirming their reliability and precision for professional maintenance and repair applications worldwide.
Product innovation and ergonomic design enhancements boosting adoption across multiple segments
Ergonomic advancements drive adoption in diverse customer categories. Manufacturers prioritize lightweight designs that reduce fatigue during long use. The Hitter Based Hand Tools Market witnesses upgrades in grip comfort, material strength, and safety features. It is expanding into specialized designs tailored for precision tasks. Professionals value tools that combine efficiency with safety performance. Research investments continue to enhance durability standards. Innovation pipelines include advanced alloys and non-slip coatings. This ongoing innovation cycle ensures broader acceptance across industrial and household markets.
Market Trends:
Rising integration of smart packaging and tracking features for tool distribution efficiency
Manufacturers are introducing smart packaging solutions to streamline logistics and distribution. Packaging now incorporates QR codes for tool authenticity and warranty verification. The Hitter Based Hand Tools Market integrates these measures to combat counterfeiting. It is benefiting from traceable supply chains that reassure both retailers and consumers. Distributors optimize inventory through smart tracking features. Enhanced packaging durability reduces damage during transport. The approach ensures a consistent brand presence across markets. Packaging innovation transforms the buyer experience and strengthens trust in established brands.
- For example, Stanley Black & Decker, in partnership with TerraCycle, operates the Tool Free Recycling Program in the U.S. and Canada, covering DEWALT, CRAFTSMAN, BLACK+DECKER, STANLEY, and other branded tools. Participants can recycle eligible products by requesting a QR code or prepaid shipping label, ensuring proper collection and recycling through TerraCycle’s logistics network.
Expansion of e-commerce platforms shaping purchase behaviors across professional and retail buyers
E-commerce has become a major sales channel for tool manufacturers. Online platforms provide price comparisons and wide product visibility. The Hitter Based Hand Tools Market records significant growth in online sales penetration. It is influenced by global buyers who prefer doorstep delivery and digital support. Retailers align with direct-to-consumer models to extend reach. Online tutorials increase awareness and confidence in tool use. Discounts and promotional bundles drive seasonal peaks in online purchases. E-commerce accelerates both retail and bulk sales segments worldwide.
Focus on sustainability and recyclable materials gaining importance in tool manufacturing processes
Sustainability drives innovation in modern hand tool production. Manufacturers adopt recyclable and eco-friendly materials for handles and packaging. The Hitter Based Hand Tools Market adapts to regulations promoting green manufacturing. It is aligned with consumer preference for environmentally conscious products. Supply chains increasingly incorporate waste reduction measures. Firms emphasize reusable packaging and resource efficiency. Branding efforts highlight eco-friendly tool certifications. Sustainable practices enhance brand reputation and competitive positioning in global markets.
Collaborations and strategic partnerships enhancing product reach in global and regional markets
Strategic partnerships are reshaping distribution and product development strategies. Global firms collaborate with regional retailers to strengthen presence. The Hitter Based Hand Tools Market gains exposure through joint ventures and licensing deals. It is benefiting from partnerships that expand product customization for local markets. Co-branding initiatives increase recognition and sales momentum. Professional training workshops by manufacturers promote correct tool usage. Collaborations with e-commerce giants drive targeted promotions. Partnerships secure market resilience and position brands competitively across industries.
- For example, Milwaukee Tool supported over 500 trade apprentice graduations nationwide in 2024 and contributed more than 1,000 hours to training apprentices at U.S. centers. The company also donated over USD 4 million in power tools, hand tools, and job-site accessories to vocational schools and apprenticeship programs, through its partnership with Bring Back the Trades.
Market Challenges Analysis:
Rising competition and price pressures limiting profit margins for tool manufacturers
The industry faces mounting competition from global and regional players. Large firms offer established reputations while smaller firms compete on price. The Hitter Based Hand Tools Market is under pressure to balance quality with affordability. It is challenged by low-cost imports that undercut branded products. Price-sensitive consumers in emerging regions often prefer cheaper substitutes. Manufacturers must absorb raw material price fluctuations to remain competitive. Marketing and distribution costs further squeeze profitability margins. Sustaining revenue growth in such an environment demands strong brand differentiation.
Technological adoption gaps and counterfeit product risks affecting long-term growth
Technology adoption varies across manufacturers, creating performance gaps in the industry. Companies without innovation pipelines risk losing relevance in competitive markets. The Hitter Based Hand Tools Market is vulnerable to counterfeit products that erode consumer trust. It is also impacted by inconsistent global standards for product quality. Counterfeit tools reduce safety and performance, discouraging repeat purchases. Smaller firms face hurdles in implementing automation for efficiency gains. Global supply chain disruptions create delays in raw material sourcing. Long-term resilience depends on addressing these operational and regulatory risks effectively.
Market Opportunities:
Emerging economies and urban infrastructure expansion generating new growth potential for hand tools
Rapid industrialization in Asia-Pacific, Africa, and Latin America presents strong growth prospects. Governments invest in housing and urban development projects to meet rising demand. The Hitter Based Hand Tools Market benefits from increased construction and renovation work. It is well-positioned to expand distribution in these emerging regions. Demand for affordable yet durable tools ensures high market penetration. Retail and wholesale networks expand rapidly across developing economies. Infrastructure-focused policies accelerate tool adoption. Urbanization ensures recurring demand across multiple consumer and professional categories.
Product diversification and advanced materials creating scope for premium tool segments
Manufacturers explore new opportunities through advanced materials and product innovation. Lightweight alloys and reinforced composites improve tool strength and lifespan. The Hitter Based Hand Tools Market leverages innovation to create premium segments. It is seeing strong interest from professionals seeking high-performance, specialized tools. Diversified product portfolios capture both entry-level and premium buyers. Innovative handle designs and safety features enhance user appeal. Targeted R&D investment drives continual product evolution. This path ensures consistent market opportunities for manufacturers across global and regional levels.
Market Segmentation Analysis:
The Hitter Based Hand Tools Market is segmented
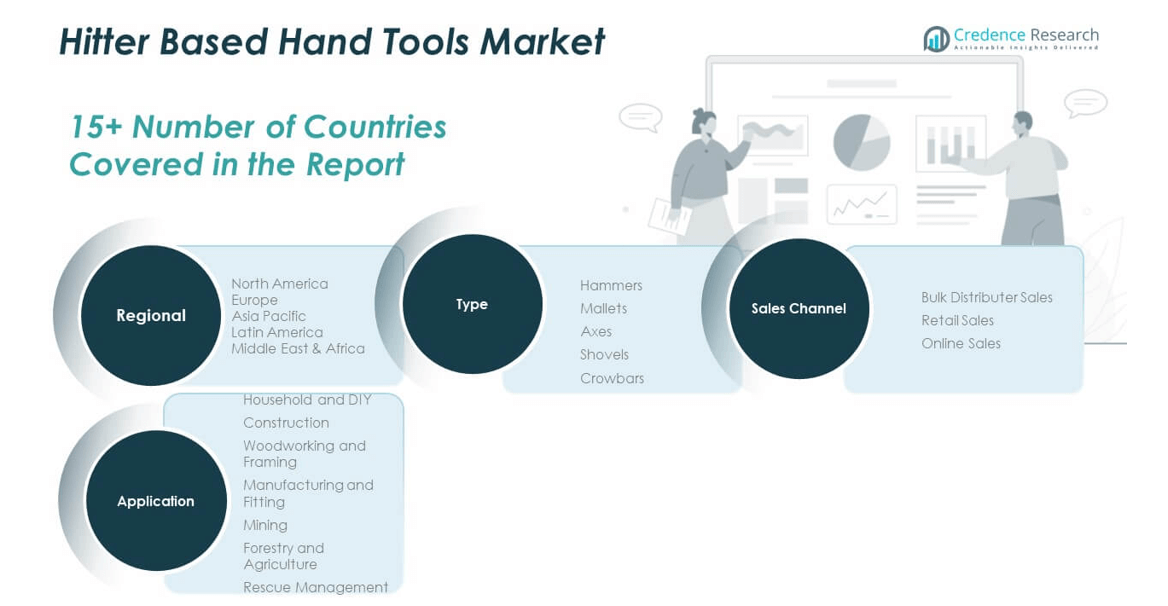
By type into hammers, mallets, axes, shovels, and crowbars. Hammers dominate due to their wide utility in construction, woodworking, and household tasks. Mallets support woodworking and delicate applications, while axes and shovels remain essential in forestry, agriculture, and outdoor activities. Crowbars serve heavy-duty applications in demolition and rescue operations, driving demand from industrial and emergency service sectors. Each type addresses distinct end-user needs, ensuring balanced demand across both professional and domestic markets.
- For example, Fiskars is recognized for its X-series axes, which are designed for forestry, agriculture, and outdoor activities. The brand consistently features in forestry and outdoor use-product rankings and its axes are engineered for chopping efficiency and durability, widely adopted in global forestry and rural tool sets.
By application, the market is divided into household and DIY, construction, woodworking and framing, manufacturing and fitting, mining, forestry and agriculture, and rescue management. Construction holds the largest share, supported by global infrastructure growth. Household and DIY activities contribute strongly with rising consumer interest in home projects. Mining and forestry require specialized heavy-duty tools, while rescue management increasingly relies on durable hitter-based tools for emergency response. It is well-diversified across multiple sectors, providing resilience against demand fluctuations.
- For example, AMES shovels are widely used in agriculture for planting, debris removal, and soil management. The Jackson Professional Tools line by AMES includes a forest fire shovel with a 41-inch hardwood handle and steel blade, designed for ditch work and debris removal in forestry and agricultural applications.
By sales channel, the market includes bulk distributor sales, retail sales, and online sales. Bulk distributors remain critical for professional and industrial buyers, offering volume-based supply. Retail sales drive adoption among households and small businesses through hardware stores and specialty outlets. Online sales continue to expand rapidly, driven by convenience, broad product availability, and competitive pricing. Each channel supports distinct buyer segments, and manufacturers balance distribution strategies to maximize market penetration. This multi-channel structure strengthens accessibility across developed and emerging regions.
Segmentation:
By Type
- Hammers
- Mallets
- Axes
- Shovels
- Crowbars
By Application
- Household and DIY
- Construction
- Woodworking and Framing
- Manufacturing and Fitting
- Mining
- Forestry and Agriculture
- Rescue Management
By Sales Channel
- Bulk Distributor Sales
- Retail Sales
- Online Sales
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Hitter Based Hand Tools Market size was valued at USD 295.6 million in 2018 to USD 314.4 million in 2024 and is anticipated to reach USD 417.4 million by 2032, at a CAGR of 3.7% during the forecast period. North America represents 26.4% of the global market share in 2024. Strong construction activity, DIY culture, and robust automotive maintenance demand drive steady consumption. The U.S. leads the region with widespread adoption across both residential and commercial sectors. Canada contributes with rising renovation projects, while Mexico supports growth through infrastructure expansion. It benefits from well-established retail and distribution networks. Professional users continue to demand high-performance tools, ensuring steady revenue streams. Growth is supported by leading manufacturers headquartered in the region, enabling strong competitive positioning.
Europe
The Europe Hitter Based Hand Tools Market size was valued at USD 257.5 million in 2018 to USD 266.4 million in 2024 and is anticipated to reach USD 332.1 million by 2032, at a CAGR of 2.9% during the forecast period. Europe holds a 22.4% share of the global market in 2024. Demand is fueled by industrial applications, construction projects, and woodworking traditions. Germany leads the market with manufacturing strength, while France and the UK contribute through infrastructure and renovation activity. Southern Europe adds demand from agriculture and small-scale construction. It benefits from strong consumer preference for durable, branded tools. Regulations on quality and safety ensure product consistency across the region. DIY popularity in Western Europe further sustains retail sales. Stable demand across applications reinforces Europe’s position as a key regional contributor.
Asia Pacific
The Asia Pacific Hitter Based Hand Tools Market size was valued at USD 404.8 million in 2018 to USD 450.7 million in 2024 and is anticipated to reach USD 640.1 million by 2032, at a CAGR of 4.5% during the forecast period. Asia Pacific dominates with 37.9% of the global share in 2024. Strong urbanization and industrial growth drive the region’s leadership. China leads with large-scale construction and manufacturing, while India grows with infrastructure and DIY adoption. Japan and South Korea support demand through advanced manufacturing hubs. Southeast Asia and Australia expand consumption with mining and forestry applications. It benefits from rising middle-class expenditure on home improvement tools. Regional growth is enhanced by expanding online sales networks. Asia Pacific remains the fastest-growing region, securing long-term momentum.
Latin America
The Latin America Hitter Based Hand Tools Market size was valued at USD 69.5 million in 2018 to USD 74.5 million in 2024 and is anticipated to reach USD 91.9 million by 2032, at a CAGR of 2.8% during the forecast period. Latin America holds a 6.3% share of the global market in 2024. Brazil dominates with construction and agricultural activities fueling demand. Argentina adds consumption from industrial and residential applications. It benefits from expanding retail distribution across urban centers. Local manufacturers cater to cost-sensitive buyers, while imports serve premium demand. Construction projects and government investments in infrastructure support growth. DIY adoption remains lower compared to developed regions, limiting retail expansion. Regional growth is steady but dependent on economic stability.
Middle East
The Middle East Hitter Based Hand Tools Market size was valued at USD 45.1 million in 2018 to USD 45.9 million in 2024 and is anticipated to reach USD 55.6 million by 2032, at a CAGR of 2.5% during the forecast period. The Middle East contributes 3.9% of the global share in 2024. Growth is supported by large construction projects in GCC countries. Demand also arises from oil and gas-related maintenance activities. Israel and Turkey expand adoption with industrial sectors. It benefits from bulk distributor networks catering to large-scale projects. DIY adoption remains limited but is gradually increasing. Retail channels are expanding in urban areas with growing consumer awareness. Regional demand aligns closely with infrastructure investments and government-funded projects.
Africa
The Africa Hitter Based Hand Tools Market size was valued at USD 27.5 million in 2018 to USD 37.8 million in 2024 and is anticipated to reach USD 45.6 million by 2032, at a CAGR of 2.1% during the forecast period. Africa accounts for 3.2% of the global share in 2024. South Africa leads with industrial, mining, and construction activities driving demand. Egypt contributes with strong government-backed infrastructure projects. It benefits from agricultural requirements across rural economies. DIY adoption remains at early stages but shows promise in urban centers. Distribution networks are gradually expanding to support accessibility. Price-sensitive markets prefer cost-effective tools, challenging premium product penetration. Growth is steady but constrained by economic and logistical challenges.
Key Player Analysis:
- Techtronic Industries Co. Ltd.
- Stanley Black & Decker, Inc.
- Snap-On Incorporated
- Apex Tool Group LLC
- E.P. Co., Inc.
- Vaughan Manufacturing
- The Ames Companies, Inc.
- ABC Hammers
- Hardcore Hammers
- Isotools
- Besdrill Machinery
- ABS Utensili S.r.l.
- Hitter Inc.
Competitive Analysis:
The Hitter Based Hand Tools Market features a competitive landscape led by global and regional manufacturers. Key players such as Stanley Black & Decker, Snap-On Incorporated, Techtronic Industries, and Apex Tool Group dominate with strong brand portfolios, broad distribution networks, and continuous product innovation. It is shaped by mid-sized companies like Vaughan Manufacturing, The Ames Companies, and Q.E.P. Co., which focus on specialized segments and niche applications. Emerging firms such as Hardcore Hammers and ABC Hammers compete by offering durable, ergonomic designs targeted at professionals and DIY users. Competitive dynamics are influenced by pricing strategies, product differentiation, and regional expansion. E-commerce platforms strengthen visibility and allow smaller players to capture market share. Partnerships, mergers, and acquisitions remain central strategies to expand global reach and enhance product offerings. The market is defined by the balance between established brands securing premium positioning and smaller firms targeting cost-sensitive buyers.
Recent Developments:
- In March 2024, Stanley Black & Decker completed the divestiture of its STANLEY Infrastructure business segment to Epiroc in a strategic acquisition valued at $760 million. This sale transferred key hand tool and attachment brands such as LaBounty and Paladin, strengthening Epiroc's infrastructure and construction portfolio.
- In February 2025, CRAFTSMAN received two Popular Mechanics 2025 Tool Awards, including recognition for new hand tools designed for both DIYers and professionals. This accolade points to CRAFTSMAN’s ongoing product development and recent launches in the market, particularly in hitter-based hand tools that combine ergonomic features with improved durability.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing construction activities worldwide will sustain steady demand for hitter-based tools.
- DIY adoption will expand household usage, supported by urban consumers seeking affordable toolkits.
- Industrial maintenance and automotive repair will remain key sectors driving recurring purchases.
- Product innovation in ergonomic designs and durable materials will strengthen professional adoption.
- Online sales channels will gain prominence, offering wider accessibility and competitive pricing.
- Emerging economies will provide growth momentum through rapid urbanization and infrastructure investment.
- Sustainability initiatives will encourage manufacturers to adopt recyclable materials and eco-friendly packaging.
- Partnerships and acquisitions will reshape competition, expanding global reach and product diversity.
- Training programs and awareness campaigns will promote safe tool usage among new users.
- Technological integration in supply chains will enhance efficiency, distribution, and market responsiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hitter Based Hand Tools market?
What factors are driving the growth of the Hitter Based Hand Tools market?
Who are the major players in the Hitter Based Hand Tools market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hitter Based Hand Tools Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hitter Based Hand Tools Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,189.8 million → 2032: USD 1,582.7 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hitter Based Hand Tools Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hitter Based Hand Tools Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hitter Based Hand Tools Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hitter Based Hand Tools Market Drivers
- 3.3 Hitter Based Hand Tools Market Restraints & Challenges
- 3.4 Hitter Based Hand Tools Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hitter Based Hand Tools Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hitter Based Hand Tools Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hitter Based Hand Tools category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hitter Based Hand Tools Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Hitter Based Hand Tools Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Hitter Based Hand Tools. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hitter Based Hand Tools Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hitter Based Hand Tools Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Hitter Based Hand Tools Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hitter Based Hand Tools (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Hitter Based Hand Tools
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hitter Based Hand Tools Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Hitter Based Hand Tools Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hitter Based Hand Tools Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hitter Based Hand Tools Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hitter Based Hand Tools Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hitter Based Hand Tools Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hitter Based Hand Tools Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hitter Based Hand Tools Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
