
Human Nutrition Market Overview:
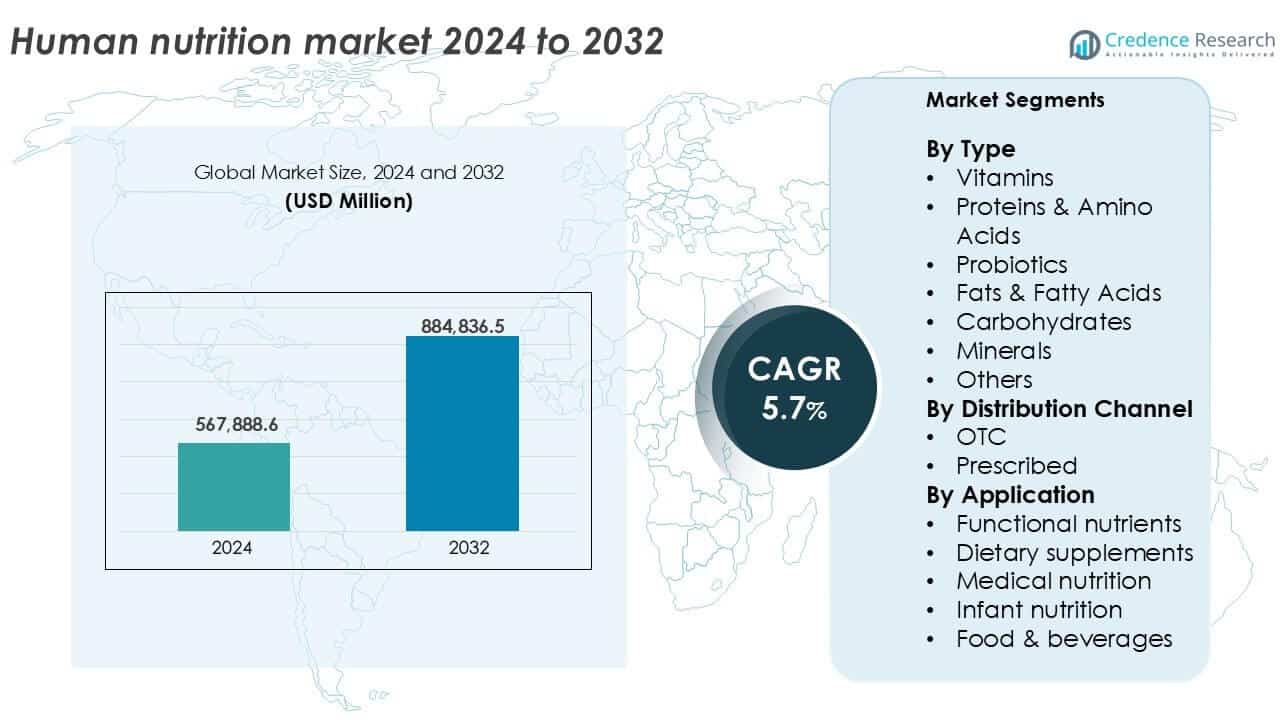
The Human Nutrition Market size was valued at USD 567,888.6 million in 2024 and is anticipated to reach USD 884,836.5 million by 2032, at a CAGR of 5.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Human Nutrition Market Size 2024 | USD 567,888.6 million |
| Human Nutrition Market , CAGR | 5.7% |
| Human Nutrition Market Size 2032 | USD 884,836.5 million |
Top players in the Human Nutrition Market include Nestlé S.A., ADM, Kerry Group PLC, Bayer Health Care AG, and Glanbia PLC. These companies lead through diverse product portfolios, global distribution networks, and continuous investment in innovation. Nestlé dominates in infant and medical nutrition, while ADM and Kerry focus on functional ingredients and personalized nutrition. Bayer and Glanbia strengthen their positions in dietary supplements and wellness solutions. North America leads the market with a 32% share, driven by high health awareness and strong supplement adoption. Europe follows with 27% due to structured regulations and an aging population, while Asia Pacific shows the fastest growth, supported by rising income levels, urbanization, and preventive health demand.
Human Nutrition Market Insights
- The Human Nutrition Market was valued at USD 567,888.6 million in 2024 and is projected to reach USD 884,836.5 million by 2032, growing at a CAGR of 5.7% during the forecast period.
- Rising consumer focus on preventive health and immunity-boosting products is driving strong demand for vitamins, proteins, and functional supplements globally.
- Clean-label, plant-based, and personalized nutrition products are gaining traction, supported by digital health platforms and e-commerce expansion.
- Key players such as Nestlé, ADM, Kerry Group, and Bayer dominate the competitive landscape with diverse portfolios and global reach, while regulatory complexity and product skepticism pose barriers in some markets.
- North America holds the largest regional share at 32%, followed by Europe at 27% and Asia Pacific at 22%, while dietary supplements remain the dominant application segment, and OTC channels lead distribution due to easy accessibility and self-medication trends.
Human Nutrition Market Segmentation Analysis:
By Type
Vitamins held the largest market share in the Human Nutrition Market under the type segment. Their dominance stems from high consumer awareness, preventive healthcare trends, and broad applications across all age groups. Rising demand for immunity-boosting products has further fueled vitamin intake, especially post-pandemic. Proteins & amino acids follow closely due to increasing fitness culture and senior population protein needs. Probiotics are gaining traction due to digestive health awareness. Fats, carbohydrates, and minerals maintain steady demand driven by balanced nutrition goals. The “Others” category includes emerging compounds like botanicals and fibers, contributing modestly to segment expansion.
- For instance, in 2011, Amway's Nutrilite brand of vitamins and dietary supplements led company sales, totaling nearly $4.7 billion. By 2014, it continued to be recognized by Euromonitor International as the world's No. 1 selling brand in its category.
By Distribution Channel
The OTC segment dominated the distribution channel category, supported by growing self-medication practices and accessibility through retail and online platforms. Consumers prefer OTC products for dietary supplements and vitamins due to ease of availability and minimal regulatory barriers. Pharmacies, supermarkets, and e-commerce channels have enhanced consumer reach. The prescribed segment remains strong in clinical nutrition areas, particularly for medical and infant nutrition. Physician-directed purchases maintain trust for therapeutic formulations. However, digital health platforms are gradually shifting consumer reliance toward OTC and DTC models, especially in urban markets.
- For instance, Haleon plc owner of Centrum vitamins reported £11.23 billion in revenue in 2024, with OTC nutritional products as a key portfolio driver.
By Application
Dietary supplements emerged as the leading application, holding the largest market share due to broad consumer adoption for wellness, immunity, and sports nutrition. This segment benefits from rising lifestyle diseases and preventive health consciousness. Functional nutrients rank second, driven by inclusion in daily food products like fortified cereals and beverages. Medical nutrition shows significant potential due to aging populations and chronic disease prevalence. Infant nutrition remains essential, supported by demand for formula and fortified baby food. Food & beverages represent a growing segment, as brands integrate health-oriented ingredients into mainstream products to meet clean label trends.
Human Nutrition Market Key Growth Drivers
Rising Health Awareness and Preventive Healthcare Focus
Global consumers are increasingly focused on long-term wellness and disease prevention, driving demand in the human nutrition market. Awareness campaigns, lifestyle changes, and post-pandemic health priorities have pushed people to proactively manage their diets and supplement intake. This shift fuels purchases of vitamins, minerals, proteins, and functional nutrients across age groups. Preventive healthcare also receives policy-level support in many countries, strengthening consumer education and access to nutritional products. Growing interest in immunity, gut health, and energy metabolism further accelerates market expansion. Brands respond with tailored product lines targeting specific deficiencies, age brackets, and conditions, reinforcing preventive care adoption.
- For instance, demand for vitamins, minerals, and dietary supplements has grown as consumers proactively manage diets to support immunity and energy metabolism.
Expanding Aging Population and Chronic Disease Prevalence
The growing elderly population significantly boosts demand for targeted nutritional solutions. Aging increases susceptibility to chronic illnesses, such as osteoporosis, cardiovascular diseases, and diabetes, requiring specialized diets and supplementation. Medical nutrition and prescribed products gain traction as seniors require easy-to-absorb, nutrient-dense formulations. The rise in chronic health conditions among younger adults also contributes to consistent product use. Hospitals and long-term care facilities increase reliance on human nutrition products to support patient recovery and reduce hospital stays. This demographic shift enhances the market scope for therapeutic nutrition, especially in developed economies with aging populations.
- For instance, older adults often require nutrient‑dense and easy‑to‑absorb supplementation to support digestive health and reduce deficiency risk as absorption declines with age.
Innovation in Product Formats and Personalized Nutrition
Advances in biotechnology, AI, and food science are enabling highly customized nutritional solutions. Companies now offer DNA-based dietary plans and microbiome-specific probiotics. Personalized nutrition appeals to consumers seeking optimal health and performance, strengthening loyalty and product differentiation. Innovations in delivery formats such as gummies, powders, liquid sachets, and functional snacks enhance user convenience and compliance. Startups and established players invest in R&D to launch clean-label, allergen-free, and plant-based alternatives catering to diverse consumer needs. This technology-driven approach improves user engagement and expands addressable markets across lifestyle categories like fitness, aging, and cognitive health.
Human Nutrition Market Key Trends & Opportunities
Digital Health Platforms Fueling Supplement Adoption
The rise of telehealth, mobile wellness apps, and online diagnostics supports the growth of the human nutrition market. Consumers now access personalized nutrition advice, product recommendations, and automated supplement subscriptions without visiting clinics. Digital engagement drives data-backed decisions, improving adherence and encouraging experimentation with newer products. E-commerce platforms further support this trend with bundled health kits, easy reordering, and subscription models. Companies integrating digital tools into their product ecosystem see higher user retention. This digital transformation offers a strong opportunity to expand reach, especially in younger, tech-savvy demographics who value on-demand wellness services.
- For instance, Hims & Hers Health Inc. recorded over 1.43 million subscriptions in Q3 2023, driven by digital health consultations and automated supplement fulfillment.
Clean Label and Plant-Based Nutrition Demand
Consumers increasingly prefer natural, sustainably sourced, and minimally processed nutrition products. This clean-label trend is reshaping ingredient sourcing and product formulation strategies. Plant-based nutrition is particularly in demand among vegans, vegetarians, and flexitarians, pushing manufacturers to replace synthetic additives with organic, recognizable ingredients. Regulatory bodies also encourage transparency in labeling and allergen disclosures. As a result, companies invest in botanical extracts, fermented plant proteins, and bioavailable mineral blends. This shift presents an opportunity for brands to align with ethical consumption trends, enhance brand trust, and differentiate in a competitive market landscape.
Human Nutrition Market Key Challenges
Regulatory Variability and Product Classification Issues
Global differences in product labeling, health claims, and supplement classification present challenges for manufacturers. A product considered OTC in one country may require prescription or face restrictions in another. Frequent updates in food safety laws, such as limits on certain additives or contaminants, increase compliance burden. Unclear classification between food, drug, and supplement categories also leads to legal risks and approval delays. These regulatory inconsistencies hinder fast international expansion and raise product launch costs. Companies must invest in localized compliance teams and maintain adaptive labeling practices, which can delay time-to-market and reduce profit margins.
Consumer Skepticism and Product Efficacy Concerns
Despite rising interest in nutrition, some consumers remain skeptical about supplement quality and claimed benefits. Poorly regulated markets, misleading advertisements, and adulterated products have undermined trust in some regions. Lack of visible results or scientific backing can discourage continued usage. This skepticism especially affects newer categories like nootropics and probiotics, where clinical validation is limited. Brands must invest in transparency, third-party testing, and science-based marketing to build long-term credibility. Educating consumers on usage timelines, dosage accuracy, and realistic benefits becomes critical in addressing hesitation and driving sustained market growth.
Human Nutrition Market Regional Analysis
North America
North America accounted for over 32% of the global human nutrition market share in 2024, driven by high health awareness, advanced healthcare systems, and wide supplement adoption. The U.S. leads with strong demand for vitamins, proteins, and medical nutrition products, especially among aging adults and fitness-focused consumers. Rising chronic disease prevalence supports sustained intake of functional foods and personalized nutrition. E-commerce penetration and DTC brands boost market accessibility. Canada follows with strong regulatory frameworks and growing plant-based supplement demand. The region benefits from established retail networks, ongoing innovation, and expanding digital health platforms for nutritional engagement.
Europe Europe held approximately 27% of the global market share, supported by strong regulatory policies and widespread consumer adoption of dietary supplements. Germany, the UK, and France lead the region, with demand concentrated around vitamins, minerals, and probiotics. The aging population, especially in Western Europe, fuels growth in medical nutrition and prescribed products. Clean-label and organic formulations gain traction, supported by EU-wide regulations encouraging transparency and quality. Eastern European countries show rising interest in functional food and wellness products, aided by improving income levels. Europe’s structured regulatory landscape ensures high product quality and sustained consumer trust.
Asia Pacific
Asia Pacific captured around 22% of the human nutrition market in 2024 and is expected to grow at the fastest pace through 2032. Rapid urbanization, rising disposable incomes, and growing awareness of preventive healthcare drive demand. China and India are key markets, with increasing adoption of dietary supplements among the middle class. Japan and South Korea show high demand for functional foods and aging-related nutrition. Regional governments promote fortified food programs to address micronutrient deficiencies. E-commerce expansion and digital health platforms accelerate access, while local manufacturers innovate with herbal and traditional medicine-based nutrition solutions.
Latin America
Latin America held about 9% of the global human nutrition market share, led by Brazil and Mexico. The region’s market is driven by growing interest in wellness, immune health, and weight management. Rising middle-class income and urban living patterns promote the adoption of functional foods and supplements. Demand for vitamins and proteins is increasing, especially through OTC channels. However, limited regulatory harmonization across countries poses challenges for cross-border distribution. Despite this, local players and international brands are expanding through retail chains and e-commerce platforms, capitalizing on the region’s improving consumer awareness and product accessibility.
Middle East & Africa
The Middle East & Africa accounted for approximately 6% of the global market share in 2024. Growth in this region is supported by rising investments in healthcare infrastructure, improving nutrition education, and increasing chronic disease burden. The Gulf Cooperation Council (GCC) countries lead, with growing demand for vitamins, fortified foods, and sports nutrition products. In Africa, malnutrition-focused public health programs and fortified staple food initiatives boost demand for essential nutrients. Market growth remains uneven due to income disparities and limited product access in rural areas. International players are expanding partnerships with local distributors to improve market reach.
Human Nutrition Market Segmentations:
By Type
- Vitamins
- Proteins & Amino Acids
- Probiotics
- Fats & Fatty Acids
- Carbohydrates
- Minerals
- Others
By Distribution Channel
- OTC
- Prescribed
By Application
- Functional nutrients
- Dietary supplements
- Medical nutrition
- Infant nutrition
- Food & beverages
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Human Nutrition Market features a mix of global food, pharmaceutical, and specialty ingredient companies competing across product categories and regions. Leading players like Nestlé S.A., ADM, and Kerry Group PLC focus on broad product portfolios, clinical research, and fortified foods to strengthen market positions. Firms such as USANA Health Science, Amway Corp., and Pharmavite LLC emphasize branded supplements and direct-to-consumer models. Companies like Bayer Health Care AG and Glanbia PLC invest in innovation, functional nutrition, and personalized health solutions. Strategic partnerships, acquisitions, and regional expansions remain common growth strategies. For instance, ADM continues expanding its health and wellness division through targeted acquisitions in probiotics and plant-based proteins. Product differentiation through clean-label ingredients, science-backed efficacy, and digital health integration shapes competitive edge. The market remains fragmented in emerging regions, offering scope for local players and startups to scale. Regulatory compliance and transparency are key for maintaining consumer trust and gaining long-term competitive advantage.
Key Player Analysis
- ADM
- Amway Corp.
- Bayer Health Care AG
- Corbion N.V.
- Glanbia PLC
- Hansen Holding A/S
- Kerry Group PLC
- Nestlé S.A.
- Pharmavite LLC
- USANA Health Science, Inc.
Recent Developments
- In April 2023, the premium health and wellness division of the UK's Genetic Nutrition brand began operations in India. Sandesh Prasannakumar, an international superbike racer, founded the company which offers Indians the best dietary supplements. The company's selection of nutritional supplements includes amino acids, protein powders, and vitamins made with top-notch components for optimal potency. The health and wellness category includes supplements that assist digestive health, joint health, functioning of the immune system, and other conditions. Genetic nutrition's dedication to openness and quality control makes them unique from other dietary supplement companies. Every supplement batch from this company is subjected to independent lab testing to confirm purity, potency, and correctness. This provides customers with peace of mind that they are receiving only the ingredients mentioned on the label and nothing hazardous or unnecessary.
- In Feb 2023, Nestle launched a multitude of NPD related to wellness, health, and nutrition in response to the rising demand for immunity-boosting foods and plant-based substitutes. Vital Proteins Daily Greens is one of the new items. It is packed with research-backed probiotics, nutrient-dense superfoods, and broad-spectrum antioxidants. The Plant Protein + Collagen Powder from Orgain, a protein powder business that Nestle just purchased, was unveiled. It is constructed of plant protein and peptides from bovine collagen and promotes the health of the intestines, hair, skin, and nails. Nestle is addressing the increasing need for alternative plant-based protein options by promoting its plant-based brand Sweet Earth.
- In January 2023, at an event attended by scientific council members from fit council, Superfoods Valley, a nutrition and food technology firm headquartered in Bangalore, unveiled its flagship product, Good Monk, a unique nutrition mix. The company also announced an innovative app that aids in user education and fosters transparency regarding the nutritional content of our food. Good Monk is a unique blend of incredibly bio-available nutrients, including Lysine (a protein building block), 130 Cr. Probiotics & Fiber, Vit A, C, and D, vitamins B6, B9, B12, Zinc, Iron, Brahmi, and Ashwagandha. The effectiveness of 13 Nutri-Herbs promotes intestinal health, immunity, vitality, and mental development. Mothers may easily add nutrition to food because of the product's No COT feature.
Report Coverage
The research report offers an in-depth analysis based on Type, Distribution Channel, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for personalized nutrition products will rise with advancements in genomics and diagnostics.
- Plant-based and clean-label formulations will gain stronger consumer preference across all age groups.
- E-commerce and direct-to-consumer models will drive supplement accessibility and market penetration.
- Aging populations will boost demand for medical and senior-focused nutritional products.
- Functional beverages and fortified foods will expand as convenient health solutions.
- Companies will invest more in clinical validation to build product credibility and trust.
- Strategic partnerships and M&A activity will increase to strengthen portfolios and reach.
- Regulatory harmonization will become critical for global product expansion and labeling.
- Digital health platforms will integrate with nutrition brands to offer data-driven recommendations.
- Emerging markets in Asia and Latin America will offer high growth due to rising awareness and income levels.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Human Nutrition Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Human Nutrition Market projected to grow between 2024 and 2032?
Which Human Nutrition Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Human Nutrition Market?
Who are the leading companies in the Human Nutrition Market?
Which region commanded the largest share of the Human Nutrition Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 567,888.6 million → 2032: USD 884,836.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Human Nutrition Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Human Nutrition Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Human Nutrition Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Human Nutrition Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Human Nutrition Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Human Nutrition Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Human Nutrition Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Human Nutrition Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 567,888.6 million → 2032: USD 884,836.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Human Nutrition Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Human Nutrition Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Human Nutrition Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Human Nutrition Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

