
Market Overview:
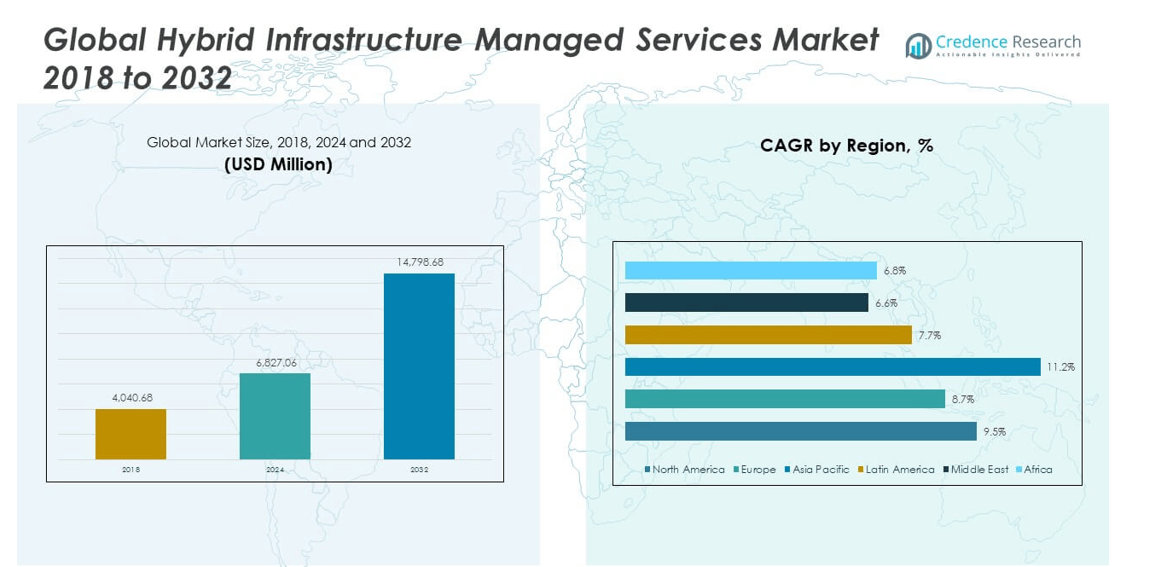
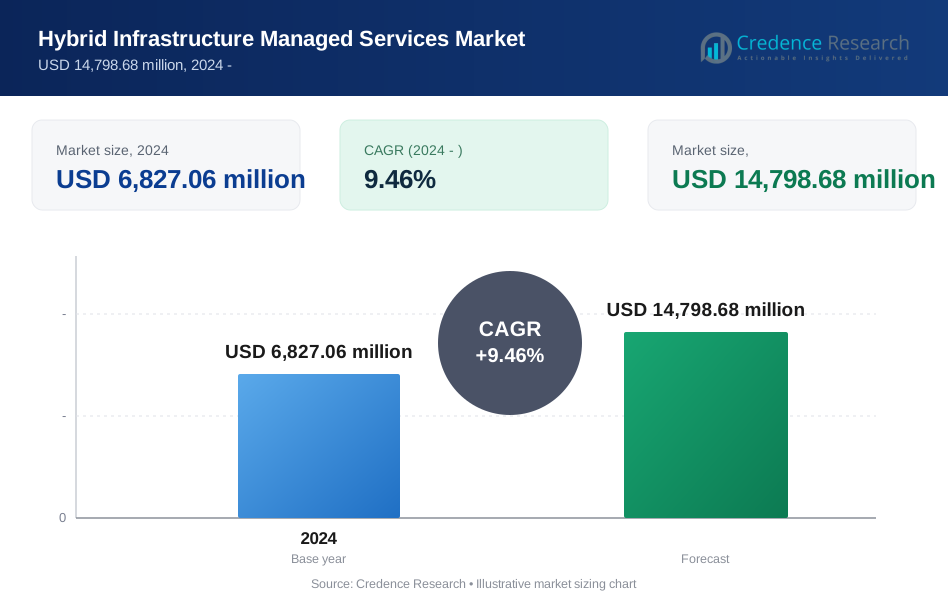
The Global Hybrid Infrastructure Managed Services Market size was valued at USD 4,040.68 million in 2018 to USD 6,827.06 million in 2024 and is anticipated to reach USD 14,798.68 million by 2032, at a CAGR of 9.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hybrid Infrastructure Managed Services Market Size 2024 | USD 6,827.06 million |
| Hybrid Infrastructure Managed Services Market, CAGR | 9.46% |
| Hybrid Infrastructure Managed Services Market Size 2032 | 14,798.68 million |
The market is driven by rising enterprise demand for secure, scalable, and flexible IT environments. Organizations invest in hybrid infrastructure services to balance cloud adoption with legacy system management while ensuring operational continuity. It supports business transformation by improving agility, enabling compliance, and optimizing costs. Service providers strengthen their offerings with AI-driven automation, cybersecurity frameworks, and multi-cloud orchestration. Enterprises adopt these solutions to manage complex infrastructure seamlessly, reduce downtime, and enhance digital capabilities across industries. The increasing focus on resilience and efficiency sustains strong growth momentum.
North America leads the Global Hybrid Infrastructure Managed Services Market due to advanced IT infrastructure, strong vendor presence, and early adoption of hybrid models. Europe follows with steady growth, supported by strict regulatory compliance and digital modernization initiatives. Asia Pacific emerges as the fastest-growing region, driven by rapid digitalization, expanding cloud adoption, and government-backed infrastructure programs in countries such as China, India, and Japan. Latin America shows rising adoption fueled by cost efficiency needs, while the Middle East and Africa record steady progress through smart city projects and enterprise modernization efforts.
Market Insights:
- The Global Hybrid Infrastructure Managed Services Market was valued at USD 4,040.68 million in 2018, reached USD 6,827.06 million in 2024, and is projected to achieve USD 14,798.68 million by 2032, growing at a CAGR of 9.46%.
- North America leads with 43.27% share in 2024, driven by advanced IT infrastructure and early adoption of hybrid models; Europe follows with 28.11% due to strict regulatory compliance, while Asia Pacific holds 19.95% supported by rapid digitalization.
- Asia Pacific is the fastest-growing region with 19.95% share in 2024, fueled by cloud adoption, digital ecosystems, and government-backed modernization initiatives in countries like China, India, and Japan.
- Cloud management services hold the largest segment share at 41% in 2024, reflecting enterprises’ preference for multi-cloud integration and scalable infrastructure.
- Security and compliance management accounts for 22% share in 2024, underscoring enterprise focus on regulatory alignment and protection in increasingly complex hybrid environments.
Market Drivers
Rising Demand For Optimized And Flexible Infrastructure Services Across Enterprises
The Global Hybrid Infrastructure Managed Services Market benefits from a surge in enterprise demand for optimized IT solutions that balance scalability and flexibility. Organizations adopt hybrid models to integrate legacy systems with cloud platforms and maintain seamless performance. This approach reduces complexity and allows businesses to address evolving workloads effectively. It also helps enterprises avoid high capital expenditure linked to infrastructure ownership. Service providers offer expertise in managing diverse IT environments, creating long-term client reliance. Enterprises gain predictable cost structures and enhanced operational efficiency. Hybrid solutions also support continuous operations across distributed locations. The market benefits from enterprises pursuing agility while keeping costs in check.
Growing Need For Enhanced Security And Compliance In Multi-Cloud Environments
The market growth is influenced by the critical need for stronger security and regulatory compliance within multi-cloud operations. Enterprises face increasing cyber threats, requiring advanced managed services to secure data and applications. Hybrid infrastructure services ensure compliance with industry regulations while protecting sensitive information. It supports encrypted data transfers and automated monitoring, reducing risks from breaches. Managed service providers deliver specialized security tools that many organizations cannot develop internally. Clients receive regular audits, reporting, and compliance updates tailored to their sector. Financial, healthcare, and government sectors especially rely on such support. The Global Hybrid Infrastructure Managed Services Market gains traction as enterprises prioritize secure, compliant infrastructure.
- For example, in February 2025, Microsoft announced that Defender for Cloud expanded support to over 30 security and regulatory compliance frameworks across Azure, AWS, and Google Cloud, offering enhanced multicloud compliance monitoring and reporting.
Rapid Digital Transformation Initiatives Across Industries Worldwide
Enterprises across multiple industries prioritize digital transformation, driving adoption of hybrid managed services. Businesses pursue modernization projects to enhance competitiveness, customer experience, and operational productivity. Hybrid solutions enable organizations to scale resources, align with digital strategies, and ensure performance reliability. The demand for automation, analytics, and smart tools increases reliance on service providers. It allows companies to integrate digital platforms quickly while avoiding service disruptions. Service providers support migration projects and minimize risks tied to transformation. Enterprises also value managed services for aligning technology with business objectives. The Global Hybrid Infrastructure Managed Services Market expands as transformation becomes a central business priority.
Rising Focus On Business Continuity And Resilience In A Dynamic Environment
Business continuity planning has become vital, creating a strong driver for hybrid infrastructure services. Enterprises seek robust systems capable of mitigating downtime and supporting disaster recovery. Hybrid models combine cloud flexibility with on-premises reliability, ensuring operational resilience. Managed service providers deliver high availability frameworks and backup solutions to support continuity. It allows enterprises to withstand unexpected disruptions while maintaining customer trust. Hybrid services also minimize risks linked to natural disasters, cyber incidents, or system failures. Organizations integrate proactive monitoring tools to detect issues before they escalate. The Global Hybrid Infrastructure Managed Services Market benefits from demand for resilience in unpredictable global conditions.
- For instance, in April 2023, Accenture and Microsoft completed the migration of Unilever’s entire global digital operations to the Microsoft Azure cloud, helping Unilever whose 400+ brands reach 3.4 billion people daily transition to a cloud-only enterprise. The migration, with minimal business disruption, has enabled Unilever to drive innovation, enhance operational resilience, and accelerate product delivery, as confirmed by joint Accenture/Microsoft press releases
Market Trends
Integration Of Artificial Intelligence And Automation In Hybrid Service Delivery
The Global Hybrid Infrastructure Managed Services Market is experiencing a shift toward AI and automation for service efficiency. Automation tools streamline workload management, reduce downtime, and support proactive monitoring. AI-driven insights help organizations optimize resource allocation across hybrid environments. It enables predictive maintenance, lowering system failure risks. Enterprises rely on AI for faster decision-making in complex IT operations. Service providers integrate chatbots and automated service desks to enhance client experience. Automation also reduces costs by minimizing repetitive manual tasks. The trend highlights a transition toward smarter, self-managed infrastructure models.
Expansion Of Industry-Specific Hybrid Infrastructure Solutions Globally
The market is witnessing increasing development of sector-focused hybrid services designed for healthcare, finance, and manufacturing. These industries require tailored compliance, security, and operational efficiency. Service providers create specialized offerings that address unique regulatory and technical demands. It strengthens adoption among enterprises seeking solutions aligned with business goals. Healthcare firms adopt hybrid services for data-intensive records and telemedicine platforms. Financial institutions rely on hybrid solutions for secure transactions and reporting. Manufacturing companies integrate hybrid services with IoT-driven operations. The Global Hybrid Infrastructure Managed Services Market grows as sector-based customization gains momentum.
- For instance, Siemens Energy implemented its Connected Factory Industrial IoT platform using AWS IoT managed services across 18 global factories, resulting in a 50% reduction in time spent on manual data collection, 25% lower operational maintenance costs, and a 15% increase in machine availability. This deployment is validated by official AWS case studies from September 2025.
Rising Popularity Of Hybrid Cloud Management Platforms Across Enterprises
Enterprises increasingly adopt advanced platforms to manage multi-cloud and on-premises systems within a single dashboard. These platforms provide visibility, monitoring, and orchestration tools for seamless control. It improves performance consistency and reduces the complexity of hybrid environments. Service providers introduce integrated dashboards that simplify multi-layered infrastructure management. Enterprises achieve operational transparency and optimize workload distribution. This trend allows businesses to address cost concerns while maintaining performance standards. The Global Hybrid Infrastructure Managed Services Market gains strength from demand for centralized management. The popularity of these platforms reflects growing enterprise expectations for unified solutions.
Increasing Collaborations Between Service Providers And Cloud Hyperscalers
Partnerships between managed service firms and hyperscale cloud providers represent a growing trend in this market. Such collaborations enhance service portfolios and strengthen global reach. It enables enterprises to access hybrid services with integrated hyperscaler support. Service providers partner with AWS, Microsoft Azure, and Google Cloud to expand client offerings. Enterprises gain multi-layered benefits, including migration support and application modernization. Partnerships also accelerate innovation through shared R&D and service integration. The Global Hybrid Infrastructure Managed Services Market advances as these alliances deliver broader solutions. This trend fosters growth by aligning enterprise demand with hyperscaler expertise.
- For instance, in November 2024, Kyndryl and Microsoft announced the launch of end-to-end services for mainframe application modernization with Microsoft Azure. These services are designed to accelerate AI-powered application migration and unlock generative AI capabilities for large enterprises, as reported in Kyndryl’s official press release and multiple news outlets.
Market Challenges Analysis
High Complexity In Managing Multi-Layered Hybrid Infrastructure Systems
Enterprises face a significant challenge in managing complex hybrid setups involving multiple clouds, legacy systems, and distributed data centers. The Global Hybrid Infrastructure Managed Services Market must address interoperability issues between diverse platforms. Organizations struggle with visibility and control across fragmented environments. It creates risks of inconsistent performance, higher costs, and service downtime. The complexity also raises the need for specialized expertise, which many firms lack internally. Service providers must invest in advanced monitoring and orchestration tools to solve these issues. Enterprises also demand customization, further complicating standardization efforts. Managing hybrid infrastructure at scale remains a persistent challenge.
Growing Concerns Related To Rising Costs And Resource Optimization
While hybrid managed services promise cost efficiency, many enterprises face challenges controlling operational expenses. Organizations often underestimate the hidden costs of multi-cloud adoption and complex contracts. The Global Hybrid Infrastructure Managed Services Market experiences hurdles when clients demand transparency in billing and ROI justification. It becomes difficult for providers to balance service quality with competitive pricing. Enterprises also face challenges in allocating resources effectively to avoid underutilization. Cost unpredictability reduces trust in providers and slows decision-making. It creates pressure on providers to offer flexible models without compromising profitability. Balancing service quality with financial efficiency remains a central market challenge.
Market Opportunities
Rising Adoption Of Emerging Technologies Creating New Service Possibilities
The Global Hybrid Infrastructure Managed Services Market benefits from opportunities created by AI, IoT, and 5G integration. These technologies demand flexible and secure infrastructure that hybrid services can provide. It enables enterprises to innovate while maintaining operational stability. Providers can expand service offerings to include edge computing and smart analytics. Growth in connected devices further drives demand for managed services tailored to real-time workloads. Enterprises seek providers capable of supporting these next-generation requirements. This opportunity positions managed services as strategic enablers of digital growth. Providers able to capture this shift gain long-term competitive advantage.
Expanding Demand In Emerging Markets With Strong Digital Growth Potential
Emerging economies present opportunities for providers to expand their hybrid infrastructure services. The Global Hybrid Infrastructure Managed Services Market benefits from governments and enterprises investing in digital transformation. It creates strong demand for hybrid solutions that balance scalability and cost control. Enterprises in these regions seek managed services to support modernization initiatives. Service providers can strengthen presence through localized offerings and strategic partnerships. Growing startup ecosystems further drive adoption of hybrid services for agility. It allows providers to capture new revenue streams from fast-developing economies. These opportunities highlight untapped potential across global digital markets.
Market Segmentation Analysis:
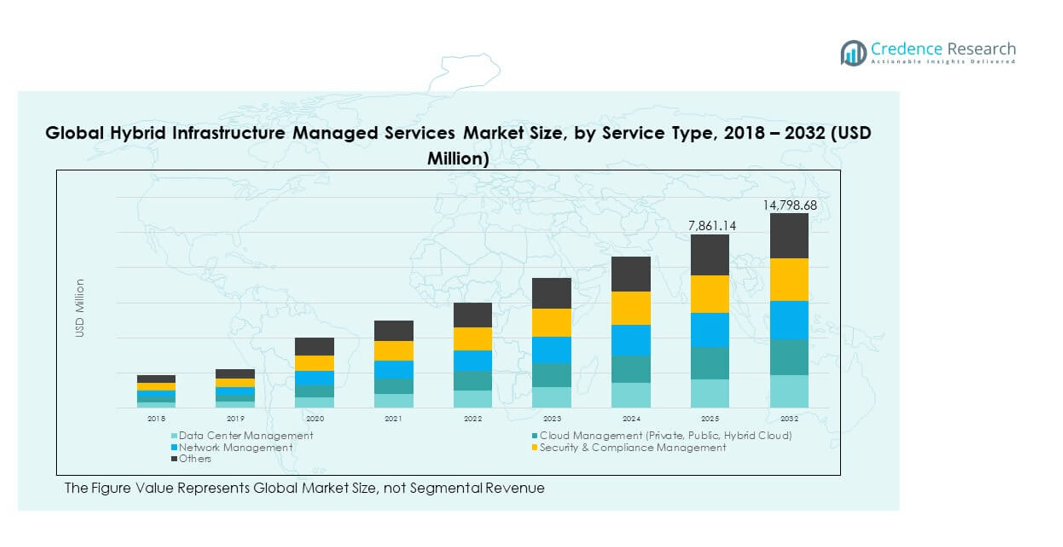
The Global Hybrid Infrastructure Managed Services Market is segmented by service type, deployment mode, and industry vertical.
By service type, cloud management dominates due to its central role in enterprise modernization, supporting integration across private, public, and hybrid environments. Data center management holds steady demand, driven by the need to optimize legacy systems and ensure continuity. Network management gains relevance with enterprises requiring reliable connectivity across distributed operations. Security and compliance management grows rapidly as organizations prioritize protection and regulatory alignment. Other service categories add niche value to specialized enterprise needs.
- For instance, according to the 2024 HashiCorp State of Cloud Strategy Survey, only 8% of nearly 1,200 global enterprises have achieved "high cloud maturity," and these organizations are 71% more likely to increase cloud spending and report stronger security outcomes due to advanced cloud management practices.
By deployment mode, cloud-based managed services lead adoption, reflecting enterprises’ preference for scalability and flexibility. Hosted managed services follow, serving organizations that require tailored infrastructure solutions. On-premises services maintain relevance among highly regulated sectors, where control and compliance outweigh cost concerns.
By industry vertical, IT and telecom represent the largest share, driven by reliance on hybrid infrastructure for service delivery. BFSI and healthcare adopt hybrid managed services to balance compliance with modernization. Retail, consumer goods, and manufacturing expand demand as digital ecosystems grow. It reflects a broadening application base across industries seeking resilience and agility.
- For instance, Cisco reports that global banks (including HSBC) have accelerated hybrid cloud deployments, integrating secure SD-WAN to enhance uptime and support compliance with international regulatory standards throughout 2024.
Segmentation:
By Service Type
- Data Center Management
- Cloud Management (Private, Public, Hybrid Cloud)
- Network Management
- Security & Compliance Management
- Others
By Deployment Mode
- On-Premises Managed Services
- Hosted Managed Services
- Cloud-Based Managed Services
By Industry Vertical
- IT & Telecom
- BFSI (Banking, Financial Services, Insurance)
- Healthcare
- Retail & Consumer Goods
- Manufacturing
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Hybrid Infrastructure Managed Services Market size was valued at USD 1,767.17 million in 2018 to USD 2,954.82 million in 2024 and is anticipated to reach USD 6,422.77 million by 2032, at a CAGR of 9.5% during the forecast period. North America holds a 43.27% share of the market in 2024. The region benefits from advanced IT infrastructure, strong demand for managed cloud, and early adoption of hybrid models by large enterprises. The United States dominates with widespread investments in data centers and digital transformation programs. Canada and Mexico contribute through government modernization projects and rising enterprise cloud adoption. Service providers in the region focus on cybersecurity, compliance, and integrated management platforms. It remains a key hub for innovation, driven by partnerships with hyperscale providers. The Global Hybrid Infrastructure Managed Services Market in this region continues to expand on the strength of enterprise readiness and regulatory maturity.
Europe
The Europe Global Hybrid Infrastructure Managed Services Market size was valued at USD 1,177.21 million in 2018 to USD 1,919.17 million in 2024 and is anticipated to reach USD 3,923.32 million by 2032, at a CAGR of 8.7% during the forecast period. Europe accounts for 28.11% share of the 2024 market. The region emphasizes compliance and data sovereignty regulations, which drive managed service adoption. Countries like Germany, France, and the UK invest heavily in hybrid infrastructure to meet enterprise modernization needs. Organizations prioritize managed services that align with GDPR and industry-specific standards. It enables firms to balance innovation with risk management. Cloud adoption accelerates across retail, healthcare, and BFSI, supporting hybrid demand. Regional service providers collaborate with global firms to deliver tailored offerings. The Global Hybrid Infrastructure Managed Services Market in Europe grows steadily on regulatory-driven modernization.
Asia Pacific
The Asia Pacific Global Hybrid Infrastructure Managed Services Market size was valued at USD 741.29 million in 2018 to USD 1,362.62 million in 2024 and is anticipated to reach USD 3,362.72 million by 2032, at a CAGR of 11.2% during the forecast period. Asia Pacific contributes a 19.95% share of the 2024 market. The region is the fastest-growing, fueled by rapid digitalization, cloud adoption, and expanding startup ecosystems. China, India, Japan, and South Korea lead investments in hybrid services to support enterprise agility. Service demand grows across telecom, manufacturing, and financial services. It is driven by cost optimization and the need for advanced security frameworks. Governments in the region encourage digital infrastructure upgrades, further fueling demand. Regional providers partner with global firms to expand managed service capacity. The Global Hybrid Infrastructure Managed Services Market in Asia Pacific shows strong momentum from enterprise modernization and public investments.
Latin America
The Latin America Global Hybrid Infrastructure Managed Services Market size was valued at USD 186.82 million in 2018 to USD 311.64 million in 2024 and is anticipated to reach USD 596.20 million by 2032, at a CAGR of 7.7% during the forecast period. Latin America holds a 4.56% share of the 2024 market. Brazil dominates with enterprise modernization and rising adoption of hybrid cloud solutions. Mexico and Argentina show steady growth supported by investments in IT outsourcing. Regional enterprises focus on cost efficiency and compliance with international data standards. It helps businesses manage complex infrastructure with limited internal expertise. Service providers emphasize scalable offerings and localized support. Cloud adoption is expanding across retail, healthcare, and financial services. The Global Hybrid Infrastructure Managed Services Market in Latin America is gaining pace through digital growth initiatives.
Middle East
The Middle East Global Hybrid Infrastructure Managed Services Market size was valued at USD 94.75 million in 2018 to USD 143.67 million in 2024 and is anticipated to reach USD 252.22 million by 2032, at a CAGR of 6.6% during the forecast period. The region represents 2.10% of the 2024 market. The market is driven by government digital initiatives, smart city projects, and enterprise adoption of hybrid cloud. Gulf countries lead with strong investments in digital infrastructure. Israel shows demand growth driven by technology innovation and cybersecurity solutions. It benefits from hybrid adoption across banking, telecom, and energy. Service providers collaborate with local governments to ensure compliance and security. Regional enterprises rely on managed services to reduce operational burdens and enhance resilience. The Global Hybrid Infrastructure Managed Services Market in the Middle East expands steadily, anchored by government-led innovation.
Africa
The Africa Global Hybrid Infrastructure Managed Services Market size was valued at USD 73.44 million in 2018 to USD 135.15 million in 2024 and is anticipated to reach USD 241.45 million by 2032, at a CAGR of 6.8% during the forecast period. Africa accounts for 1.98% of the 2024 market. South Africa leads adoption, supported by digital transformation across telecom and BFSI sectors. Egypt shows rising interest with government-backed infrastructure projects. Other African nations adopt hybrid services gradually due to limited IT budgets and connectivity challenges. It strengthens reliance on managed service providers to deliver cost-efficient solutions. Regional enterprises demand scalable services to support growth and modernization. Service providers target Africa as an emerging market with long-term potential. The Global Hybrid Infrastructure Managed Services Market in Africa grows on the back of digital reforms and private investments.
Key Player Analysis:
- IBM Corporation
- Accenture
- Cisco Systems, Inc.
- DXC Technology
- Atos SE
- Fujitsu Limited
- Cognizant Technology Solutions
- HCL Technologies
- Wipro Limited
- Capgemini SE
Competitive Analysis:
The Global Hybrid Infrastructure Managed Services Market is highly competitive, shaped by global technology leaders and regional specialists. Major players include IBM Corporation, Accenture, Cisco Systems, DXC Technology, Atos SE, Fujitsu, Cognizant, HCL Technologies, Wipro, and Capgemini. It is defined by continuous innovation in hybrid cloud, data center, and security management services. Companies compete through service differentiation, global delivery networks, and strategic alliances with hyperscale cloud providers. The market emphasizes acquisitions, partnerships, and regional expansions to strengthen presence across diverse industries. Providers invest heavily in AI-driven automation, cybersecurity, and compliance solutions to meet enterprise demands. It highlights an environment where both global leaders and local firms capture opportunities through customization and sector-specific solutions. The competitive landscape remains dynamic, reflecting the growing demand for hybrid models that support scalability, efficiency, and digital transformation goals.
Recent Developments:
- In September 2025, IBM Corporation announced the launch of its latest brand campaign, "Let's create smarter business," designed to accelerate AI adoption among enterprise customers worldwide. The campaign features Lewis Hamilton and underscores IBM's push to integrate AI more deeply across business processes and hybrid infrastructure services.
- In July 2025, Accenture revealed its agreement to acquire Maryville Consulting Group, a U.S.-based technology consultancy focused on product-driven growth strategies, digital operations, and technology business management. This acquisition enhances Accenture’s capabilities in technology-enabled reinvention and aligns with its goal of helping clients modernize hybrid infrastructures and digital service delivery.
- In February 2025, IBM completed the acquisition of HashiCorp for USD 6.4 billion, integrating HashiCorp’s Terraform and Vault tools into its hybrid cloud platform. This move highlights IBM's commitment to expanding its hybrid infrastructure managed services portfolio, with a focus on automation and advanced cloud management capabilities designed to address growing enterprise demand for secure, multi-cloud environments.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Deployment Mode and Industry Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Hybrid Infrastructure Managed Services Market will expand through rising enterprise reliance on managed hybrid ecosystems.
- Demand will intensify for cloud management platforms that unify multi-cloud, hybrid, and on-premises infrastructure.
- AI-driven automation will enhance monitoring, cost control, and workload optimization across diverse enterprise systems.
- Security and compliance management will remain central as cyber threats and regulatory requirements increase worldwide.
- Industry-specific solutions will see growth, particularly in healthcare, BFSI, and manufacturing, requiring customized hybrid strategies.
- Strategic alliances between service providers and hyperscale cloud companies will strengthen market positioning.
- Small and medium enterprises will increasingly adopt hybrid services to achieve scalability and operational efficiency.
- Emerging markets in Asia Pacific, Latin America, and Africa will create new opportunities through rapid digital transformation.
- Investments in edge computing and 5G integration will drive hybrid services closer to end-user environments.
- The competitive environment will remain dynamic, with innovation, acquisitions, and service differentiation shaping long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enterprise Demand for Secure, Scalable, and Flexible IT Environments
Organizations are increasingly investing in hybrid infrastructure managed services to balance cloud adoption with legacy system management, ensuring operational continuity and supporting business transformation with improved agility and cost optimization.
Enhanced Security and Compliance Needs in Multi-Cloud Environments
The proliferation of cyber threats and stringent regulatory requirements are driving enterprises to adopt managed services that provide advanced security frameworks, automated compliance monitoring, and regular audits, especially in sectors like finance, healthcare, and government.
Rapid Digital Transformation Initiatives
Businesses across industries are prioritizing digital modernization, leveraging hybrid managed services to scale resources, integrate digital platforms, and accelerate innovation while minimizing disruption and risk during transformation projects.
Focus on Business Continuity and Operational Resilience
Hybrid infrastructure models are increasingly adopted to ensure high availability, disaster recovery, and minimal downtime, enabling enterprises to maintain operations and customer trust in the face of disruptions such as cyber incidents or natural disasters.
Integration of AI and Automation in Service Delivery
Service providers are embedding AI-driven automation and analytics into their offerings, enabling proactive monitoring, predictive maintenance, and optimized resource allocation, which enhances efficiency and reduces operational costs for enterprises managing complex hybrid environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Hybrid Infrastructure Managed Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Hybrid Infrastructure Managed Services Market projected to grow between 2024 and 2032?
Which Global Hybrid Infrastructure Managed Services Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Hybrid Infrastructure Managed Services Market?
Who are the leading companies in the Global Hybrid Infrastructure Managed Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Data Center Management
- 1.2.2 Cloud Management (Private, Public, Hybrid Cloud)
- 1.2.3 Network Management
- 1.2.4 Security & Compliance Management
- 1.2.5 Others
- 1.3 By Deployment Mode
- 1.3.1 On-Premises Managed Services
- 1.3.2 Hosted Managed Services
- 1.3.3 Cloud-Based Managed Services
- 1.4 By Industry Vertical
- 1.4.1 IT & Telecom
- 1.4.2 BFSI (Banking, Financial Services, Insurance)
- 1.4.3 Healthcare
- 1.4.4 Retail & Consumer Goods
- 1.4.5 Manufacturing
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,827.06 million → 2032: USD 14,798.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hybrid Infrastructure Managed Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hybrid Infrastructure Managed Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Hybrid Infrastructure Managed Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Hybrid Infrastructure Managed Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hybrid Infrastructure Managed Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hybrid Infrastructure Managed Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hybrid Infrastructure Managed Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hybrid Infrastructure Managed Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,827.06 million → 2032: USD 14,798.68 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hybrid Infrastructure Managed Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Data Center Management
- 12.3.6.2 Cloud Management (Private, Public, Hybrid Cloud)
- 12.3.6.3 Network Management
- 12.3.6.4 Security & Compliance Management
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 On-Premises Managed Services
- 12.4.6.2 Hosted Managed Services
- 12.4.6.3 Cloud-Based Managed Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 IT & Telecom
- 12.5.6.2 BFSI (Banking, Financial Services, Insurance)
- 12.5.6.3 Healthcare
- 12.5.6.4 Retail & Consumer Goods
- 12.5.6.5 Manufacturing
- 12.5.6.6 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hybrid Infrastructure Managed Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hybrid Infrastructure Managed Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hybrid Infrastructure Managed Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hybrid Infrastructure Managed Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Accenture
- 18.4 Cisco Systems, Inc.
- 18.5 DXC Technology
- 18.6 Atos SE
- 18.7 Fujitsu Limited
- 18.8 Cognizant Technology Solutions
- 18.9 HCL Technologies
- 18.10 Wipro Limited
- 18.11 Capgemini SE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

