
Market Overview:
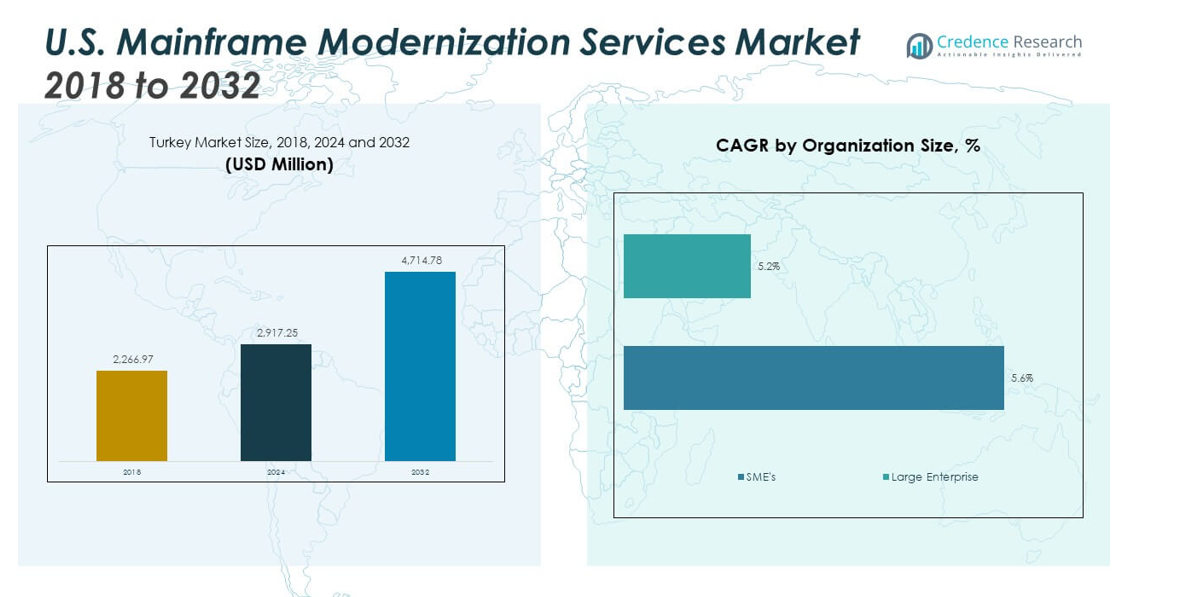
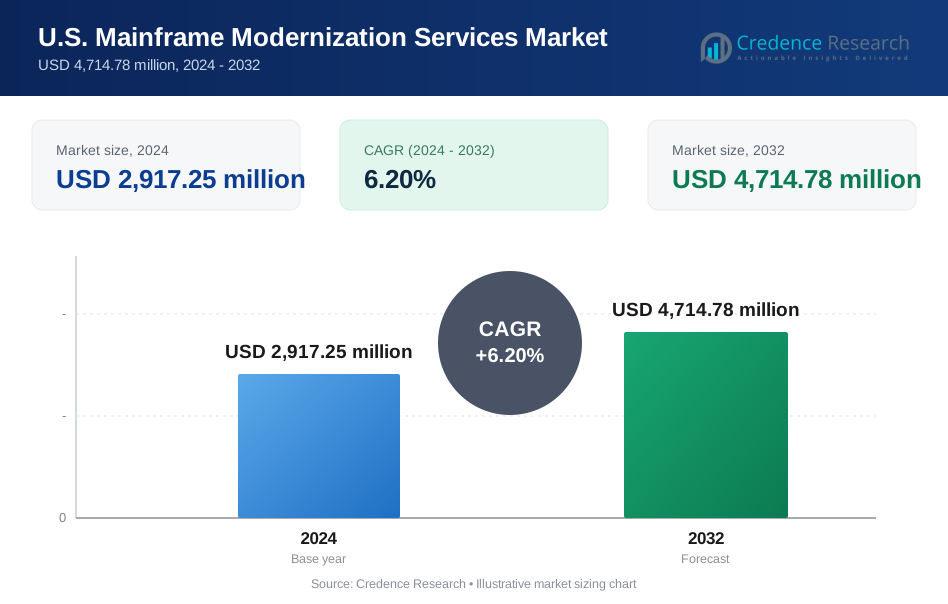
The U.S. Mainframe Modernization Services Market size was valued at USD 2,266.97 million in 2018 to USD 2,917.25 million in 2024 and is anticipated to reach USD 4,714.78 million by 2032, at a CAGR of 6.20% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Mainframe Modernization Services Market Size 2024 | USD 2,917.25 million |
| U.S. Mainframe Modernization Services Market, CAGR | 6.20% |
| U.S. Mainframe Modernization Services Market Size 2032 | USD 4,714.78 million |
Market growth is driven by rising pressure to reduce operational risk and improve agility. Enterprises modernize mainframes to integrate cloud, analytics, and API-based systems. Skilled workforce shortages push firms toward managed modernization partners. Regulatory compliance also drives upgrades in security and data governance. Cost optimization motivates code refactoring and workload optimization. Business demand for faster application deployment supports DevOps adoption. These factors together strengthen demand for structured and phased modernization programs.
The market is led by the United States due to a high concentration of legacy mainframe users. Financial services, government agencies, and large retailers drive sustained demand. The Northeast and Midwest remain strong due to dense enterprise and public sector presence. The West Coast shows growth from digital-first integration projects. Southern states emerge through modernization in healthcare and utilities. Nationwide adoption reflects broad reliance on mainframe platforms across industries.
Market Insights:
- The market expanded from USD 2,266.97 million in 2018 to USD 2,917.25 million in 2024 and is projected to reach USD 4,714.78 million by 2032, growing at a CAGR of 6.20%, driven by sustained enterprise reliance on legacy mainframes and phased modernization strategies.
- The Western United States leads with about 35% share due to strong technology adoption and large enterprise IT budgets, followed by the Northeast at nearly 25% supported by BFSI concentration, and the Midwest at around 22% driven by manufacturing and regional financial institutions.
- The Southern United States is the fastest-growing region with close to 18% share, supported by rising healthcare, telecom, and public sector modernization activity and wider adoption of hybrid deployment models.
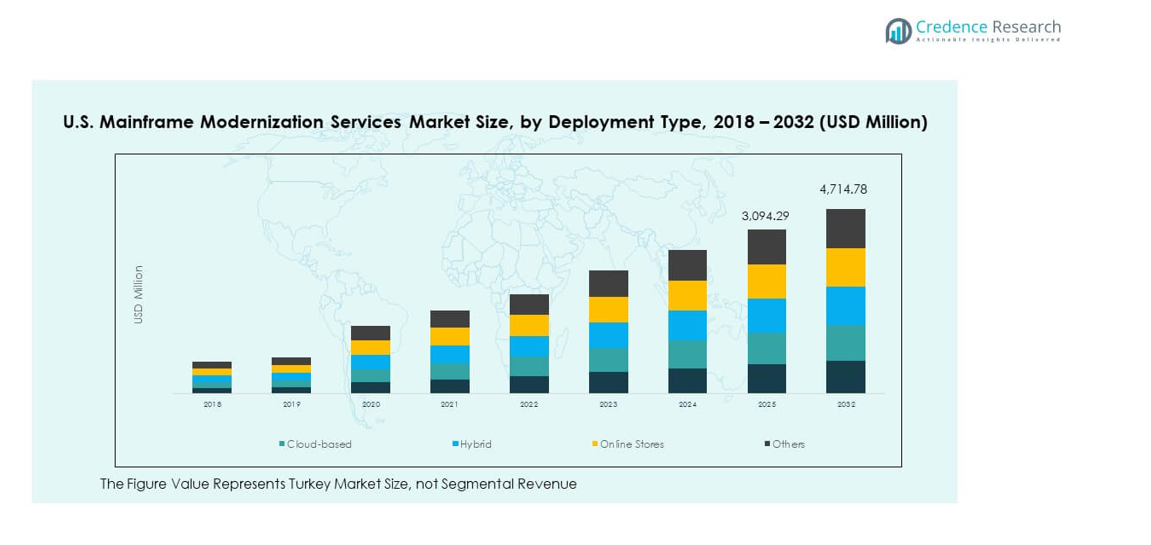
- By deployment type, hybrid deployment holds the largest share at about 45%, reflecting enterprise preference for balancing control with scalability while modernizing critical workloads.
- Cloud-based deployment accounts for nearly 35% share, driven by flexibility and integration needs, while on-premise models retain around 20% share due to compliance and data sensitivity requirements.
Market Drivers:
Sustained Reliance On Mainframes For High-Volume Mission-Critical Operations
Large enterprises depend on mainframes for core transaction processing. Financial institutions process payments and settlements on these systems. Insurance firms manage policies and claims through legacy platforms. Government agencies rely on mainframes for citizen records. System stability remains non-negotiable for these users. Modernization extends system life without disruption. Risk reduction drives service adoption. The U.S. Mainframe Modernization Services Market supports controlled transformation.
- For instance, IBM zSystems supports hybrid cloud DevOps pipelines that perform up to 15× faster in test cycles. Modernization extends system life without disruption. Risk reduction drives service adoption.
Enterprise Pressure To Improve Operational Agility And Application Responsiveness
Business units demand faster product and service launches. Legacy environments limit rapid application changes. Modernization enables modular application architectures. Service providers refactor code for flexibility. Enterprises gain faster development cycles. Improved responsiveness supports competitive positioning. IT teams align systems with business goals. Agility remains a key modernization driver.
- For instance, Infosys modernization helped a telco save USD 13 million annually by re-engineering CRM. Improved responsiveness supports competitive positioning.
Escalating Workforce Constraints Within Legacy Technology Environments
Mainframe-skilled professionals continue to retire. New graduates favor cloud-native technologies. Enterprises face operational continuity risk. Service partners provide specialized expertise. Knowledge transfer becomes a priority activity. Automation reduces manual dependency. Workforce gaps accelerate modernization decisions. Talent scarcity shapes long-term strategy.
Heightened Focus On Security, Audit Readiness, And System Resilience
Cyber threats target legacy vulnerabilities. Regulators demand stronger data controls. Enterprises modernize to enhance security frameworks. Improved monitoring supports audit readiness. Encryption upgrades protect sensitive data. Resilience planning gains executive attention. Modernization aligns systems with compliance needs. Security concerns sustain demand.
Market Trends:
Growing Preference For Incremental Modernization Over Full System Replacement
Enterprises avoid disruptive platform replacements. Incremental approaches reduce operational risk. Teams modernize applications in defined phases. Core processing remains intact. This model suits regulated industries. Service providers design staged roadmaps. Risk-managed execution gains favor. Adoption continues across sectors.
- For instance, Roc ket Software closes a USD 2.275 billion acquisition of modernization & connectivity assets, enhancing hybrid capabilities.
Expansion Of Platform-Agnostic Toolsets Supporting Cross-Environment Operations
Tool vendors support mainframe and cloud integration. Unified toolsets simplify system management. Enterprises gain centralized visibility. Cross-platform tools improve efficiency. Vendors invest in interoperability features. Standardization reduces operational complexity. Tool maturity influences vendor selection. This trend reshapes service delivery.
- For instance, Google Cloud’s Mainframe Assessment Tool inventories workloads and recommends target architectures. Vendors invest in interoperability features. Standardization reduces operational complexity.
Rising Use Of Advanced Testing And Simulation Before Production Changes
Enterprises emphasize pre-deployment validation. Simulation tools model workload behavior. Testing reduces outage risk. Automated testing improves release confidence. Providers embed testing frameworks in projects. Quality assurance gains priority. Risk avoidance shapes modernization planning. Testing maturity defines success.
Increased Adoption Of Long-Term Managed Modernization Engagement Models
Enterprises favor predictable service structures. Managed models reduce internal workload. Providers offer continuous optimization services. Performance metrics guide service outcomes. Long-term contracts improve cost visibility. Trust strengthens provider relationships. This trend supports recurring revenue growth. Managed services gain traction.
Market Challenges Analysis:
High Architectural Complexity Across Decades Of Customized Legacy Systems
Mainframe environments reflect long customization histories. Documentation gaps hinder transformation planning. Interconnected applications raise dependency risks. Testing cycles become resource intensive. Enterprises require uninterrupted system availability. Errors impact critical business functions. Providers face execution pressure. The U.S. Mainframe Modernization Services Market navigates these complexities.
Budget Sensitivity And Unclear Short-Term Business Value Perception
Modernization requires multi-year investment. Executive teams scrutinize spending justification. Benefits appear gradually over time. Cost overruns remain a concern. Scope creep challenges project control. ROI measurement lacks standard benchmarks. Decision cycles extend due to uncertainty. Financial caution slows adoption.
Market Opportunities:
Rising Modernization Demand Across Public Sector And Regulated Utility Enterprises
Public institutions operate large legacy estates. Budget discipline favors modernization strategies. Compliance requirements support upgrade initiatives. Utilities depend on system reliability. Modernization enhances disaster recovery readiness. Providers tailor solutions to regulatory needs. These sectors offer steady demand. Long-term contracts support growth.
Growth Of Industry-Aligned And Outcome-Focused Modernization Service Models
Enterprises seek sector-specific modernization expertise. Financial services prioritize transaction integrity. Healthcare emphasizes data accessibility and privacy. Outcome-based pricing gains interest. Providers link fees to performance milestones. This model improves accountability. Client trust strengthens partnerships. It expands service opportunities.
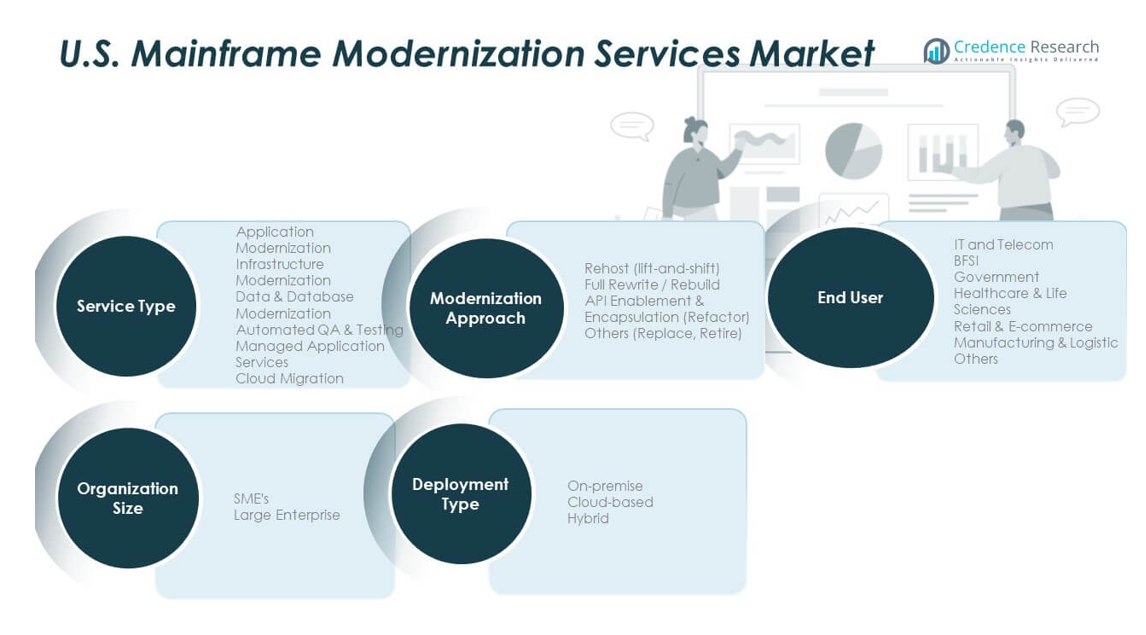
Market Segmentation Analysis:
By Service Type
Application modernization leads demand as enterprises update core systems for agility. Data modernization supports analytics, governance, and secure data access. Infrastructure modernization focuses on performance, scalability, and system resilience. Integration services enable connectivity with cloud and digital platforms. Consulting and assessment services guide roadmap design and risk control. These services support phased transformation programs. Service mix reflects enterprise maturity levels.
- For instance, IBM’s zSystems DevOps integration can execute tests up to 15× faster than traditional mainframe. Integration services enable connectivity with cloud and digital platforms.
By Modernization Approach
Rehosting remains common for risk-averse organizations. Replatforming improves efficiency with limited code change. Refactoring supports performance and maintainability goals. Re-architecting enables long-term digital alignment. Replacement sees selective use for non-core applications. Approach choice depends on complexity and business impact. The U.S. Mainframe Modernization Services Market reflects a preference for balanced strategies.
- For instance, tools like TmaxSoft OpenFrame rehost legacy assets to cloud environments quickly. Refactoring supports performance and maintainability goals.
By End-User
BFSI dominates due to transaction volume and compliance needs. Government and public sector drive steady modernization demand. Healthcare and life sciences focus on data access and security. Retail and e-commerce modernize for real-time operations. Manufacturing and others adopt modernization to improve system integration. End-user needs vary by regulatory and operational intensity. Sector diversity supports stable demand.
By Organization Size
Large enterprises represent the primary customer base. Complex legacy estates require structured modernization. Small and medium enterprises adopt selective upgrades. Budget control shapes SME service adoption. Scale influences service scope and timelines. Both segments value risk mitigation. Size affects provider engagement models.
By Deployment Type
On-premise remains relevant for sensitive workloads. Cloud-based deployment gains traction for flexibility. Hybrid deployment balances control and scalability. Enterprises favor hybrid for gradual transition. Deployment choice aligns with compliance needs. Architecture strategy drives service demand.
Segmentation:
- By Service Type
- Application Modernization
- Data Modernization
- Infrastructure Modernization
- Integration Services
- Consulting and Assessment Services
- By Modernization Approach
- Rehosting
- Replatforming
- Refactoring
- Re-architecting
- Replacement
- By End-User
- Banking, Financial Services, and Insurance (BFSI)
- Government and Public Sector
- Healthcare and Life Sciences
- Retail and E-commerce
- Manufacturing and Others
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By Deployment Type
- On-Premise
- Cloud-Based
- Hybrid Deployment
Regional Analysis:
Western United States Dominates Through Technology-Driven Enterprise Demand
The U.S. Mainframe Modernization Services Market shows the Western United States leading with nearly 35% market share. The region benefits from a strong presence of technology firms and digital-first enterprises. Large corporations modernize mainframes to align with cloud-native ecosystems. Financial services, technology providers, and media companies drive steady demand. Enterprises focus on integration, automation, and scalability improvements. High IT budgets support complex multi-year modernization programs. The West remains the most advanced regional market.
Northeastern And Midwestern United States Sustain Demand From Core Industries
The Northeastern region accounts for around 25% market share, supported by dense BFSI concentration. Banks and insurers rely on mainframes for transaction-heavy operations. Regulatory oversight encourages continuous system upgrades. The Midwest contributes close to 22% share through manufacturing and regional financial institutions. Enterprises modernize to improve system reliability and integration. Cost discipline shapes phased project execution. Both regions value stability and long-term service partnerships.
Southern United States And Emerging Regional Markets Show Steady Expansion
The Southern United States holds approximately 18% market share and shows rising momentum. Healthcare, telecom, and energy enterprises drive modernization activity. Population growth supports expansion of digital public services. Enterprises adopt hybrid deployment models to manage risk. Smaller regional markets together represent about 10% share. These areas modernize selectively based on operational needs. Regional diversity supports balanced national growth.
Key Player Analysis:
- IBM
- Infosys
- Tata Consultancy Services (TCS)
- Cognizant
- Accenture
- HCL Technologies
- DXC Technology
- Wipro
- Capgemini
- NTT DATA Services
Competitive Analysis:
The competitive landscape of the U.S. Mainframe Modernization Services Market features global IT service providers with deep legacy expertise. Large vendors compete on domain knowledge, delivery scale, and modernization frameworks. Firms differentiate through automation tools, hybrid architecture capability, and industry-specific solutions. Strategic partnerships with cloud providers strengthen service depth. Providers emphasize risk-controlled migration and phased execution models. Client retention depends on long-term managed service capability. Competitive intensity remains high due to large enterprise contracts and recurring revenue potential.
Recent Developments:
- On December 16, 2025, Accenture signed an agreement to acquire a majority stake of 65% in DLB Associates, a US-based AI data center engineering and consulting firm. The acquisition is designed to expand Accenture's end-to-end data center capabilities to help clients accelerate time to market and meet demand for AI enablement. Upon closing, DLB's approximately 620 employees, led by David Quirk and Neil Chauhan, will join Accenture's Industry X practice, augmenting its infrastructure and capital projects (I&CP) capabilities. DLB, founded in 1980, specializes in data center site selection, design engineering, commissioning, and energy optimization services. While not directly focused on mainframe modernization, this acquisition strengthens Accenture's ability to support infrastructure modernization and AI-driven transformation initiatives for enterprise clients.
- In May 2025, Cognizant expanded its strategic collaboration with Pegasystems to augment agentic AI services and drive rapid cloud transformations for joint clients. The partnership integrates Cognizant's intellectual property with Pega Blueprint capabilities, enabling the rapid conversion of legacy systems into AI-powered solutions. The collaboration focuses on integrating Pega Blueprint with Cognizant's internal innovation program Bluebolt to help teams rapidly convert ideas into Minimum Viable Products using low-code tools and AI-assisted process mapping. Cognizant leverages its AI-driven code rewrite workbench to extract legacy logic, data, and workflows, reimplementing them in cloud-ready environments on the Pega Infinity platform. This partnership represents a strategic shift away from traditional 'lift-and-shift' approaches toward AI-infused transformation journeys.
- In April 2025, IBM announced the IBM z17, its next-generation mainframe platform engineered with integrated artificial intelligence capabilities spanning hardware, software, and system operations. The z17 features the Telum II processor with embedded AI accelerators, enabling the system to process over 450 billion inference operations daily with response times under one millisecond. The platform underwent five years of development incorporating feedback from more than 100 clients and resulted in more than 300 filed patents. The z17 achieved general availability on June 8, 2025. IBM is also introducing the Spyre Accelerator in Q4 2025 as an add-on to provide additional compute power for generative AI tasks. Additionally, IBM previewed z/OS 3.2, scheduled for Q3 2025, which will include support for hardware-accelerated AI and hybrid cloud data integration.
Report Coverage:
The research report offers an in-depth analysis based on service type, modernization approach, end-user, organization size, and deployment type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Enterprises will prioritize phased modernization to reduce operational risk.
- Hybrid deployment models will dominate long-term strategies.
- Automation tools will shorten assessment and migration timelines.
- Managed modernization services will gain wider acceptance.
- BFSI and public sector demand will remain stable anchors.
- Security-driven upgrades will shape service scope.
- Skill shortages will support outsourcing growth.
- Industry-specific modernization frameworks will expand.
- Provider competition will intensify around value delivery.
- Long-term contracts will improve revenue visibility.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustained Reliance on Mainframes for Mission-Critical Operations
Large U.S. enterprises, especially in BFSI, government, and retail, continue to depend on mainframes for high-volume transaction processing and core business functions. The need to maintain system stability while extending the life of these platforms drives demand for structured modernization services.
Enterprise Pressure to Improve Agility and Application Responsiveness
Business units require faster product launches and more responsive IT systems. Modernization enables modular architectures and DevOps adoption, allowing organizations to accelerate development cycles and better align IT with business goals.
Escalating Workforce Constraints in Legacy Environments
The retirement of mainframe-skilled professionals and a shortage of new talent familiar with legacy systems create operational risks. This talent gap pushes organizations to partner with managed service providers for modernization expertise and automation.
Heightened Focus on Security, Compliance, and System Resilience
Increasing cyber threats and regulatory requirements are prompting enterprises to modernize mainframes for enhanced security, audit readiness, and data governance. Upgrades in encryption, monitoring, and resilience are critical for compliance and risk reduction.
Cost Optimization and Operational Efficiency
Organizations seek to reduce operational costs and improve efficiency by refactoring code, optimizing workloads, and leveraging hybrid or cloud deployments. Modernization initiatives are often justified by long-term savings and improved resource utilization.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Mainframe Modernization Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Mainframe Modernization Services Market projected to grow between 2024 and 2032?
What factors are driving the growth of the U.S. Mainframe Modernization Services market?
What are the key segments within the U.S. Mainframe Modernization Services market?
What are some challenges faced by the U.S. Mainframe Modernization Services market?
Who are the major players in the U.S. Mainframe Modernization Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Banking, Financial Services, and Insurance (BFSI)
- 1.2.2 Government and Public Sector
- 1.2.3 Healthcare and Life Sciences
- 1.2.4 Retail and E-commerce
- 1.2.5 Manufacturing and Others
- 1.3 By Service Type
- 1.3.1 Application Modernization
- 1.3.2 Data Modernization
- 1.3.3 Infrastructure Modernization
- 1.3.4 Integration Services
- 1.3.5 Consulting and Assessment Services
- 1.4 By Deployment Type
- 1.4.1 On-Premise
- 1.4.2 Cloud-Based
- 1.4.3 Hybrid Deployment
- 1.5 By Modernization Approach
- 1.5.1 Rehosting
- 1.5.2 Replatforming
- 1.5.3 Refactoring
- 1.5.4 Re-architecting
- 1.5.5 Replacement
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,917.25 million → 2032: USD 4,714.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Mainframe Modernization Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Mainframe Modernization Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 U.S. Mainframe Modernization Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 U.S. Mainframe Modernization Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Mainframe Modernization Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Mainframe Modernization Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Mainframe Modernization Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Mainframe Modernization Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,917.25 million → 2032: USD 4,714.78 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Mainframe Modernization Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Banking, Financial Services, and Insurance (BFSI)
- 12.3.6.2 Government and Public Sector
- 12.3.6.3 Healthcare and Life Sciences
- 12.3.6.4 Retail and E-commerce
- 12.3.6.5 Manufacturing and Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Application Modernization
- 12.4.6.2 Data Modernization
- 12.4.6.3 Infrastructure Modernization
- 12.4.6.4 Integration Services
- 12.4.6.5 Consulting and Assessment Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premise
- 12.5.6.2 Cloud-Based
- 12.5.6.3 Hybrid Deployment
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Modernization Approach - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Rehosting
- 12.6.6.2 Replatforming
- 12.6.6.3 Refactoring
- 12.6.6.4 Re-architecting
- 12.6.6.5 Replacement
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Mainframe Modernization Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Mainframe Modernization Services Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Mainframe Modernization Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Mainframe Modernization Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Infosys
- 18.4 Tata Consultancy Services (TCS)
- 18.5 Cognizant
- 18.6 Accenture
- 18.7 HCL Technologies
- 18.8 DXC Technology
- 18.9 Wipro
- 18.10 Capgemini
- 18.11 NTT DATA Services
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

