
Market Overview
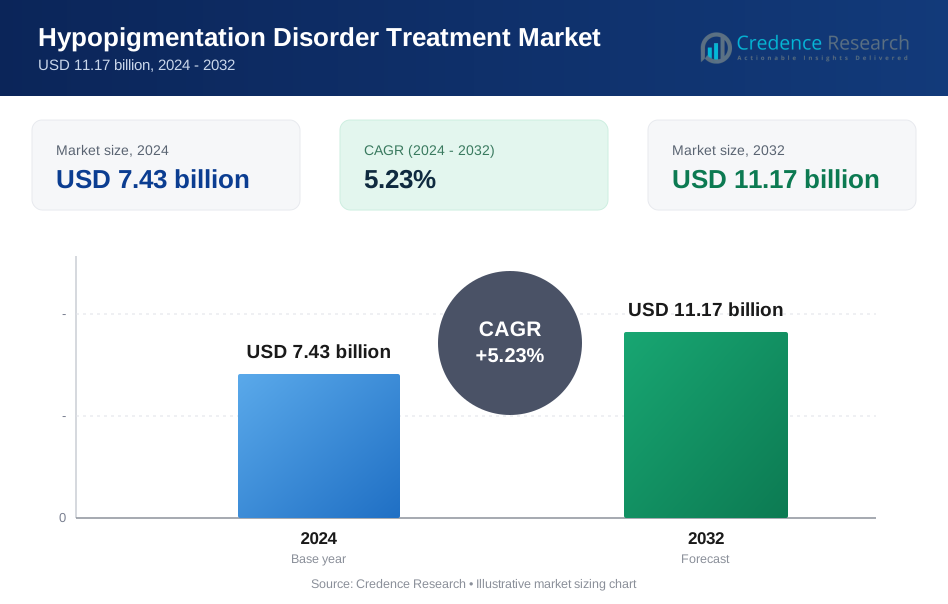
The global Hypopigmentation Disorder Treatment Market was valued at USD 7.43 billion in 2024 and is projected to reach USD 11.17 billion by 2032, growing at a CAGR of 5.23% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hypopigmentation Disorder Treatment Market Size 2024 | USD 7.43 Billion |
| Hypopigmentation Disorder Treatment Market, CAGR | 5.23% |
| Hypopigmentation Disorder Treatment Market Size 2032 | USD 11.17 Billion |
The Hypopigmentation Disorder Treatment Market grows with rising prevalence of vitiligo, albinism, and post-inflammatory hypopigmentation worldwide. Increasing patient awareness and focus on aesthetic appearance drive demand for advanced therapies. It benefits from technological advancements in phototherapy, topical immunomodulators, and regenerative medicine.
Geographically, the Hypopigmentation Disorder Treatment Market shows strong growth across North America, Europe, and Asia-Pacific, supported by improved access to dermatology care and rising awareness of skin health. North America leads with advanced infrastructure, high patient awareness, and strong adoption of innovative therapies like biologics and phototherapy devices. Europe follows with growing clinical research, standardized treatment guidelines, and wide availability of excimer laser and narrowband UVB systems. Asia-Pacific emerges as the fastest-growing region, driven by expanding healthcare facilities, rising medical tourism, and growing affordability for advanced procedures. Key players influencing this market include Galderma, Pfizer Inc., AbbVie Inc., and Novartis AG, who focus on product innovation, clinical trials, and global partnerships to strengthen their market presence. Their strategies emphasize research into novel drug formulations and regenerative therapies to provide more effective, long-term solutions for patients with hypopigmentation disorders worldwide.
Market Insights
- The Hypopigmentation Disorder Treatment Market was valued at USD 7.43 billion in 2024 and is projected to reach USD 11.17 billion by 2032, growing at a CAGR of 5.23% during the forecast period.
- Rising prevalence of vitiligo, albinism, and post-inflammatory hypopigmentation drives consistent demand for treatment solutions worldwide.
- Increasing use of combination therapies, advanced phototherapy devices, and regenerative medicine boosts treatment effectiveness and patient satisfaction.
- Leading players include Galderma, Pfizer Inc., AbbVie Inc., and Novartis AG, focusing on innovative biologics, topical solutions, and clinical research collaborations.
- High treatment costs, limited insurance coverage, and inconsistent outcomes challenge widespread adoption, particularly in developing economies.
- North America leads due to advanced dermatology infrastructure and high patient awareness, followed by Europe with strong clinical guidelines and access to laser-based therapies.
- Asia-Pacific is the fastest-growing region, supported by expanding healthcare access, rising medical tourism, and government initiatives improving dermatology services.
Market Drivers
Rising Prevalence of Hypopigmentation Disorders
The Hypopigmentation Disorder Treatment Market is driven by increasing cases of vitiligo, albinism, and post-inflammatory hypopigmentation worldwide. Growing awareness of skin health encourages patients to seek timely diagnosis and treatment. It fuels demand for topical creams, light therapy, and oral medications. Dermatology clinics report a steady rise in consultations for pigmentary disorders. Advances in diagnostic tools improve early detection, leading to higher treatment initiation rates. This trend supports market expansion across both developed and emerging regions.
- For instance, Incyte announced results from its TRuE-V clinical program showing that approximately 50% of patients achieved ≥75% facial repigmentation (F-VASI75) at Week 52, supporting its FDA approval for nonsegmental vitiligo treatment.
Growing Focus on Aesthetic and Psychological Well-Being
Demand for hypopigmentation treatments rises as patients prioritize cosmetic appearance and emotional wellness. The Hypopigmentation Disorder Treatment Market benefits from increased acceptance of medical and cosmetic dermatology solutions. It helps restore skin tone, improving patient confidence and quality of life. Rising disposable incomes enable more individuals to afford advanced therapies. Social media awareness campaigns promote acceptance of treatment options and boost patient education. This focus on aesthetics drives adoption of combination therapies and clinic-based procedures.
- For instance, in a Phase 2 trial presented by AbbVie, upadacitinib monotherapy for vitiligo resulted in significant improvements in facial repigmentation as measured by the F-VASI scale after 24 weeks. The 11 mg dose showed a mean F-VASI reduction of -35.6% compared to a -14.4% reduction for the placebo group at week 24, for a least squares mean difference versus placebo of -21.27%.
Technological Advancements in Treatment Modalities
Continuous innovation strengthens the Hypopigmentation Disorder Treatment Market by offering more effective solutions. New phototherapy devices, topical immunomodulators, and regenerative techniques improve treatment outcomes. It shortens recovery time and enhances patient satisfaction. Stem cell-based therapies and targeted drug delivery systems show promising results in clinical studies. Pharmaceutical companies invest in R&D to launch safer, more potent formulations. These advancements expand the range of treatment options available to dermatologists and patients.
Rising Healthcare Access and Dermatology Infrastructure
Expansion of healthcare infrastructure supports growth of the Hypopigmentation Disorder Treatment Market. Dermatology clinics, hospitals, and specialty centers are increasing globally, improving patient access. It helps deliver treatments to rural and underserved areas. Government programs in several regions support dermatology awareness and subsidize care for skin disorders. Insurance coverage for dermatological treatments becomes more common, encouraging patient adoption. Strong distribution networks ensure availability of products and devices across markets, driving consistent growth.
 Market Trends
Growing Adoption of Combination Therapies
The Hypopigmentation Disorder Treatment Market shows rising adoption of combination approaches for improved outcomes. Dermatologists pair topical corticosteroids, calcineurin inhibitors, and phototherapy to achieve faster repigmentation. It enhances treatment efficacy and reduces recurrence rates. Patients prefer multi-modal regimens that deliver visible results in shorter timeframes. Research supports combination therapy as the standard for conditions like vitiligo. Pharmaceutical companies develop products designed for use with light-based therapies. This trend boosts patient compliance and market demand.
- For instance, multiple clinical studies have investigated the use of combination therapy for vitiligo management, demonstrating the benefits of combining topical treatments like clobetasol propionate or pimecrolimus with narrow-band ultraviolet B (NB-UVB) phototherapy.
Increasing Use of Advanced Phototherapy Devices
The Hypopigmentation Disorder Treatment Market benefits from the popularity of targeted phototherapy devices. Narrowband UVB and excimer laser treatments gain traction for localized hypopigmentation patches. It allows precise targeting of affected skin while minimizing damage to surrounding tissue. Clinics adopt portable devices to expand treatment access and reduce costs. Home-use phototherapy units are also gaining approval, supporting convenience for patients. Rising availability of compact, safe devices drives greater adoption worldwide. This trend improves treatment accessibility and patient adherence.
- For instance, Daavlin manufactures the DermaPal handheld narrowband UVB device, which delivers light with a peak at 311 nm for treating conditions like localized vitiligo. The unit is designed with high-intensity lamps that offer shorter treatment times compared to older phototherapy systems, though specific session durations vary based on individual treatment protocols. The initial dose is determined by a doctor and can be adjusted as treatment progresses to achieve the desired therapeutic effect.
Focus on Regenerative and Biologic Therapies
Emerging regenerative medicine approaches are reshaping the Hypopigmentation Disorder Treatment Market. Stem cell therapy and melanocyte transplantation gain attention for refractory cases. It offers potential for long-lasting repigmentation and fewer relapses. Biologic therapies targeting autoimmune mechanisms are under clinical investigation. These innovations expand treatment possibilities beyond conventional topical and systemic drugs. Growing investment in clinical research accelerates the development of these advanced solutions. This trend signals a shift toward more personalized and durable treatment outcomes.
Expansion of Teledermatology and Digital Tools
The Hypopigmentation Disorder Treatment Market experiences a rise in teledermatology services and digital solutions. Virtual consultations enable early diagnosis and prescription of therapies. It saves patient time and improves access in underserved areas. AI-powered skin analysis tools support dermatologists in tracking progress and customizing treatment plans. Mobile apps encourage patient engagement through reminders and progress monitoring. Healthcare providers adopt digital platforms to streamline follow-ups and reduce clinic burden. This trend enhances treatment continuity and patient satisfaction.
Market Challenges Analysis
High Treatment Costs and Limited Insurance Coverage
The Hypopigmentation Disorder Treatment Market faces challenges due to high treatment costs and limited reimbursement options. Advanced phototherapy devices, stem cell procedures, and biologics remain expensive for many patients. It creates affordability barriers, especially in developing regions. Insurance coverage for cosmetic dermatology treatments is still limited, discouraging adoption. Patients often discontinue treatment midway due to financial constraints. High out-of-pocket expenses slow market growth despite rising awareness. This cost-related challenge impacts overall access to quality care.
Variable Treatment Outcomes and Lack of Standardization
The Hypopigmentation Disorder Treatment Market also struggles with inconsistent treatment results. Individual responses to phototherapy or topical agents vary widely, leading to patient dissatisfaction. It reduces trust in available options and lowers compliance. Lack of globally standardized treatment protocols complicates decision-making for clinicians. Limited clinical data on long-term efficacy of new regenerative therapies further slows adoption. Side effects such as skin irritation and risk of relapse add to concerns. These factors restrict the pace of widespread adoption and hinder market penetration.
Market Opportunities
Emergence of Advanced Therapies and Personalized Medicine
The Hypopigmentation Disorder Treatment Market offers strong opportunities with the development of biologics, stem cell therapy, and melanocyte transplantation techniques. These solutions promise longer-lasting repigmentation and better outcomes for patients unresponsive to conventional methods. It supports a shift toward personalized medicine where treatments are tailored to genetic and autoimmune profiles. Pharmaceutical companies invest in R&D to introduce novel immunomodulators and targeted drug delivery systems. Growing regulatory approvals for innovative therapies will expand patient access. This wave of innovation strengthens the market’s growth potential over the next decade.
Expansion of Healthcare Access and Digital Platforms
Wider healthcare coverage and teledermatology adoption create significant opportunities for the Hypopigmentation Disorder Treatment Market. Clinics and hospitals are expanding in emerging economies, bringing advanced treatments to underserved populations. It helps reduce diagnosis delays and encourages early intervention. Digital platforms and AI-powered tools improve treatment monitoring and patient compliance. Rising investments from public health agencies and private players enhance awareness of pigmentary disorders. These factors open new growth avenues for service providers and manufacturers worldwide.
Market Segmentation Analysis:
By Drugs Type
The Hypopigmentation Disorder Treatment Market is segmented into corticosteroids, calcineurin inhibitors, topical psoralens, immunomodulators, and others. Corticosteroids dominate the segment due to their ability to quickly reduce inflammation and stimulate repigmentation. It remains the first-line therapy for many patients with vitiligo and post-inflammatory hypopigmentation. Calcineurin inhibitors are increasingly used as steroid-sparing agents to minimize side effects, particularly for facial and sensitive areas. Topical psoralens combined with UV therapy show effectiveness in severe cases. Growing interest in biologics and regenerative therapies is expanding treatment choices and driving research investments.
- For instance, one 2017 study with 90 patients showed that a combination therapy of mometasone furoate and tacrolimus resulted in a statistically significant mean improvement in the Vitiligo Area Scoring Index after 24 weeks, a finding that reinforced the role of topical corticosteroids in vitiligo therapy.
By Disease Indication
The market is divided into vitiligo, albinism, post-inflammatory hypopigmentation, and others. Vitiligo accounts for the largest share, driven by its high prevalence and rising demand for effective treatment. It benefits from growing clinical trials and drug approvals targeting autoimmune causes of pigment loss. Albinism treatment is focused on symptom management, including UV protection and supportive care. Post-inflammatory hypopigmentation cases rise with increasing cosmetic procedures and skin trauma incidence. Demand for treatment grows as patients seek faster skin tone restoration. Research on repigmentation techniques continues to expand the scope of clinical interventions.
By End-user
The Hypopigmentation Disorder Treatment Market is segmented by end-user into hospitals, dermatology clinics, and homecare settings. Hospitals hold a significant share due to availability of advanced phototherapy equipment and experienced dermatologists. It enables comprehensive diagnosis and treatment under one roof. Dermatology clinics are growing rapidly, offering personalized treatment plans and convenient access for patients. Homecare settings gain traction with the availability of portable phototherapy devices and teledermatology services. Expansion of specialty skincare centers and online consultations supports rising treatment adoption across multiple regions.
- For instance, in some clinical settings, excimer laser phototherapy devices used to treat localized vitiligo have shown success rates dependent on the body part treated. Studies have indicated that after about 24 treatments, patients with vitiligo patches on the face and neck tend to show a better response than those with patches on the hands and feet.
Segments:
Based on Drugs Type
- Corticosteroids
- Melanocyte-stimulating hormone
- Other drugs
Based on Disease Indication
- Vitiligo
- Albinism
- Other disease indications
Based on End-user
- Hospitals
- Dermatology clinics
- Aesthetic centers
- Other end-users
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds 38% market share in the Hypopigmentation Disorder Treatment Market, driven by advanced healthcare infrastructure and strong patient awareness. The region benefits from high adoption of innovative therapies, including phototherapy devices and topical immunomodulators. It leads in clinical research and drug approvals, with several biologics under development for vitiligo treatment. The U.S. sees growing demand for dermatology services due to rising prevalence of autoimmune skin disorders. Presence of key pharmaceutical and device manufacturers strengthens treatment availability. Insurance coverage for dermatological procedures continues to improve, encouraging higher patient participation in treatment programs.
Europe
Europe accounts for 27% market share, supported by strong dermatology networks and public healthcare systems. The region focuses on early diagnosis and patient education through government-led awareness campaigns. It witnesses growing adoption of excimer laser therapy and narrowband UVB devices in hospitals and clinics. Countries like Germany, France, and the UK lead in clinical research and contribute to guidelines for standardized treatment. Reimbursement policies in several nations make advanced therapies accessible to a larger population. Rising demand for combination therapies drives innovation and market expansion in the region.
Asia-Pacific
Asia-Pacific captures 22% market share, emerging as a fast-growing market due to rising healthcare access and increasing awareness of hypopigmentation disorders. Large populations in India, China, and Southeast Asia contribute to higher case numbers, creating demand for affordable treatment solutions. It benefits from expanding dermatology clinics and investments in healthcare infrastructure. Growth in medical tourism supports adoption of advanced procedures like melanocyte transplantation and phototherapy. Pharmaceutical companies focus on expanding distribution networks to improve drug availability across remote areas. Government initiatives to improve skin health and training programs for dermatologists further strengthen regional growth.
Latin America
Latin America represents 7% market share, with growth driven by rising access to dermatology services and improving economic conditions. Brazil and Mexico are major contributors, with an expanding network of private clinics offering phototherapy and topical treatments. It faces challenges from uneven healthcare infrastructure in rural regions, but urban centers see strong adoption of cosmetic dermatology procedures. Rising middle-class income levels support demand for advanced treatments to address cosmetic concerns. Awareness programs and partnerships with global manufacturers help improve access to effective solutions.
Middle East and Africa
Middle East and Africa hold 6% market share, supported by growing healthcare investments and awareness about skin disorders. Gulf countries focus on expanding specialized dermatology centers equipped with modern treatment devices. It faces challenges with limited availability of dermatologists in some African nations, which slows adoption. Rising disposable incomes and demand for aesthetic treatments boost market prospects in urban regions. International collaborations with healthcare providers help improve training and availability of advanced therapies. Expansion of teledermatology services further supports access to treatment in remote areas.
Key Player Analysis
- Galderma
- Pfizer Inc.
- AbbVie Inc.
- Shiseido Company Limited
- Aclaris Therapeutics, Inc.
- Novartis AG
- Pierre Fabre Group
- Bayer AG
- Incyte
- Candela Corporation
Competitive Analysis
Competitive landscape of the Hypopigmentation Disorder Treatment Market is shaped by key players such as Galderma, Pfizer Inc., AbbVie Inc., Novartis AG, Bayer AG, Aclaris Therapeutics Inc., Incyte, Shiseido Company Limited, Pierre Fabre Group, and Candela Corporation. These companies compete by focusing on innovation, clinical research, and strategic partnerships to expand their treatment portfolios. They invest heavily in R&D to develop novel biologics, immunomodulators, and regenerative solutions aimed at improving repigmentation outcomes. Many are engaged in late-stage clinical trials for vitiligo therapies and exploring advanced delivery systems for topical medications. Strategic collaborations with dermatology clinics and research institutes help accelerate product adoption and market penetration. Companies also strengthen their global presence by expanding distribution networks and securing regulatory approvals in emerging economies. Continuous focus on patient-centric solutions and aesthetic outcomes allows them to maintain a competitive edge and meet the growing demand for effective hypopigmentation treatments.
Recent Developments
- In April 2025, a study showed combining ritlecitinib with narrow-band UVB (nbUVB) phototherapy yields higher repigmentation rates for facial and body areas than ritlecitinib alone.
- In March 2025, AbbVie presented new findings on Upadacitinib’s effects in non-segmental vitiligo during the American Academy of Dermatology (AAD) meeting.
- In 2025, Pfizer is recruiting for a 52-week clinical trial to evaluate the safety and effects of ritlecitinib in participants with non-segmental vitiligo.
- In 2025, Pfizer published a Phase 2b trial result combining oral ritlecitinib with narrowband UV-B phototherapy produced stronger facial repigmentation than ritlecitinib alone.
Report Coverage
The research report offers an in-depth analysis based on Drugs Type, Disease Indication, End-User Industry, Form, Purity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Emergence of targeted biologic treatments will improve repigmentation outcomes significantly.
- Deeper integration of stem cell and melanocyte transplantation techniques will address severe cases.
- Teledermatology services will expand access in rural and underserved areas.
- AI-powered diagnostic tools and personalized therapy plans will drive patient satisfaction.
- Portable phototherapy and home-use devices will increase treatment convenience.
- Regulatory agencies will approve more innovative therapies, boosting clinical adoption.
- Public awareness campaigns will reduce treatment stigma and encourage earlier intervention.
- Larger product pipelines will introduce immune-modulating treatments targeting autoimmune pathways.
- Combination therapies will become standard protocols for better responses and lower relapse.
- Emerging markets will invest in dermatology infrastructure and skilled professionals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hypopigmentation Disorder Treatment, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hypopigmentation Disorder Treatment market projected to grow between 2025 and 2032?
Which Hypopigmentation Disorder Treatment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hypopigmentation Disorder Treatment market?
Who are the leading companies in the Hypopigmentation Disorder Treatment market?
Which region commanded the largest share of the Hypopigmentation Disorder Treatment market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hypopigmentation Disorder Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hypopigmentation Disorder Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7.43 billion → 2032: USD 11.17 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hypopigmentation Disorder Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hypopigmentation Disorder Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hypopigmentation Disorder Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hypopigmentation Disorder Treatment Market Drivers
- 3.3 Hypopigmentation Disorder Treatment Market Restraints & Challenges
- 3.4 Hypopigmentation Disorder Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hypopigmentation Disorder Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hypopigmentation Disorder Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hypopigmentation Disorder Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hypopigmentation Disorder Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hypopigmentation Disorder Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hypopigmentation Disorder Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hypopigmentation Disorder Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hypopigmentation Disorder Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hypopigmentation Disorder Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hypopigmentation Disorder Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hypopigmentation Disorder Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hypopigmentation Disorder Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hypopigmentation Disorder Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hypopigmentation Disorder Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hypopigmentation Disorder Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hypopigmentation Disorder Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hypopigmentation Disorder Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hypopigmentation Disorder Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hypopigmentation Disorder Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
