
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ice Cream And Frozen Dessert Market Size 2024 | USD 138315 Million |
| Ice Cream And Frozen Dessert Market, CAGR | 8% |
| Ice Cream And Frozen Dessert Market Size 2032 | USD 256011.41 Million |
Market Overview:
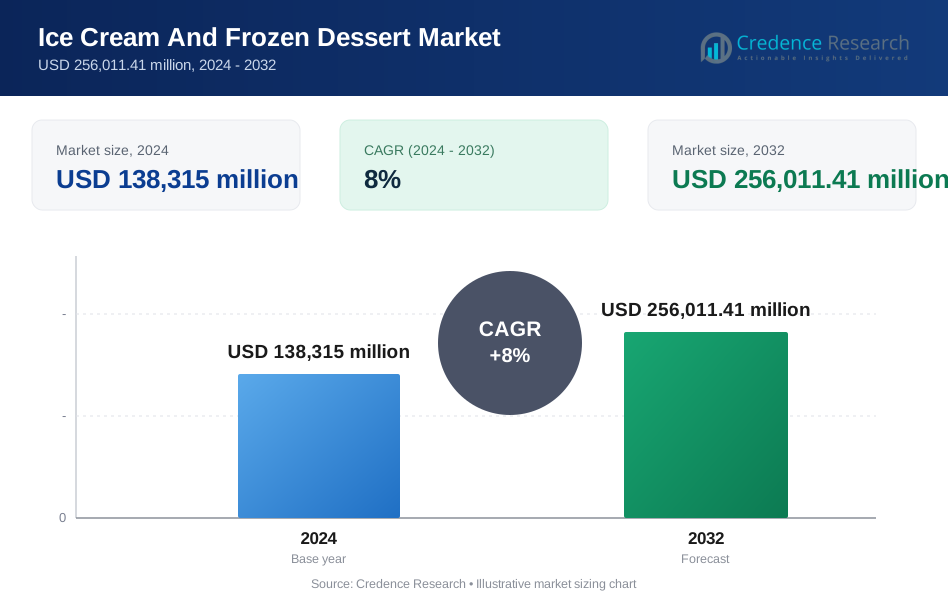
The Ice Cream And Frozen Dessert Market is projected to grow from USD 138315 million in 2024 to an estimated USD 256011.41 million by 2032, with a compound annual growth rate (CAGR) of 8% from 2024 to 2032.
Key drivers of the ice cream and frozen dessert market include the evolving consumer preferences for a wider variety of flavors and product formats. The rise of healthier alternatives, such as dairy-free, low-fat, and sugar-free options, is expanding the consumer base and attracting health-conscious individuals. Additionally, the growing popularity of premium and artisanal ice creams, with unique ingredients and flavors, has significantly contributed to market expansion. Convenience is another crucial factor, with increased demand for ready-to-eat products and online sales driving the growth of frozen desserts. The increasing availability of ice cream in diverse packaging sizes and formats, catering to individual consumption and family needs, also supports this growth. Moreover, seasonal and festive promotions continue to contribute to market acceleration, particularly in summer months.
North America dominates the ice cream and frozen dessert market, accounting for the largest share in 2024. The U.S. is the key contributor, driven by a well-established ice cream culture, high disposable incomes, and the presence of leading brands such as Ben & Jerry’s and Häagen-Dazs. In addition, North America's rising preference for premium ice cream and innovative flavors has led to significant growth in this region. Europe follows closely, with countries like Italy and France having a long-standing tradition of producing high-quality frozen desserts. The Asia-Pacific region is experiencing the fastest growth, with countries like China, India, and Japan showing increasing demand for both traditional and modern frozen dessert options. The region benefits from growing middle-class populations, improving distribution channels, and a shift in consumer tastes toward indulgent, exotic, and affordable frozen treats. Latin America and the Middle East & Africa are also gradually witnessing growth, particularly as global brands expand into emerging markets, tapping into the rising demand for frozen desserts in these regions.
Market Insights:
- The ice cream and frozen dessert market is projected to grow from USD 138,315 million in 2024 to USD 256,011.41 million by 2032, with a CAGR of 8%.
- Consumer demand for healthier alternatives, such as dairy-free, low-fat, and sugar-free options, is expanding the market to a broader audience.
- Product innovation, including unique and exotic flavors, artisanal offerings, and convenient packaging, continues to drive market growth and attract adventurous consumers.
- Rising disposable incomes, particularly in emerging economies, and changing consumer lifestyles are fueling the demand for indulgent frozen desserts.
- The increasing popularity of online sales and expanded distribution channels, such as supermarkets and convenience stores, is making frozen desserts more accessible.
- Premium ice creams and artisanal products are seeing increased demand as consumers seek high-quality, indulgent experiences.
- Seasonal fluctuations in demand, particularly in warmer months, create challenges for manufacturers, but also present opportunities for targeted promotions and limited-time offerings.
Market Drivers:
Increasing Consumer Demand for Healthier Options
The growing demand for healthier food options is a significant driver of the ice cream and frozen dessert market. As consumers become more health-conscious, there has been a surge in demand for dairy-free, low-fat, sugar-free, and organic frozen desserts. These products cater to individuals with dietary restrictions, such as lactose intolerance, gluten sensitivity, and vegan preferences. For instance, Ben & Jerry's has expanded its product line to include dairy-free options, which now account for 25% of their total sales. Manufacturers are responding to these shifts by innovating and creating frozen dessert alternatives that align with healthier lifestyles while still providing indulgence. This shift toward healthier and functional offerings is expanding the market to a broader audience, including those who are traditionally not heavy consumers of ice cream and frozen desserts.
Product Innovation and Variety
Product innovation remains a key driver of growth in the ice cream and frozen dessert market. Consumers now expect an array of flavors, textures, and formats that go beyond traditional offerings. Premium ice creams with exotic flavors, such as matcha, salted caramel, and lavender, have become increasingly popular. For example, Häagen-Dazs introduced a line of exotic flavors, including green tea and yuzu citrus, which have seen a increase in sales. Additionally, the rise of artisanal ice creams and small-batch productions, often featuring locally sourced ingredients, is further fueling this demand. In addition to flavor innovation, advancements in packaging, such as single-serve portions and resealable containers, are enhancing convenience and making frozen desserts more accessible for a variety of consumption occasions. This ongoing innovation across multiple dimensions is essential to the market's continued expansion.
Rising Disposable Income and Changing Lifestyles
The growth in disposable income and changing consumer lifestyles are also major factors driving the ice cream and frozen dessert market. As disposable incomes rise, particularly in emerging economies, more consumers are opting for indulgent treats as a form of leisure and enjoyment. For instance, in India, the increase in disposable income has led to rise in premium ice cream sales. Moreover, rapid urbanization and busy, fast-paced lifestyles have increased the demand for convenient, ready-to-eat products like ice cream and frozen desserts. This has prompted manufacturers to introduce products that cater to on-the-go consumers, such as ice cream bars and portable cups. In developed economies, consumers are willing to spend more on premium, high-quality ice cream offerings, further boosting market growth.
Expanding Distribution Channels and Online Sales
The expansion of distribution channels, especially online sales, is a crucial driver of market growth. E-commerce platforms are making it easier for consumers to access a wider range of frozen dessert products, with home delivery services allowing people to purchase ice cream and frozen treats with greater convenience. For example, during the COVID-19 pandemic, Hindustan Unilever reported a significant increase in online sales for their ice cream business. This trend has been particularly prominent during the COVID-19 pandemic, as consumers increasingly turn to online shopping for food and grocery items. In addition, supermarkets, hypermarkets, and convenience stores are expanding their frozen dessert sections, providing a larger selection of products that cater to varying consumer needs. This enhanced availability of products through multiple distribution channels is driving the growth of the ice cream and frozen dessert market, ensuring that consumers can easily access their favorite treats.
Market Trends:
Premiumization and Artisanal Offerings
The trend toward premiumization is significantly shaping the ice cream and frozen dessert market. Consumers are increasingly willing to pay more for high-quality, artisanal products that offer unique flavors and premium ingredients. This trend includes the growing demand for small-batch, locally sourced, and organic ice creams, as well as those crafted with natural or sustainable ingredients. For instance, Sucres Des Terres in Mumbai creates small-batch artisanal ice creams in 500ml mason jars, featuring unique flavors like Mango Mascarpone and Orange Rosemary. Their Bean To Jar and Salted Caramel remain bestselling flavors. These products cater to discerning consumers seeking indulgent yet sophisticated frozen desserts. This shift towards premium products is expanding the market, with brands focusing on high-end, gourmet offerings to attract this growing consumer segment.
Rise of Non-Dairy and Plant-Based Alternatives
Non-dairy ice creams and frozen desserts have experienced significant growth, driven by the increasing number of consumers adopting vegan, lactose-free, and dairy-free diets. Plant-based ice creams made from almond, coconut, and oat milks, among other alternatives, are becoming mainstream. This trend is not only fueled by dietary preferences but also by environmental sustainability concerns. Plant-based desserts are appealing to health-conscious consumers, offering lower environmental impact compared to traditional dairy products. As a result, many established ice cream brands are expanding their offerings to include these alternatives to meet consumer demand for more inclusive options. For instance, Ben & Jerry's e-commerce platform offers traditional and non-dairy pints through store.benjerry.com.
Product Innovation and Exotic Flavors
Innovative flavors and unique combinations continue to be a major trend within the ice cream and frozen dessert industry. Consumers, especially younger demographics, are increasingly seeking more adventurous and exotic flavors beyond traditional varieties. Popular trends include the introduction of matcha, salted caramel, exotic fruit combinations, and even spicy options such as chili chocolate. For instance, Cold Love demonstrates premium crafting with exclusive flavors like Boozy Bailey's and Pink Guava Sorbet, using only natural ingredients without artificial additives. These bold and unconventional flavor offerings not only capture the interest of adventurous consumers but also provide brands with opportunities to differentiate themselves in a competitive market. Additionally, functional frozen desserts, such as those with added superfoods or probiotics, are becoming increasingly popular among health-conscious buyers.
E-commerce and Direct-to-Consumer Growth
E-commerce and direct-to-consumer (DTC) models are rapidly growing trends in the ice cream and frozen dessert market. Online platforms offer consumers the convenience of ordering frozen desserts from the comfort of their homes, with many brands offering home delivery services. This trend was particularly accelerated during the COVID-19 pandemic but continues to show growth as consumers appreciate the convenience and variety that e-commerce provides. Subscription-based services are also gaining traction, where customers can receive regular deliveries of their favorite ice cream or frozen desserts. For example, Graeter's Ice Cream offers a subscription service that delivers pints of their artisanal ice cream directly to customers' doors. As more brands embrace online retail, this trend is expected to continue shaping the market, particularly as consumer behavior shifts further toward digital purchasing.
Market Challenges Analysis:
High Production and Distribution Costs
One of the primary challenges facing the ice cream and frozen dessert market is the high cost of production and distribution. The production of quality frozen desserts, especially premium products that use organic, natural, or locally sourced ingredients, requires significant investment. Additionally, maintaining the appropriate storage conditions for frozen products throughout the distribution chain—such as refrigeration and temperature control—adds to operational expenses. These high costs can result in higher retail prices, which may limit the affordability and accessibility of these products for a wider range of consumers, especially in emerging markets where disposable income is lower.
Seasonal Demand Fluctuations
The demand for ice cream and frozen desserts tends to be highly seasonal, with consumption peaking during warmer months, particularly in summer. This creates significant revenue fluctuations for manufacturers and retailers, making it difficult to maintain consistent sales throughout the year. Companies often face inventory and supply chain challenges, particularly when demand peaks unexpectedly or when there is a sudden shift in weather conditions. Seasonal variations can lead to inefficiencies in production planning and distribution, ultimately affecting profitability.
Health Concerns and Changing Consumer Preferences
Despite increasing demand for indulgent treats, health concerns surrounding high sugar content, fat, and artificial additives in traditional ice creams and frozen desserts remain a key restraint. Growing awareness of the negative health effects of excessive sugar consumption, particularly among children, has led to a shift toward healthier alternatives. While manufacturers are responding with reduced-fat and sugar-free options, some consumers still avoid ice cream and frozen desserts entirely, opting instead for other snacks that are perceived as healthier. This presents an ongoing challenge for the market, requiring manufacturers to continually innovate in order to address these evolving consumer preferences.
Regulatory and Compliance Challenges
The ice cream and frozen dessert market is subject to stringent regulatory requirements related to food safety, labeling, and ingredient transparency. These regulations vary across regions, and ensuring compliance with these standards can be complex, particularly for global brands. Changes in government policies related to labeling, sugar content, or environmental sustainability can require substantial adjustments to product formulations and marketing strategies. Navigating these regulations can be costly and time-consuming for manufacturers, particularly smaller companies without the resources to manage compliance effectively.
Market Opportunities:
The ice cream and frozen dessert market presents significant opportunities, particularly in the growing demand for healthier alternatives and plant-based options. As more consumers shift toward vegan, lactose-free, and dairy-free diets, the demand for non-dairy frozen desserts made from almond, coconut, oat, and soy milk is rapidly increasing. This trend is particularly strong in North America and Europe, where consumer preferences are evolving towards cleaner, more sustainable ingredients. Manufacturers who can innovate and cater to these dietary preferences have the potential to capture a large and expanding market segment. Furthermore, the rising awareness about environmental sustainability presents an opportunity to offer products with eco-friendly packaging and responsibly sourced ingredients, further appealing to eco-conscious consumers.
Additionally, the premiumization trend offers considerable growth potential. As disposable incomes rise, particularly in emerging markets such as Asia-Pacific and Latin America, there is a growing demand for premium and artisanal ice creams. This trend is driven by consumers' willingness to pay more for high-quality, small-batch, and gourmet products that offer unique flavors and high-end ingredients. Brands that invest in product differentiation, such as organic, non-GMO, or indulgent flavors, stand to benefit from this trend. Furthermore, the expansion of e-commerce platforms for ice cream and frozen desserts presents an opportunity for direct-to-consumer sales, enabling brands to reach broader audiences and offer customized subscription services. These opportunities highlight a dynamic and evolving market, with significant potential for growth in various consumer segments.
Market Segmentation Analysis:
The ice cream and frozen dessert market is segmented by type, distribution channel, and region, highlighting diverse opportunities across multiple consumer segments.
By Type, the market is primarily divided into frozen yogurt, frozen cakes, ice cream, and others. Ice cream holds the largest market share, driven by its wide consumer appeal and variety of flavors. Frozen yogurt is gaining popularity, particularly among health-conscious consumers seeking lower-fat alternatives. Frozen cakes, including ice cream cakes, are growing in demand, especially for celebrations and special occasions. The "others" category includes novelties like ice cream bars, sandwiches, and dairy-free frozen desserts, which are becoming increasingly popular due to changing consumer preferences.
By Distribution Channel, supermarkets and hypermarkets dominate the market, offering consumers a wide variety of frozen desserts in one location. Convenience stores are also growing in importance as they provide easy access to impulse purchases, especially in urban areas. Specialty stores, including those focusing on premium or health-conscious products, are attracting a niche but growing customer base. Other channels, such as e-commerce and direct-to-consumer sales, are expanding as online grocery shopping and home delivery services rise in popularity.
Segmentation:
By Type:
- Frozen Yogurt
- Frozen Cakes
- Ice Cream
- Others
By Distribution Channel:
- Supermarkets/Hypermarkets
- Convenience Stores
- Specialty Stores
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is the dominant region in the ice cream and frozen dessert market, holding the largest market share of approximately 35% in 2024. The United States, in particular, is the key contributor, driven by a well-established ice cream culture and the presence of leading brands such as Ben & Jerry’s, Häagen-Dazs, and Nestlé. The region’s strong retail infrastructure and high disposable incomes further support the market’s growth. In addition, the increasing demand for premium and innovative products, including non-dairy, sugar-free, and low-fat options, is expanding the consumer base. Convenience and e-commerce have also played a significant role, especially during the COVID-19 pandemic, with more consumers opting for online ordering and home delivery of frozen desserts.
Europe
Europe accounts for around 30% of the global ice cream and frozen dessert market share, with countries like Italy, France, and Germany being key contributors. Italy, with its long history of gelato production, continues to be one of the largest consumers of premium ice cream in Europe. France follows closely with a strong tradition of high-quality frozen desserts. In recent years, Europe has seen a rise in demand for healthier and plant-based alternatives, reflecting a broader trend toward sustainable and health-conscious eating habits. Additionally, the region’s focus on premiumization and innovation in flavors, such as exotic fruits and indulgent desserts, contributes to the overall growth of the market.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the ice cream and frozen dessert market, with a projected share of 25% by 2024. This growth is primarily driven by rising disposable incomes, urbanization, and changing consumer preferences in countries like China, India, and Japan. In particular, China is a significant market due to its large population and increasing middle-class consumers who are spending more on indulgent treats like ice cream. India is also witnessing rapid growth, with a younger population that is increasingly inclined to try innovative and premium flavors. Japan’s preference for unique and seasonal flavors continues to influence the market, making the Asia-Pacific region a key area for growth and opportunity.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for about 10% of the market share. In Latin America, countries such as Brazil and Mexico are seeing increasing demand for frozen desserts, driven by both local brands and international players expanding their reach. The Middle East & Africa, while smaller in market size, is experiencing growing interest in premium and luxury frozen desserts, particularly in urban areas. Rising incomes, along with the influence of Western food culture, are boosting market demand in these regions. Both regions offer significant growth potential as market penetration increases and consumer preferences evolve.
Key Player Analysis:
- Baskin-Robbins
- Ben & Jerry's Homemade Holdings Inc.
- Breyers Ice Cream
- Casper’s Ice Cream
- Cielo USA
- Danone Groupe SA
- Graeter’s Ice Cream
- Kraft Foods Group Inc.
- Nestle SA
- Unilever
Competitive Analysis:
The ice cream and frozen dessert market is highly competitive, with key players such as Unilever, Nestlé, General Mills, and Mars Inc. dominating the industry. These companies leverage strong brand recognition, extensive distribution networks, and significant investments in research and development to maintain their market positions. They continue to innovate, introducing new flavors, healthier options, and plant-based alternatives to cater to evolving consumer preferences. Additionally, premium and artisanal brands like Ben & Jerry’s and Häagen-Dazs are capitalizing on the growing demand for high-quality and unique frozen desserts. Ben & Jerry’s has expanded its product line to include dairy-free options, which now account for 25% of their total sales. The market also sees the emergence of smaller, regional players offering specialized products, particularly in the premium and health-conscious segments. E-commerce and direct-to-consumer models are gaining traction, with both established and new players focusing on online sales and subscription-based services. As a result, companies are increasingly using technology and consumer data to create personalized offerings and drive brand loyalty.
Recent Developments:
- In March 2024, Oreo launched a new line of mint-flavored frozen treats, including bars, sandwiches, and a scoopable tub. These products feature mint creme-flavored frozen dairy with Oreo cookie pieces, inspired by the iconic mint Oreo cookies.
- In February 2024, Katoomba Global Foods entered the frozen dessert market with a premium Indian kulfi ice cream range. The dense dessert combines Australia-made kulfi with India's Parle G biscuits, creating a unique fusion for dessert enthusiasts.
- In May 2023, Häagen-Dazs introduced oat-based, vegan-certified frozen desserts in Canada, produced locally in London, Ontario. The products are designed for plant-based consumers who seek creamy textures and indulgent flavors without compromising taste.
- In July 2023, Snoop Dogg and Happi Co. launched Dr. Bombay Ice Cream in 3,500 Walmart stores. The line, priced at $4.98 each, offers seven flavors, including Bonus Track Brownie and Tropical Sherbet Swizzle, inspired by Snoop Dogg's NFT character.
- In January 2024, Oatly and Carvel partnered to offer dairy-free options across 18 states. The line includes strawberry soft serve, cookies and cream, chocolate peanut butter, flying saucer sandwiches, and frozen dessert cakes, allowing consumers to enjoy a dairy-free Carvel experience.
Market Concentration & Characteristics:
The ice cream and frozen dessert market is moderately concentrated, with several dominant global players holding significant market shares. Companies such as Unilever, Nestlé, General Mills, and Mars Inc. lead the market due to their vast product portfolios, strong brand presence, and extensive distribution channels. These players dominate the mass-market segment but also compete in premium and niche markets, particularly with products catering to health-conscious consumers and those seeking indulgent, artisanal options. The market is also characterized by the rise of smaller, specialized brands offering unique, high-quality, or plant-based products to meet the growing demand for diverse choices. This trend has led to the emergence of local and artisanal ice cream producers who focus on customization, organic ingredients, and sustainability. While global players maintain a stronghold, the market is dynamic, with competition intensifying in premium, functional, and plant-based product categories.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to continue growing, driven by increasing consumer demand for healthier, low-fat, and sugar-free alternatives.
- Premium and artisanal ice creams will see increased popularity as consumers seek higher quality and unique flavor experiences.
- Plant-based and dairy-free frozen desserts will become more mainstream, supported by the growing vegan and lactose-free population.
- Technological advancements in production processes will lead to more efficient and cost-effective manufacturing, benefiting both large and small producers.
- E-commerce platforms will expand, with more brands offering direct-to-consumer models and home delivery services.
- Sustainability will become a key focus, with eco-friendly packaging and sustainable sourcing gaining importance.
- The rise of functional frozen desserts, such as those with added superfoods or probiotics, will cater to health-conscious consumers.
- Emerging markets in Asia-Pacific and Latin America will experience strong growth due to rising disposable incomes and changing consumer habits.
- Companies will continue to innovate with exotic and local flavors to cater to adventurous consumers.
- Collaborations and acquisitions will increase as larger players seek to diversify their product offerings and expand into new markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the ice cream and frozen dessert market?
What are the main drivers of the ice cream and frozen dessert market?
Which region dominates the ice cream and frozen dessert market?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ice Cream And Frozen Dessert Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ice Cream And Frozen Dessert Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 138,315 million → 2032: USD 256,011.41 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ice Cream And Frozen Dessert Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ice Cream And Frozen Dessert Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ice Cream And Frozen Dessert Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ice Cream And Frozen Dessert Market Drivers
- 3.3 Ice Cream And Frozen Dessert Market Restraints & Challenges
- 3.4 Ice Cream And Frozen Dessert Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ice Cream And Frozen Dessert Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ice Cream And Frozen Dessert Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ice Cream And Frozen Dessert category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ice Cream And Frozen Dessert Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ice Cream And Frozen Dessert Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ice Cream And Frozen Dessert market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ice Cream And Frozen Dessert Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ice Cream And Frozen Dessert Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ice Cream And Frozen Dessert Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ice Cream And Frozen Dessert (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ice Cream And Frozen Dessert Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ice Cream And Frozen Dessert Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ice Cream And Frozen Dessert Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ice Cream And Frozen Dessert Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ice Cream And Frozen Dessert Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ice Cream And Frozen Dessert Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ice Cream And Frozen Dessert Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ice Cream And Frozen Dessert Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ice Cream And Frozen Dessert Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
