
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| In Store Theater Packaging Market Size 2024 | USD 44,614.5 million |
| In Store Theater Packaging Market, CAGR | 18.9% |
| In Store Theater Packaging Market Size 2032 | USD 178,209.5 million |
Market Overview:
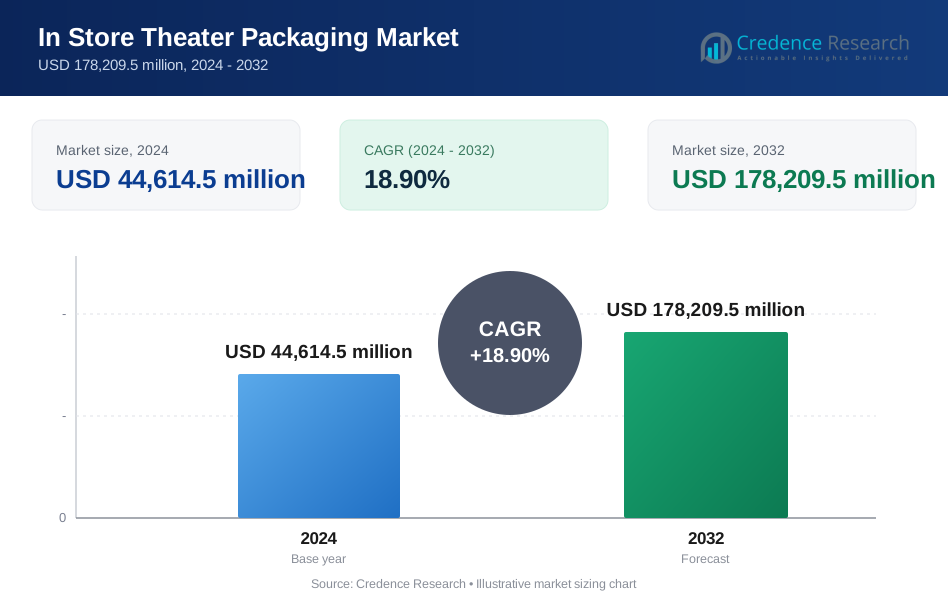
The global in-store theater packaging market size was valued at USD 44,614.5 million in 2024 and is anticipated to reach USD 178,209.5 million by 2032, at a CAGR of 18.9% during the forecast period. (2024-2032)
This growth is driven by the increasing demand for impactful and eye-catching retail displays that enhance customer engagement and brand visibility. The market's expansion is also attributed to the rising adoption of innovative and customizable packaging solutions by retailers and brands. Several factors are driving the growth of the In Store Theater Packaging Market. The growing emphasis on enhancing consumer experience and optimizing shelf visibility is a significant contributor. Retailers and brands are increasingly adopting digital printing, lightweight materials, and sustainable packaging solutions to attract customers and differentiate their products. The demand for in-store theater packaging solutions is also fueled by the need for product-specific designs that promote seasonal and promotional campaigns. Additionally, the use of LED screens and other beautification elements in theater packaging is gaining popularity, further driving market growth.
Regionally, North America holds the largest share of the In Store Theater Packaging Market, driven by the high demand for innovative retail displays and the presence of a well-established retail industry. Europe follows closely, with significant growth attributed to the increasing adoption of sustainable packaging solutions and supportive government initiatives. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, primarily due to the rising retail industry, increasing urbanization, and growing consumer awareness in emerging economies such as China and India. The market in Latin America and the Middle East & Africa is also expected to grow steadily, driven by improving retail infrastructure and increasing adoption of modern marketing techniques. These factors collectively contribute to the robust growth of the In Store Theater Packaging Market, making it a vital component of the global retail industry.
Market Insights:
- The global in-store theater packaging market is projected to grow from USD 44,614.5 million in 2024 to USD 178,209.5 million by 2032, driven by increasing brand engagement strategies and high-impact packaging adoption.
- Over 70% of purchasing decisions occur in-store, fueling demand for visually compelling, strategically positioned packaging solutions that enhance brand visibility and impulse buying.
- Over 60% of consumers prefer eco-friendly packaging, prompting brands to invest in recyclable cardboard structures, biodegradable printing solutions, and low-carbon materials.
- Experiential retail strategies have driven a 40% rise in impulse purchases, pushing companies to integrate AI-powered analytics, augmented reality (AR), and smart packaging into in-store displays.
- The U.S. retail sector, valued at over USD 5 trillion, leads in interactive and sustainable packaging solutions, with brands investing USD 200 billion annually in in-store marketing.
- China’s smart packaging market is growing at 20% annually, with retailers adopting QR code-enabled displays and AI-powered signage to attract digital-savvy consumers.
- High costs of advanced packaging materials and digital integration remain barriers, requiring brands to balance innovation with cost efficiency.
Market Drivers:
Heightened Emphasis on Captivating In-Store Experiences:
A primary driver fueling the in-store theater packaging market is the rising demand for captivating in-store experiences. With a notable 70% of purchase decisions occurring within retail stores, the in-store environment significantly influences consumer behavior. This has led brands and store owners to focus on product displays as a crucial element for successfully converting potential customers into actual buyers. For instance, retailers are increasingly adopting retail-ready packaging solutions to establish guidelines assisting in standardizing and transitioning their shelves to showcase the latest package designs, creating a visually appealing and engaging shopping atmosphere.
Growing E-commerce Proliferation and Need for Standout Packaging:
The proliferation of e-commerce is indirectly driving the in-store theater packaging market by emphasizing the need for brick-and-mortar stores to offer unique and engaging experiences that differentiate them from online shopping. As online spending has grown to unprecedented levels, with a 35% year-on-year rise in the United States, brick-and-mortar stores need to provide compelling reasons for consumers to visit and make purchases. For instance, retailers are focusing on creating visually appealing displays and interactive packaging to capture consumer attention and drive impulse purchases in physical stores. This trend encourages the use of in-store theater packaging to enhance the shopping experience and create a memorable brand impression.
Reduction in Operating Expenses and Packaging Waste:
The in-store theater packaging market is further propelled by its capacity to aid in reducing packaging waste and lowering operating expenses for retailers. Retail-ready packaging (RRP) reduces the need for excessive labor in unpacking and stocking shelves, streamlining operations and improving efficiency. For instance, stores can benefit from die-cut display containers' ability to expedite stock shelves and increase shelf-space efficiency. RRPs are also preferred for facilitating efficient customer shopping and encouraging impulsive buying behaviors. By adopting in-store theater packaging solutions, retailers can optimize their supply chains and make inventory storage and logistics more cost-effective.
Integration of Smart Packaging Solutions:
The increasing integration of smart packaging solutions with rigid packaging formats is positively impacting the market. Technologies such as QR codes and sensors are becoming increasingly prevalent, improving inventory management and enhancing visibility within the supply chain. For instance, incorporating augmented reality (AR) and virtual reality (VR) into packaging designs can enhance the consumer experience and provide valuable product information, driving consumer engagement and brand loyalty. This trend toward smart packaging solutions enhances the appeal of in-store theater packaging, making it a more attractive option for retailers seeking to create interactive and informative displays that captivate consumers and drive sales.
Market Trends:
Emphasis on Sustainability and Eco-Friendly Materials:
A significant trend in the in-store theater packaging market is the strong emphasis on sustainability and the utilization of eco-friendly materials. Driven by increasing environmental awareness and consumer demand for sustainable products, brands and retailers are actively seeking packaging solutions that minimize their environmental impact. For instance, companies are exploring innovative materials like paper wrapping for chocolate and edible algae packaging to reduce waste and appeal to eco-conscious consumers.
Integration of Digital Technologies for Enhanced Engagement:
The in-store theater packaging market is witnessing a growing trend of integrating digital technologies, such as augmented reality (AR), virtual reality (VR), and QR codes, to enhance consumer engagement and create interactive shopping experiences. These technologies offer opportunities for brands to provide additional product information, personalized content, and immersive experiences that capture consumer attention and drive sales. For instance, incorporating AR into packaging designs allows consumers to access virtual product demonstrations or interactive games through their smartphones, creating a memorable and engaging brand interaction.
Focus on Personalization and Customization:
Personalization and customization are becoming increasingly important in the in-store theater packaging market, as brands seek to create unique and tailored experiences for individual consumers. By leveraging data analytics and customer insights, brands can develop personalized packaging designs and messaging that resonate with specific consumer segments, fostering stronger brand loyalty and driving purchase decisions. For instance, offering customized packaging options or incorporating personalized content based on consumer preferences can enhance the perceived value of the product and create a more meaningful shopping experience.
Rising Popularity of Retail-Ready Packaging (RRP) Solutions:
The retail-ready packaging (RRP) segment is experiencing rising popularity as it offers convenience to both consumers and store managers. RRP solutions are designed to be easily opened, stocked, and displayed on shelves, reducing labor costs and improving efficiency in retail operations. For instance, the implementation of retail-ready packaging solutions assists in standardizing and transitioning shelves to showcase the latest package designs, creating a visually appealing and engaging shopping atmosphere. Moreover, RRP enhances brand visibility and product presentation, driving impulse purchases and increasing sales.
Market Challenges Analysis:
High Implementation Costs and ROI Uncertainty:
One of the primary restraints in the in-store theater packaging market is the high cost associated with developing and implementing innovative packaging solutions. Designing interactive displays, integrating augmented reality, and utilizing premium materials can significantly increase packaging expenses. Retailers, particularly smaller businesses, may hesitate to invest in in-store theater packaging due to budgetary constraints and uncertainty regarding the return on investment (ROI). The cost of incorporating advanced digital signage technology and customized packaging can be prohibitive for some businesses, especially when compared to traditional packaging options.
Complexity in Design and Execution:
The complexity involved in designing and executing effective in-store theater packaging presents a significant challenge. Creating engaging and memorable experiences requires coordination across multiple departments and stakeholders, including designers, marketers, and supply chain managers. Implementing augmented reality features necessitates collaboration with software developers and content creators, adding to the complexity and potential for delays or errors. Streamlining this process and ensuring seamless integration of various elements can be demanding and time-consuming.
Regulatory Scrutiny and Sustainability Concerns:
The in-store theater packaging market faces increasing scrutiny from regulatory bodies and consumers regarding sustainability and environmental impact. Government regulations, such as those related to packaging waste and recyclability, are becoming more stringent, requiring companies to adopt eco-friendly materials and practices. The European Union (EU) has implemented regulations aimed at reducing packaging waste and promoting circular economy principles, pushing companies to minimize the environmental footprint of their packaging solutions. Additionally, consumers are increasingly conscious of the environmental impact of packaging and may prefer products with minimal or sustainable packaging, creating pressure on brands to adopt more eco-friendly alternatives.
Market Opportunities:
The in-store theater packaging market presents significant opportunities driven by shifting consumer behavior, digital retail integration, and sustainability trends. As over 70% of purchasing decisions are made in-store, brands are investing in high-impact, interactive packaging solutions to capture consumer attention and enhance engagement. The rise of experiential retail, where consumers seek immersive shopping experiences, is fueling demand for AI-driven packaging displays, augmented reality (AR) elements, and LED-enhanced signage. Retailers implementing in-store theater packaging have reported up to a 40% increase in impulse purchases, demonstrating its effectiveness in driving sales and brand visibility. Additionally, as the global luxury retail market surpasses USD 350 billion, premium brands are leveraging theatrical packaging designs to create exclusive, high-value in-store experiences.
Sustainability presents another key growth avenue, as over 60% of consumers prefer eco-friendly packaging solutions. The shift toward biodegradable materials, recyclable cardboard structures, and low-carbon production methods is encouraging brands to adopt green packaging innovations. Government regulations, such as the EU’s Green Deal and U.S. extended producer responsibility (EPR) policies, are further incentivizing the adoption of sustainable in-store displays. Meanwhile, the expansion of omnichannel retail strategies is integrating smart packaging technologies, allowing brands to connect in-store experiences with digital engagement through QR codes, NFC tags, and AI-powered analytics. As retailers seek to differentiate themselves in an increasingly competitive landscape, businesses that invest in innovative, sustainable, and technology-driven in-store theater packaging will gain a strong competitive advantage.
Market Segmentation Analysis:
By Material
The market includes paper & paperboard, plastic, metal, glass, and biodegradable materials. Paper & paperboard dominate the segment, accounting for over 45% of total market demand, due to their eco-friendly nature, cost-effectiveness, and ease of customization. The rising global sustainability movement, where over 60% of consumers prefer recyclable packaging, is driving increased adoption of FSC-certified paper-based in-store displays. Biodegradable materials are also gaining traction, fueled by government regulations promoting plastic-free retail packaging. Meanwhile, plastic remains relevant for high-durability and transparent display solutions, particularly in electronics and luxury product segments.
By End User
Key end-user industries include retail, food & beverage, cosmetics & personal care, electronics, and automotive. The retail sector holds the largest share, with supermarkets, hypermarkets, and convenience stores investing heavily in high-impact point-of-sale (POS) displays to boost impulse purchases. The food & beverage industry is another major contributor, as brands enhance visual merchandising strategies with LED-lit, interactive packaging solutions to attract customers. Cosmetics & personal care brands are increasingly adopting digital integration in packaging, with AI-powered displays and augmented reality (AR) features enhancing consumer engagement. The electronics and automotive industries leverage in-store theater packaging for premium branding, product demonstrations, and interactive display solutions to elevate the customer shopping experience.
Segmentations:
By Material
- Paperboard
- Kraft Paper
By End Use
- Food & Beverages
- Grocery Products
- Pharmaceutical
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America dominates the in-store theater packaging market, accounting for 35% of global market share. The region’s growth is fueled by high retail investments, strong consumer engagement strategies, and advancements in point-of-sale (POS) marketing. For instance, the U.S. retail industry, valued at over USD 5 trillion, allocates more than USD 200 billion annually to in-store marketing, including theater-style packaging and interactive retail displays. Research shows that over 70% of in-store purchases in the U.S. are influenced by display-driven promotions, underscoring the significance of strategic and visually engaging packaging solutions. Leading retailers like Walmart, Target, and Costco have reported a 25% increase in impulse purchases after integrating LED-enhanced and motion-activated packaging solutions. The demand for eco-friendly in-store displays is also rising, with surveys indicating that over 60% of U.S. consumers prefer brands that utilize sustainable packaging materials, prompting retailers to adopt biodegradable and recyclable cardboard displays.
Asia-Pacific:
Asia-Pacific holds 30% of the global market share and remains the fastest-growing region. The rapid expansion is attributed to increasing retail infrastructure, rising disposable incomes, and digital transformation in brick-and-mortar stores. For instance, China’s smart packaging sector is growing at a rate of 20% annually, with retailers integrating AI-powered displays, QR code-enabled packaging, and augmented reality (AR) in their marketing strategies to engage tech-savvy consumers. India’s retail sector has grown by over 25% in the past five years, with brands focusing on customized, high-impact packaging solutions to drive in-store conversions. Japan, recognized for its expertise in automation and sensor-based packaging, has seen a 15% rise in demand for motion-activated in-store displays, particularly in luxury goods and electronics retail. The rise of experiential retail in the region has led to a surge in investments in LED-integrated and interactive packaging solutions, enhancing the consumer shopping experience and brand recall.
Europe:
Europe accounts for 20% of the global in-store theater packaging market share, driven by strict sustainability regulations, premium branding strategies, and high consumer engagement in retail. For instance, Germany, France, and the UK together account for over 60% of Europe's demand for sustainable in-store packaging, as retailers increasingly comply with EU Green Deal policies and plastic reduction mandates. Research suggests that over 50% of European brands are now using recyclable materials in their in-store packaging, reflecting growing consumer preference for eco-friendly and low-carbon packaging solutions. The demand for digital signage, LED-integrated displays, and AI-driven retail technologies is also rising, with companies experiencing a 30% increase in consumer engagement after integrating interactive packaging formats. Additionally, the expansion of premium and luxury retail brands in Europe has fueled the adoption of high-quality, immersive packaging solutions, further strengthening the region’s position as a high-value packaging market.
Latin America and Middle East & Africa:
Latin America and the Middle East & Africa (MEA) together account for 15% of the global market share, supported by expanding urban retail markets and increasing investments in in-store marketing strategies. For instance, Brazil’s retail sector has grown by 12% annually, prompting major brands to invest in customized, brand-centric in-store displays that enhance consumer interaction and sales conversions. In Mexico, retailers implementing LED and smart packaging solutions have reported a 20% increase in customer engagement, highlighting the potential for digital transformation in point-of-sale marketing.
In the Middle East & Africa, the rise of luxury retail investments is fueling market expansion. For instance, Saudi Arabia and the UAE have invested over USD 500 million in premium retail infrastructure, driving the demand for high-end in-store theater packaging in luxury fashion, cosmetics, and consumer electronics. The Middle East’s luxury retail market is expected to grow by 15% annually, increasing the need for visually striking and immersive in-store display solutions. However, import costs and limited local manufacturing capabilities continue to challenge market growth, leading to a surge in regional production partnerships and investments in domestic packaging facilities to meet rising demand.
Key Player Analysis:
- Spectrio
- Screenfeed
- Visua
- Retail Digital Signage
- MiraSign
- Fision
- Mood Media
- Captivate, Inc.
- InReality
- SignStix
Competitive Analysis:
The in-store theater packaging market is highly competitive, with key players focusing on innovation, sustainability, and digital integration to enhance consumer engagement and drive brand visibility. For instance, industry leaders such as DS Smith, Smurfit Kappa, WestRock, and International Paper collectively account for over 50% of the global market share, leveraging advanced customized POS displays, LED-enhanced packaging, and eco-friendly materials to attract retailers and brands. Over 70% of global retailers report that in-store display marketing significantly influences consumer purchasing decisions, pushing companies to develop AI-driven smart packaging solutions that analyze foot traffic and optimize product placements. The growing demand for sustainable and recyclable packaging materials has led companies to invest in biodegradable cardboard structures and water-based printing technologies, with over 60% of brands prioritizing low-carbon packaging solutions. Strategic partnerships and acquisitions are shaping the competitive landscape, as firms expand their global footprint and technological capabilities.
Recent Developments:
-
- In January 2025 Spectrio highlighted key milestones achieved in 2024, including advancements in its Retail Media Network offerings. These advancements deliver a fully integrated solution that empowers businesses to transform their physical spaces into revenue-driving, customer-engaging environments.
- In January 2025 Signagelive teamed up with Screenfeed to offer cost-effective pricing on Screenfeed’s premium content. This includes a library of news, sports, and curated social media feeds and the potential to create data-driven, automated content via Screenfeed Connect.
- In October 2024 AD Retail Media, the advertising arm of Ahold Delhaize USA, announced enhanced in-store audio solutions for brands like Food Lion, Giant Food, and Stop & Shop.
- In November 2024 Xibo Blog highlighted the top 7 retail digital signage trends in 2025, including the growth of Retail Media Networks, retail automation, smart shelves, and interactive experiences. The blog emphasizes how retailers can use these digital solutions to create personalized experiences and boost sales.
Market Concentration & Characteristics:
The in-store theater packaging market is moderately concentrated, with a mix of global packaging giants and specialized retail display solution providers competing for market share. leading companies such as DS Smith, Smurfit Kappa, WestRock, and International Paper collectively hold over 50% of the global market, leveraging their strong production capabilities and expertise in high-impact retail displays. The market is characterized by rapid technological innovation, increasing demand for sustainable materials, and the integration of digital enhancements such as LED displays and AI-driven smart packaging. Retailers are prioritizing customized and interactive packaging solutions, with research showing that over 70% of consumer purchase decisions are influenced by in-store displays. Additionally, the shift toward eco-friendly materials has led to a surge in demand for recyclable cardboard, biodegradable printing inks, and low-carbon production processes, shaping the future of sustainable in-store marketing solutions.
Report Coverage:
The research report offers an in-depth analysis based on Material, End Use, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Retailers will increasingly invest in AI-powered packaging solutions to enhance in-store engagement, with smart displays analyzing foot traffic and optimizing product placement for higher conversion rates.
- Sustainability will be a key driver, as brands shift toward biodegradable, recyclable, and low-carbon materials, responding to consumer demand for eco-friendly retail packaging solutions.
- The integration of LED-enhanced displays and digital signage in packaging will grow, as retailers leverage interactive visuals and motion-activated elements to capture shopper attention.
- Experiential retail will continue expanding, with immersive packaging solutions, augmented reality (AR), and QR-code-enabled interactions driving consumer engagement.
- Luxury brands will invest more in premium in-store displays, using high-end materials, custom designs, and digital enhancements to create exclusive and high-impact shopping experiences.
- North America and Europe will continue leading in-store theater packaging adoption, while Asia-Pacific will experience the fastest growth, fueled by expanding retail infrastructure and digital transformation.
- Personalization and customization trends will drive innovation, with brands using AI and data analytics to create localized and consumer-specific packaging designs.
- Retailers will integrate omnichannel strategies, connecting physical store packaging with e-commerce experiences through scannable codes, digital loyalty programs, and interactive elements.
- Regulatory pressures on plastic reduction will accelerate the transition to paper-based and compostable packaging, impacting material sourcing strategies globally.
- Strategic mergers and acquisitions will shape the competitive landscape, as major packaging firms expand their capabilities in digital, sustainable, and high-impact retail solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Emphasis on Captivating In-Store Experiences
With over 70% of purchase decisions made in-store, brands and retailers are investing in visually impactful and interactive packaging to enhance consumer engagement and drive impulse purchases.
Sustainability and Eco-Friendly Packaging
Rising consumer preference for recyclable and biodegradable materials, along with regulatory pressures such as the EU Green Deal, is pushing brands to adopt sustainable in-store theater packaging solutions.
Integration of Digital and Smart Technologies
The adoption of augmented reality (AR), LED displays, and AI-powered analytics in packaging is enabling retailers to create immersive, data-driven experiences that increase shopper engagement and optimize product placement.
Growth of Experiential and Omnichannel Retail
As brick-and-mortar stores compete with e-commerce, experiential retail strategies - such as interactive displays and omnichannel packaging that connects physical and digital experiences - are driving demand for innovative in-store theater packaging.
Operational Efficiency and Cost Reduction
Retail-ready and theater packaging solutions streamline shelf stocking, reduce labor costs, and minimize packaging waste, making them attractive for retailers seeking to optimize operations and improve supply chain efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the In-Store Theater Packaging Market
What factors are driving the growth of the In-Store Theater Packaging Market?
What are some challenges faced by the In-Store Theater Packaging Market?
Who are the major players in the In-Store Theater Packaging Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Retail
- 1.2.2 Food & Beverages
- 1.2.3 Cosmetics & Personal Care
- 1.2.4 Electronics
- 1.2.5 Automotive
- 1.2.6 Pharmaceutical
- 1.3 By Material
- 1.3.1 Paperboard
- 1.3.2 Kraft Paper
- 1.3.3 Plastic
- 1.3.4 Metal
- 1.3.5 Glass
- 1.3.6 Biodegradable Materials
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44,614.5 million → 2032: USD 178,209.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In Store Theater Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In Store Theater Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In Store Theater Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In Store Theater Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In Store Theater Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In Store Theater Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In Store Theater Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In Store Theater Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44,614.5 million → 2032: USD 178,209.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In Store Theater Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Retail
- 12.3.7.2 Food & Beverages
- 12.3.7.3 Cosmetics & Personal Care
- 12.3.7.4 Electronics
- 12.3.7.5 Automotive
- 12.3.7.6 Pharmaceutical
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paperboard
- 12.4.7.2 Kraft Paper
- 12.4.7.3 Plastic
- 12.4.7.4 Metal
- 12.4.7.5 Glass
- 12.4.7.6 Biodegradable Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global In Store Theater Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global In Store Theater Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global In Store Theater Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global In Store Theater Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DS Smith
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smurfit Kappa
- 18.4 WestRock
- 18.5 International Paper
- 18.6 Spectrio
- 18.7 Screenfeed
- 18.8 Visua
- 18.9 Retail Digital Signage
- 18.10 Mood Media
- 18.11 SignStix
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

