
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Indexable Inserts Market Size 2024 | USD 6,395 Million |
| Indexable Inserts Market, CAGR | 5.4% |
| Indexable Inserts Market Size 2032 | USD 9,740.15 Million |
Market Overview:
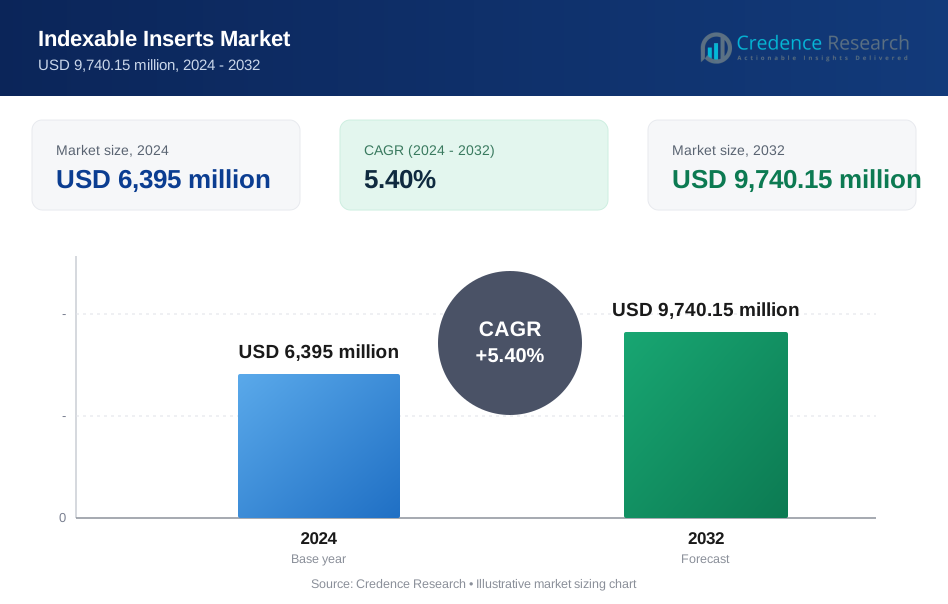
The Indexable Inserts Market is projected to grow from an estimated USD 6,395 million in 2024 to approximately USD 9,740.15 million by 2032, with a compound annual growth rate (CAGR) of 5.4% over the forecast period. Indexable inserts, commonly used in manufacturing processes like turning, milling, and drilling, enhance precision, reduce production downtime, and optimize machining efficiency. These inserts are integral to industrial applications due to their cost-effectiveness, allowing companies to replace only the worn-out cutting edges rather than the entire tool. Growth in sectors such as automotive, aerospace, and heavy machinery, where high-speed and high-precision machining are essential, is anticipated to fuel this market’s expansion.
Key drivers of growth in the indexable inserts market include the rapid expansion of the automotive and aerospace industries, which rely on advanced machining solutions to meet stringent precision requirements. Technological advancements in manufacturing processes, including automation and computer numerical control (CNC) machining, have spurred the demand for indexable inserts that offer enhanced performance and longevity. Furthermore, the development of specialized materials for inserts, such as carbide, ceramic, and cubic boron nitride, has enabled manufacturers to achieve higher cutting speeds and improved durability, driving productivity. The trend toward miniaturization in electronic components is also increasing the demand for small, precise indexable inserts, as manufacturers seek tools capable of handling intricate, detailed machining.
Regionally, Asia-Pacific holds a significant share of the indexable inserts market, driven by robust industrialization in countries such as China, Japan, and India. The region’s strong manufacturing base, particularly in automotive and electronics, underpins this demand. North America follows, where advanced manufacturing and a growing aerospace industry drive demand for high-performance machining solutions. In Europe, Germany and Italy are key markets, supported by a well-established automotive sector and strong engineering capabilities. Meanwhile, the Middle East & Africa and Latin America are anticipated to experience steady growth, with emerging industries in these regions gradually increasing their adoption of precision machining tools. These regional dynamics reflect the global expansion of the indexable inserts market as industries prioritize efficiency and cost-effective manufacturing solutions.
Market Drivers:
Growth in the Automotive and Aerospace Industries:
The automotive and aerospace sectors rely on high-precision machining to produce complex parts, driving demand for advanced indexable inserts. For example, according to the International Organization of Motor Vehicle Manufacturers (OICA), global automotive production is steadily rising, requiring efficient and precise tools to meet high-volume demands. Additionally, as these industries strive to reduce weight and improve fuel efficiency, they increasingly utilize lightweight materials like aluminum and titanium, which necessitate specialized inserts that can handle their unique properties. The aerospace sector, with stringent quality and durability requirements, further stimulates demand for high-performance indexable inserts to support advanced machining processes.
Advancements in CNC and Automation Technologies:
The adoption of CNC and automated machining technologies has significantly boosted demand for indexable inserts. These technologies enable greater precision and control, allowing manufacturers to produce intricate and highly consistent parts. The International Federation of Robotics (IFR) reports that industrial automation is on the rise globally, with CNC machines increasingly becoming the standard in manufacturing facilities. Indexable inserts, essential in these automated setups, enhance production efficiency and reduce tool replacement times, providing cost-effective solutions for high-precision and high-speed machining applications. Companies are therefore investing in durable and wear-resistant inserts to maximize machine uptime and output.
Development of Specialized Materials for Enhanced Performance:
Manufacturers are continually innovating to improve the materials used in indexable inserts, such as carbide, ceramic, and cubic boron nitride, which offer superior hardness and heat resistance. These materials enable machining at higher speeds, resulting in increased productivity and cost savings. For instance, the U.S. Department of Energy has highlighted the importance of durable materials in extending tool life and reducing production waste. The development of such specialized materials allows manufacturers to meet the stringent demands of industries like aerospace, where advanced materials are commonly used, and high performance is essential.
Increasing Demand for Miniaturization in Electronics:
As electronic devices become smaller and more complex, manufacturers require precise tools to machine miniaturized components. The electronics industry, particularly in Asia-Pacific, is witnessing substantial growth, with companies like TSMC and Samsung investing heavily in facilities to produce high-precision components. Indexable inserts capable of detailed, intricate machining play a crucial role in this sector. According to the Semiconductor Industry Association (SIA), the demand for precise, high-quality components is growing as electronics become increasingly compact, making specialized indexable inserts indispensable in the production of these devices.
Market Trends:
Rising Demand for Multi-Functionality and Versatile Tooling Solutions:
Manufacturers increasingly seek indexable inserts that support multiple machining functions, allowing them to perform tasks like turning, milling, and drilling with a single tool. For instance, modular tooling systems are gaining popularity as they can accommodate various insert geometries, reducing the need for frequent tool changes and improving production efficiency. According to the U.S. Department of Commerce, multi-functional tools that minimize downtime and improve flexibility are now integral to advanced manufacturing processes, especially in sectors with high precision requirements such as aerospace and medical device manufacturing.
Integration of Advanced Coating Technologies:
Advanced coating technologies are widely adopted in the production of indexable inserts to enhance tool life and performance. Coatings such as titanium nitride (TiN), aluminum oxide (Al2O3), and diamond-like carbon (DLC) provide superior hardness and heat resistance, enabling inserts to maintain precision at higher speeds and temperatures. For example, the National Institute of Standards and Technology (NIST) highlights that these coatings can extend tool life by reducing friction and wear. As a result, manufacturers are increasingly utilizing coated inserts in high-demand applications like automotive manufacturing to achieve greater productivity and cost savings.
Adoption of Sustainable Manufacturing Practices:
Sustainability initiatives are influencing the indexable inserts market as companies seek to reduce waste and energy consumption. Tool manufacturers are adopting sustainable practices, such as using recyclable materials and extending tool life to minimize production waste. For instance, the European Union’s Circular Economy Action Plan emphasizes resource efficiency, encouraging manufacturers to develop inserts that can be reused or recycled. Companies are also exploring ways to optimize manufacturing processes, reducing energy usage and carbon footprints, which aligns with broader industrial trends toward sustainability.
Growing Focus on Precision Machining for Emerging Technologies:
The expansion of emerging technologies, such as electric vehicles and renewable energy, has heightened the need for precision machining. For example, electric vehicle (EV) components, such as battery housings and drive units, require precise machining due to stringent safety and performance standards. According to the International Energy Agency (IEA), the rapid growth of the EV industry is driving demand for highly accurate machining tools like indexable inserts. Similarly, renewable energy projects, such as wind and solar energy systems, require high-performance machining components for manufacturing critical parts, such as turbine blades, which must withstand extreme conditions. These demands reflect the market’s shift toward specialized, high-precision indexable inserts to support next-generation technologies.
Market Challenges Analysis:
High Initial Costs and Maintenance Requirements:
One of the primary challenges in the indexable inserts market is the high initial cost of advanced materials and technologies, which can limit adoption, particularly among smaller manufacturers. Indexable inserts made from specialized materials like cubic boron nitride (CBN) and ceramics offer enhanced performance but are significantly more expensive than conventional tools. Additionally, these advanced inserts often require precise handling and maintenance to achieve optimal performance. For small and medium-sized enterprises, these costs can be prohibitive, slowing market penetration and limiting growth potential.
Fluctuations in Raw Material Prices:
The production of indexable inserts relies on various raw materials, including tungsten carbide, titanium, and ceramics. Fluctuations in the prices of these materials, often due to supply chain disruptions or geopolitical tensions, impact manufacturing costs and, consequently, the overall price of indexable inserts. For instance, the U.S. Geological Survey (USGS) reports that global tungsten prices have been volatile in recent years, influenced by changing supply dynamics and trade restrictions. These fluctuations can create challenges for manufacturers who must balance cost management with maintaining a reliable supply of raw materials, affecting profitability and production stability.
Environmental Regulations and Compliance Costs:
Environmental regulations aimed at reducing industrial emissions and waste pose a significant challenge to the indexable inserts market. Authorities like the U.S. Environmental Protection Agency (EPA) enforce strict guidelines on the disposal of industrial waste, which includes by-products from the machining processes where inserts are used. Compliance with these regulations often necessitates additional investments in eco-friendly technologies and waste management practices, which can increase operational costs for manufacturers. Additionally, European Union regulations under the REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) framework impose rigorous requirements on the use of certain chemicals in industrial applications, impacting production processes and the formulation of cutting tools.
Technological Complexity and Skilled Labor Shortage:
The adoption of advanced manufacturing technologies, such as CNC machines and automated machining centers, requires skilled labor capable of handling and optimizing indexable inserts within these systems. However, a shortage of skilled machinists and technicians familiar with these technologies presents a challenge for manufacturers. The U.S. Bureau of Labor Statistics has identified a gap in skilled labor within the manufacturing sector, which affects the efficient use of high-precision tools like indexable inserts. This shortage can result in suboptimal tool performance and lower productivity, limiting the full potential of these advanced machining solutions.
Market Segmentation Analysis:
By Type
Indexable inserts are categorized into several types, including turning, milling, drilling, and parting & grooving inserts. Turning inserts hold a significant share due to their widespread use in various industries, including automotive and aerospace, where high-precision turning operations are essential. Milling inserts follow closely, used primarily for applications requiring the shaping and finishing of materials. Drilling inserts are crucial for industries that need to create precise holes in materials, while parting & grooving inserts serve specialized functions in the production of complex components.
By Technology
The technology segment includes carbide, ceramic, and cubic boron nitride (CBN) inserts. Carbide inserts dominate the market, as they offer a good balance between durability and cost-effectiveness, making them suitable for general-purpose machining tasks. Ceramic inserts, known for their heat resistance and hardness, are ideal for high-speed applications, particularly in environments where tool life is a priority. CBN inserts cater to demanding applications, as they offer superior wear resistance and are ideal for machining hard materials such as hardened steels, making them essential in industries that prioritize durability and precision.
By End User
Key end users of indexable inserts are the automotive, aerospace, and general engineering industries. The automotive sector, which requires large-scale, high-precision machining, represents the largest share, driven by the production of vehicle components. The aerospace industry, with its demand for machining hard-to-cut materials, relies on advanced inserts for precision manufacturing. General engineering covers a broad range of applications, including industrial machinery and tools, where versatility and cost-effectiveness are key factors. Each of these end-user segments underscores the need for specialized and efficient machining solutions, contributing to the diverse applications within the indexable inserts market.
Segmentations:
By Insert Type:- Turning Inserts
- Milling Inserts
- Drilling Inserts
- Threading Inserts
- Grooving and Parting Inserts
- Carbide Inserts
- Cermet Inserts
- CBN (Cubic Boron Nitride) Inserts
- PCD (Polycrystalline Diamond) Inserts
- Titanium Nitride (TiN) Coating
- Titanium Carbo Nitride (TiCN) Coating
- Titanium Aluminum Nitride (TiAlN) Coating
- Aluminum Titanium Nitride (AlTiN) Coating
- Chemical Vapor Deposition (CVD) Coating
- Physical Vapor Deposition (PVD)Coating
- Steel
- Stainless Steel
- Cast Iron
- Aluminum
- Exotic Alloys
- Non-Ferrous Metals
- Rough Machining
- Finishing Machining
- High-Speed Machining
- Hard Material Machining
- Positive Rake Inserts
- Negative Rake Inserts
- Round Inserts
- Square Inserts
- Triangle Inserts
- Rhombic Inserts
- Octagonal Inserts
- Aerospace
- Automotive
- Medical Devices
- Electronics
- Energy
- General Manufacturing
- Heavy Machinery
- Direct Sales
- Distributors
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the indexable inserts market, accounting for approximately 40% of the global market. The dominance of this region is driven by its extensive manufacturing base, particularly in countries like China, Japan, and India. China, a global hub for automotive and electronics manufacturing, is the largest consumer of indexable inserts, where high demand stems from continuous investments in industrial machinery and infrastructure. Japan, known for its advanced manufacturing technologies, supports the adoption of high-precision tools. India’s rapid industrialization further fuels market demand, as government initiatives such as “Make in India” promote domestic manufacturing. The region’s focus on expanding its industrial capabilities aligns with the need for efficient, durable, and cost-effective machining solutions, underscoring the demand for indexable inserts.
North America
North America accounts for around 25% of the market, led primarily by the United States. The region’s demand for indexable inserts is driven by its highly developed aerospace, automotive, and defence industries. The U.S. in particular has a significant aerospace manufacturing sector, requiring precise machining capabilities for complex parts. Government agencies, including the U.S. Department of Defence, prioritize advanced manufacturing technologies that contribute to high demand for durable, high-performance inserts. Additionally, the trend toward automation in the manufacturing sector supports the adoption of CNC machining and robotic tools that rely on indexable inserts to enhance efficiency and precision.
Europe
Europe holds approximately 20% of the global market share, with key contributors being Germany, France, and Italy. Germany’s strong automotive sector and its reputation as a leader in industrial engineering make it a major consumer of indexable inserts. France and Italy contribute significantly due to their well-established aerospace and manufacturing industries. The European market is also influenced by stringent environmental regulations, which drive demand for advanced materials that reduce waste and improve tool life. The European Union’s focus on sustainable manufacturing practices has encouraged companies to adopt eco-friendly machining solutions, further promoting the use of durable, high-performance indexable inserts.
Latin America
Latin America accounts for roughly 8% of the market, with demand driven primarily by the automotive and construction sectors in countries like Brazil and Mexico. Industrial growth and infrastructure development in these countries support the use of precision machining tools, including indexable inserts. Although the region’s share is relatively smaller, increasing foreign investments and government initiatives aimed at boosting local manufacturing are expected to drive steady market growth. The need for affordable and durable tools that support large-scale projects in construction and automotive industries is particularly evident in Brazil, where economic development has heightened demand for efficient manufacturing solutions.
Middle East & Africa
The Middle East & Africa region holds approximately 7% of the global indexable inserts market, with demand led by the construction and oil & gas sectors. The United Arab Emirates and Saudi Arabia, in particular, are investing in infrastructure and energy projects, driving demand for durable machining tools capable of handling tough materials. In Africa, countries like South Africa are seeing growth in the mining and construction sectors, where indexable inserts are essential for precision cutting in challenging environments. Although this region holds a smaller market share, ongoing investments in industrial and infrastructure projects suggest a positive outlook for indexable inserts as these sectors expand.
Key Player Analysis:
- Sandvik Coromant
- Kennametal Inc.
- Iscar Ltd.
- Mitsubishi Materials Corporation
- Seco Tools
- Walter AG
- Kyocera Corporation
- Tungaloy Corporation
- Sumitomo Electric Industries, Ltd.
- Ceratizit Group
Competitive Analysis:
The Indexable Inserts Market is highly competitive, driven by the increasing demand for precision and efficiency in manufacturing industries such as automotive, aerospace, and electronics. Key players, including Sandvik, Kennametal, and Mitsubishi Materials, are focusing on product innovation, expanding their portfolios to include advanced materials and specialized coatings that enhance cutting speed, wear resistance, and tool life. Emerging competitors, especially from the Asia-Pacific region, are intensifying competition by offering cost-effective solutions and leveraging regional manufacturing advantages. Technological advancements, such as additive manufacturing and IoT-enabled inserts, are reshaping the market dynamics, allowing manufacturers to optimize operations and reduce costs. Strategic collaborations, mergers, and acquisitions are prevalent as companies aim to strengthen their market presence, improve R&D capabilities, and expand their distribution networks. The industry’s future outlook remains robust, with sustainability trends driving the development of eco-friendly inserts, aligning with global regulatory standards and customer expectations.
Recent Developments:
- In 2024 Companies have made significant strides in coating technology. For instance, advancements such as TiAlN and Diamond-like coatings have improved wear resistance and heat dissipation in indexable inserts, allowing for longer tool life and greater machining precision, particularly in high-speed applications.
- In 2023, Kennametal introduced its "Intelligent Inserts," which incorporate sensors to monitor cutting conditions and provide real-time data to optimize machining processes. This development aligns with Industry 4.0 trends, enabling predictive maintenance and enhancing productivity.
- In 2022, manufacturers expanded their offerings to include inserts tailored for niche applications, such as aerospace and medical devices. These customized solutions are designed to meet specific machining requirements, offering enhanced performance and precision for challenging materials.
- In 2023, CB-CERATIZIT, part of the Plansee Group, acquired a majority stake in Changzhou CW Toolmaker Inc. This acquisition allows CB-CERATIZIT to broaden its product portfolio in carbide cutting tools, particularly within the electronics and aviation sectors, underscoring a trend of strategic alliances in the market.
Market Concentration & Characteristics:
The Indexable Inserts Market is moderately concentrated, with a few key players, such as Sandvik, Kennametal, and Mitsubishi Materials, holding substantial market shares. These companies leverage their extensive research and development capabilities to innovate and offer high-performance products tailored to various industries, including automotive, aerospace, and electronics. The market's competitive landscape is shaped by the need for advanced materials and coatings that extend tool life and enhance machining efficiency. Emerging players, particularly from the Asia-Pacific region, are intensifying competition by offering cost-effective solutions, which appeals to price-sensitive customers. Market characteristics include a growing emphasis on customization and integration with smart technologies, such as sensor-enabled inserts, that support Industry 4.0 practices. Furthermore, strategic acquisitions and partnerships are common as companies seek to expand their regional footprints and bolster their technical expertise, thus fostering ongoing consolidation in the industry.
Report Coverage:
The research report offers an in-depth analysis based on Insert Type, Material Type, Coating Type, and Geometry Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Companies will continue innovating with advanced coatings and materials, enhancing the wear resistance and thermal stability of indexable inserts to meet demanding applications.
- Customization will play a crucial role, with manufacturers increasingly offering inserts tailored to specific industries.
- Integration with Industry 4.0 technologies is expected to expand, with smart inserts enabling real-time data collection on tool wear and cutting conditions to optimize productivity.
- Emerging markets, especially in the Asia-Pacific region, are anticipated to contribute significantly to demand due to rising industrialization.
- Sustainable practices and eco-friendly materials will gain importance, driven by stricter environmental regulations and customer preferences for reduced environmental impact.
- Acquisitions and partnerships among leading players will likely increase as companies seek to enhance their technology portfolios and expand into new geographic regions.
- Automation in manufacturing is projected to boost demand for high-precision indexable inserts compatible with CNC and other automated systems.
- Advances in high-speed and hard material machining techniques will drive development of specialized inserts optimized for these applications.
- The automotive industry’s shift towards lightweight materials will create demand for inserts that can handle complex composites and exotic alloys.
- Ongoing R&D investments in nanostructured and alloyed coatings will foster longer-lasting inserts, reducing tool changeovers and lowering operational costs for end users.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Indexable Inserts Market?
What factors are driving the growth of the Indexable Inserts Market?
What are some challenges faced by the Indexable Inserts Market?
Who are the major players in the Indexable Inserts Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Indexable Inserts Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Indexable Inserts Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,395 million → 2032: USD 9,740.15 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Indexable Inserts Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Indexable Inserts Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Indexable Inserts Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Indexable Inserts Market Drivers
- 3.3 Indexable Inserts Market Restraints & Challenges
- 3.4 Indexable Inserts Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Indexable Inserts Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Indexable Inserts Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Indexable Inserts category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Indexable Inserts Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Indexable Inserts Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Indexable Inserts. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Indexable Inserts Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Indexable Inserts Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Indexable Inserts Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Indexable Inserts (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Indexable Inserts
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Indexable Inserts Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Indexable Inserts Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Indexable Inserts Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Indexable Inserts Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Indexable Inserts Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Indexable Inserts Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Indexable Inserts Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Indexable Inserts Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
